
 Container Handling Equipment Market | 2026-2036
Container Handling Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Container Handling Equipment Market Intelligence
Asian crane manufacturing capacity is shifting toward mega-scale assembly yards in China and South Korea. Cargotec Corporation leverages its Kalmar brand to dominate automated stacking crane deliveries across European hub ports. Liebherr Group sustains engineering intensity with heavy-lift ship-to-shore cranes rated above 25,000 TEU vessel class. Konecranes anchors aftermarket service revenue through predictive maintenance contracts on rubber-tired gantry fleets.
Container handling equipment comprises mobile and stationary machinery engineered to lift, transport, and stack ISO-standard containers weighing up to 40 tons, with reach stackers delivering boom articulation to 45 meters and straddle carriers clearing four-high container stacks. Forklifts occupy the highest unit-volume tier though margin pools concentrate in automated systems where port operators amortize capital across twenty-year concession terms. Reach stackers compete for intermodal yard flexibility where rail-mounted gantry cranes lack span coverage. Electrical systems within the technology segment displace diesel engines as lithium-ion pack costs fall and charging infrastructure densifies.
EPA Tier 4 Final and EU Stage V emissions standards compel engine redesigns or full powertrain substitution in diesel-dependent equipment classes. The EU Green Deal and California Air Resources Board maritime regulations accelerate zero-emission procurement timelines for terminal operators under concession renewal pressure. China's MIIT dual carbon goals enforce domestic OEM electrification roadmaps that SANY Group and Shanghai Zhenhua Heavy Industries must satisfy for state-owned port tenders. Stakeholders must weigh battery-electric against hydrogen fuel cell architectures before concession bidding cycles lock in decade-long fleet commitments.
Market Dynamics
Terminal operators face concession renewal cycles that lock in equipment choices for fifteen to twenty years, compressing the window for powertrain technology bets before capital commitments crystallize.
Growth Catalysts
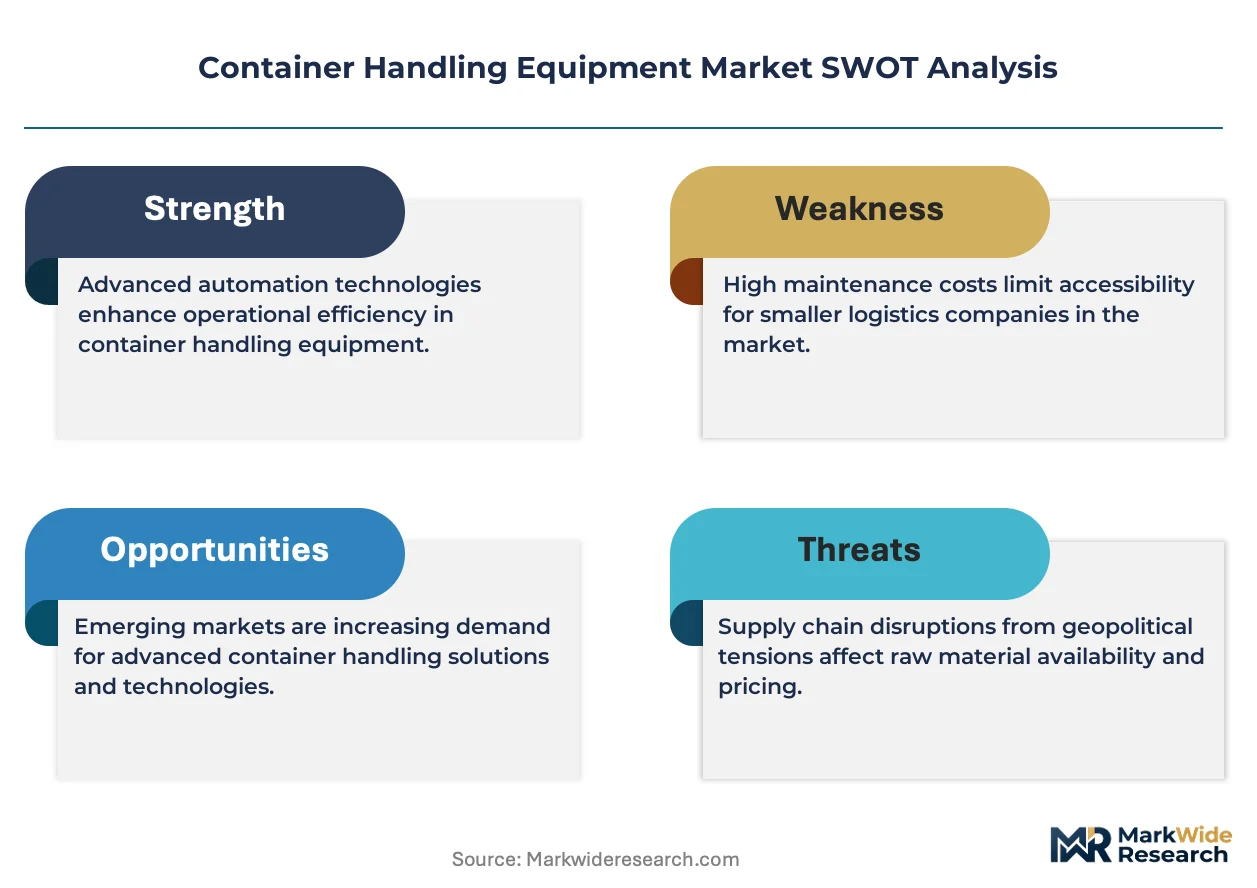
- EU Green Deal maritime regulations:The EU Green Deal mandates zero-emission terminal equipment procurement timelines, forcing port authorities to electrify fleets before concession deadlines expire.
- Straddle carrier automation:Automated stacking systems reduce labor costs per container move by eliminating crane operator shifts in high-throughput European hub ports.
- Vietnam:Greenfield terminal investments at Lach Huyen and Cai Mep International Terminal outpace retrofit demand elsewhere, concentrating new equipment orders in Southeast Asian manufacturing clusters.
Market Restraints
- Lithium-ion pack cost volatility:Battery raw material price swings compress margins on electric reach stackers, forcing OEMs to absorb input spikes or pass through to price-sensitive intermodal yards.
- Chinese mega-yard concentration:Assembly capacity centralization in Shanghai and Ningbo creates single-source dependency for super-post-Panamax crane structures, exposing delivery timelines to port congestion and customs delays.
- Hydrogen fuel cell infrastructure gaps:Refueling station scarcity limits fuel cell straddle carrier deployment to Rotterdam and Hamburg terminals with captive hydrogen supply chains.
Strategic Opportunities
- Indonesia:New Priok container terminal expansion and Patimban port development create first-mover advantage for automated rubber-tired gantry crane suppliers before local assembly requirements tighten.
- Predictive maintenance convergence:IoT sensor fusion with crane structural health monitoring enables condition-based overhaul scheduling, shifting revenue from spare parts to uptime guarantees.
- California Air Resources Board incentive pools:CARB's zero-emission port equipment funding accelerates battery-electric forklift fleet turnover in Los Angeles and Long Beach terminals ahead of federal mandates.
Industry Challenges
- Automation commissioning complexity:Terminal operating system integration with legacy NAVIS and TOS platforms extends project timelines by eight to fourteen months, delaying revenue recognition.
- High-voltage technician scarcity:Qualified electricians for 800V battery pack maintenance command wage premiums exceeding forty percent above diesel mechanic rates, constraining fleet scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Handling Equipment Market |
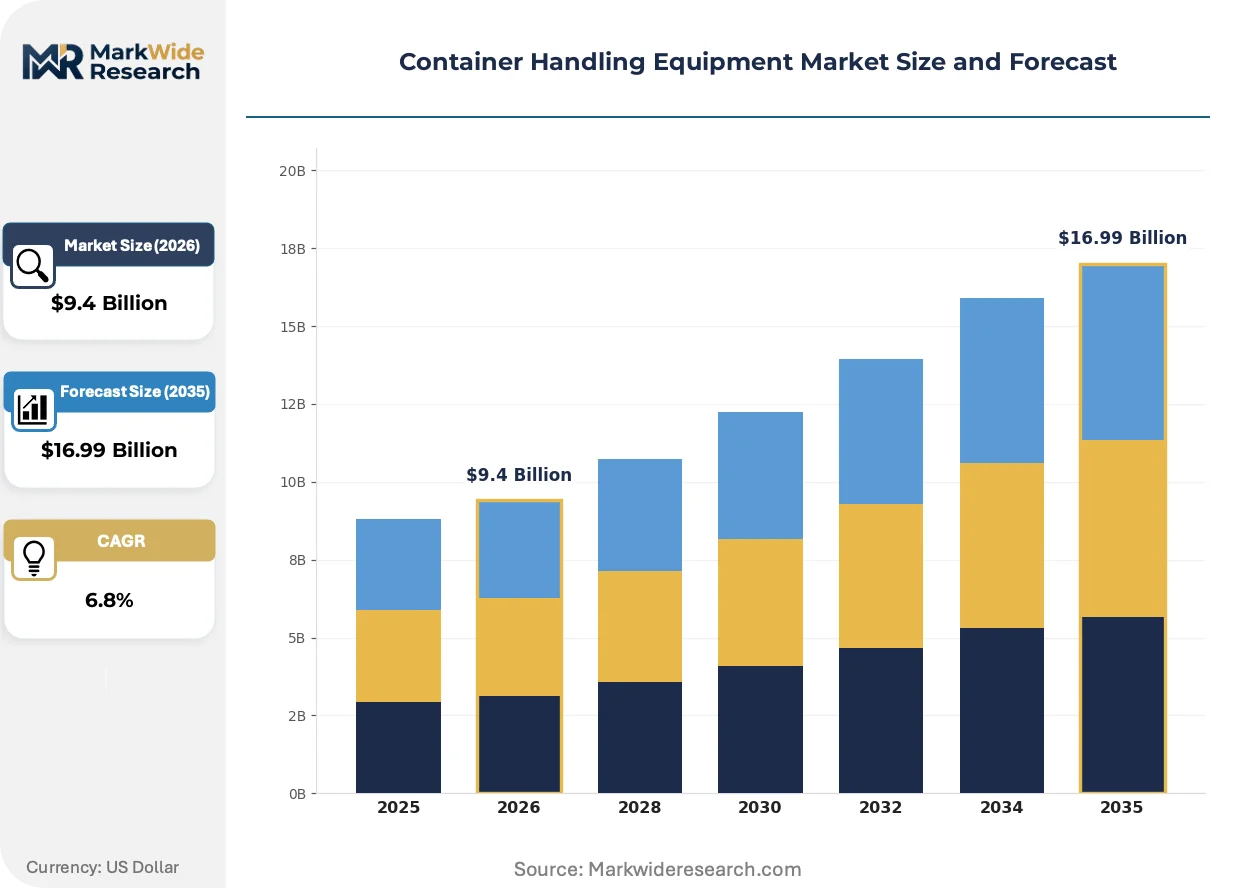
| Market Size in 2026 | $9.4 Billion |
| Market Size in 2035 | $16.99 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Forklifts, Straddle Carriers, Reach Stackers, Transfer Vehicles Application: Ports, Terminals, Distribution Centers, Freight Stations End User: Shipping Companies, Logistics Providers, Warehouse Operators, Importers Technology: Automated Systems, Electrical Systems, Diesel Engines, Hybrid Solutions |
| Companies Covered | Liebherr Group, Cargotec Corporation, Konecranes, SANY Group, Kalmar Corporation, Shanghai Zhenhua Heavy Industries Co., Ltd., Hyster-Yale Materials Handling Inc., Toyota Industries Corporation, Palfinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Handling Equipment Market Strategic Shifts & Innovations
Powertrain architecture decisions now precede equipment specification by three to five years as terminal operators model total cost of ownership across diesel, battery-electric, and hydrogen fuel cell alternatives.
Battery pack design is modularizing around swappable 200kWh units that crane OEMs can configure in series for ship-to-shore applications or parallel for straddle carrier duty cycles. Port operators in Hamburg and Singapore pilot hot-swap stations that eliminate charging downtime for continuous operations. This architecture is modularizing fleet standardization across equipment classes, compressing spare parts inventory requirements and technician training pathways.
EPA Tier 4 Final and EU Stage V emissions standards have eliminated off-the-shelf engine options for new diesel equipment above 175kW, forcing engine redesigns or hybrid-electric transitions. OEM engineering teams split resources between compliance retrofits and clean-sheet electric architectures, stretching R&D budgets across dual development tracks. Rubber-tired gantry crane segments in European transshipment hubs bear the heaviest compliance burden, accelerating pre-buy activity ahead of 2027 enforcement windows.
Terminal operators now unbundle equipment purchase from full-service maintenance contracts, separating capital expenditure approval from operating budget commitments. Independent service providers in Rotterdam and Antwerp capture aftermarket revenue previously retained by OEM captive finance arms, fragmenting the service profit pool. This unbundling is most advanced in automated stacking crane fleets where specialized automation integrators command premium billing rates for control system diagnostics.
Container Handling Equipment Market Segmentation
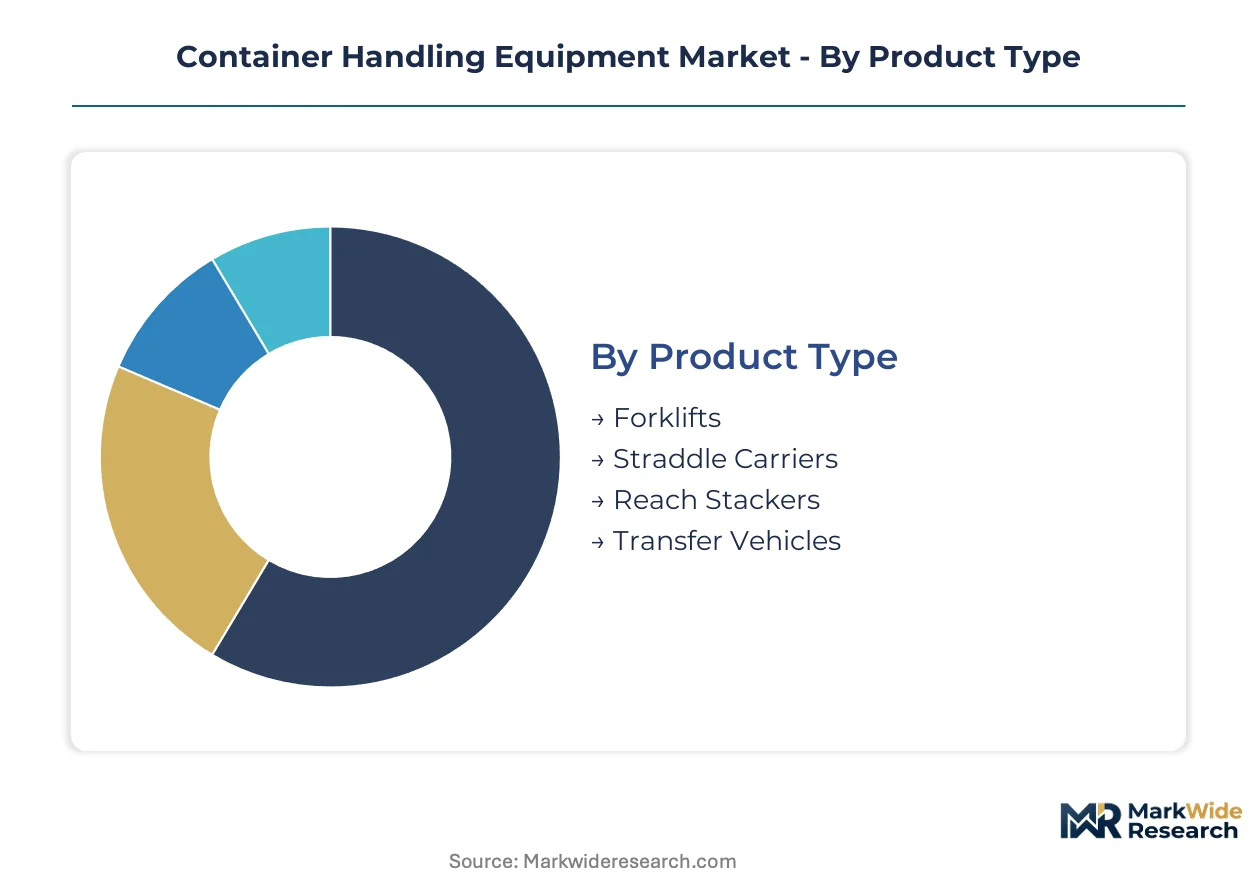
Equipment segmentation in container handling reveals how procurement priorities diverge across powertrain technologies and operational environments. Terminal operators structure capital allocation around automation readiness and concession timelines rather than unit economics alone.
Product Type:
Procurement decisions pivot on yard layout constraints and vessel class compatibility, with automation feasibility driving specification choices.
- Reach Stackers:Boom articulation to 45 meters enables intermodal yard flexibility where rail-mounted gantry cranes lack span coverage. Demand concentrates in Vietnam and Indonesia where greenfield terminal investments outpace retrofit cycles, driven by transshipment volume expansion.
- Straddle Carriers:Four-high container stack clearance suits high-density European hub ports with vertical storage optimization. Automated stacking systems reduce labor costs per container move in Rotterdam and Hamburg terminals facing concession renewal pressure.
- Forklifts:Highest unit-volume tier serves distribution centers and freight stations with sub-40-ton lift requirements.
- Transfer Vehicles:Automated guided variants shuttle containers between quay and yard blocks in Singapore and Shanghai mega-terminals.
Volume sits with forklifts; growth tilts toward straddle carriers.
Application:
Operational intensity and concession duration determine equipment lifecycle economics across facility types.
- Ports:Ship-to-shore crane procurement locks in twenty-year capital commitments at Lach Huyen and Cai Mep International Terminal. EU Green Deal mandates force zero-emission fleet decisions before concession deadlines expire.
- Terminals:Rubber-tired gantry crane segments bear heaviest EPA Tier 4 Final compliance burden, accelerating pre-buy activity ahead of enforcement windows.
- Distribution Centers:Battery-electric forklift turnover accelerates in Los Angeles and Long Beach ahead of California Air Resources Board mandates.
- Freight Stations:Reach stacker flexibility dominates intermodal handoffs where rail and road modes converge.
Capital deployment heaviest at ports; electrification timelines tightest at terminals.
End User:
Fleet ownership models diverge between asset-heavy operators and third-party logistics providers with variable throughput commitments.
- Shipping Companies:Vertical integration into terminal operations drives captive equipment procurement at dedicated berths.
- Logistics Providers:Third-party operators favor leasing structures to match equipment scale with contract volatility.
- Warehouse Operators:Forklift unit volumes concentrate here though margin pools remain thin relative to automated systems.
- Importers:Regional distribution networks prioritize reach stacker acquisition for container devanning flexibility.
Shipping companies anchor capital expenditure; logistics providers expand fastest.
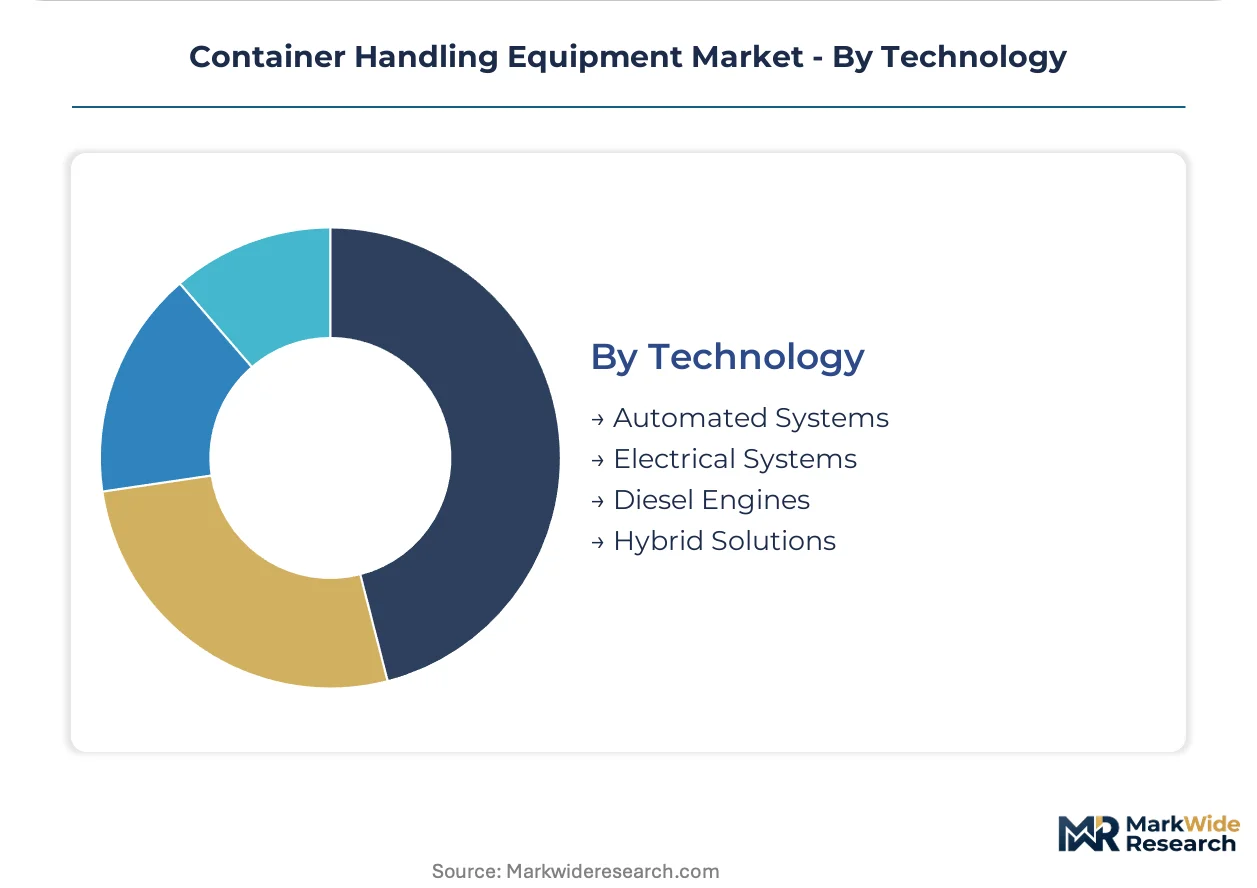
Technology:
Powertrain architecture decisions now precede equipment specification by three to five years as operators model total cost of ownership.
- Electrical Systems:Lithium-ion pack costs falling below threshold levels enable battery-electric straddle carrier deployment. Port operators in Hamburg and Singapore pilot hot-swap stations that eliminate charging downtime for continuous operations.
- Automated Systems:Terminal operating system integration with legacy NAVIS and TOS platforms extends project timelines, delaying revenue recognition for OEMs.
- Diesel Engines:EPA Tier 4 Final and EU Stage V standards eliminated off-the-shelf options above 175kW, forcing engine redesigns.
- Hybrid Solutions:Transitional architecture splits engineering resources between compliance retrofits and clean-sheet electric designs.
Installed base remains diesel-dominant; order intake shifts toward electrical systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel plate and casting clusters in China's Yangtze River Delta and South Korea's Gyeongsang belt feed crane fabrication yards across East Asia. Equipment procurement concentrates where transshipment volumes climb and concession renewal cycles force capital commitments.
China
MIIT dual carbon goals enforce domestic OEM electrification roadmaps for state-owned port tenders. Shanghai Zhenhua Heavy Industries and SANY Group anchor mega-yard assembly in Shanghai and Ningbo, though port congestion and customs delays expose delivery timelines to single-source dependency.
Germany
EU Green Deal maritime regulations accelerate zero-emission procurement timelines for terminal operators under concession renewal pressure. Hamburg pilots hot-swap battery stations that eliminate charging downtime for continuous straddle carrier operations, while automation integrators command premium billing rates for control system diagnostics.
United States
California Air Resources Board incentive pools accelerate battery-electric forklift fleet turnover in Los Angeles and Long Beach terminals ahead of federal mandates. EPA Tier 4 Final standards eliminated off-the-shelf engine options above 175kW, forcing hybrid-electric transitions in rubber-tired gantry crane segments.
Vietnam
Greenfield terminal investments at Lach Huyen and Cai Mep International Terminal outpace retrofit demand elsewhere, concentrating new equipment orders in Southeast Asian manufacturing clusters. Transshipment volume expansion drives reach stacker procurement for intermodal yard flexibility.
Indonesia
New Priok container terminal expansion and Patimban port development create first-mover advantage for automated rubber-tired gantry crane suppliers before local assembly requirements tighten. Battery-electric architectures face infrastructure gaps that hydrogen fuel cell alternatives cannot yet fill.
Container Handling Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue automation integration and electrification architectures. The vendor base clusters around three maturity tiers: diversified industrial conglomerates with captive port equipment divisions, specialized crane engineering houses with heavy-lift credentials, and regional fabricators serving price-sensitive intermodal yards. Strategic archetypes include full-stack automation providers bundling equipment with terminal operating systems, aftermarket service specialists monetizing predictive maintenance contracts, and battery system integrators capturing powertrain value migration. Competitive moves concentrate on geographic expansion into Southeast Asian greenfield terminals and technology licensing partnerships for hydrogen fuel cell prototypes.
Within the diversified industrial tier, Cargotec Corporation and Liebherr Group exemplify engineering-intensive positioning across automated stacking crane and heavy-lift ship-to-shore categories. Konecranes occupies a service-anchored archetype, with aftermarket revenue streams tied to predictive maintenance contracts on rubber-tired gantry fleets. Shanghai Zhenhua Heavy Industries Co., Ltd. represents the China-based mega-yard fabrication model, supplying super-post-Panamax structures to state-owned port tenders under MIIT compliance mandates.
| Leading Market Players |
|---|
| Liebherr Group |
| Cargotec Corporation |
| Konecranes |
| SANY Group |
| Kalmar Corporation |
| Shanghai Zhenhua Heavy Industries Co., Ltd. |
| Hyster-Yale Materials Handling Inc. |
| Toyota Industries Corporation |
| Palfinger |
| Others |
Cost & Logistics Intelligence
High-voltage technician scarcity in European port clusters widens pricing-tier spreads between premium full-service bundles and stripped equipment-only transactions. Labor-cost differentials between Hamburg automation specialists and Southeast Asian maintenance crews compress margins on battery-electric fleets while inflating aftermarket premiums.
Pricing Analysis
Warranty and predictive maintenance bundling now separates premium automated stacking crane contracts from economy reach stacker sales with minimal service attachment. Three-tier pricing structure across premium, standard, and economy levels reflects automation complexity, OEM brand intensity, and geographic delivery distance from Shanghai and Ningbo assembly yards. Pricing pressure stems from lithium-ion pack cost volatility forcing OEMs to absorb input spikes or surrender share to Chinese regional fabricators. Third-party logistics providers leasing rubber-tired gantry crane fleets exhibit highest price sensitivity; state-owned port authorities in Vietnam and Indonesia prioritize automation readiness over unit economics.
Supply Chain Analysis
Indonesian local-content mandates and Vietnam's domestic assembly requirements are reshaping sourcing patterns for European automation integrators and Korean mega-yard suppliers. Steel plate and casting clusters in China's Yangtze River Delta and South Korea's Gyeongsang belt feed crane fabrication, with high-tensile steel and lithium-ion cells drawing from concentrated East Asian supply bases. Single-source dependency on Shanghai and Ningbo super-post-Panamax structure production exposes delivery timelines to port congestion and customs clearance delays. Distribution runs through OEM captive finance arms in European hub ports and independent service providers in Rotterdam and Antwerp.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EU Green Deal maritime regulations erect barrier-to-entry moats favoring OEMs with certified zero-emission architectures and established terminal operating system integration capabilities.
For Market Incumbents: Hedge against hydrogen fuel cell infrastructure gaps by maintaining parallel battery-electric engineering tracks while locking in long-term lithium supply agreements before concession renewal cycles crystallize fleet commitments. Defend service revenue pools by resisting unbundling pressure from independent automation integrators in Antwerp and Hamburg.
For New Entrants and Emerging Players: Enter via Indonesia's Patimban port development and Vietnam's Lach Huyen greenfield terminals before local assembly requirements tighten procurement eligibility. Battery system integration for modular 200kWh swappable packs offers the most penetrable wedge against entrenched full-stack automation providers.
For Investors and Strategic Acquirers: The window for entry favors aftermarket service specialists with predictive maintenance platform capabilities and condition-based overhaul scheduling expertise. Monitor EPA Tier 4 Final enforcement intensity and CARB incentive pool exhaustion as inflection signals for diesel equipment residual value collapse.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Pack Standardization | Swappable 200kWh units enable fleet commonality across straddle carriers and ship-to-shore cranes in Hamburg and Singapore. |
| Terminal Operating System Integration | Legacy NAVIS and TOS platform compatibility determines automation commissioning timelines and revenue recognition schedules. |
| Predictive Maintenance Platform Deployment | IoT sensor fusion with structural health monitoring shifts OEM revenue from spare parts to uptime guarantees. |
| Zero-Emission Certification Investment | EU Green Deal and CARB compliance credentials unlock state-owned port tenders in Vietnam and Indonesia. |
| Local Assembly Partnership Formation | Indonesian domestic content requirements tighten procurement eligibility for New Priok and Patimban terminal expansions. |
Research Approach
Multi-period observation of concession renewal cycles, powertrain procurement patterns, and automation commissioning timelines anchored the trend analysis, supplemented by interviews with terminal operations directors, OEM aftermarket service heads, port authority procurement managers, and automation integration specialists. Secondary validation drew from EU Green Deal regulatory filings, EPA Tier 4 Final enforcement notices, CARB incentive program disclosures, and customs trade data on steel plate and crane component flows. Bottom-up equipment shipment tracking and top-down port capacity expansion modeling provided triangulation across the analysis window.
An input-output matrix framed volume and value projections across the modeling period, segmenting by equipment class, powertrain architecture, automation level, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and concession duration modeling, with lithium-ion cost curves and hydrogen infrastructure build-out assumptions feeding scenario-weighted outcomes.
Forecast precision tightens around the base case; tail outcomes carry wider variance under battery raw material price spikes, trade policy disruptions affecting Chinese mega-yard output, and accelerated EU Green Deal enforcement timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Global Elevator Market
Material Handling Equipment
Selective Pallet Racking System Market
Material Handling Equipment
Pneumatic Conveying Diverters Market
Material Handling Equipment
Ship Loader and Unloader Market
Material Handling Equipment
Crate Handling Systems Market
Material Handling Equipment
Rubber Tired Gantry (RTG) Crane Market
Material Handling Equipment
Vertical Reciprocating Conveyor Market
Material Handling Equipment
Bridge Cable Sockets Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Slitting Machines Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Wagon Tipplers Market
Material Handling Equipment
Wire Pulling and Tensioning Market