
 High-Precision Gear Reducer Market | 2026-2036
High-Precision Gear Reducer Market Size, Share, and Industry Trends Forecast 2026-2036
High-Precision Gear Reducer Market Insights
Industrial robotics is pivoting toward collaborative and surgical applications that demand sub-arc-minute positioning accuracy. Nabtesco Corporation dominates cycloidal precision reducer supply for heavy-payload robot joints. Harmonic Drive LLC specializes in strain wave architectures for compact six-axis arms. Wittenstein SE differentiates through integrated servo-actuator systems that combine reducer, motor, and encoder in one housing.
A high-precision gear reducer is a mechanical transmission device engineered to reduce input speed while multiplying torque with positional accuracy typically below one arc-minute of backlash, achieved through hardened alloy steel gearing and preloaded bearing arrangements. Its primary purpose is enabling repeatable motion control in servo-driven automation where standard gearboxes introduce unacceptable positioning error. Harmonic drive and strain wave variants command premium positioning in semiconductor lithography and surgical robotics due to zero-backlash characteristics and compact form factors. Planetary gear configurations sustain volume leadership in CNC machine tool spindles where torque density and thermal stability outweigh absolute precision requirements. Cycloidal drives anchor medium-speed robotics applications with superior shock load tolerance compared to harmonic alternatives.
ISO 9409-1 robot mounting standards, EU Machinery Directive 2006/42/EC safety requirements, and REACH material compliance frameworks collectively shape reducer design validation and market access protocols across European and Asian manufacturing jurisdictions. FDA 510(k) clearance pathways for surgical robot subsystems further constrain supplier qualification timelines for medical-grade precision transmissions. Stakeholders must monitor evolving IEC 60034 servo motor interface standards and assess bearing material substitutions ahead of anticipated PFAS restrictions affecting fluoropolymer lubrication systems.
Market Dynamics
ISO 9409-1 backlash tolerance revisions are compressing supplier qualification timelines while concentrating procurement authority among robot OEMs capable of certifying sub-arc-minute precision at volume.
Growth Catalysts
- EU Machinery Directive 2006/42/EC safety mandates:Stricter functional safety requirements for collaborative robot joints are forcing upgrades to zero-backlash harmonic drive architectures in Stuttgart-area automotive assembly plants.
- Semiconductor lithography tooling:Wafer stepper manufacturers in Taiwan and South Korea are specifying strain wave reducers with sub-30-arc-second repeatability for EUV alignment stages.
- Surgical robotics FDA 510(k) pathway:Minimally invasive procedure systems requiring sterilizable precision transmissions are creating dedicated supply contracts for medical-grade cycloidal variants.
Market Restraints
- Alloy steel input volatility:Vacuum-degassed bearing steel prices fluctuate with nickel and molybdenum exchange dynamics, compressing margin visibility for mid-tier reducer assemblers.
- Japanese supply concentration:Specialized cup-type flexspline manufacturing for harmonic drives remains captive to Nagano and Shizuoka prefecture machining clusters.
- Thermal expansion coefficients:Differential expansion between steel gearing and aluminum housings limits sustained precision in high-duty-cycle CNC spindle applications above 8,000 RPM.
Strategic Opportunities
- India PLI scheme for industrial automation:Production-linked incentives for robot component manufacturing are attracting reducer assembly investments in Gujarat and Tamil Nadu precision engineering corridors.
- Integrated servo-actuator convergence:Combining planetary reducers with frameless torque motors and absolute encoders in single housings is collapsing commissioning time for six-axis cobot integrators.
- PFAS lubrication substitution:Anticipated REACH restrictions on fluoropolymer greases are creating first-mover advantage for ionic liquid and synthetic hydrocarbon lubricant formulations in cleanroom-rated reducers.
Industry Challenges
- Precision grinding skill scarcity:Master craftspeople capable of lapping cycloidal disc profiles to ISO 1328-1 grade 4 quality are retiring faster than apprenticeship programs in Germany and Japan can replenish.
- Cross-certification complexity:Simultaneous FDA 510(k), CE-MDR, and NMPA registration for surgical robot subsystems extends qualification timelines to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High-Precision Gear Reducer Market |
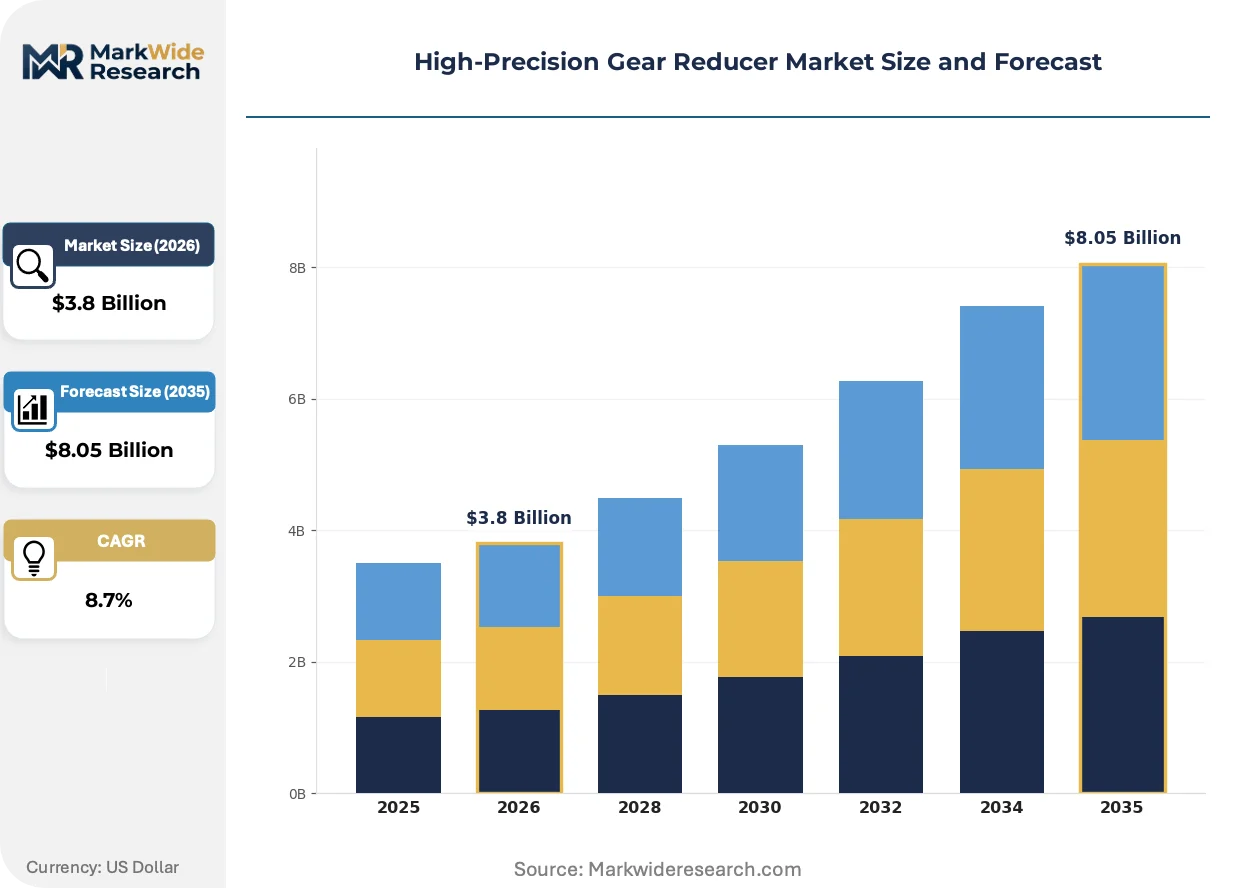
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Harmonic Drive, Cycloidal Drive, Planetary Gear, Worm Gear, Strain Wave, Epicyclic Technology: Ball Bearings, Roller Bearings, Needle Bearings, Magnetic Drive, Hydrodynamic, Air Bearings Application: Robotics, Aerospace Actuators, CNC Machines, Semiconductor Manufacturing, Packaging Equipment, Optical Instruments End User: OEM Manufacturers, Automation Firms, Precision Equipment Makers, Defense Contractors, Electronics Producers, Research Institutions |
| Companies Covered | Harmonic Drive LLC, Nabtesco Corporation, Wittenstein SE, Neugart GmbH, Sumitomo Drive Technologies, Nidec-Shimpo Corporation, SEW-EURODRIVE GmbH & Co KG, Apex Dynamics, Inc., SPINEA, s.r.o., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High-Precision Gear Reducer Market Trends and Innovations
Active magnetic bearing integration and AI-driven predictive maintenance algorithms are redefining precision transmission value propositions beyond mechanical backlash specifications alone.
Integrated condition monitoring is automating failure prediction in high-precision gear reducers. Sensor-embedded bearing races in Wittenstein and Nabtesco flagship lines stream vibration and temperature data to edge computing nodes. Automotive OEMs in Bavaria and Baden-Württemberg are mandating this capability for predictive maintenance contracts on paint-shop robot lines, compressing unplanned downtime liability to sub-2% availability targets.
REACH PFAS restrictions are forcing lubrication system redesigns across European precision reducer supply chains. ECHA regulatory timelines anticipate 2026-2027 prohibitions on perfluorinated grease formulations currently standard in cleanroom and vacuum-rated harmonic drives. German reducer specialists are accelerating ionic liquid and PAO-based alternatives through accelerated life testing, with semiconductor lithography OEMs in Dresden and Leuven qualifying substitutes ahead of mandate deadlines.
Modular actuator procurement is consolidating vendor relationships among collaborative robot manufacturers. End-users in Michigan and Ontario automotive clusters are specifying complete rotary axis modules—reducer, servo motor, brake, and encoder pre-integrated—rather than sourcing components separately. This pattern compresses integration engineering overhead while shifting technical liability upstream to Nabtesco, Harmonic Drive, and Wittenstein system houses.
High-Precision Gear Reducer Market Segmentation
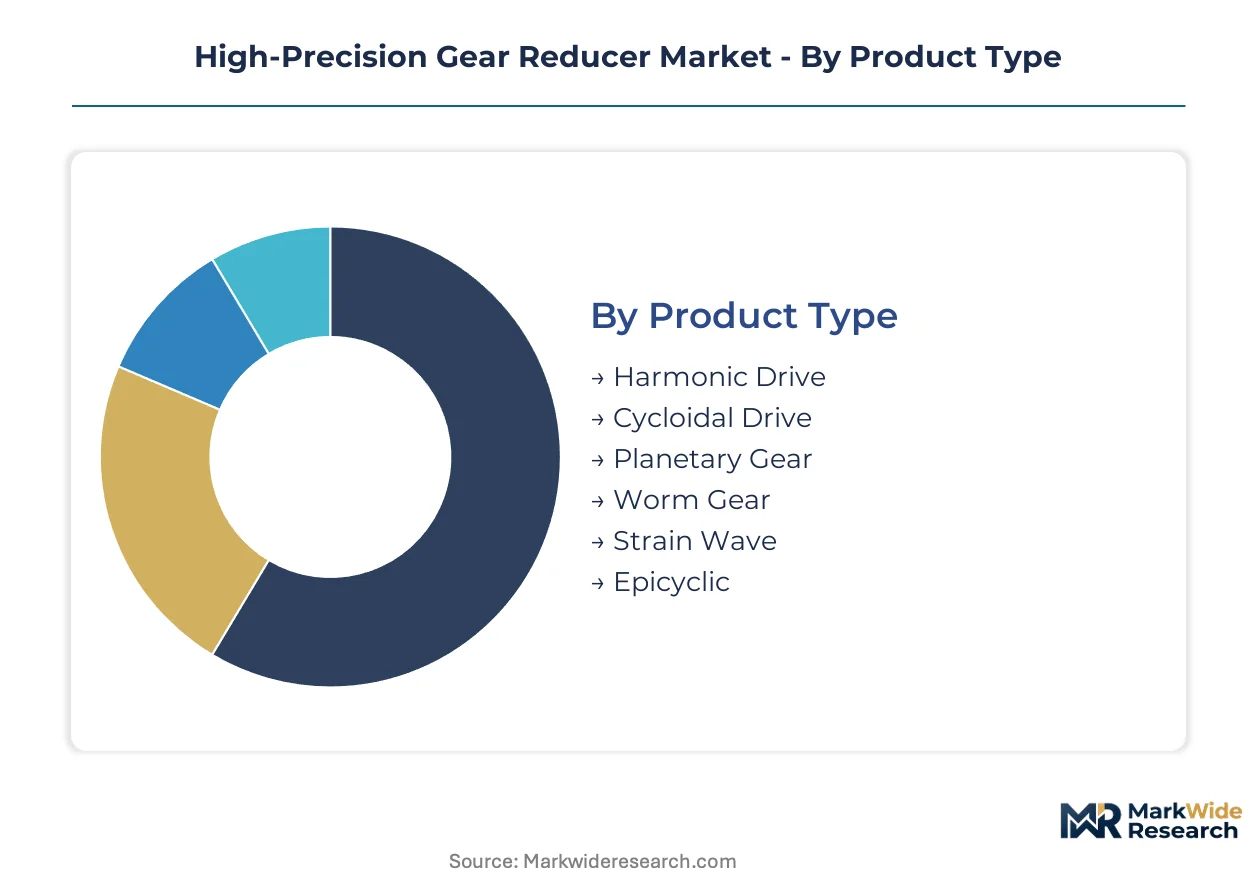
High-precision gear reducer procurement patterns diverge sharply across certification regimes, with FDA 510(k) medical robotics demanding zero-backlash architectures while automotive assembly tolerates higher backlash for cost efficiency. Segmentation reveals how regulatory burden concentrates margin in medically qualified supply chains.
Product Type:
Harmonic Drive and Cycloidal Drive variants carry the heaviest certification overhead for surgical robotics, while Planetary Gear and Worm Gear configurations face lighter functional safety scrutiny in industrial automation.
- Harmonic Drive:Strain wave gearing with zero-backlash preloaded flexsplines achieves sub-arc-minute positioning. Wafer stepper manufacturers in Taiwan and South Korea specify these for EUV alignment stages requiring sub-30-arc-second repeatability.
- Cycloidal Drive:Eccentric cam-roller mechanisms deliver superior shock load tolerance through multi-tooth engagement. Stuttgart-area automotive plants specify these for collaborative robot joints under EU Machinery Directive 2006/42/EC functional safety mandates.
- Planetary Gear:Sun-planet-ring configurations balance torque density with thermal stability in CNC machine tool spindles.
- Worm Gear:Right-angle power transmission with inherent self-locking characteristics suits vertical axis positioning.
- Strain Wave:Compact cup-type flexspline architecture dominates six-axis compact robot arms.
- Epicyclic:Coaxial input-output geometry enables inline servo motor integration.
Cycloidal Drive sits at the top of the volume ranking, with Strain Wave climbing the fastest.
Technology:
Bearing technology selection directly determines cleanroom qualification pathways, with magnetic and air bearing variants bypassing lubricant contamination risks that trap conventional rolling element bearings in extended REACH compliance cycles.
- Ball Bearings:Deep-groove and angular-contact configurations provide cost-effective radial and axial load support. Volume demand concentrates in mid-precision packaging equipment where standard ISO P5 accuracy grades suffice.
- Roller Bearings:Cylindrical and tapered variants handle heavy radial loads in machine tool spindles above 8,000 RPM. Thermal expansion differentials between steel races and aluminum housings constrain sustained precision in high-duty-cycle applications.
- Needle Bearings:Compact radial envelope enables high load capacity in constrained joint spaces.
- Magnetic Drive:Active magnetic bearing integration eliminates mechanical contact for vacuum-rated semiconductor handling.
- Hydrodynamic:Oil film lubrication supports high-speed continuous rotation with minimal wear.
- Air Bearings:Pressurized gas film delivers frictionless motion for optical lithography stages.
Ball Bearings dominate shipment volumes across all precision tiers, though Magnetic Drive is gaining share fastest in EUV lithography applications.
Application:
Application segmentation tracks directly against regulatory jurisdiction density, with surgical robotics and semiconductor manufacturing facing triple-certification burdens while packaging equipment operates under single-framework compliance.
- Robotics:Six-axis articulated arms and collaborative cobots demand sub-arc-minute repeatability for automotive paint-shop lines. Bavarian and Baden-Württemberg OEMs now mandate integrated condition monitoring for predictive maintenance contracts targeting sub-2% unplanned downtime.
- Aerospace Actuators:Flight control surface positioning requires MIL-STD-810 environmental qualification. Defense contractors in the US and Europe specify redundant encoder feedback architectures for fail-operational certification.
- CNC Machines:Spindle and rotary axis reducers prioritize thermal stability over absolute zero backlash.
- Semiconductor Manufacturing:EUV lithography stages require vacuum-compatible, non-outgassing transmission architectures.
- Packaging Equipment:High-speed pick-and-place tolerates moderate backlash for throughput optimization.
- Optical Instruments:Telescope and microscope positioning demands ultra-fine incremental motion control.
Robotics commands the largest installed base, with Semiconductor Manufacturing expanding most quickly on EUV capital investment cycles.
End User:
End user type determines procurement centralization, with OEM Manufacturers consolidating multi-year supply agreements while Research Institutions fragment demand across low-volume custom configurations.
- OEM Manufacturers:Robot builders and machine tool producers negotiate three to five-year supply contracts with technical liability shifting upstream. Nabtesco, Harmonic Drive, and Wittenstein system houses now face consolidated vendor qualification for complete rotary axis modules.
- Automation Firms:System integrators in Michigan and Ontario automotive clusters specify pre-integrated servo-actuator assemblies to collapse commissioning timelines.
- Precision Equipment Makers:Metrology and calibration equipment producers demand traceable calibration certificates.
- Defense Contractors:Military qualification pathways extend procurement cycles to 24-36 months.
- Electronics Producers:Consumer device assembly tolerates standard precision grades for cost containment.
- Research Institutions:University and national laboratory procurement operates through fragmented grant-funded purchasing.
OEM Manufacturers represent the dominant revenue concentration, with Automation Firms climbing fastest on collaborative robot deployment acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production geography as REACH compliance costs in Europe push reducer assembly toward jurisdictions with lighter chemical-handling mandates but equivalent precision-engineering capabilities.
Germany
Stuttgart's precision engineering corridor concentrates cycloidal drive demand from automotive OEMs retooling for collaborative robotics. EU Machinery Directive 2006/42/EC functional safety mandates are compressing supplier qualification timelines for zero-backlash architectures. Baden-Württemberg machine builders now mandate integrated condition monitoring for predictive maintenance contracts on paint-shop robot lines.
Japan
Nagano and Shizuoka prefectures retain captive supply of specialized cup-type flexspline manufacturing for harmonic drives. METI industrial automation incentives are reinforcing domestic machining cluster capabilities against Korean and Taiwanese competition. Osaka-area system integrators are consolidating procurement authority for six-axis cobot rotary axis modules.
United States
FDA 510(k) clearance pathways for surgical robot subsystems are extending qualification timelines to 18-24 months for precision transmission suppliers. Michigan and Ontario automotive clusters are specifying pre-integrated servo-actuator assemblies to collapse commissioning overhead. Bavarian OEMs with US operations are mandating identical predictive maintenance specifications across transatlantic facilities.
South Korea
Taiwan and South Korean wafer stepper manufacturers are specifying strain wave reducers with sub-30-arc-second repeatability for EUV alignment stages. MFDS medical device regulations are creating parallel certification tracks for sterilizable precision transmissions. Seoul-area automation firms are accelerating backward integration into reducer assembly to secure supply chain control.
India
Production-linked incentives for robot component manufacturing under the PLI scheme are attracting reducer assembly investments in Gujarat and Tamil Nadu precision engineering corridors. BIS standards harmonization with ISO 9409-1 is compressing technical barriers to entry for domestic suppliers. Chennai-area automotive OEMs are qualifying local cycloidal drive sources for collaborative robot joint applications.
High-Precision Gear Reducer Market Competitive Landscape
Strategic partnerships dominate the current landscape as tier-one robot OEMs consolidate vendor relationships around complete rotary axis modules rather than discrete components. The supplier base exhibits tiered concentration: Japanese specialists control harmonic drive architectures, German system houses anchor integrated servo-actuator convergence, and mid-tier planetary gear assemblers compete on torque density specifications. Three archetypes define positioning: zero-backlash medical-grade specialists, automotive-volume cycloidal suppliers, and modular actuator system integrators. Capacity expansion in Indian precision engineering corridors and technology licensing for PFAS-free lubrication formulations represent the dominant competitive vectors.
Within the Japanese specialist tier, Harmonic Drive LLC and Nabtesco Corporation exemplify divergent architectural approaches—strain wave versus cycloidal—while occupying positions as default suppliers for heavy-payload and compact six-axis applications respectively. Wittenstein SE represents the German system-integration archetype, anchoring the integrated servo-actuator convergence trend that combines reducer, motor, and encoder functions in single housings. These three entities collectively illustrate how geographic clustering around Nagano, Stuttgart, and Bavaria translates into divergent technical specializations despite shared exposure to ISO 9409-1 backlash tolerance revisions.
| Leading Market Players |
|---|
| Harmonic Drive LLC |
| Nabtesco Corporation |
| Wittenstein SE |
| Neugart GmbH |
| Sumitomo Drive Technologies |
| Nidec-Shimpo Corporation |
| SEW-EURODRIVE GmbH & Co KG |
| Apex Dynamics, Inc. |
| SPINEA, s.r.o. |
| Others |
Pricing and Supply Chain Analysis
REACH PFAS restrictions on fluoropolymer lubricants gate qualified supply for cleanroom-rated harmonic drives while compressing premium-tier pricing access for European semiconductor and surgical robotics OEMs. Buyers without approved ionic liquid or synthetic hydrocarbon alternatives face 18-24 month requalification timelines that concentrate procurement leverage among incumbent suppliers with validated substitute formulations.
Pricing Analysis
Distributor margins of 12-18% separate authorized channel partners from direct-to-OEM volume contracts negotiated by Stuttgart-area automotive clusters and Taiwan wafer stepper manufacturers. Three-tier pricing structure across medical-grade zero-backlash, industrial precision, and standard planetary configurations tracks ISO 9409-1 certification tier and FDA 510(k) clearance status. Cost compression in mid-tier planetary gear segments is intensifying because Indian PLI scheme entrants are undercutting Japanese and German incumbents on torque-density specifications. Price sensitivity peaks among packaging equipment OEMs tolerating moderate backlash, while surgical robotics manufacturers absorb 40-60% premiums for sterilizable cycloidal variants.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from robot builders consolidating rotary axis module procurement, while specialized distributors serve fragmented research institution and precision equipment maker segments. Supply concentrates in Japan for cup-type flexspline machining, Germany for integrated servo-actuator assembly, and India for emerging cycloidal drive fabrication under PLI incentives. Raw material dependencies center on vacuum-degassed bearing steel from Austrian and Swedish mills, nickel-alloy output from Russian and Canadian sources, and rare-earth magnet feedstock for frameless torque motor integration. Single-source vulnerability in Nagano and Shizuoka prefecture harmonic drive machining clusters exposes downstream OEMs to earthquake and trade disruption risks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Machinery Directive 2006/42/EC functional safety mandates and REACH PFAS timelines are accelerating replacement demand for zero-backlash architectures across European automotive and semiconductor manufacturing corridors.
For Market Incumbents: Lock in multi-year supply agreements with Baden-Württemberg and Bavarian OEMs before Indian PLI scheme capacity reaches qualification maturity. Prioritize backward integration into ionic liquid lubricant formulation to defend margin position against REACH compliance cost pass-through requirements. Certify sub-30-arc-second repeatability specifications for EUV lithography stages ahead of Korean and Taiwanese wafer stepper procurement cycles. For New Entrants and Emerging Players: PFAS-free lubrication formulation expertise offers a technology-first wedge into cleanroom-rated reducer segments where incumbent requalification timelines create temporary supply windows. Target Gujarat and Tamil Nadu precision engineering corridors for cycloidal drive assembly partnerships with domestic automotive OEMs qualifying local sources. Pursue medical device component supplier status through MFDS parallel certification tracks in South Korea where Seoul-area automation firms seek supply chain control. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier planetary gear assemblers because ISO 9409-1 backlash tolerance revisions are compressing supplier qualification timelines and concentrating procurement authority among volume-certified vendors. Platform consolidation across German system integrators and Japanese machining specialists offers 5-10 year viability through integrated servo-actuator convergence. Monitor ECHA regulatory enforcement timing as the inflection signal for first-mover advantage in PFAS-free lubricant substitution.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Lubricant Formulation | REACH PFAS deadlines force captive ionic liquid capacity for cleanroom qualification retention. |
| Integrated Servo-Actuator Convergence | Wittenstein and Nabtesco system houses collapse commissioning time for Michigan cobot integrators. |
| India PLI Scheme Manufacturing Footprint | Gujarat and Tamil Nadu corridors attract reducer assembly investments from domestic automotive OEMs. |
| Medical-Grade Cycloidal Certification | FDA 510(k) clearance creates dedicated supply contracts for sterilizable precision transmissions. |
| Condition Monitoring Platform Integration | Sensor-embedded bearing races enable predictive maintenance contracts targeting sub-2% downtime. |
Research Methodology
Multiple input streams — primary interviews with precision transmission engineering directors, robot OEM procurement leads, and semiconductor lithography equipment specialists; secondary validation through ISO 9409-1 technical committee documentation, ECHA regulatory filings, and METI industrial automation incentive disclosures; plus customs and trade flow data from Japanese and German precision component export registries — were reconciled through bottom-up shipment analysis and top-down market sizing triangulation.
Data-stream reconciliation across product type, bearing technology, application, and end user segmentation dimensions anchored volume and value outputs throughout the projection horizon. CAGRs were derived from installed base replacement cycles, EUV capital expenditure trajectories, and collaborative robot deployment acceleration patterns. Industry-specific forecast inputs incorporated REACH PFAS restriction timelines, FDA 510(k) clearance pathway durations, and India PLI scheme capacity ramp assumptions.
The model holds under stable alloy steel input pricing and sustained EU Machinery Directive enforcement; deviation in Japanese machining cluster disruption or accelerated PFAS prohibition would shift volume concentration toward qualified alternative suppliers. Periodic stress-testing of base assumptions against regulatory enforcement calendars and commodity exchange dynamics is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Surface Contact Wire Rope Market
Material Handling Equipment
High-Performance Seals Market
Material Handling Equipment
Truck Loader Crane Market
Material Handling Equipment
Log Stackers Market
Material Handling Equipment
Centrifugal Industrial Dryer Market
Material Handling Equipment
Pallet Circulation System Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Clinching Machines Market
Material Handling Equipment
Swivel Coupler Market
Material Handling Equipment
Material Handling Automation Market
Material Handling Equipment
Asia Pacific Mobile Crane Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Sifter Fitment Market
Material Handling Equipment
US and Mexico Metal Stamping Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market