
 Lump Breaker Machines Market | 2026-2036
Lump Breaker Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Lump Breaker Machines Market Insights
North American capital goods producers is restructuring supply chains for lump breaker fabrication, shifting toward regional component sourcing to reduce lead times. Prater Industries leverages its Midwest manufacturing footprint to serve domestic chemical processors. Schutte Hammermill anchors its position through specialized hammer mill configurations for abrasive mineral applications. Franklin Miller differentiates via sanitary-grade designs that penetrate pharmaceutical and food processing installations.
Lump breaker machines employ rotating blades, hammers, or rollers to reduce agglomerated materials into uniform, flowable particles, typically operating at throughputs from 500 kg/hr to 50 tonnes/hr depending on rotor diameter and motor configuration. These units serve primary industrial functions in upstream material handling, preventing blockages in pneumatic conveying lines and ensuring consistent feed to extruders, mixers, and reactors. Hammer mills occupy the largest installed base across mining and mineral processing due to their tolerance for abrasive ores and construction debris. Rotary crushers capture expanding share in food processing where gentle lump breaking preserves particle integrity for downstream extrusion. Pneumatic technology represents the fastest-growing segment as plants automate material transfer and integrate dust collection systems.
OSHA enforces permissible exposure limits for respirable crystalline silica and combustible dust, compelling sealed construction and explosion-proof motor specifications in US installations. REACH and the EU ATEX Directive mandate material certifications and ignition risk assessments for equipment deployed across European chemical and pharmaceutical facilities. Stakeholders must evaluate how evolving PFAS restrictions and polymer recycling mandates in multiple jurisdictions reshape material streams and corresponding machine duty requirements.
Market Dynamics
Chemical processing plants are consolidating material conditioning operations into continuous upstream systems, forcing lump breaker manufacturers to engineer sealed, high-throughput units that integrate with pneumatic conveying and dust collection infrastructure.
Growth Catalysts
- REACH compliance mandates:European chemical facilities must install sealed-system designs to prevent dust emissions and cross-contamination, accelerating replacement cycles for open-frame legacy equipment.
- Hygroscopic material handling:Fertilizer and specialty chemical producers require rotary crushers with heated housings to prevent caking during high-moisture processing.
- Rhineland corridor clustering:Germany's integrated production hubs demand synchronized material conditioning systems that feed continuous reactor trains without buffer storage.
Market Restraints
- Alloy steel price volatility:Rotor shafts and hammers require abrasion-resistant grades whose nickel and molybdenum content exposes fabricators to commodity swings.
- Explosion-proof motor supply concentration:ATEX-certified drive systems source primarily from Italian and German suppliers, creating lead time vulnerability for non-European OEMs.
- Hammer mill substitution ceiling:Mineral processors tolerate abrasive wear in hammer mills that rotary designs cannot match, limiting segment crossover.
Strategic Opportunities
- Polymer recycling mandates:EU regulations requiring post-industrial plastic reprocessing create demand for gentle lump breaking that preserves molecular chain length for re-extrusion.
- Pharmaceutical containment integration:Isolator-compatible designs that dock with split-valve powder transfer systems open high-margin sanitary applications.
- India's PLI scheme for chemicals:Domestic agrochemical and dye intermediate producers qualify for capital subsidies that cover automated material handling equipment.
Industry Challenges
- ATEX certification timelines:European notified body backlogs delay market entry for new explosion-proof configurations by 8-14 months.
- Legacy DCS integration:Brownfield chemical plants require custom communication modules to connect modern lump breakers to 1990s-era distributed control systems.
- Welding qualification scarcity:Pressure vessel fabrication for pharmaceutical-grade units demands ASME Section IX certified welders in short supply across Midwest US manufacturing zones.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lump Breaker Machines Market |
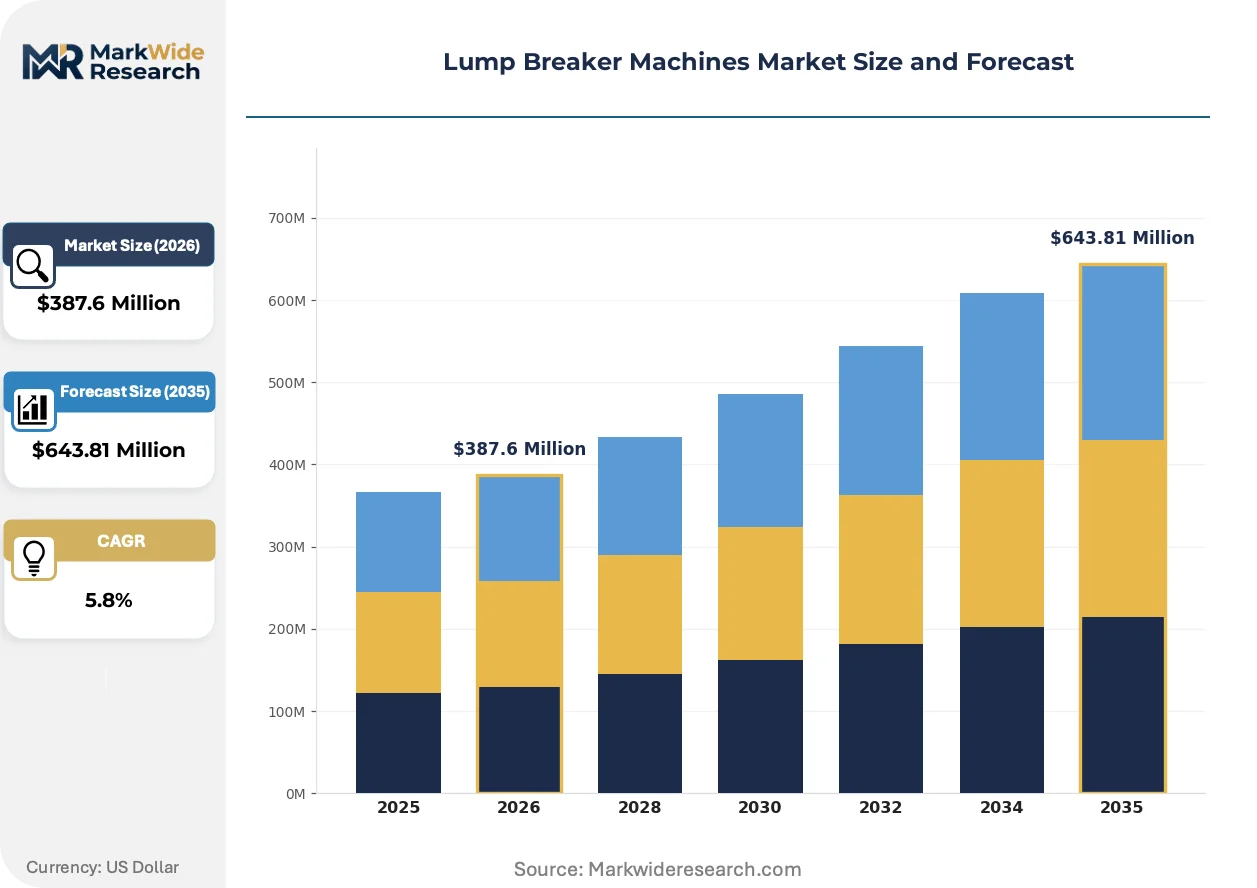
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Hammer Mills, Rotary Crushers, Impact Breakers, Roller Crushers, Gyratory Crushers Technology: Mechanical, Pneumatic, Hydraulic, Electric, Magnetic Application: Pharmaceutical Processing, Food Processing, Chemical Processing, Plastic Recycling, Mineral Processing End User Industry: Pharma Manufacturers, Food & Beverage Plants, Chemical Producers, Plastic Recyclers, Mining Companies |
| Companies Covered | Prater Industries, Stedman Machine Company, Schutte Hammermill, Palamatic Process, Hapman, WAMGROUP, Munson Machinery, Franklin Miller, Carrier Vibrating Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lump Breaker Machines Market Trends and Innovations
Equipment intelligence and material science advances are compressing the gap between commodity mineral processing and precision pharmaceutical applications, creating hybrid machine architectures that serve both domains.
Variable frequency drive integration with torque-limiting couplings is rewriting how operators manage energy consumption and mechanical protection. Food processors in the Netherlands and Belgium adopt these systems to handle crystalline sugar and salt with minimal fines generation. The technology is compressing total cost of ownership calculations by eliminating shear pin maintenance and reducing peak power draw.
OSHA's enhanced enforcement of combustible dust National Emphasis Program is compelling US facilities to document ignition source control. Chemical processors in the Gulf Coast petrochemical corridor now specify intrinsically safe instrumentation packages on all new installations. The regulation is accelerating retirement of unsealed equipment that cannot demonstrate containment during rotor stall conditions.
Service unbundling is fragmenting traditional capital equipment sales. Mining operators in Western Australia now procure lump breakers through equipment-as-a-service arrangements where the OEM retains ownership and charges per tonne processed. The model transfers maintenance burden and residual value risk to manufacturers while locking processors into long-term consumables supply agreements for hammers and screens.
Lump Breaker Machines Market Segmentation
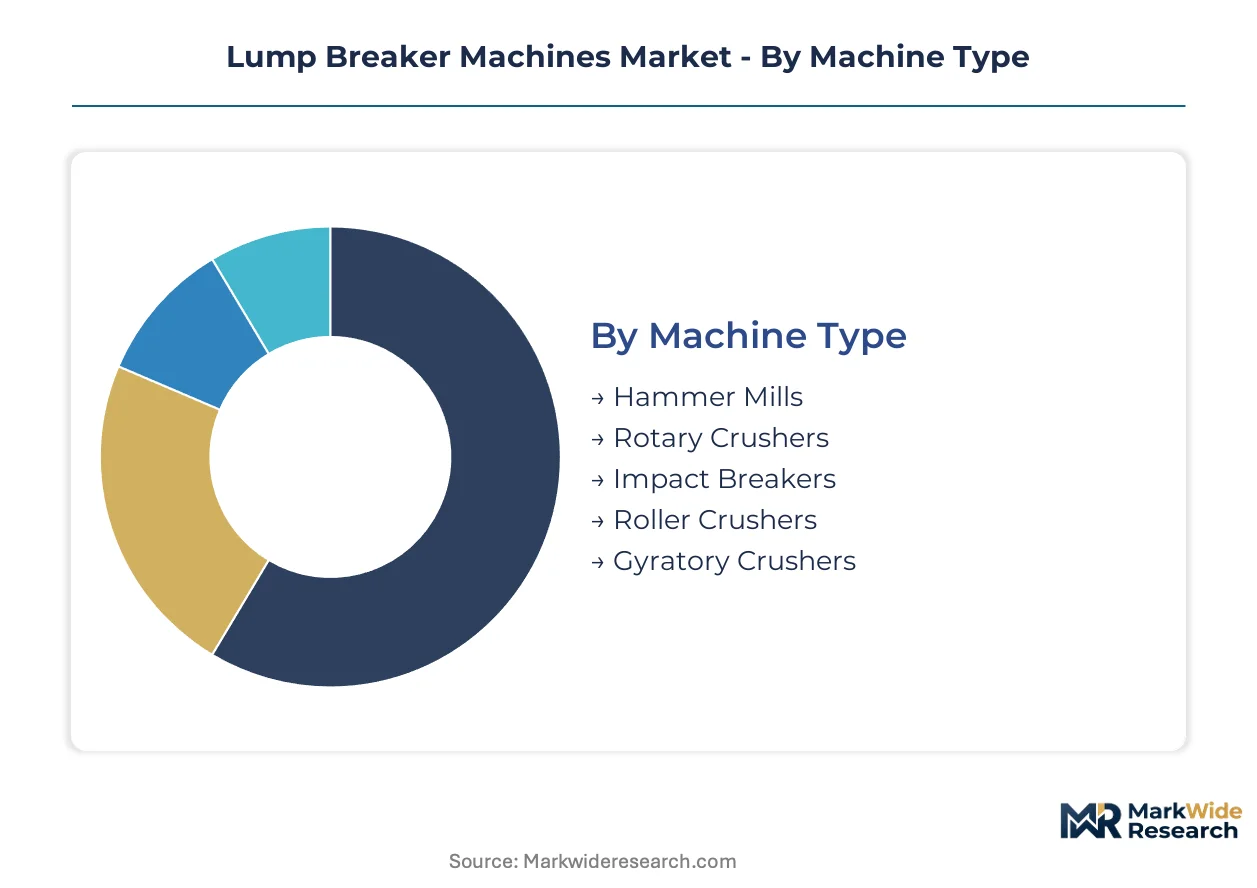
Segmentation in lump breaker machines reveals how duty requirements, material abrasiveness, and containment standards fragment equipment specifications across industrial verticals. Certification burdens and throughput demands create distinct procurement patterns that manufacturers must navigate.
Machine Type:
ATEX and OSHA compliance requirements vary sharply across configurations, with explosion-proof specifications mandatory for hammer mills in combustible dust environments while sanitary-grade rotary crushers face FDA validation cycles.
- Hammer Mills:Rotating hammers mounted on horizontal shafts pulverize abrasive minerals and construction debris through repeated impact. Mining operations in Western Australia and Chilean copper belts specify these units for their tolerance of silica-laden feedstocks despite high consumable wear rates.
- Rotary Crushers:Slow-speed dual-rotor designs shear agglomerates without generating excessive fines, preserving particle integrity for downstream extrusion. Food processors in the Netherlands and Belgian sugar refineries specify heated housings to prevent caking during high-moisture crystalline handling.
- Impact Breakers:High-velocity rotors with replaceable blow bars handle medium-hardness materials in quarrying applications.
- Roller Crushers:Compressive crushing between corrugated drums suits friable minerals requiring controlled size reduction with minimal dust generation.
- Gyratory Crushers:Conical head assemblies within stationary concaves process large feed lumps in primary mining circuits.
Hammer mills sit at the top of the volume ranking, with rotary crushers climbing the fastest.
Technology:
Capital intensity and energy efficiency separate procurement tiers, with pneumatic systems commanding premium positioning for automated integration while mechanical drives dominate cost-sensitive mineral applications.
- Mechanical:Direct-coupled gearboxes and V-belt drives deliver brute-force torque for heavy mineral duties. Indian cement producers and Indonesian coal processors favor these configurations for their field-serviceability and spare parts availability.
- Pneumatic:Vacuum-assisted material transfer integrates lump breaking with dust collection and conveying infrastructure. German chemical processors along the Rhineland corridor specify these systems for continuous reactor feeding without buffer storage.
- Hydraulic:Variable displacement pumps enable precise torque control for heterogeneous feedstocks.
- Electric:Servo-controlled drives with regenerative braking reduce energy consumption in high-cycle food processing.
- Magnetic:Eddy-current separation integration targets ferrous contamination removal in plastic recycling streams.
Mechanical technology dominates installed base, though pneumatic configurations are expanding most quickly.
Application:
Containment validation requirements stratify equipment architectures, with pharmaceutical and food installations demanding isolator-compatible designs that chemical and mineral processors rarely specify.
- Chemical Processing:Sealed-system rotary crushers handle hygroscopic fertilizers and heat-sensitive intermediates under nitrogen purging. REACH compliance mandates drive replacement of open-frame legacy equipment across European facilities.
- Pharmaceutical Processing:Containment-integrated designs dock with split-valve powder transfer systems for potent compound handling. FDA validation protocols and OEL (occupational exposure limit) compliance add 12-18 months to qualification timelines.
- Food Processing:Sanitary-grade stainless construction with quick-clean features serves sugar, salt, and spice milling.
- Plastic Recycling:Gentle low-shear breaking preserves polymer chain length for re-extrusion under EU recycling mandates.
- Mineral Processing:Abrasion-resistant hammer mills tolerate silica and metal contaminants in primary crushing circuits.
Chemical processing commands the largest equipment spend, while pharmaceutical applications deliver the steepest margin expansion.
End User Industry:
Procurement sophistication varies by sector maturity, with pharma and food buyers specifying total cost-of-ownership models while mining and chemical purchasers prioritize upfront capital efficiency.
- Chemical Producers:Integrated production clusters in Germany, Belgium, and Louisiana require synchronized material conditioning without intermediate storage. These buyers specify predictive maintenance integration with existing DCS infrastructure.
- Pharma Manufacturers:Containment validation and batch documentation requirements drive specification of isolator-compatible units with automated clean-in-place capability. Swiss and Irish formulation hubs concentrate demand for highest-containment configurations.
- Food & Beverage Plants:Allergen management protocols and sanitary design standards govern equipment selection for sugar, dairy, and spice processing.
- Plastic Recyclers:Post-industrial and post-consumer reprocessing operations require gentle size reduction to preserve material properties.
- Mining Companies:Remote operations in Western Australia and Chile favor equipment-as-a-service arrangements transferring maintenance burden to OEMs.
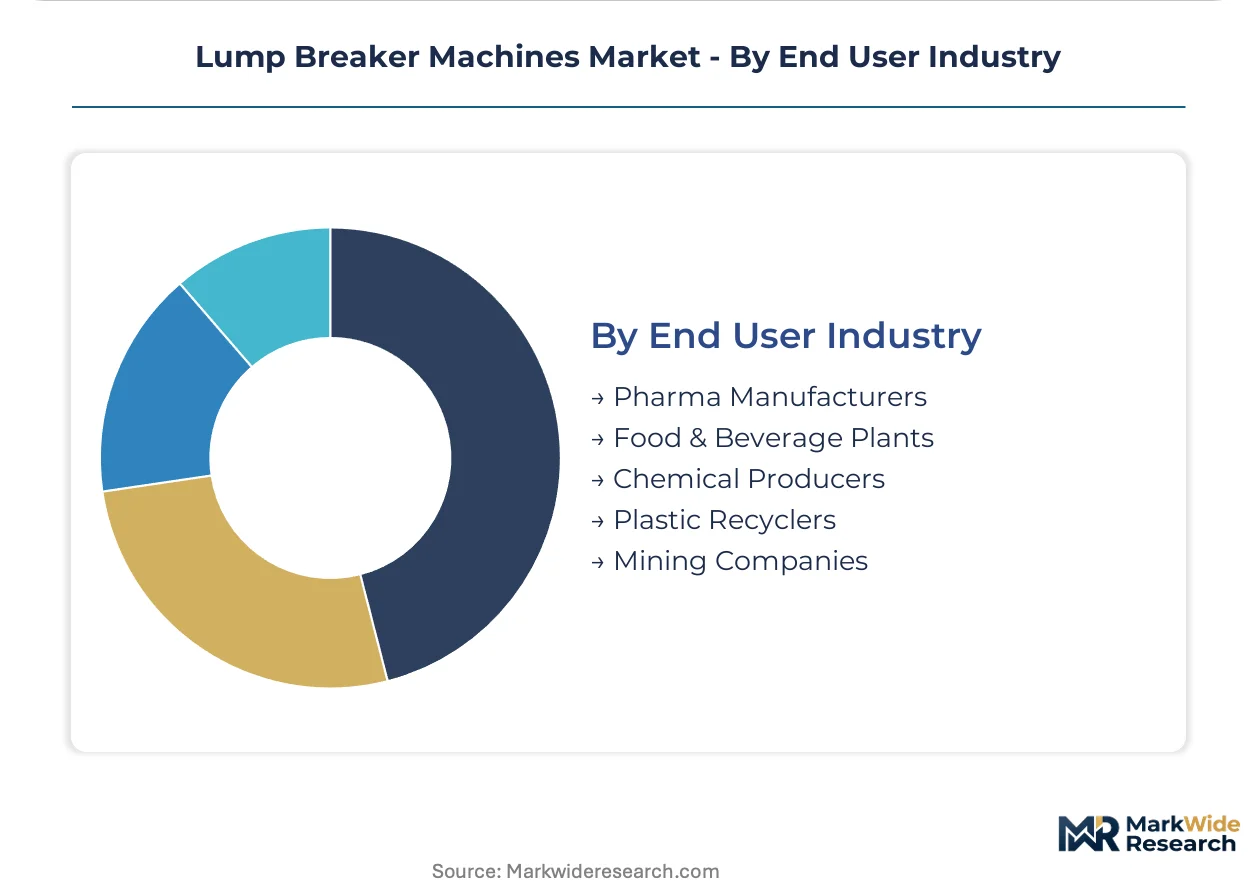
Chemical producers represent the deepest buyer segment by volume, with pharma manufacturers gaining share fastest on containment premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium equipment specifications through REACH-mandated containment systems, while India scales domestic fabrication under capital subsidy programs for chemical processing infrastructure.
Germany
Rhineland chemical corridors drive synchronized material conditioning demand for continuous reactor trains. REACH and the EU ATEX Directive mandate sealed-system designs with ignition risk assessments, accelerating replacement of open-frame legacy equipment. Leverkusen and Ludwigshafen production clusters specify pneumatic-integrated lump breakers for nitrogen-purged hygroscopic material handling.
United States
Gulf Coast petrochemical facilities upgrade dust collection infrastructure under OSHA combustible dust enforcement. The National Emphasis Program compels documentation of ignition source control, pushing intrinsically safe instrumentation specifications. Louisiana integrated production hubs demand predictive maintenance integration with existing distributed control systems.
India
Domestic agrochemical and dye intermediate producers expand automated material handling capacity under the PLI scheme for chemicals. Central Electricity Authority regulations govern motor efficiency standards for process equipment. Gujarat and Maharashtra industrial corridors concentrate demand for field-serviceable mechanical drive configurations with local spare parts availability.
China
Cement and coal processing operations favor abrasion-resistant hammer mill configurations for silica-laden feedstocks. Ministry of Ecology and Environment standards tighten dust emission controls at mineral processing sites. Shandong Peninsula and Yangtze River Delta manufacturing zones source rotating assemblies from regional alloy steel suppliers.
Australia
Western Australian mining operations pioneer equipment-as-a-service procurement models transferring maintenance burden to OEMs. Work Health and Safety regulations enforce respirable crystalline silica exposure limits at remote extraction sites. Pilbara iron ore and Chilean copper belt operations specify identical hammer mill configurations for abrasive mineral duties.
Lump Breaker Machines Market Competitive Landscape
Midwestern US producers anchor one tier; European specialists hold premium positions through ATEX certification depth. The vendor base separates into scale-driven fabricators, containment-integrated specialists, and regional service providers. Strategic moves concentrate on backward integration into alloy steel sourcing and geographic expansion through distribution partnerships.
Among US-based fabricators, Prater Industries, Schutte Hammermill, and Franklin Miller occupy distinct positioning vectors. Prater Industries exemplifies the Midwest manufacturing footprint archetype serving domestic chemical processors. Schutte Hammermill represents specialized hammer mill configuration expertise for abrasive mineral applications. Franklin Miller anchors the sanitary-grade design tier penetrating pharmaceutical and food processing installations with isolator-compatible specifications.
| Leading Market Players |
|---|
| Prater Industries |
| Stedman Machine Company |
| Schutte Hammermill |
| Palamatic Process |
| Hapman |
| WAMGROUP |
| Munson Machinery |
| Franklin Miller |
| Carrier Vibrating Equipment |
| Others |
Pricing and Supply Chain Analysis
ATEX-certified premium configurations command three-to-fourfold multiples over standard mechanical units, a divergence that traces directly to Italian and German motor supplier concentration for explosion-proof drives and the extended certification timelines that lock in scarcity rents. That premium tier sources rotor shafts through specialized alloy steel mills in Germany and Japan, while commodity hammer mills draw from regional carbon steel suppliers in India and China, creating parallel supply chains segmented by certification burden rather than manufacturing complexity alone.
Pricing Analysis
Distributor margins absorb 15-25 points on pharmaceutical-grade units routed through specialized process equipment dealers, whereas direct OEM relationships in mining verticals trade those markups for volume commitments and long-term consumables contracts. Three-tier pricing structure across premium containment-integrated, standard sealed-system, and economy open-frame levels tracks ATEX, OSHA, and baseline CE certification tiers respectively. Cost compression in the standard tier intensifies as Indian fabricators scale mechanical drive production under PLI chemical scheme subsidies. Mining operators exhibit lowest price sensitivity due to equipment-as-a-service procurement models that shift capital burden to OEMs.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston, and Singapore maintain finished goods inventory for 6-8 week coverage of European, North American, and Asia-Pacific demand clusters respectively. Manufacturing concentration in Germany, the United States, and China reflects proximity to Rhineland chemical corridors, Gulf Coast petrochemical infrastructure, and domestic cement processing scale. Rotor assemblies depend on nickel-molybdenum alloy steel from specialty mills in Japan and Sweden, with hammer forgings sourced from Indian and Chinese foundries. Single-source vulnerability concentrates in ATEX-certified motor supply from Italian and German producers. Distribution runs through authorized dealer networks for pharma and food verticals, while mining and chemical procurement favors direct OEM engagement with embedded service technicians.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lump breaker machines market functions as a geographic-arbitrage play where European regulatory stringency under REACH and ATEX sustains premium pricing power, while Indian PLI scheme subsidies compress landed costs for standard mechanical configurations serving price-sensitive Asian chemical processors.
For Market Incumbents: Anticipate margin compression in standard mechanical tiers as Indian fabricators scale under capital subsidy programs, and defend position by deepening backward integration into alloy steel sourcing through captive forging partnerships in Sweden or Japan. Prioritize ATEX certification pipeline investment to maintain premium tier scarcity rents against emerging Eastern European competitors. For New Entrants and Emerging Players: Mid-tier Indian agrochemical producers represent the most penetrable buyer archetype, underserved by incumbent service infrastructure despite PLI scheme equipment eligibility. Target polymer recycling mandates in the EU as a white-space application requiring gentle low-shear rotary designs that preserve molecular chain length. Pursue equipment-as-a-service financing partnerships to bypass capital expenditure approval barriers at remote mining operations. For Investors and Strategic Acquirers: Consolidation pressure builds where ATEX certification backlogs exceed 8 months and specialized welding qualifications for pharmaceutical-grade pressure vessels remain scarce across Midwest US manufacturing zones. Five-to-ten year viability favors fabricators with demonstrated European notified body relationships and installed base density in synchronized chemical production clusters. Monitor Italian and German motor supplier capacity expansion announcements as the critical inflection signal for premium tier margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alloy Steel | Captive supply of nickel-molybdenum grades insulates rotor fabrication from commodity volatility and secures lead time advantage. |
| ATEX Certification Pipeline Expansion | European notified body relationships accelerate market entry timelines and sustain premium pricing power against non-certified competitors. |
| Equipment-as-a-Service Model Deployment | Per-tonne pricing transfers maintenance burden to OEMs while locking processors into long-term consumables supply agreements. |
| Pharmaceutical Containment Integration | Isolator-compatible designs with automated clean-in-place capability penetrate high-margin Swiss and Irish formulation hubs. |
| Regional Distribution Hub Establishment | Singapore and Rotterdam centers compress delivery timelines for Asia-Pacific and European chemical corridor demand clusters. |
Research Methodology
Direct dialogue with plant engineers at German Rhineland chemical facilities, maintenance directors at Western Australian mining operations, procurement leads at Indian agrochemical producers, and aftermarket service heads at Midwest US fabricators grounded qualitative findings in operational reality. Secondary validation drew from customs and trade data, SEC 10-K filings of listed capital goods producers, ECHA REACH registration databases, and OSHA enforcement action records. Bottom-up equipment installation tracking and top-down chemical processing capacity expansion forecasts were triangulated to constrain estimate variance.
Bottom-up modeling aggregated individual facility procurement patterns across machine type, technology, and application segments, while top-down analysis calibrated against chemical processing, pharmaceutical manufacturing, and mining output projections across the analysis window. Segmentation dimensions included certification tier, rotor configuration, drive technology, and end-use industry vertical. CAGRs were derived from regression against historical replacement cycle data and regulatory mandate implementation schedules. Forecast inputs incorporated alloy steel price indices and ATEX certification queue lengths as industry-specific demand shapers.
Underlying measurement precision varies by segment; pharmaceutical and food processing installations carry tighter precision due to FDA and EMA validation documentation requirements, while mining equipment-as-a-service arrangements exhibit wider variance due to confidential contract terms. Forecasts reflect assumptions around regulatory enforcement continuity, subsidy program duration, and motor supplier capacity expansion. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Pneumatic Equipment Market
Material Handling Equipment
Global Bop Handling Systems Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
North America Conveyor Belt Market
Material Handling Equipment
Industrial Wood Chipper Market
Material Handling Equipment
Pharmaceutical Material Handling Equipment Market
Material Handling Equipment
Dry Bulk Handling System Market
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Light Duty Telehandler Market
Material Handling Equipment
Lifting Machinery Market
Material Handling Equipment
Australia Forklift Rental Market
Material Handling Equipment
Loader Crane Market
Material Handling Equipment
Hydraulic Cylinder Rod Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
GCC Conveyor Belt Market
Material Handling Equipment
Mobile Conveyor Market