
 Spiral Fitting Machines Market | 2026-2036
Spiral Fitting Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Spiral Fitting Machines Market Analytics
REACH compliance is realigning the cost-of-entry calculus for European suppliers of spiral fitting equipment. Mestek Machinery leverages its vertical integration to control raw material sourcing for duct-forming systems. Spiro International SA anchors its competitive position through specialized R&D in automated coil-line technology. Lockformer competes on manufacturing scale across North American distribution channels.
Spiral fitting machines form helical seams on sheet metal to produce round ductwork, typically handling galvanized steel or aluminum coils from 0.4 mm to 1.2 mm thickness at speeds up to 30 meters per minute. These systems serve HVAC contractors and industrial fabricators requiring airtight, structurally rigid pneumatic and ventilation conduits. Electric machines dominate installed base value due to precision motor control and lower operating costs, while CNC technology segments command premium positioning where complex geometries and repeatability standards apply. Manual machines retain share in emerging workshops with constrained capital budgets and intermittent production volumes.
EPA energy efficiency guidelines shape product specifications for equipment sold into US commercial building projects. CE marking requirements under the EU Machinery Directive govern safety interlocks and operator guarding for European deployments. China's GB standards for ventilation equipment quality influence export-oriented manufacturers serving Asian construction markets. Stakeholders must monitor how evolving carbon accounting rules affect material selection and equipment lifecycle valuations across their installed base.
Market Dynamics
Commercial building energy codes in Germany, the United States, and China are tightening simultaneously, forcing HVAC contractors to replace legacy pneumatic ductwork with precision-formed spiral systems that meet airtightness mandates.
Growth Catalysts
- Electric motor precision:Servo-controlled forming heads enable tighter seam tolerances required by updated German DIN standards for commercial ventilation. Fabricators in Stuttgart and Munich report retrofit demand from municipal building upgrades.
- REACH substance restrictions:ECHA's evolving chemical compliance rules are eliminating solvent-based sealants from legacy duct assembly, redirecting specification toward mechanically locked spiral seams that require no adhesives.
- Automated coil-line integration:Manufacturing facilities in China's Pearl River Delta are replacing batch-fed pneumatic systems with continuous-feed electric spiral formers tied directly to ERP production scheduling.
Market Restraints
- Galvanized steel coil volatility:Zinc input cost swings compress margin predictability for equipment buyers financing 15-year production line investments.
- Specialized technician scarcity:CNC programming and servo calibration skills concentrate in Germany's Baden-Württemberg and China's Jiangsu province, limiting deployment speed elsewhere.
- Aluminum substitution ceiling:Lightweight aluminum ductwork for data center cooling faces GB standard certification delays that block specification in Beijing and Shanghai commercial projects.
Strategic Opportunities
- India's PLI-linked manufacturing:The country's production-linked incentive scheme for capital goods is attracting spiral fitting machine assembly to Pune and Chennai industrial corridors.
- Carbon accounting integration:EU CSRD disclosure requirements are creating specification preference for equipment with embedded emissions tracking and lifecycle documentation.
- Rental/lease channel emergence:Project-based HVAC contractors in Texas and Florida are accessing spiral formers through equipment-as-a-service models that transfer obsolescence risk.
Industry Challenges
- CNC retrofit complexity:Legacy pneumatic machine bases require complete control system replacement to achieve CE-marked safety interlocks, extending commissioning timelines.
- Cross-border certification lag:GB standard test results from Shanghai laboratories face extended mutual recognition delays with EU Notified Bodies, fragmenting product launch sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spiral Fitting Machines Market |
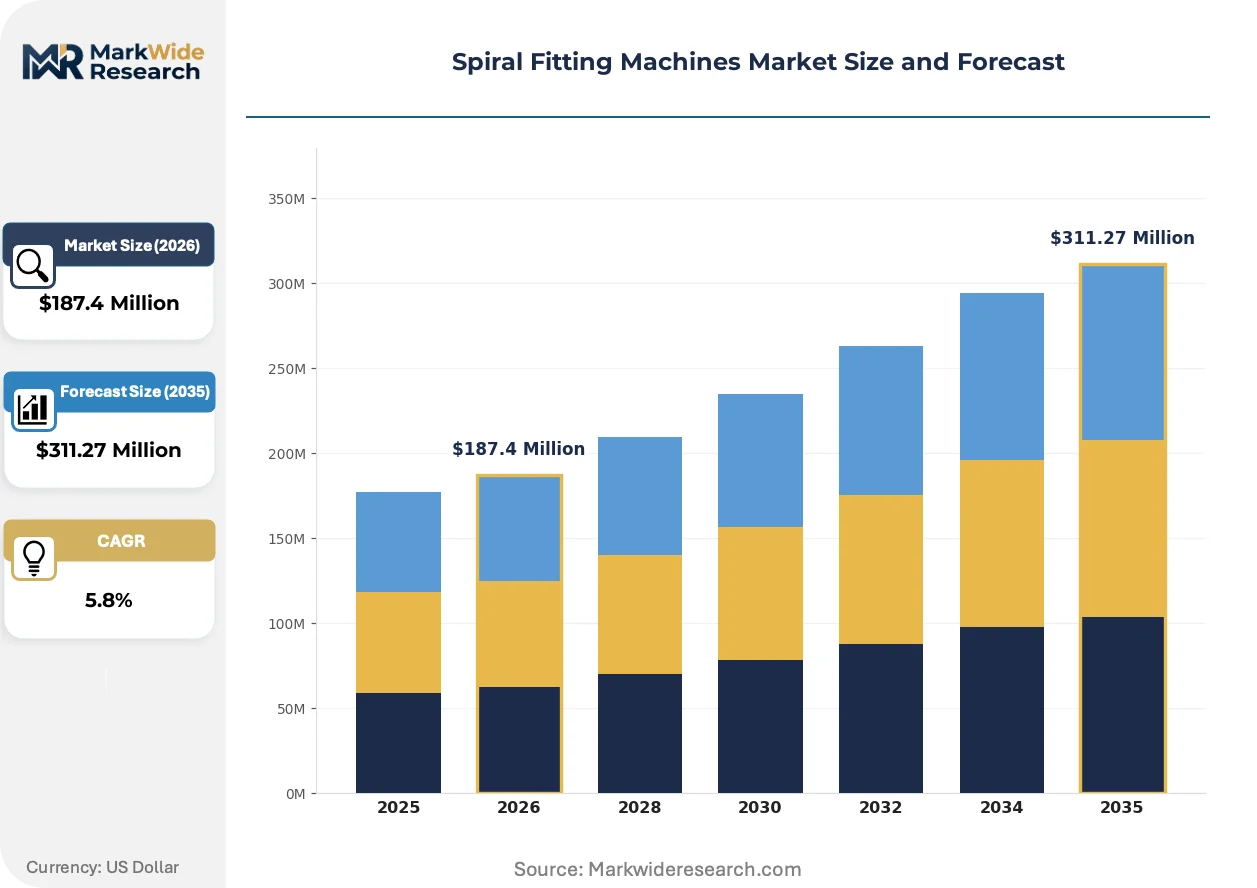
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Machines, Pneumatic Machines, Electric Machines, Manual Machines End User: Manufacturing Facilities, Construction Companies, Automotive Workshops, Metal Fabrication Technology: Computerized Systems, CNC Technology, Analog Systems, Robotics Application: Pipe Fitting, Cable Management, Structural Assembly, HVAC Installation |
| Companies Covered | Mestek Machinery, Spiro International SA, ISM Machinery, COMAC, Lockformer, ISABE, Tenengroup, METU MAKINA, RAS Reinhardt Maschinenbau GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spiral Fitting Machines Market Evolving Landscape
Digital thread integration is rewiring how spiral fitting machines connect to broader manufacturing ecosystems, with real-time seam quality data flowing directly into building information modeling systems.
Servo-electric forming heads with integrated laser seam monitoring are converging with cloud-based predictive maintenance platforms. Tier-one HVAC contractors in Germany's Ruhr region are deploying these systems to eliminate manual inspection stations. The convergence is compressing total installed cost justification cycles from three years to eighteen months for high-volume duct fabricators.
EPA energy efficiency guidelines for commercial buildings are mandating specific duct leakage rates that legacy equipment cannot achieve. Equipment specification documents in California and New York now require third-party verified airtightness certification. Manufacturers serving these states are reengineering forming roll geometries to guarantee seam performance under variable thermal cycling.
Buyers are unbundling after-sales service from initial equipment purchase, preferring regional technical service contracts over factory-direct maintenance agreements. Independent service providers in Texas and Ohio are capturing calibration and spare parts revenue that OEMs previously controlled. This channel fragmentation is most pronounced among mid-volume contractors operating 2-4 machine shops.
Spiral Fitting Machines Market Segmentation
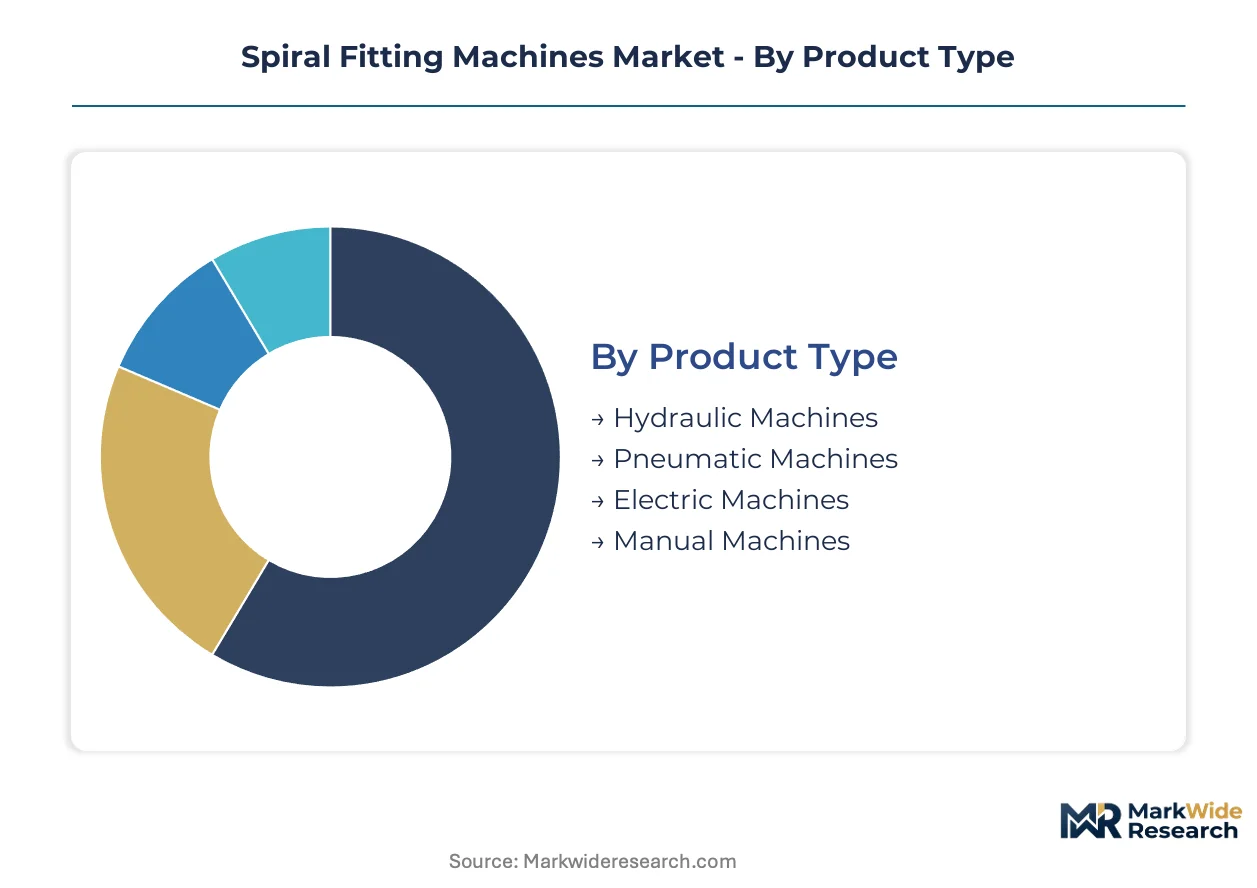
Spiral fitting machines serve distinct operational profiles across fabrication environments. Procurement patterns diverge sharply between high-volume automated facilities and intermittent-production workshops, with technology choices locking in fifteen-year cost trajectories.
Product Type:
Capital intensity and energy efficiency mandates separate buyers across this dimension, with operating cost exposure driving specification divergence between municipal contractors and industrial fabricators.
- Electric Machines:Servo-controlled forming heads deliver seam tolerances within 0.2 millimeters for precision HVAC ductwork. Demand concentrates in Germany's commercial building retrofit sector where DIN airtightness standards now mandate verified leakage rates below 0.9 liters per second per square meter.
- Pneumatic Machines:Compressed-air systems dominate legacy installed bases in China's Pearl River Delta manufacturing corridors. Buyers face REACH-aligned solvent elimination pressures that mechanically locked spiral seams resolve without adhesive dependencies.
- Hydraulic Machines:High-tonnage forming capacity serves structural steel applications in heavy fabrication yards along India's Chennai industrial belt.
- Manual Machines:Hand-cranked units retain viability in emerging market workshops across Vietnam and Indonesia with sub-500-unit annual production volumes.
Electric machines lead volumes today; manual machines are gaining share fastest in Southeast Asian capital-constrained markets.
End User:
Production scale and specification stringency define customer archetypes, with certification requirements fragmenting addressable markets across building codes and industrial safety regimes.
- Manufacturing Facilities:Continuous-feed coil-line integration demands ERP-connected spiral formers operating at 25-30 meters per minute. China's Jiangsu province electronics manufacturers are replacing batch-fed systems to meet export-oriented quality traceability requirements.
- HVAC Installation:Commercial building contractors in Texas and Florida specify equipment-as-a-service access models that transfer obsolescence risk from balance sheets to operating expenditure.
- Construction Companies:Project-based procurement cycles concentrate demand in Germany's municipal building upgrade programs across Stuttgart and Munich metropolitan zones.
- Metal Fabrication:Job-shop operators in Ohio and Pennsylvania unbundle after-sales service from initial purchase, preferring regional technical contracts over factory-direct maintenance.
- Automotive Workshops:Exhaust system fabricators in Mexico's Querétaro automotive cluster require quick-change forming heads for mixed-model production.
Manufacturing facilities dominate current procurement value; HVAC installation contractors are expanding most quickly through rental channel adoption.
Technology:
Control system sophistication determines repeatability certification eligibility, with cloud connectivity emerging as a procurement discriminator among tier-one contractors.
- CNC Technology:Programmable forming geometries enable complex elbow and transition piece production without manual setup changeovers. Germany's Ruhr region HVAC contractors deploy these systems to eliminate dedicated inspection stations through integrated laser seam monitoring.
- Computerized Systems:PC-based control architectures with Ethernet/IP connectivity feed real-time quality data directly into building information modeling platforms. California and New York now require third-party verified airtightness certification that these systems document automatically.
- Robotics:Automated material handling and coil feeding reduce direct labor content in high-volume operations across China's automated production lines.
- Analog Systems:Relay-logic controls persist in price-sensitive emerging markets where technician scarcity limits digital upgrade feasibility.
CNC technology anchors premium positioning today; computerized systems are climbing the fastest as BIM integration becomes mandatory.
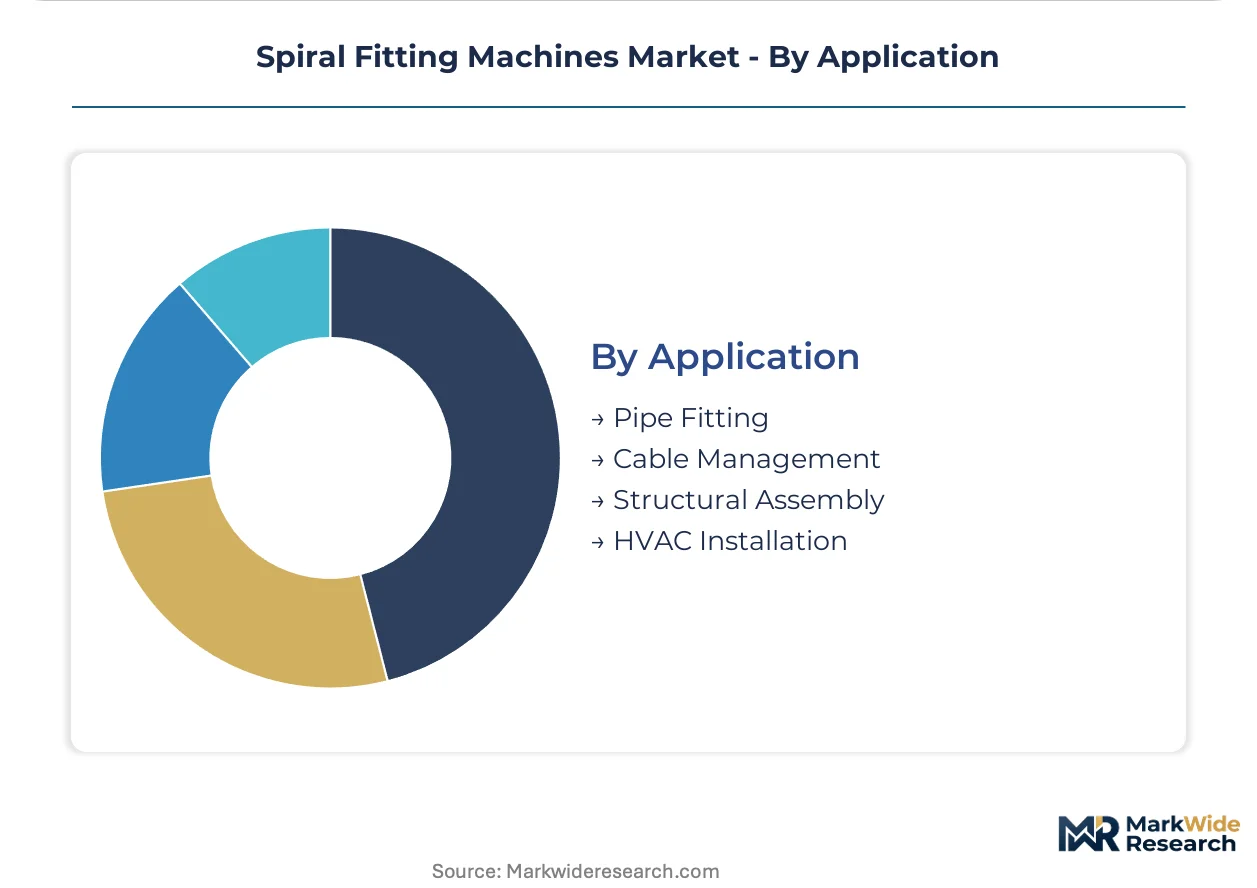
Application:
Performance validation requirements and lifecycle cost exposure shape specification divergence, with regulatory leakage mandates forcing equipment replacement cycles in commercial construction.
- HVAC Installation:Round ductwork for commercial ventilation demands seam integrity under variable thermal cycling. EPA energy efficiency guidelines in California and New York now specify maximum allowable leakage rates that legacy equipment cannot achieve.
- Pipe Fitting:Process piping for pharmaceutical and food-grade applications requires surface finish certification that electric forming heads deliver consistently.
- Cable Management:Spiral-wound conduit for data center infrastructure faces GB standard certification delays blocking specification in Beijing and Shanghai projects.
- Structural Assembly:Architectural metalwork applications in Germany's commercial building sector prioritize aesthetic seam appearance alongside mechanical performance.
HVAC installation commands the largest equipment installed base; pipe fitting applications are expanding most quickly in regulated process industries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered precision duct-forming equipment in the post-war reconstruction era, establishing the technical foundation that shaped global spiral fitting machine standards. Commercial building energy codes now force replacement cycles across multiple continents.
Germany
DIN airtightness mandates below 0.9 liters per second per square meter drive municipal retrofit programs in Stuttgart and Munich. ECHA REACH compliance eliminates solvent-based sealants from legacy assembly methods. The Ruhr region hosts tier-one HVAC contractors deploying servo-electric forming heads with integrated laser monitoring.
United States
EPA energy efficiency guidelines mandate duct leakage rates that legacy pneumatic equipment cannot achieve. California and New York specification documents now require third-party verified airtightness certification. Texas and Florida contractors access spiral formers through emerging equipment-as-a-service rental channels.
China
GB standards for ventilation equipment quality reshape export-oriented manufacturer requirements. The Pearl River Delta electronics sector replaces batch-fed pneumatic systems with continuous-feed electric coil-line integration. Jiangsu province fabricators upgrade for quality traceability compliance with European import regulations.
India
Production-linked incentive schemes for capital goods attract spiral fitting machine assembly to Pune and Chennai industrial corridors. BIS certification alignment with international standards accelerates domestic specification adoption. Heavy fabrication yards along Chennai's industrial belt demand high-tonnage hydraulic forming capacity.
United Arab Emirates
Commercial megaproject construction in Dubai and Abu Dhabi specifies precision-formed spiral ductwork for high-efficiency HVAC systems. MOHAP-equivalent building safety regulations import European CE marking standards for equipment deployment. Regional contractors source electric machines with ERP connectivity for large-scale facility rollouts.
Spiral Fitting Machines Market Competitive Landscape
The competitive structure tilts toward vertically integrated specialists with captive control over raw material sourcing and forming system engineering. Mid-scale regional fabricators occupy fragmented territory between these anchored positions and price-sensitive emerging market entrants. Two archetypes dominate: precision-engineering specialists serving DIN-certified European contractors, and scale-oriented manufacturers distributing through North American dealer networks. Competitive moves concentrate on strategic partnerships for coil-line integration and geographic expansion into India's PLI-linked manufacturing corridors.
Among European precision-engineering specialists, Spiro International SA and RAS Reinhardt Maschinenbau GmbH exemplify the R&D-intensive tier where automated coil-line technology anchors competitive positioning. Mestek Machinery represents the vertically integrated archetype with upstream control over raw material sourcing for duct-forming systems. Lockformer occupies a position within the North American scale-driven segment, competing through manufacturing scale across established distribution channels. These three company structures illustrate how geographic origin and organizational form map onto divergent strategic postures in this equipment category.
| Leading Market Players |
|---|
| Mestek Machinery |
| Spiro International SA |
| ISM Machinery |
| COMAC |
| Lockformer |
| ISABE |
| Tenengroup |
| METU MAKINA |
| RAS Reinhardt Maschinenbau GmbH |
| Others |
Value Network & Pricing Analysis
Galvanized steel coil costs cascade through three distinct equipment pricing tiers, with zinc price volatility compressing margin predictability for buyers financing long-horizon production investments across Germany, China, and the United States.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates CNC-equipped electric machines from pneumatic legacy systems and manual units. Certification grade—CE marking for EU deployment versus GB standard alignment for China—drives price differentiation alongside after-sales service bundling. Cost compression in the standard tier intensifies because regional technical service providers capture calibration revenue previously controlled by OEMs. HVAC installation contractors in Texas and Florida exhibit highest price sensitivity through equipment-as-a-service preference, while Germany's municipal retrofit programs show lowest sensitivity due to DIN airtightness mandate compliance requirements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China's Pearl River Delta electronics manufacturers, while independent distributors serve fragmented job-shop operators across Ohio and Pennsylvania. Manufacturing concentration rests on Germany, China, and India, with Pune and Chennai industrial corridors attracting assembly under PLI-linked capital goods incentives. Raw material dependencies center on galvanized steel coils, aluminum sheet, and servo motor control systems. Single-source vulnerability in precision forming head components from Germany's Baden-Württemberg region creates supply chain risk. Distribution runs through regional dealer networks in North America and direct factory relationships for European DIN-certified contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spiral fitting machines function as a stable compounder, with commercial building energy code tightening across multiple continents driving replacement cycles that sustain equipment demand through regulatory compliance rather than discretionary investment.
For Market Incumbents: Lock in coil-line integration partnerships with ERP platform providers to defend against emerging equipment-as-a-service entrants capturing HVAC contractor preference in Texas and Florida. Deepen backward integration into raw material sourcing to buffer zinc price volatility exposure. Prioritize R&D investment in laser seam monitoring technology to maintain premium positioning against CNC retrofit competitors. For New Entrants and Emerging Players: Begin with India's PLI-linked manufacturing corridors, where domestic BIS certification alignment accelerates specification adoption among Pune and Chennai fabricators. Target manual machine replacement demand in Vietnam and Indonesia workshops with sub-500-unit annual volumes. Pursue regional technical service contracts as the primary go-to-market angle, unbundling aftermarket revenue from initial equipment sales. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale fabricators lack captive control over forming system engineering and raw material sourcing. The market supports long-term viability for vertically integrated specialists with automated coil-line technology depth. Acquisition target archetype: European precision-engineering specialists with DIN-certified installed bases. Watch for GB standard mutual recognition delays with EU Notified Bodies as inflection signal for geographic expansion timing.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Coil-Line Integration | ERP-connected spiral formers enable continuous-feed production scheduling for China's electronics manufacturers. |
| Backward Integration into Raw Materials | Captive galvanized steel coil sourcing buffers Mestek Machinery against zinc price volatility swings. |
| Equipment-as-a-Service Launch | Rental channels transfer obsolescence risk for Texas HVAC contractors seeking operating expenditure treatment. |
| Laser Seam Monitoring Deployment | Integrated quality systems eliminate manual inspection stations across Germany's Ruhr region tier-one contractors. |
| Regional Technical Service Expansion | Independent calibration providers capture aftermarket revenue from Ohio and Pennsylvania job-shop operators. |
Research Methodology
Direct dialogue with plant engineers, OEM procurement teams, aftermarket service heads, and HVAC contractor operations managers grounded the qualitative foundation. Secondary validation drew from SEC filings of industrial equipment manufacturers, customs and trade data for galvanized steel coil movements, DIN standard documentation, and ECHA REACH substance restriction updates. Bottom-up equipment shipment analysis triangulated against top-down construction spending projections across commercial building markets.
Bottom-up modeling segmented demand across electric, pneumatic, hydraulic, and manual machine categories, with end-user splits for manufacturing facilities, HVAC installation, construction companies, metal fabrication, and automotive workshops. Technology tiers—CNC, computerized, robotics, and analog—were modeled separately. Growth projections across the analysis window incorporated energy efficiency mandate implementation timelines, REACH compliance phase-out schedules, and PLI scheme uptake rates in Indian manufacturing corridors.
Several conditions sit outside the modeled scope, including extreme zinc price volatility scenarios, abrupt trade policy shifts affecting coil import tariffs, and faster-than-anticipated pneumatic system replacement acceleration in China's Pearl River Delta. Forecasts reflect assumptions about regulatory implementation pacing and technician training pipeline development. Periodic stress-testing of base assumptions is recommended against ECHA substance restriction updates and GB standard mutual recognition progress with EU Notified Bodies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Hopper Loader Market
Material Handling Equipment
Global Refuse Compactor Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Gas Connectors and Gas Hoses Market
Material Handling Equipment
Asia-Pacific Conveyors Market
Material Handling Equipment
Floor Scrubber Machine Market
Material Handling Equipment
Enclosed Belt Conveyors Market
Material Handling Equipment
Manual Lifting Light Tower Market
Material Handling Equipment
Global Loading Dock Bumpers Market
Material Handling Equipment
Industrial Sheaves and Pulleys Market
Material Handling Equipment
Global Conveyors Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Industrial Belt Drives Market
Material Handling Equipment
Sorting Equipment Market