
 Container Handler Market | 2026-2036
Container Handler Market Size, Share, and Industry Trends Forecast 2026-2036
Container Handler Market Analytics
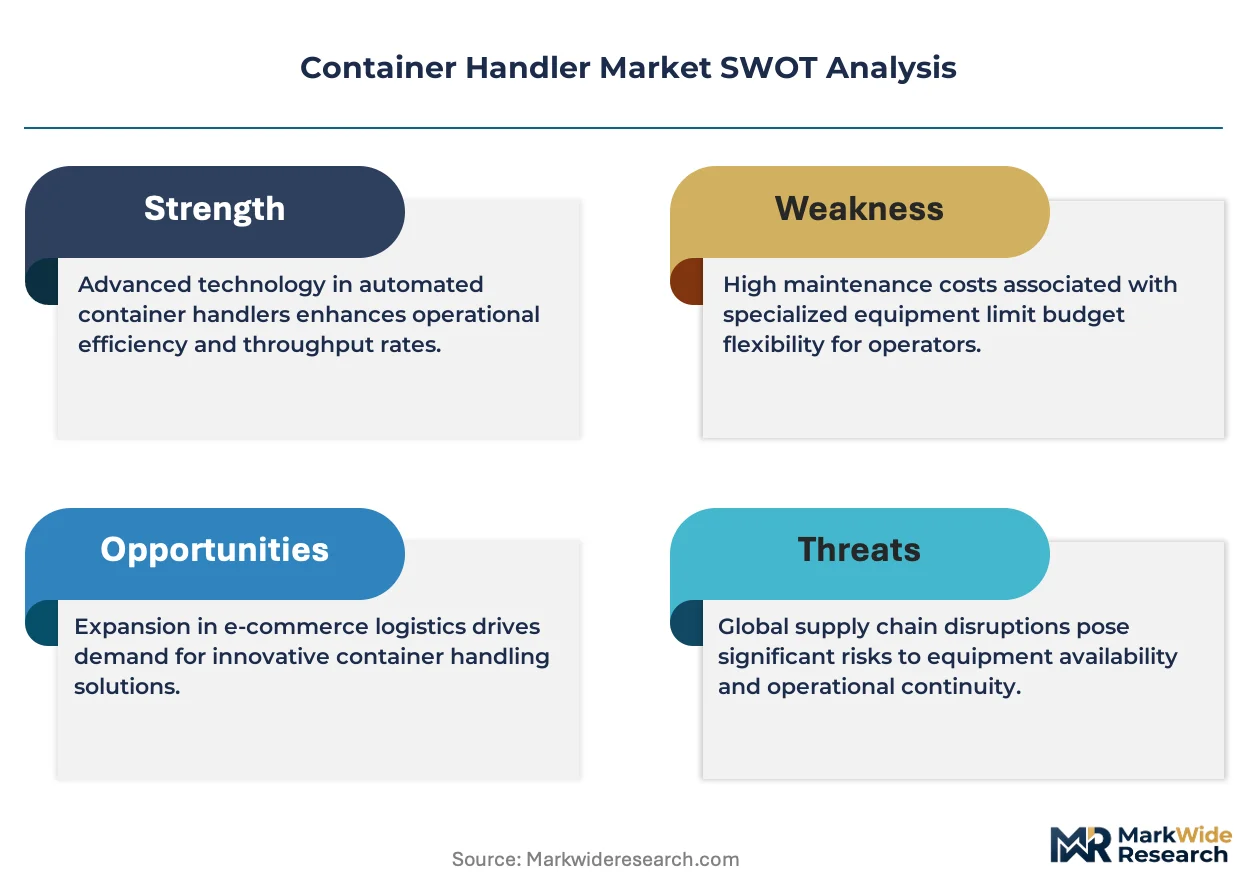
Certified crane operator shortages across major port zones is unwinding throughput capacity and forcing terminal operators toward automation-capable equipment. Konecranes leverages its deep automation portfolio to capture premium positioning in smart port deployments. Kalmar Global anchors its competitiveness through in-house production of key drivetrain components.
Container handlers are heavy-lift vehicles and cranes engineered to transport, stack, and load intermodal shipping containers, typically operating at lift heights exceeding five container tiers and load ratings from 10 to 50 tons depending on configuration. Reach stackers dominate the product mix due to their operational flexibility across medium-volume terminals, while electric and hybrid technologies are gaining fastest as port authorities enforce shore-power compatibility and zero-emission zones. Ports remain the core end-user segment, though logistics providers are emerging as a concentrated growth channel through dedicated inland container depots.
EPA marine engine standards in the United States, EU Green Deal emissions frameworks, and IMO sulfur caps collectively tighten the regulatory envelope around diesel-powered equipment and validate electric transition roadmaps. China's MEE enforces domestic non-road mobile machinery emissions tiers that parallel European benchmarks, compressing the technology adoption cycle for local manufacturers. Stakeholders must weigh automation capital intensity against labor scarcity trajectories when configuring terminal investment plans.
Market Dynamics
EU Green Deal emissions frameworks are compressing the technology adoption cycle for diesel-to-electric transitions, forcing terminal operators to front-load automation capital against tightening labor pools and shore-power mandates.
Growth Catalysts
- Shore-power compatibility mandates:Port authorities in Rotterdam and Hamburg enforce zero-emission zones that require electric container handlers for berth access, accelerating fleet replacement cycles.
- China's port throughput expansion:The country's MEE emissions tiers for non-road mobile machinery parallel European benchmarks, validating domestic manufacturer electrification roadmaps.
- Certified crane operator scarcity:Labor shortages across major port zones unwind throughput capacity and pull terminal operators toward automation-capable equipment investments.
Market Restraints
- Battery energy density limitations:Current lithium-ion chemistry constrains operational uptime for heavy-lift configurations exceeding 40-ton load ratings in multi-shift terminals.
- Charging infrastructure capital intensity:Megawatt-class shore-power installations at berth and yard positions require dedicated grid upgrades that compress project IRRs.
- Steel and copper input volatility:Boom structure fabrication and high-power cabling expose manufacturers to commodity price swings that destabilize equipment pricing.
Strategic Opportunities
- Inland container depot electrification:Logistics providers in Germany and the Netherlands are deploying dedicated electric reach stacker fleets for intermodal rail connections.
- Automation-software convergence:Terminal operating systems integrating machine vision and fleet management create premium positioning for OEMs with captive software stacks.
- EU Green Deal retrofit incentives:Subsidized repowering programs for existing diesel handlers open aftermarket revenue streams for drivetrain conversion kits.
Industry Challenges
- Automation integration complexity:Legacy terminal infrastructure requires sensor retrofit and control-system harmonization that extends commissioning timelines.
- Functional safety certification bottlenecks:ISO 3691-4 compliance for autonomous operation demands extensive field validation that delays market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Container Handler Market |
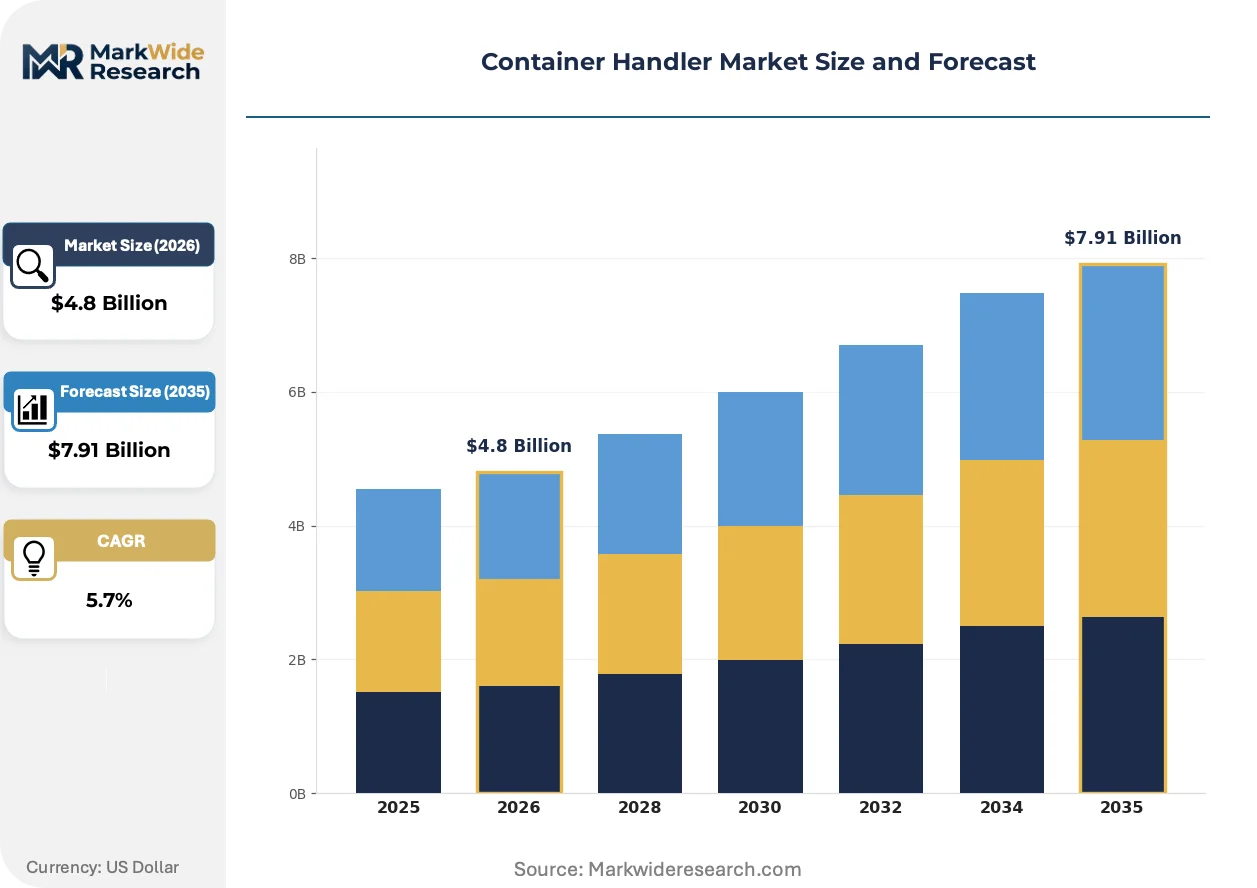
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reach Stackers, Straddle Carriers, Ship-to-Shore Cranes, Terminal tractors Technology: Electric, Hybrid, Diesel, Automation End User: Ports, Shipping Lines, Freight Forwarders, Logistics Providers Capacity: Below 10 Tons, 10-20 Tons, 20-30 Tons, Above 30 Tons |
| Companies Covered | SANY Group, Liebherr Group, Konecranes, Kalmar Global, Shanghai Zhenhua Heavy Industries, Hyster-Yale Materials Handling, Taylor Machine Works, Doosan Industrial Vehicle, Terex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Container Handler Market Evolving Landscape
Electrification and automation are rewiring competitive positioning in container handling equipment, with regulatory compliance and labor scarcity forcing simultaneous technology bets across fleet modernization programs.
Battery-electric drivetrains are bifurcating the product mix between premium configurations with fast-charge capability for continuous operations and standard variants suited for single-shift deployments with overnight charging. Medium-volume terminals in Belgium and Spain are adopting the standard tier to meet EU Green Deal deadlines without grid infrastructure overhaul. This technology split is compressing pricing power for mid-range diesel alternatives that lack either performance or cost advantage.
EPA marine engine standards and EU Green Deal emissions frameworks collectively tighten the regulatory envelope around diesel-powered equipment. These rules validate electric transition roadmaps and disqualify non-compliant handlers from port access in Los Angeles, Long Beach, and Rotterdam. Equipment lessors in North America are responding by accelerating residual value write-downs for Tier 3 diesel assets.
Service unbundling is fragmenting traditional procurement relationships as terminal operators separate equipment purchase from maintenance and software subscriptions. Third-party fleet management providers in Singapore and Dubai are capturing recurring revenue streams that OEMs previously monopolized. This shift is most visible among logistics providers operating multi-site container depots where standardized service contracts reduce operational variance.
Container Handler Market Segmentation
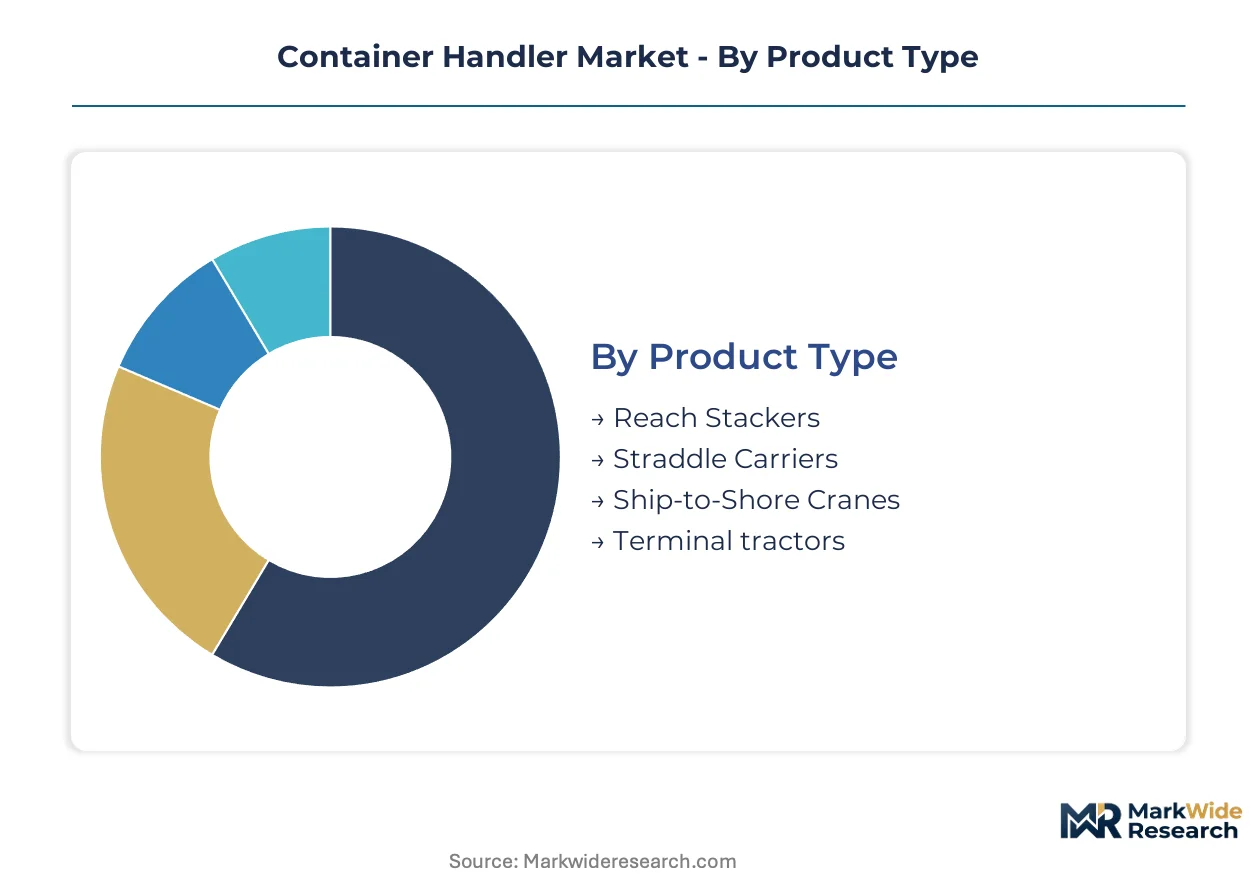
Container handler procurement decisions split across operational requirements, regulatory compliance tiers, and automation readiness. Terminal operators configure fleet mixes by balancing lift capacity against berth access rules and labor availability constraints.
Product Type:
Reach stackers face intensifying substitution pressure from straddle carriers in automated terminal deployments, while ship-to-shore cranes defend position through irreplaceable berth infrastructure requirements.
- Reach Stackers:Rubber-tired vehicles with telescopic booms handle container stacking up to five tiers and excel in medium-volume terminals requiring yard mobility. Demand concentrates in Germany and the Netherlands where logistics providers deploy dedicated fleets for inland rail connections, constrained by battery energy density limits above 40-ton configurations.
- Straddle Carriers:Self-propelled gantry systems span containers for yard stacking without external crane support, enabling higher density storage. Rotterdam and Hamburg port authorities enforce zero-emission zone access rules that favor electric variants in new procurement, displacing diesel units from berth-adjacent operations.
- Ship-to-Shore Cranes:Fixed quayside infrastructure with lift heights exceeding 50 meters serves ultra-large container vessels.
- Terminal tractors:Low-speed yard haulers shuttle containers between quay and stacking zones.
Reach stackers anchor the volume base while straddle carriers gain share at the steepest rate.
Technology:
Cost tier stratification separates premium fast-charge electric configurations from standard overnight-charging variants, with hybrid systems occupying an intermediate position under EU Green Deal retrofit incentives.
- Electric:Battery-electric drivetrains with lithium-ion chemistry power continuous operations through megawatt-class shore-power installations. Rotterdam and Los Angeles port authorities mandate electric propulsion for berth access, validating fleet replacement roadmaps despite charging infrastructure capital intensity.
- Hybrid:Diesel-electric architectures reduce fuel consumption through regenerative braking and engine downsizing. Medium-volume terminals in Belgium and Spain adopt hybrid reach stackers to meet EU Green Deal deadlines without grid overhaul, compressing pricing power for mid-range diesel alternatives.
- Diesel:Conventional internal combustion systems face residual value write-downs as EPA marine engine standards tighten.
- Automation:Autonomous navigation and machine vision integration demand ISO 3691-4 certification.
Electric configurations command the premium tier while hybrid systems bridge the cost gap for mid-market terminals.
End User:
Application concentration varies sharply by customer type, with ports driving infrastructure-scale procurement and logistics providers emerging as a fragmented but fast-growing channel through inland depot specialization.
- Ports:Public and private terminal operators deploy mixed fleets across quay, yard, and gate operations. China's port throughput expansion drives heavy investment in automated infrastructure, with MEE emissions tiers validating domestic manufacturer electrification roadmaps.
- Shipping Lines:Ocean carriers operating dedicated terminals prioritize equipment standardization across hub ports. Certified crane operator shortages unwind throughput capacity and pull operators toward automation-capable investments.
- Freight Forwarders:Intermediaries with limited physical assets rely on leased equipment or third-party terminal services.
- Logistics Providers:Dedicated inland container depots in Germany and the Netherlands deploy electric reach stacker fleets for rail connections, capturing service unbundling opportunities as terminal operators separate purchase from maintenance contracts.
Ports dominate absolute equipment volume while logistics providers expand most quickly through inland depot electrification.
Capacity:
Volume distribution skews toward mid-range tiers where operational flexibility intersects with regulatory compliance, while extreme capacity segments serve specialized heavy-lift and light-duty niches.
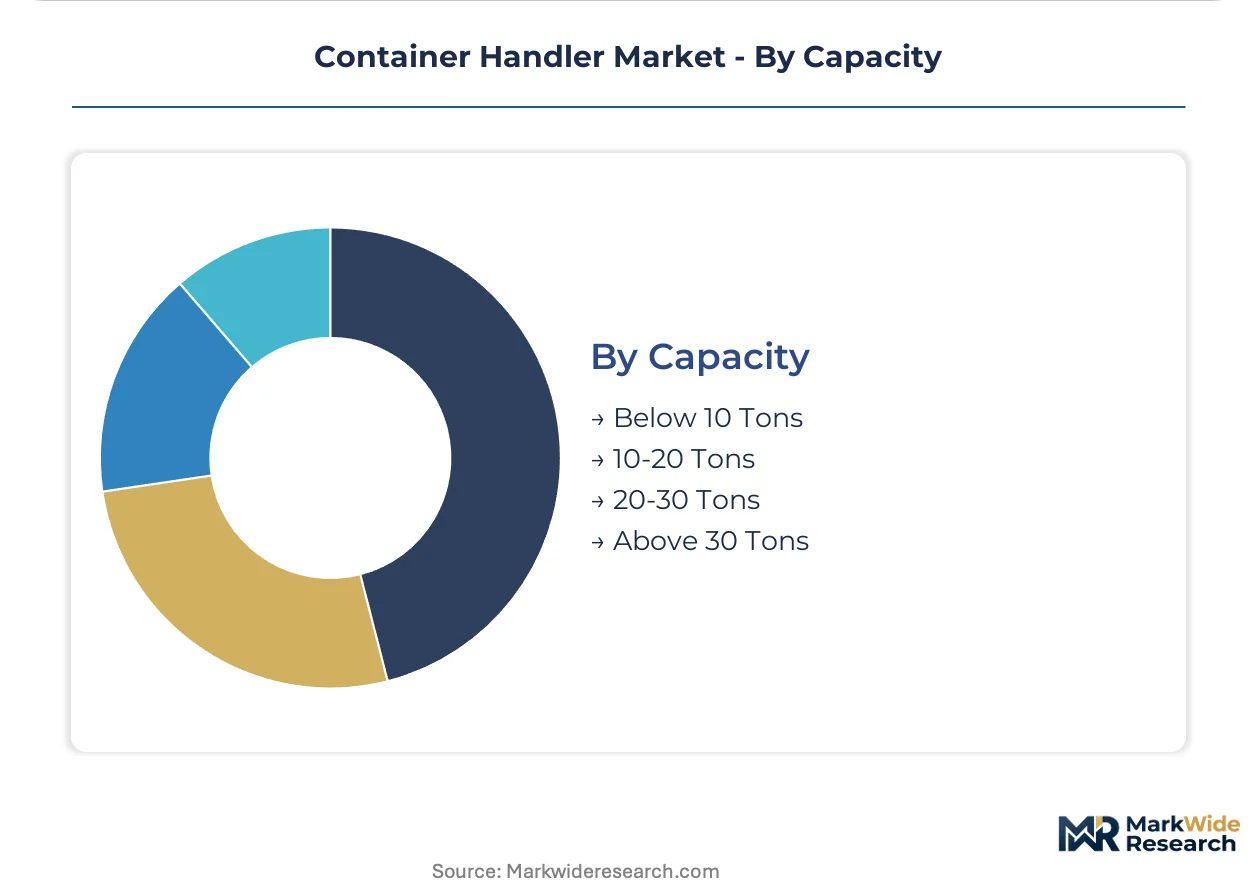
- 10-20 Tons:Standard reach stacker configurations handle single-container lifts across general cargo and intermodal operations. Medium-volume terminals in Spain and Belgium concentrate procurement in this tier to balance EU Green Deal compliance against capital constraints.
- 20-30 Tons:Heavy-lift variants accommodate twin-container handling and dense stacking requirements. China's automated terminal expansion drives demand for high-capacity electric configurations, though battery energy density limits constrain multi-shift uptime.
- Below 10 Tons:Light-duty terminal tractors and specialty handlers serve gate and maintenance operations.
- Above 30 Tons:Ultra-heavy configurations address breakbulk and project cargo intermodal requirements.
The 10-20 ton segment anchors procurement volume while the 20-30 ton tier climbs fastest on automation and electrification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment pricing power concentrates in German and Dutch port clusters where EU Green Deal mandates accelerate fleet replacement, while Chinese manufacturers compete on cost through domestic electrification scale advantages.
United States
Los Angeles and Long Beach port authorities enforce EPA marine engine standards that disqualify Tier 3 diesel handlers from berth access. The Inflation Reduction Act subsidizes charging infrastructure for electric yard equipment. Pacific Northwest terminals in Seattle-Tacoma are deploying automation-capable reach stackers to address certified crane operator shortages.
Germany
Hamburg and Bremerhaven enforce zero-emission zone rules requiring electric propulsion for berth-adjacent operations. The country's national emissions regulator accelerates diesel-to-electric transitions through retrofit incentive programs. Inland container depots in the Ruhr industrial corridor are standardizing electric reach stacker fleets for rail intermodal connections.
China
Shanghai and Ningbo-Zhoushan port throughput expansion drives automated terminal infrastructure investment at unmatched scale. The MEE enforces non-road mobile machinery emissions tiers that parallel European benchmarks. Yangtze River Delta manufacturers are compressing technology adoption cycles for domestic electrification roadmaps.
Netherlands
Rotterdam port authority mandates shore-power compatibility for all new container handler procurements. The EU Green Deal framework validates fleet replacement timelines for medium-volume terminals. Logistics providers in the Randstad cluster are separating equipment purchase from maintenance contracts through third-party fleet management.
South Korea
Busan port automation programs prioritize ISO 3691-4 certified autonomous handlers for continuous operations. The country's industrial technology regulator supports fast-charge battery infrastructure for megawatt-class shore-power installations. Seoul Capital Area equipment lessors are accelerating residual value write-downs for diesel assets ahead of compliance deadlines.
Container Handler Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where automation-capable OEMs command premium positioning against scale-driven fabricators. The market consolidates around three strategic groupings: integrated port solution providers with captive software stacks, drivetrain specialists with in-house component production, and regional manufacturers leveraging domestic electrification scale. Competitive moves center on M&A for automation capabilities and strategic partnerships for charging infrastructure deployment.
Among automation-integrated specialists, Konecranes and Kalmar Global exemplify the premium-tier archetype through software-hardware convergence. SANY Group and Shanghai Zhenhua Heavy Industries occupy positions within the scale-driven Chinese manufacturing cluster. Liebherr Group anchors the European precision-engineering segment with Swiss-German heritage.
| Leading Market Players |
|---|
| SANY Group |
| Liebherr Group |
| Konecranes |
| Kalmar Global |
| Shanghai Zhenhua Heavy Industries |
| Hyster-Yale Materials Handling |
| Taylor Machine Works |
| Doosan Industrial Vehicle |
| Terex |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Yangtze River Delta fabrication clusters shapes both supply concentration and price floors for boom structures and drivetrain assemblies. Terminal operators in Rotterdam and Hamburg face compressed procurement timelines as EU Green Deal mandates force simultaneous fleet replacement cycles.
Pricing Analysis
Configured-to-order pricing for automation-integrated reach stackers commands spreads exceeding standard variants due to ISO 3691-4 certification requirements and captive software stacks. Three-tier pricing structure across premium fast-charge electric, standard overnight-charging, and hybrid retrofit tiers reflects battery chemistry grades and shore-power compatibility levels. Pricing pressure stems from steel and copper input volatility destabilizing equipment quotations. Logistics providers operating inland container depots exhibit highest price sensitivity, while automated terminal operators prioritize performance specifications over capital outlay.
Supply Chain Analysis
Inbound logistics costs through Shanghai-Ningbo port corridors and trans-Pacific lanes constrain just-in-time delivery for lithium-ion cell assemblies and high-grade steel plate. Manufacturing concentration in China, Germany, and South Korea feeds from copper cabling, rare-earth magnet, and specialty steel dependencies. Single-source vulnerability for megawatt-class charging infrastructure components poses structural risk. Distribution runs through OEM direct sales for port-scale deployments and third-party fleet management providers for logistics provider segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Container handler procurement is shifting toward platform economics as terminal operating systems demand interoperability across automation software stacks and machine vision integration.
For Market Incumbents: Consolidate automation capabilities through software-hardware convergence investments and deepen in-house drivetrain production to defend margin position against emerging electric specialists. ISO 3691-4 certification bottlenecks create defensive moats for early movers. Channel control through captive aftermarket service contracts anchors recurring revenue streams. For New Entrants and Emerging Players: Anchor in inland container depot electrification across Germany and the Netherlands where logistics providers separate equipment purchase from maintenance contracts. Battery energy density limitations above 40-ton configurations leave white space in mid-capacity electric reach stackers. Go-to-market through third-party fleet management partnerships bypasses incumbent OEM direct sales relationships. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among automation-integrated specialists with captive software stacks and aftermarket service bundling. Long-term viability favors OEMs controlling both fast-charge battery architecture and terminal operating system interoperability. Watch for inflection when residual value write-downs accelerate for Tier 3 diesel assets ahead of compliance deadlines.| Strategic Initiative | Industry Significance |
|---|---|
| Automation Software Integration | Machine vision and fleet management convergence creates premium positioning in smart port deployments. |
| Fast-Charge Infrastructure Partnership | Megawatt-class shore-power installations at Rotterdam and Los Angeles validate electric transition roadmaps. |
| Backward Integration into Battery Systems | In-house lithium-ion pack production reduces exposure to commodity cell pricing and supply constraints. |
| Retrofit Incentive Capture | EU Green Deal subsidized repowering programs open aftermarket revenue for drivetrain conversion kits. |
| Certification Acceleration | ISO 3691-4 field validation compression delays market entry for autonomous operation competitors. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with terminal operations directors, port authority procurement leads, crane operator training coordinators, and aftermarket service managers; and secondary validation through customs trade records, port throughput statistics, SEC equipment manufacturer filings, and EU emissions registry data. Bottom-up equipment shipment analysis triangulated against top-down port infrastructure investment tracking.
Across the analysis window, the forecasting framework modeled segmentation across product type, technology tier, end-user category, and capacity configuration. CAGRs derived from equipment replacement cycle analysis, regulatory compliance deadline clustering, and automation adoption curve fitting. Battery energy density improvement trajectories and shore-power infrastructure deployment schedules served as industry-specific forecast inputs.
Material uncertainties — commodity price volatility, certification timeline delays, and grid infrastructure upgrade pacing — sit outside the modeled envelope. Forecasts reflect documented assumptions about emissions regulation enforcement intensity and labor scarcity trajectories. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Asia-Pacific Forklift Truck Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Tube Rotator Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Industrial Parts Feeders Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Drum Handling Equipment Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Telescopic Crane Market
Material Handling Equipment
Material Handling Equipment Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
US Forklift Market
Material Handling Equipment
Conveyor Sprocket Market
Material Handling Equipment
Portable Loading Ramps Market