
 Global Refuse Compactor Market | 2026-2036
Global Refuse Compactor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Refuse Compactor Market Foresight
Skilled hydraulic technician availability is bifurcating the competitive landscape between legacy OEMs and emerging electric-drive entrants. Marathon Equipment Company leverages vertical integration in North American fabrication to sustain cost advantages across its stationary and self-contained lines. Husmann Umwelttechnik GmbH anchors German engineering credibility in truck-mounted compaction systems, while Wastequip LLC competes through extensive distributor control across mid-market sanitation contractors.
A refuse compactor is a heavy-duty mechanical or hydraulic compression unit designed to reduce waste volume by ratios typically exceeding four-to-one, utilizing steel-reinforced chambers and ram assemblies driven by pressurized fluid or electromechanical actuators; its primary purpose is to minimize transportation cycles, landfill footprint, and operational expenditure for high-volume waste generators. Truck-mounted compactors dominate municipal fleet procurement due to route-efficiency imperatives, while electric and solar-powered technologies represent the fastest-expanding technology segments as fleet electrification mandates propagate across European and North American jurisdictions. Stationary compactors retain mature margin pools in manufacturing plants and distribution centers where permanent installation amortizes over decade-long operational horizons.
The EPA enforces emission standards for refuse collection vehicles under its Clean Truck program, compelling OEMs to certify hydraulic and electric powertrains for nitrogen oxide compliance. The EU Green Deal and F-Gas Regulation constrain refrigerant and hydraulic fluid chemistries, reshaping component sourcing for equipment sold into member states. Stakeholders must monitor the divergence between EPA tailpipe rules and EU machinery directives when configuring product platforms for transatlantic deployment.
Market Dynamics
Fleet electrification mandates are compressing procurement cycles as municipal buyers accelerate replacement timelines to secure federal and state incentive windows before qualification thresholds shift.
Growth Catalysts
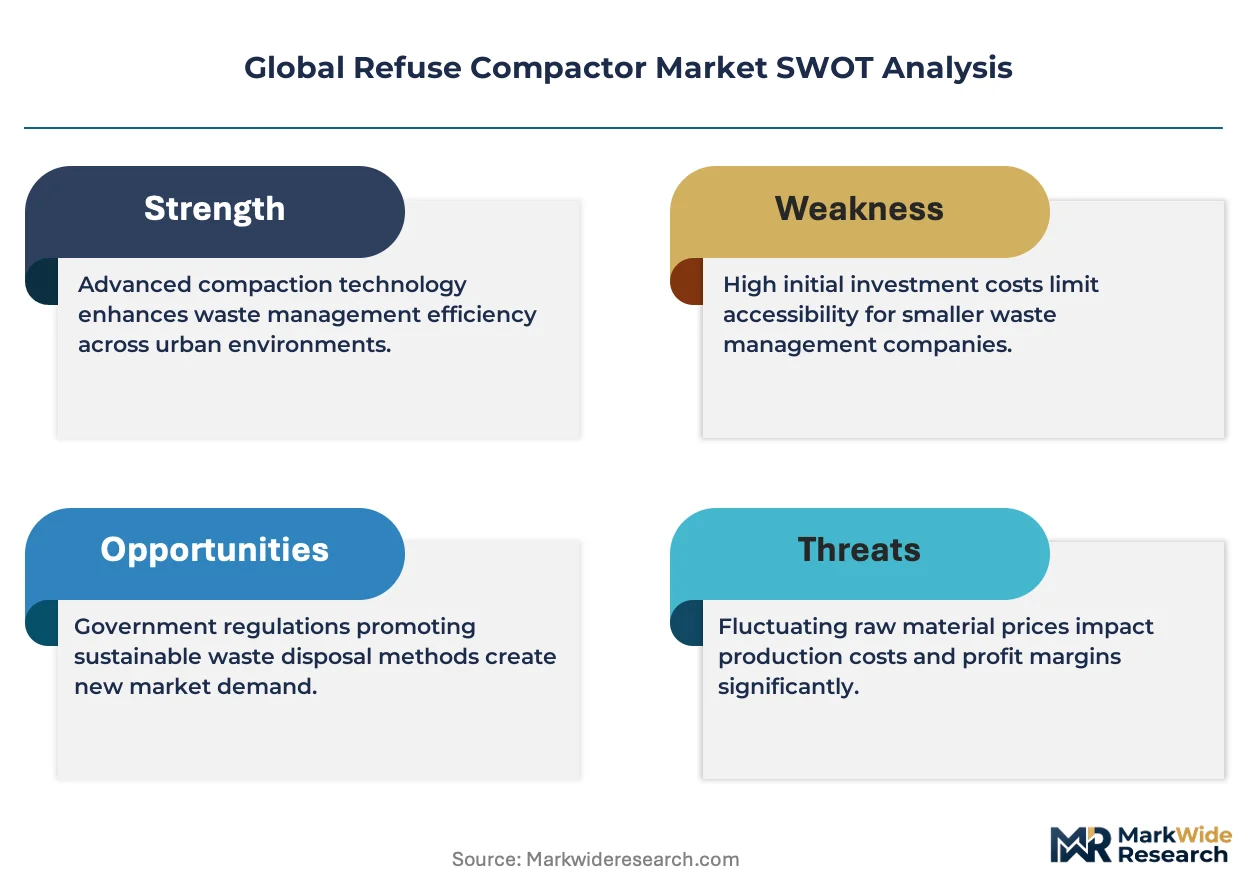
- Landfill Diversion Mandates:EPA guidelines under the Clean Truck program compel municipalities to modernize collection fleets with higher-efficiency compaction systems that reduce transport cycles and emissions intensity per ton collected.
- Battery-Electric Powertrains:Zero-emission refuse vehicles qualify for IRA tax credits and state-level clean fleet incentives, accelerating capital deployment into electrified compaction equipment across California, New York, and Texas procurement offices.
- Circular Economy Targets:Germany's national recycling quotas and the EU Green Deal's waste hierarchy enforcement are expanding truck-mounted compactor demand for source-separated organic and dry recyclable streams.
Market Restraints
- Hydraulic Fluid Cost Volatility:Base oil and additive price swings compress margin predictability for OEMs maintaining legacy product lines while transitioning to electromechanical actuation systems.
- Specialized Fabrication Concentration:Steel-reinforced chamber production clusters in Upper Midwest foundries and Ruhr Valley metalworking districts, creating geographic supply risk from energy price shocks or labor actions.
- EU F-Gas Regulation Friction:Refrigerant chemistry constraints on auxiliary cooling systems for electric compactors extend certification timelines and limit component sourcing flexibility for equipment sold into member states.
Strategic Opportunities
- Solar-Integrated Stationary Units:Off-grid compaction installations at remote industrial sites and island municipalities bypass grid dependency while qualifying for renewable energy certificates in Australia and Mediterranean jurisdictions.
- Smart Fleet Telematics Convergence:Integration of compaction load sensors with route optimization software enables pay-by-weight contracting models that shift revenue from equipment sale to performance-based service fees.
- India Urban Sanitation Expansion:Smart Cities Mission funding and Swachh Bharat infrastructure allocations are creating first-time mechanized collection demand in tier-2 municipalities previously served by manual loading.
Industry Challenges
- Hydraulic Technician Scarcity:Retirement waves among skilled fluid power specialists outpace vocational training pipeline output, forcing OEMs to absorb retraining costs or defer maintenance revenue capture.
- Electric Powertrain Integration Complexity:Battery thermal management and regenerative braking calibration for stop-start refuse routes require cross-functional engineering teams that strain mid-tier manufacturer R&D bandwidth.
- Dual Certification Burden:Divergent EPA tailpipe rules and EU machinery directives force product platform fragmentation, inflating homologation costs for manufacturers serving transatlantic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Refuse Compactor Market |
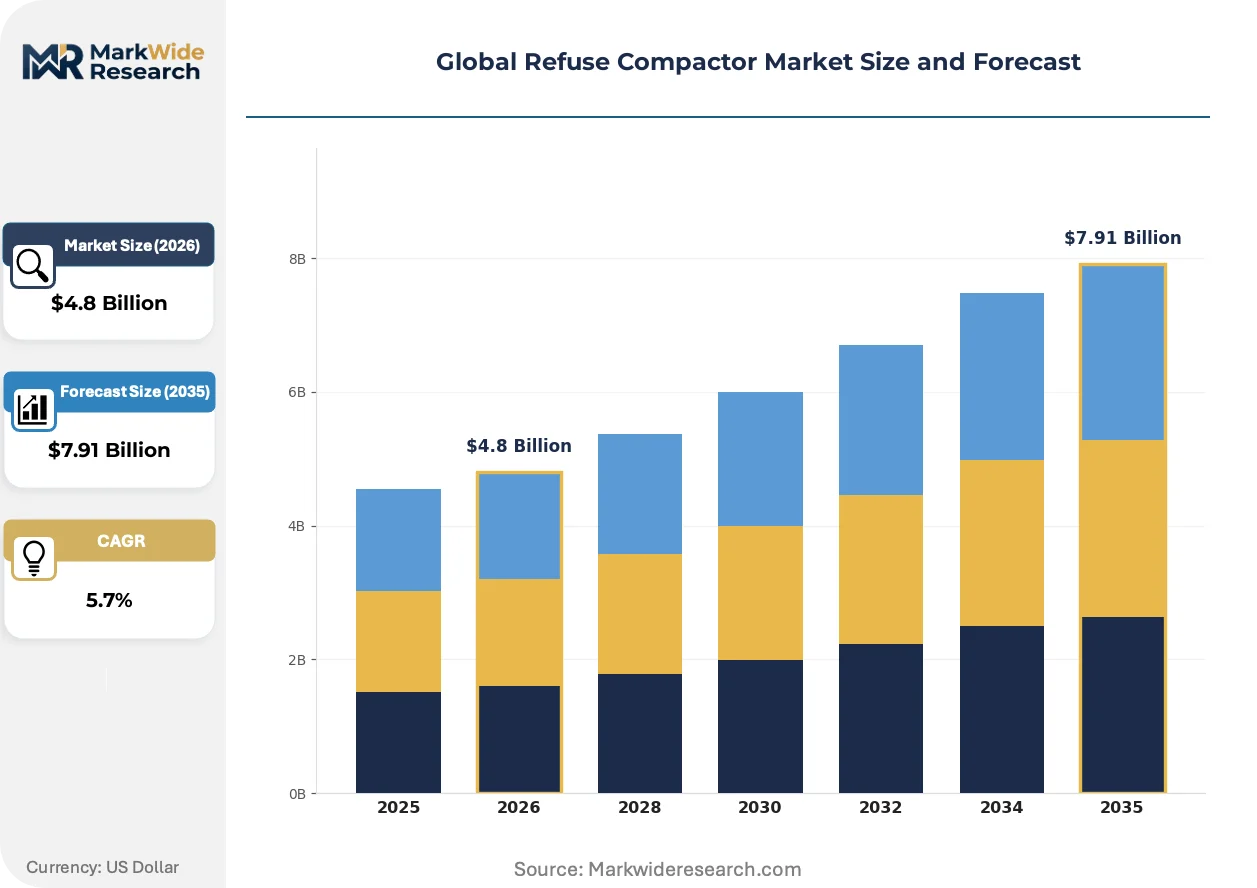
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stationary Compactors, Truck-Mounted Compactors, Self-Contained Compactors, Portable Compactors Technology: Hydraulic, Pneumatic, Electric, Mechanical, Solar-Powered Application: Municipal Waste Management, Construction Sites, Hospitality Sector, Healthcare Facilities, Manufacturing Plants End User: Sanitation Contractors, Facility Management Companies, Waste Collection Agencies, Recycling Centers |
| Companies Covered | GE Appliances, Husmann Umwelttechnik GmbH, PTR Baler & Compactor, Marathon Equipment Company, Capital Compactors Ltd, Wastequip LLC, GEESINKNORBA Group, Bergmann Group, PRESTO GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Refuse Compactor Market Shifts & Advancements
Electrification architectures are rewriting equipment specifications as buyers prioritize total cost of ownership metrics over upfront capital expenditure comparisons.
Electromechanical ram actuation is fragmenting the traditional hydraulic dominance in compaction systems. Municipal fleets in Scandinavian countries and Pacific Coast states are specifying electromechanical drives for reduced maintenance intervals and elimination of fluid leak risks. The technology is fragmenting aftermarket service revenue pools as sealed electromechanical units require less frequent intervention than pressurized hydraulic circuits.
EU F-Gas Regulation phase-down schedules are accelerating refrigerant transitions in auxiliary climate systems. OEMs must revalidate thermal management designs using lower-global-warming-potential chemistries, compressing development timelines for electric compactor platforms. Truck-mounted configurations sold into Germany, France, and Benelux markets face the most stringent compliance verification requirements.
Performance-based procurement is displacing traditional equipment ownership models in large metropolitan contracts. Waste management authorities in London, Singapore, and Toronto are piloting service agreements where vendors retain asset ownership and charge per-ton-compacted fees. This shift transfers utilization risk to manufacturers while locking in long-term revenue streams for fleet operators with telemetry-enabled asset monitoring capabilities.
Global Refuse Compactor Market Segmentation
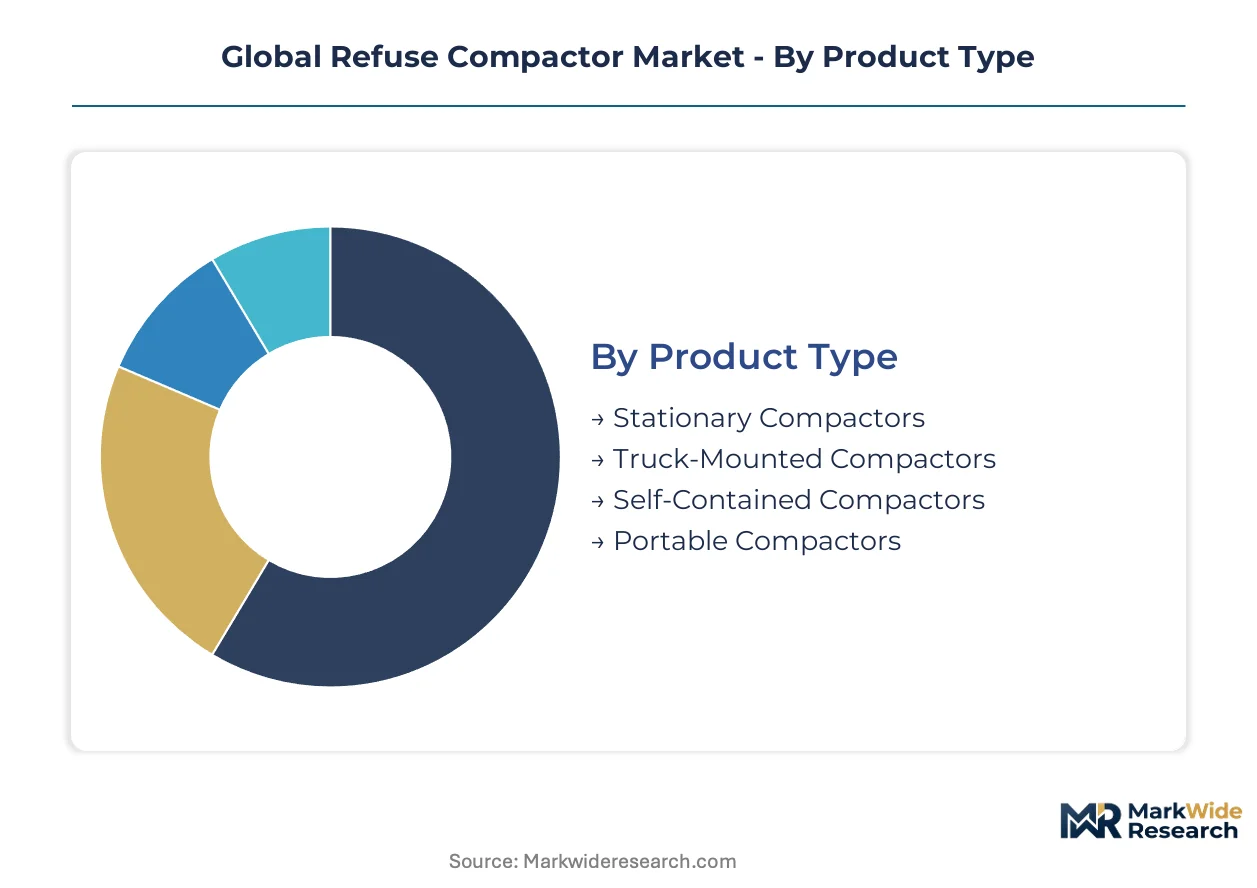
Segmentation in the refuse compactor market reveals how compaction technology adapts to divergent waste stream characteristics, regulatory environments, and capital deployment constraints across municipal and commercial buyers. Understanding these divisions exposes where substitution pressures from alternative collection technologies threaten incumbent product categories.
Product Type:
Stationary and portable compaction units face intensifying substitution pressure from on-site waste-to-energy preprocessing systems, while truck-mounted configurations defend their position through route-optimization synergies that alternative technologies cannot replicate.
- Stationary Compactors:Permanently installed steel-reinforced units with fixed concrete foundations process high-volume waste streams at manufacturing plants and distribution centers. Demand concentrates in Germany's Ruhr Valley industrial corridor where landfill diversion mandates under the EU Green Deal compel permanent on-site compaction infrastructure.
- Truck-Mounted Compactors:Hydraulic or electromechanical compression systems integrated into collection vehicle chassis reduce transport cycles by compacting waste during route operation. Municipal fleets in California, New York, and Texas are accelerating procurement to secure IRA tax credit windows before qualification thresholds shift.
- Self-Contained Compactors:Enclosed units with integrated liquid containment systems serve food service and healthcare applications where leachate control is mandatory.
- Portable Compactors:Skid-mounted or trailer-towed units provide temporary capacity for construction sites and seasonal events without permanent infrastructure commitment.
Truck-Mounted Compactors anchor the volume base while Electric drive variants within this category gain share at the steepest rate.
Technology:
Cost tier stratification separates mature hydraulic systems from premium electromechanical alternatives, with mid-market buyers caught between proven reliability and total cost of ownership advantages.
- Hydraulic:Pressurized fluid-driven ram assemblies dominate installed base through proven durability and repairable architecture. Demand persists among sanitation contractors in the US Upper Midwest where skilled technician networks remain intact.
- Electric:Battery-powered and grid-connected electromechanical actuation eliminates fluid leak risks and reduces maintenance intervals. Scandinavian municipal fleets and Pacific Coast states specify these systems to meet zero-emission mandates.
- Pneumatic:Compressed air systems serve specialized industrial applications where explosion-proof operation is required.
- Mechanical:Screw or ram drives powered by direct mechanical linkage offer simplicity for low-throughput installations.
- Solar-Powered:Photovoltaic-integrated units enable off-grid operation at remote industrial sites and island municipalities in Australia and Mediterranean jurisdictions.
Hydraulic systems retain the largest installed base while Solar-Powered configurations are expanding most quickly in off-grid niche applications.
Application:
Volume concentration in municipal procurement creates procurement pattern leverage that shapes R&D prioritization across OEM engineering teams.
- Municipal Waste Management:Curbside collection and transfer station operations represent the highest equipment throughput segment. Cities in Germany, France, and the Netherlands are modernizing fleets to meet EU Green Deal circular economy targets.
- Manufacturing Plants:Industrial waste streams with consistent composition and high daily volume justify permanent stationary installation. German automotive and chemical sectors deploy these systems to meet national recycling quotas.
- Construction Sites:Temporary waste aggregation for demolition debris and packaging materials requires mobile or portable solutions.
- Hospitality Sector:Food waste and packaging compaction for hotels and restaurants prioritizes odor control and space efficiency.
- Healthcare Facilities:Medical waste compaction with sterilization integration serves hospitals and clinical networks under strict EPA and state-level disposal regulations.
Municipal Waste Management commands procurement volume leadership while Manufacturing Plants demonstrate the steepest technology upgrade trajectory as Industry 4.0 integration accelerates.
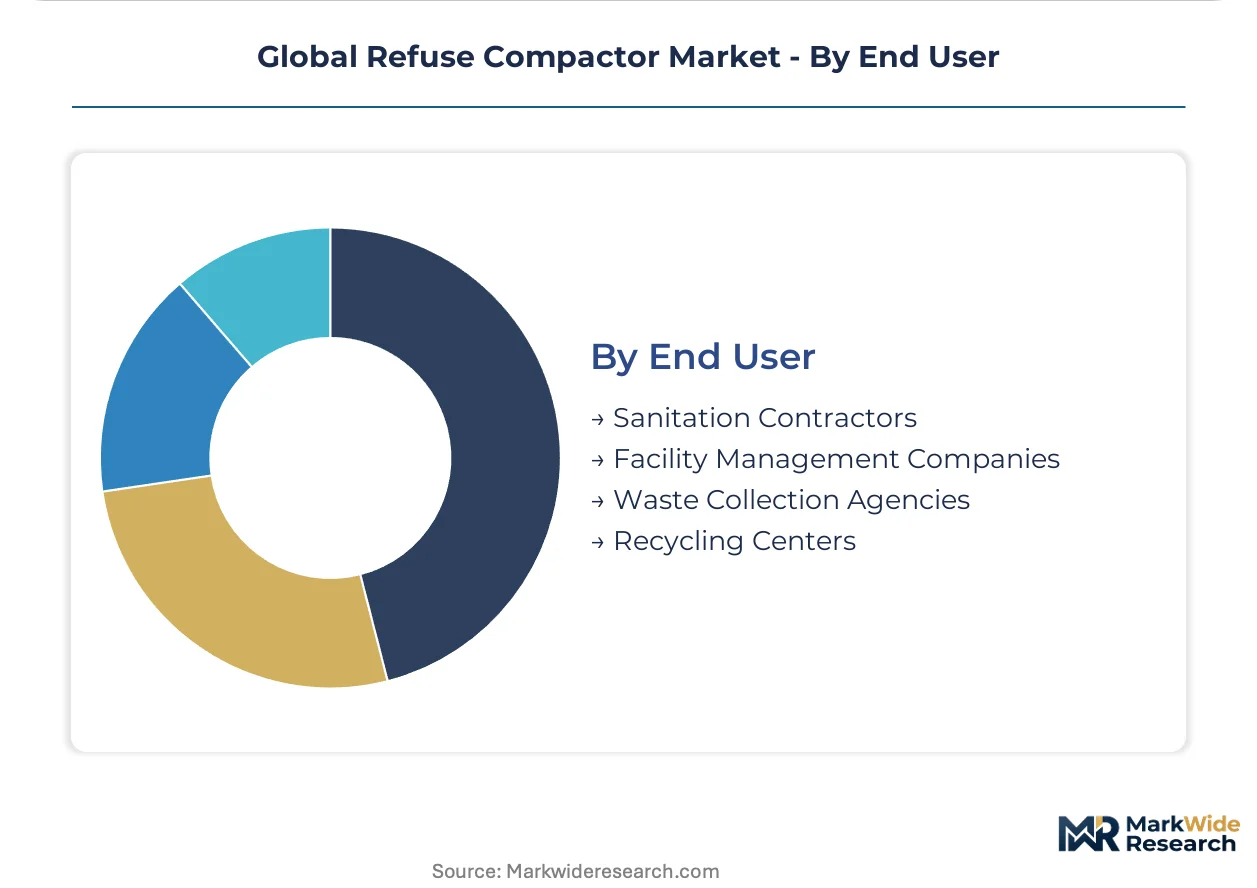
End User:
Customer type fragmentation across public and private waste handling entities creates divergent purchasing criteria that OEMs must address through differentiated sales channels.
- Sanitation Contractors:Private sector fleet operators serving municipal contracts under performance-based agreements prioritize equipment reliability and telemetry integration. These buyers in Texas and Florida are piloting pay-by-weight service models enabled by load sensor technology.
- Waste Collection Agencies:Public sector municipal departments operate the largest installed base and face the most stringent EPA Clean Truck compliance deadlines.
- Facility Management Companies:Commercial property service providers specify compactors for multi-tenant buildings and retail complexes.
- Recycling Centers:Material recovery facilities deploy compaction for baled commodity preparation and residue handling.
Waste Collection Agencies anchor public sector demand volume while Sanitation Contractors are climbing the fastest as performance-based procurement displaces traditional ownership models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EPA anchors the dominant geography through Clean Truck program enforcement that compels municipal fleet modernization across United States jurisdictions. Landfill diversion mandates and electrification incentives are reshaping procurement patterns in distinct national markets with varying regulatory stringency and industrial infrastructure maturity.
United States
Municipal sanitation departments in California, New York, and Texas are accelerating replacement timelines to secure IRA tax credit windows before qualification thresholds shift. The EPA's Clean Truck program enforces nitrogen oxide compliance standards that disqualify aging diesel hydraulic systems from federal procurement eligibility. Fabrication clusters in the Upper Midwest supply steel-reinforced chambers to domestic OEMs serving mid-market sanitation contractors.
Germany
The EU Green Deal's waste hierarchy enforcement and national recycling quotas are expanding truck-mounted compactor demand for source-separated organic streams. The F-Gas Regulation constrains refrigerant chemistries in auxiliary cooling systems, extending certification timelines for electric platforms sold into member states. Husmann Umwelttechnik GmbH and GEESINKNORBA Group anchor a dense supplier cluster in the Ruhr Valley metalworking district serving Central European circular economy targets.
China
Urban sanitation infrastructure investment under municipal beautification campaigns is creating first-time mechanized collection demand in tier-2 cities previously served by manual loading. The MIIT enforces emission standards for commercial vehicles that parallel EU regulatory frameworks. Yangtze River Delta manufacturing bases produce cost-optimized hydraulic systems for domestic fleet operators and export markets.
India
Smart Cities Mission funding and Swachh Bharat infrastructure allocations are mechanizing collection in tier-2 municipalities across Maharashtra and Gujarat. The central government's urban sanitation directives mandate compressed natural gas and electric vehicle transitions for municipal fleets. Karnataka and Tamil Nadu industrial corridors host emerging fabrication capacity for truck-mounted compaction systems.
Australia
Island municipalities and remote industrial sites are deploying solar-integrated stationary units to bypass grid dependency while qualifying for renewable energy certificates. The country's national environmental regulator enforces landfill diversion targets that accelerate compaction equipment deployment. Mediterranean-climate jurisdictions in Queensland and Western Australia represent concentrated off-grid installation demand.
Global Refuse Compactor Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in the refuse compactor market, with concentration most pronounced in German engineering clusters and North American fabrication corridors. The competitive terrain stratifies across hydraulic heritage players, electric-drive entrants, and diversified waste equipment conglomerates with captive distribution networks. Three archetypes dominate: vertically integrated fabricators controlling chamber production, technology licensors monetizing electromechanical actuation patents, and distributor-captive assemblers serving regional sanitation markets. Capacity expansion and strategic partnerships constitute the dominant competitive moves as OEMs navigate dual certification burdens for transatlantic deployment.
Within the German engineering tier, Husmann Umwelttechnik GmbH and GEESINKNORBA Group exemplify the integrated fabrication archetype through their Ruhr Valley concentration. Marathon Equipment Company occupies a position among North American fabricators with extensive distributor control across mid-market sanitation contractors. Wastequip LLC represents the distributor-captive model with broad coverage of United States procurement offices seeking IRA-compliant electrification platforms.
| Leading Market Players |
|---|
| GE Appliances |
| Husmann Umwelttechnik GmbH |
| PTR Baler & Compactor |
| Marathon Equipment Company |
| Capital Compactors Ltd |
| Wastequip LLC |
| GEESINKNORBA Group |
| Bergmann Group |
| PRESTO GmbH & Co. KG |
| Others |
Supply & Pricing Matrix
Capacity utilization rates at Upper Midwest foundries and Ruhr Valley metalworking districts determine price floors for steel-reinforced chambers, concentrating bargaining power among legacy OEMs with captive fabrication assets while squeezing mid-tier assemblers dependent on spot-market steel procurement. This scale asymmetry rewards backward integration into chamber production and punishes distributor-captive models exposed to raw material volatility.
Pricing Analysis
German-engineered truck-mounted systems command 15-25% premia over North American equivalents in cross-border tenders, reflecting CE marking compliance costs and extended warranty bundling. Three-tier pricing structure across premium electromechanical, standard hydraulic, and economy mechanical tiers segments buyers by fleet electrification mandate exposure. Cost compression in mid-market hydraulic lines is intensifying because of base oil additive price volatility and technician retraining subsidies. Sanitation contractors in Texas and Florida exhibit highest price sensitivity due to thin margins on municipal service contracts, while Scandinavian public fleets prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Strategic stockpiling of high-grade steel plate and hydraulic pump inventories dominates over just-in-time preferences, as foundry order backlogs extend lead times for chamber fabrication. Supply concentrates in the United States Upper Midwest, Germany's Ruhr Valley, and China's Yangtze River Delta, with each hub serving distinct certification regimes. Component sourcing draws from Swedish specialty steel mills, Japanese precision pump manufacturers, and South Korean battery cell suppliers for electric platforms. Single-source vulnerability in hydraulic valve production creates bottlenecks when semiconductor content in proportional control systems faces allocation constraints. Distribution runs through OEM-direct municipal procurement channels in developed markets and distributor-captive networks in fragmented commercial segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The refuse compactor market is recovering from cyclical capital expenditure compression in municipal budgets, with fleet electrification mandates under the EPA Clean Truck program and EU Green Deal providing sustained replacement demand across transatlantic procurement offices.
For Market Incumbents: Compound engineering credibility in German and North American fabrication clusters through certification pre-approval for F-Gas Regulation refrigerant transitions and EPA nitrogen oxide compliance, while absorbing electromechanical actuator R&D costs to defend against Chinese cost-optimized entrants targeting mid-market hydraulic replacement cycles. For New Entrants and Emerging Players: Differentiate on solar-integrated stationary architectures for Australian island municipalities and Mediterranean off-grid industrial sites, where renewable energy certificate qualification creates pricing power unavailable in saturated municipal fleet segments; target tier-2 Indian cities under Smart Cities Mission funding as first-time mechanized collection demand emerges from manual loading baselines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among telemetry-enabled fleet operators piloting pay-by-weight service models in London, Singapore, and Toronto; long-term viability over the next decade hinges on electromechanical actuator patent portfolios and software-defined compaction load sensing, with acquisition priority on mid-tier manufacturers possessing IRA tax credit pre-qualification and distributor control in California or Texas procurement corridors; watch for inflection when battery-electric refuse vehicle penetration in municipal fleets crosses threshold density to trigger aftermarket service revenue collapse in hydraulic maintenance networks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel-Reinforced Chamber Fabrication | Captive production at Upper Midwest foundries insulates Marathon Equipment from raw material volatility and Ruhr Valley supply shocks. |
| Electromechanical Actuator Patent Licensing | Technology monetization enables Husmann Umwelttechnik to extract royalties from Scandinavian municipal fleets specifying zero-fluid-leak systems. |
| Telemetry-Enabled Pay-by-Weight Service Model | Load sensor integration with route optimization software shifts Wastequip revenue from equipment sale to recurring performance fees in Texas sanitation contracts. |
| Dual Certification Pre-Approval for Transatlantic Deployment | Parallel EPA Clean Truck and EU F-Gas Regulation compliance reduces homologation costs for OEMs serving both California and German procurement offices. |
| Solar-Integrated Stationary Unit Development | Photovoltaic compaction systems qualify for Australian renewable energy certificates while bypassing grid dependency at remote Queensland industrial sites. |
Research Methodology
The analysis maps stationary, truck-mounted, self-contained, and portable compaction systems, each validated through maintenance directors at manufacturing plants, municipal fleet procurement officers, aftermarket service heads at distributor networks, and hydraulic technician training program administrators. Primary interview findings were cross-referenced against EPA Clean Truck program filings, EU F-Gas Regulation implementation guidance, IRA tax credit qualification databases, and customs records for steel plate and hydraulic component trade flows. Bottom-up equipment shipment data triangulated against top-down municipal capital expenditure budgets to reconcile volume estimates.
Consistency checks against external benchmarks validated projection outputs against IEA waste management infrastructure investment tracking, national recycling quota compliance reports from Germany and the Netherlands, and vehicle registration databases for refuse collection fleet composition. Segmentation modeling incorporated product type, technology architecture, application sector, and end-user procurement pattern dimensions across the projection horizon. CAGRs were derived from equipment replacement cycle analysis, electrification mandate phase-in schedules, and circular economy target enforcement trajectories, with sensitivity testing around battery cost curves and hydraulic fluid price volatility.
The analysis sits within stated boundaries; outcomes outside sustained municipal budget recovery, stable steel and base oil input costs, or uninterrupted IRA tax credit authorization would require recalibration. Forecasts reflect assumptions regarding technician training pipeline output, electromechanical actuator reliability maturation, and dual certification burden persistence. Revision becomes warranted when battery-electric refuse vehicle market penetration or F-Gas Regulation refrigerant phase-down timelines cross threshold acceleration points.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Wire Pulling and Tensioning Market
Material Handling Equipment
Gantry Crane Market
Material Handling Equipment
High-Pressure Die Casting Market
Material Handling Equipment
Conveyor Belt Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market
Material Handling Equipment
Hose Pump Market
Material Handling Equipment
Reach Stacker Market
Material Handling Equipment
Freight Elevators Market
Material Handling Equipment
Pug Mill Mixers Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Rotary Breaker Market
Material Handling Equipment
Silo Bin Activators Market
Material Handling Equipment
Industrial Counterweights Market
Material Handling Equipment
Warehouse Freight Elevators Market
Material Handling Equipment
Global Loaders Market