
 Canada Forklift Market | 2026-2036
Canada Forklift Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Forklift Market Analysis
Certified forklift technician availability is bifurcating the Canada forklift market into service-capable and service-constrained regions. Toyota Industries Corporation leverages its established dealer network to sustain parts availability across Prairie provinces. Hyster-Yale Materials Handling Inc anchors its position through Crown Holdings Inc competes on electric warehouse specialization in Ontario's distribution hubs. KION GROUP AG operates automated guided vehicle integrations that differentiate its offering for large-scale manufacturing clients.
A forklift is a powered industrial truck featuring dual front forks that hydraulically lift loads typically between one and fifty tons, with mast heights reaching twelve meters for high-density storage applications. Internal combustion forklifts dominate outdoor construction and lumber yard operations where refueling infrastructure and extreme cold tolerance prove essential. Electric forklifts capture expanding share in retail and warehousing end-user segments as lithium-ion battery energy density improves and charging cycles compress. Automated forklifts represent the fastest-growing technology category, though manual forklifts still occupy the largest installed base across Canadian manufacturing facilities.
Health Canada sets national occupational safety standards for powered industrial equipment operation through provincially administered workplace regulations. Transport Canada enforces vehicle weight and emissions compliance for interprovincial fleet movements, while provincial environmental ministries in Quebec and British Columbia advance zero-emission material handling mandates that reshape procurement specifications. Stakeholders must monitor hydrogen fuel cell infrastructure investments and telematics data interoperability standards as these elements determine fleet modernization timelines and total cost of ownership calculations.
Market Dynamics
Provincial carbon reduction mandates are compressing diesel forklift replacement timelines across Ontario and British Columbia warehousing corridors, forcing capital allocation toward electric powertrains before infrastructure maturity.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics operators in the Greater Toronto Area are expanding automated storage and retrieval system integrations that require narrow-aisle electric forklift fleets.
- Health Canada PMRA safety directives:Updated powered industrial equipment operator certification standards are mandating fleet telemetry installations that accelerate connected forklift adoption.
- Lithium-ion energy density improvements:Battery chemistry advances are eliminating the multi-shift charging downtime that previously constrained electric forklift deployment in 24-hour distribution centers.
Market Restraints
- Certified technician scarcity:Prairie provinces face acute shortages of qualified service personnel for high-voltage electric forklift maintenance, extending equipment downtime.
- Hydrogen infrastructure gaps:Fuel cell forklift pilots in British Columbia lack provincial refueling station networks comparable to battery charging depot density.
- Extreme cold performance limits:Lithium-ion capacity degradation below minus twenty degrees Celsius preserves internal combustion engine dominance in Alberta oil sands logistics.
Strategic Opportunities
- Automated guided vehicle convergence:Integration of vision-guided navigation with traditional forklift chassis is creating hybrid autonomous units for Quebec manufacturing assembly lines.
- Telematics data monetization:Fleet utilization analytics from Ontario warehousing operators are enabling outcome-based equipment leasing models.
- Atlantic Canada port modernization:Halifax and Saint John container terminal expansions are generating demand for heavy-capacity reach stackers with Tier 4 emissions compliance.
Industry Challenges
- Cross-provincial certification reciprocity:Ontario and Quebec maintain non-harmonized forklift operator licensing requirements that fragment national fleet mobility.
- Legacy warehouse retrofit costs:Narrow-aisle electric forklift deployment requires racking reconfiguration and floor loading reinforcement in pre-2000 distribution facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Forklift Market |
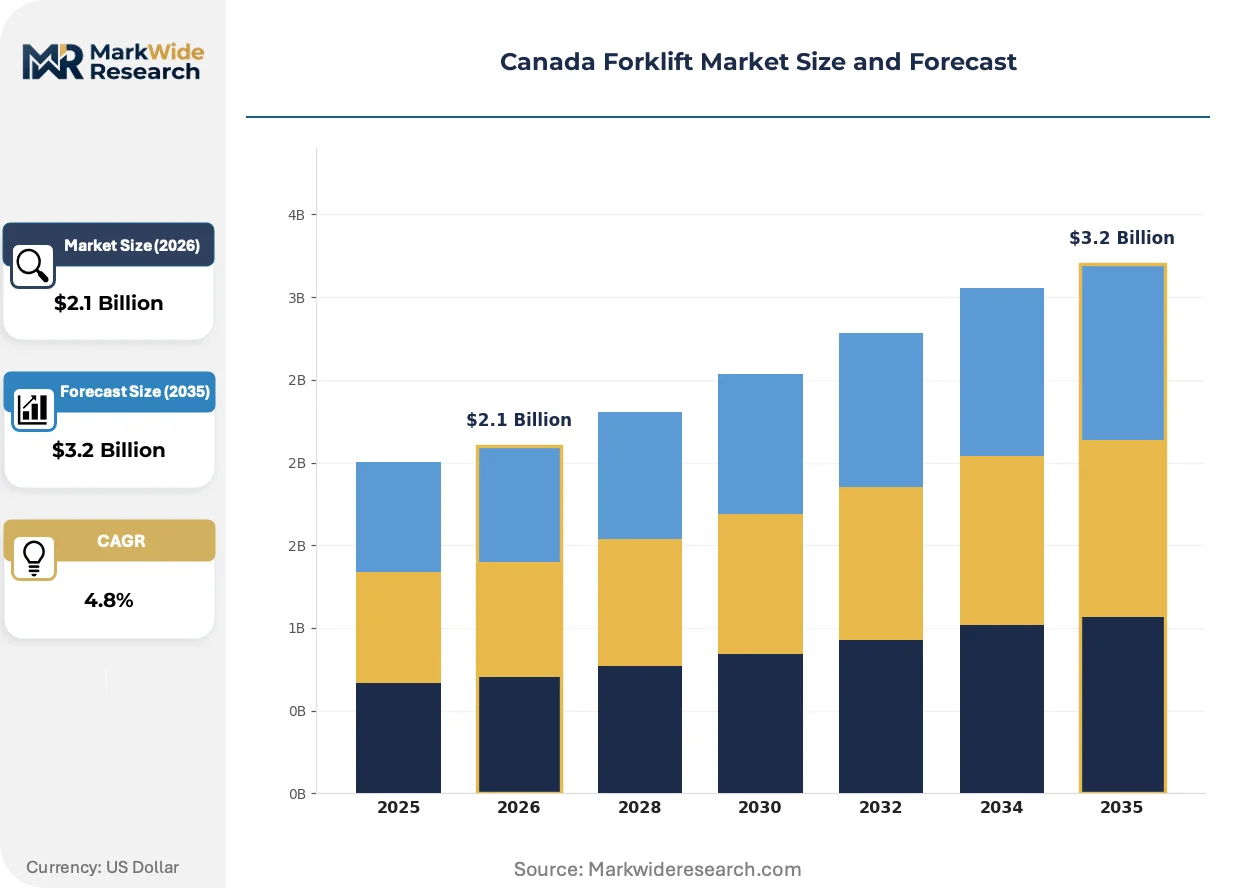
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Forklifts, Internal Combustion Forklifts, Warehouse Forklifts, Rough Terrain Forklifts End User: Retail, Manufacturing, Construction, Warehousing Capacity: Below 3 Tons, 3-5 Tons, 5-10 Tons, Above 10 Tons Technology: Automated Forklifts, Telematics-Enabled Forklifts, Hydrogen Fuel Cell Forklifts, Manual Forklifts |
| Companies Covered | Anhui Forklift Group, Hyster-Yale Materials Handling Inc, Toyota Industries Corporation, Liftking, Vallée, KION GROUP AG, Crown Holdings Inc, Doosan Heavy Industries & Construction, Jungheinrich AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Forklift Market Emerging Trajectories
Telematics integration is compressing equipment procurement from capital expenditure to operational service models, while powertrain electrification and automation converge to reshape warehouse labor economics.
Sensor-embedded lithium-ion battery management systems are miniaturizing thermal monitoring and cell-balancing hardware into forklift powertrain modules. Ontario cold-storage operators are adopting these units to replace propane fleets without facility ventilation retrofitting. The technology is miniaturizing maintenance intervals and enabling predictive component replacement that reduces unplanned downtime in high-velocity distribution environments.
British Columbia's zero-emission material handling mandate is prohibiting new internal combustion forklift purchases in provincially owned facilities after 2027. This regulatory compression is forcing Crown corporations and municipal logistics operators to accelerate electric fleet transitions ahead of private sector economics. Food processing and beverage distribution verticals in the Lower Mainland are responding with leased equipment arrangements that transfer technology obsolescence risk to OEM financing arms.
Consolidated procurement through national third-party logistics providers is displacing fragmented dealer relationships among mid-size retailers. Amazon fulfillment network expansion in Ontario and Alberta is concentrating forklift purchasing power among fewer buyers with standardized specification requirements. This concentration is most visible in automated guided vehicle tenders where volume commitments extract preferential service-level agreements from KION GROUP AG and Toyota Industries Corporation dealer networks.
Canada Forklift Market Segmentation
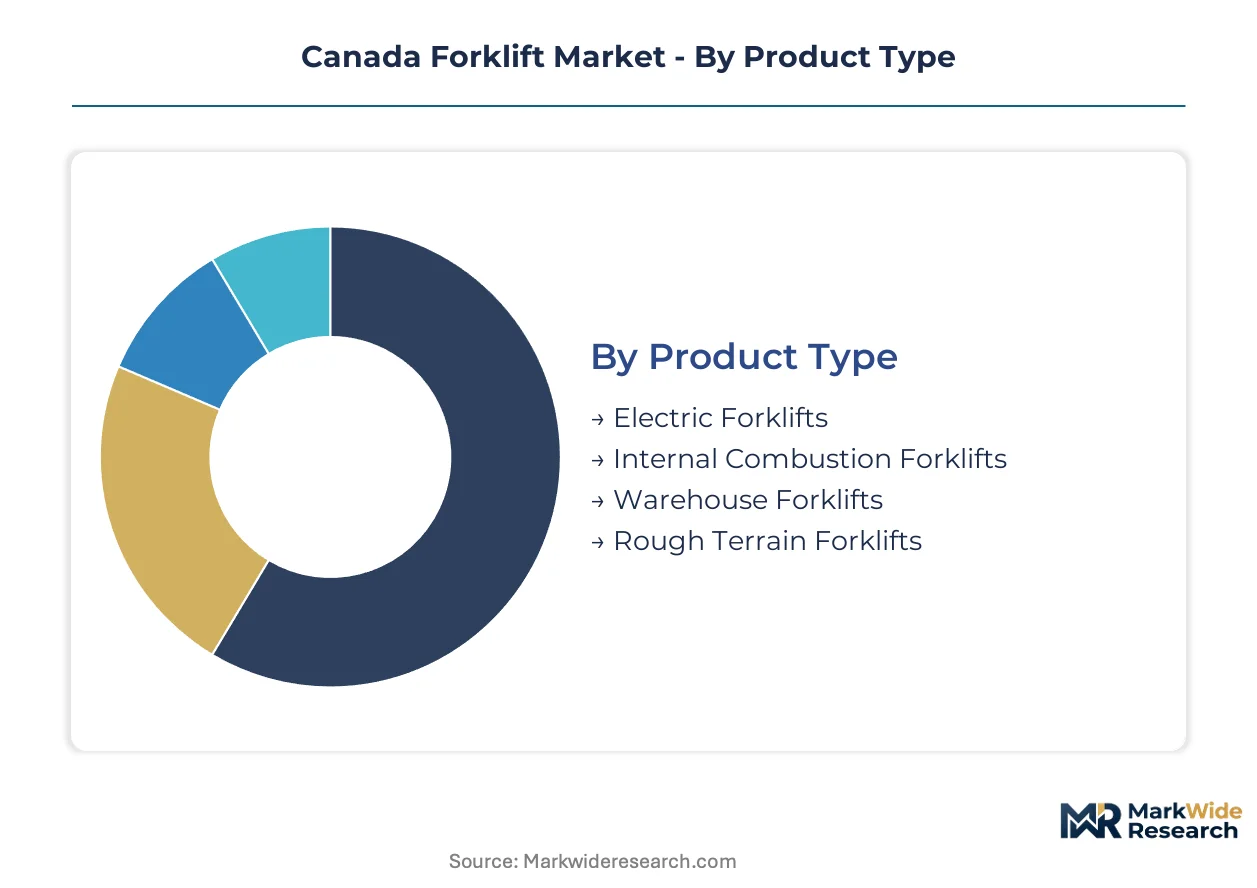
Canada's forklift market segments reflect divergent pressures from electrification mandates and automation investments. Procurement patterns vary sharply across provincial regulatory environments and end-use operational requirements.
Product Type:
Internal combustion units face substitution pressure from zero-emission mandates in British Columbia and Quebec, while electric alternatives contend with cold-climate performance limitations.
- Electric Forklifts:Lithium-ion battery systems power counterbalance and narrow-aisle configurations for indoor warehousing. Demand concentrates in Ontario's Greater Toronto Area logistics corridor where Health Canada indoor air quality standards restrict propane fleet expansion.
- Internal Combustion Forklifts:Diesel and propane engines deliver torque density for outdoor yards and unheated facilities. Alberta oil sands logistics and Prairie province lumber operations preserve demand despite carbon reduction timelines.
- Warehouse Forklifts:Reach trucks and order pickers optimize vertical storage density in distribution centers.
- Rough Terrain Forklifts:Pneumatic tires and elevated ground clearance serve construction sites and agricultural supply yards.
Internal combustion forklifts retain volume leadership; electric forklifts hold the steepest expansion curve.
End User:
Capital deployment intensity varies across customer types, with third-party logistics operators consolidating purchasing power faster than fragmented retail chains.
- Retail:Big-box and grocery chains deploy electric counterbalance fleets for store-level receiving and stockroom operations. British Columbia's provincial zero-emission procurement rules accelerate fleet turnover in Vancouver and Lower Mainland distribution networks.
- Manufacturing:Assembly line feed and work-in-process handling require precise load positioning. Quebec aerospace and automotive plants drive automated guided vehicle integration with traditional forklift chassis.
- Construction:Project-based equipment utilization favors rental models over ownership.
- Warehousing:E-commerce fulfillment density demands 24-hour operational capability.
Warehousing commands the highest unit velocity; manufacturing exhibits the strongest automation attachment rates.
Capacity:
Load rating selection tracks facility infrastructure constraints and freight handling economics across Canadian provinces.
- Below 3 Tons:Compact electric units navigate retail backrooms and light manufacturing cells. Ontario food processing plants specify these for ingredient staging and packaging line supply.
- 3-5 Tons:Standard counterbalance configurations dominate general warehousing and cross-dock operations. Alberta distribution centers favor this range for palletized freight handling in temperature-controlled environments.
- 5-10 Tons:Heavy-duty electric and diesel variants serve manufacturing raw material intake.
- Above 10 Tons:Specialized container handlers and reach stackers operate at Atlantic Canada port terminals.
The 3-5 ton range anchors installed base volumes; below 3 ton units are gaining share fastest in urban logistics.
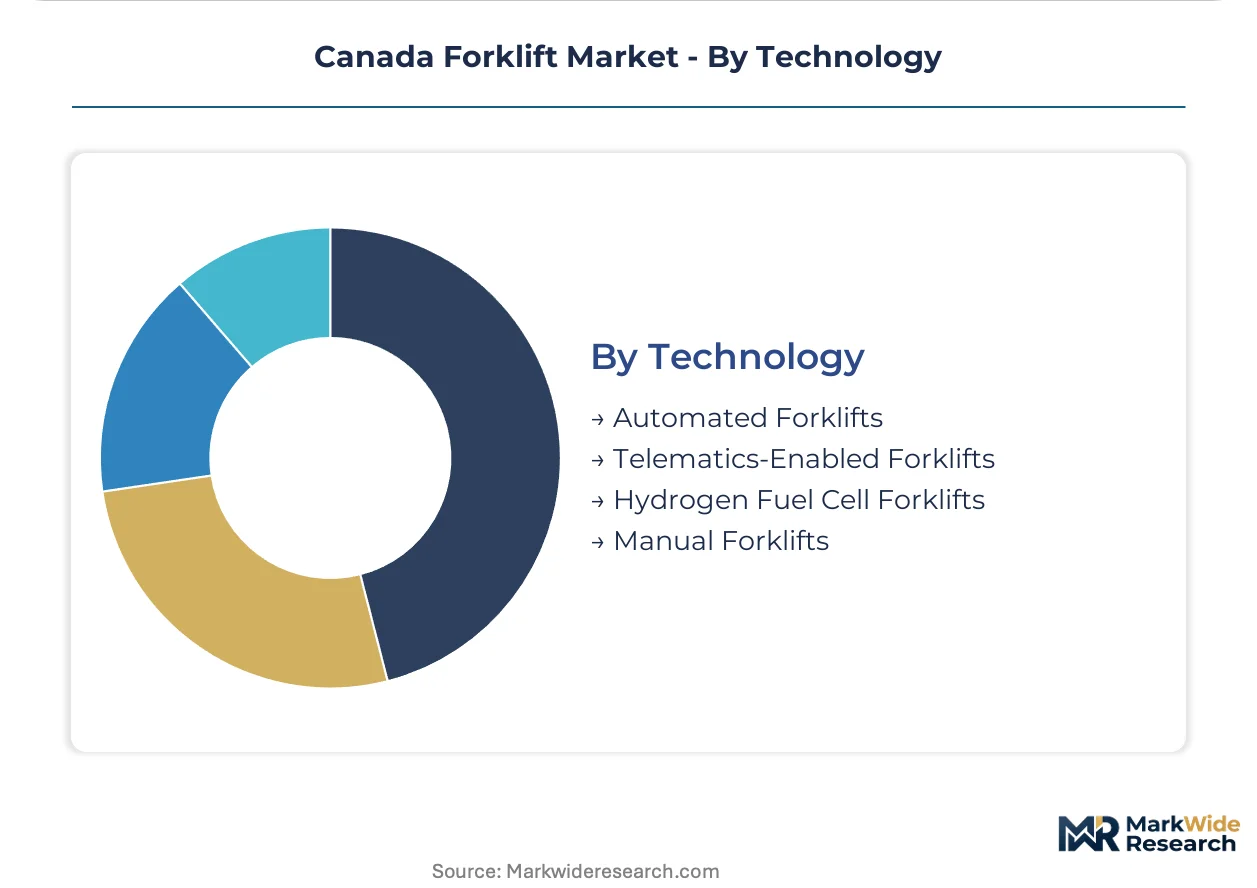
Technology:
Connectivity and autonomy investments separate capital-intensive fleet operators from price-sensitive equipment buyers.
- Automated Forklifts:Vision-guided and laser-navigation systems execute put-away and retrieval without operator intervention. Quebec manufacturing assembly lines integrate these for just-in-sequence material delivery.
- Telematics-Enabled Forklifts:IoT sensors transmit utilization, impact, and maintenance data to fleet management platforms. Health Canada PMRA certification requirements mandate operator monitoring systems that accelerate adoption.
- Hydrogen Fuel Cell Forklifts:Rapid refueling addresses multi-shift operations where battery charging infrastructure proves insufficient.
- Manual Forklifts:Hand-pallet jacks and walkie stackers serve low-throughput applications.
Manual forklifts retain the broadest installed base; automated forklifts are climbing the fastest among capital-intensive operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canadian provinces deploy forklift technologies at markedly different intensities. Ontario and British Columbia lead electric fleet penetration, while Alberta and Prairie provinces retain combustion-engine dominance for cold-climate durability.
Ontario
E-commerce fulfillment density drives narrow-aisle electric forklift demand across the Greater Toronto Area logistics corridor. Health Canada PMRA indoor air quality standards restrict propane fleet expansion in food processing plants. Toronto and Mississauga distribution centers are consolidating procurement through third-party logistics operators with standardized telematics requirements.
Quebec
Aerospace and automotive manufacturing plants drive automated guided vehicle integration with traditional forklift chassis for just-in-sequence material delivery. Provincial zero-emission procurement mandates accelerate electric fleet transitions in Crown corporation facilities. Montreal and Quebec City assembly lines are adopting vision-guided navigation systems for put-away and retrieval operations.
British Columbia
Provincial zero-emission material handling mandates prohibit new internal combustion forklift purchases in government facilities after 2027. Food processing and beverage distribution operators in the Lower Mainland are shifting to leased electric equipment arrangements. Vancouver and Surrey distribution networks are retrofitting charging infrastructure ahead of regulatory deadlines.
Alberta
Oil sands logistics and unheated outdoor yards preserve diesel forklift demand despite carbon reduction timelines. Extreme cold performance below minus twenty degrees Celsius limits lithium-ion battery viability in northern extraction operations. Edmonton and Calgary distribution centers favor 3-5 ton counterbalance configurations for temperature-controlled palletized freight handling.
Atlantic Canada
Halifax and Saint John container terminal expansions generate demand for heavy-capacity reach stackers with Tier 4 emissions compliance. Port modernization programs are upgrading legacy diesel fleets for intermodal cargo handling. Regional warehousing operators are piloting telematics-enabled equipment to meet Health Canada certification standards for operator monitoring.
Canada Forklift Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Canada forklift market. Toyota Industries Corporation and KION GROUP AG anchor the upper tier through established dealer networks and automated vehicle integration capabilities. Crown Holdings Inc and Hyster-Yale Materials Handling Inc occupy differentiated positions in electric warehouse specialization and outdoor durability segments respectively. Competitive dynamics center on fleet telemetry standardization and provincial service coverage expansion rather than pure price competition.
Within the integrated multinational tier, Toyota Industries Corporation and KION GROUP AG represent divergent strategic approaches to the Canadian market. Toyota leverages its Prairie province dealer infrastructure to sustain parts availability and technician training networks. KION occupies a position in automated guided vehicle convergence for Quebec manufacturing clients seeking hybrid autonomous solutions. Among regional specialists, Vallée and Liftking exemplify the mid-tier fabricators serving resource extraction and construction verticals with rough-terrain configurations. Jungheinrich AG and Crown Holdings Inc sit within the premium electric warehouse equipment segment, where narrow-aisle specialization commands pricing premiums in Ontario distribution hubs. Anhui Forklift Group represents the value-oriented import tier, competing on initial acquisition cost for price-sensitive Prairie province operators.
| Leading Market Players |
|---|
| Anhui Forklift Group |
| Hyster-Yale Materials Handling Inc |
| Toyota Industries Corporation |
| Liftking |
| Vallée |
| KION GROUP AG |
| Crown Holdings Inc |
| Doosan Heavy Industries & Construction |
| Jungheinrich AG |
| Others |
Supply Flow & Price Mechanics
Dealer network density in Ontario and Quebec generates procurement scale advantages that compress price floors for electric forklift configurations while elevating service-bundled premiums in Prairie provinces. Capital allocation toward lithium-ion battery supply contracts shapes both manufacturer margin structures and end-user total cost of ownership calculations across provincial fleet operators.
Pricing Analysis
Long-term fleet lease contracts dominate Ontario third-party logistics procurement, with equipment-as-a-service arrangements transferring technology obsolescence risk to OEM financing arms. Price differentiation rests on telematics integration depth and Health Canada PMRA certification tier, with premium configurations commanding service-level guarantees. Cost compression in standard electric counterbalance segments is intensifying because Crown corporation procurement consolidation extracts volume discounts. Price-sensitive Prairie province independent operators favor economy-tier internal combustion units, while least-sensitive Quebec aerospace manufacturers prioritize automated guided vehicle integration regardless of acquisition premium.
Supply Chain Analysis
Inventory lead times for lithium-ion battery modules stretch 12-16 weeks, tethering Canadian forklift assembly to South Korean and Chinese cell manufacturing schedules. Supply concentration in Japan, Germany, and the United States anchors component sourcing for hydraulic systems and drive motors. Raw material dependencies on copper windings, rare-earth magnets, and high-grade steel expose procurement to commodity price volatility. Distribution runs through manufacturer-authorized dealer networks rather than direct sales, with Toyota Industries Corporation and KION GROUP AG maintaining captive parts depots in Toronto and Montreal.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified high-voltage technician availability constrains electric fleet expansion velocity, creating capability scarcity that fragments service quality between Ontario's trained workforce and Prairie provinces' apprenticeship gaps.
For Market Incumbents: Consolidate Prairie province service coverage through acquisition of independent dealer networks before lithium-ion fleet penetration accelerates maintenance demand. Deepen backward integration into battery management system software to capture recurring revenue streams as hardware margins compress. Anchor position in Quebec automated guided vehicle convergence through exclusive assembly line integration partnerships with aerospace manufacturers. For New Entrants and Emerging Players: Aftermarket telematics retrofit services represent underserved white-space where legacy fleet operators lack connectivity infrastructure. Target Atlantic Canada port modernization contracts for heavy-capacity reach stackers, where Tier 4 compliance requirements displace aging equipment. Pursue outcome-based leasing arrangements that transfer residual value risk from municipal operators to financing entities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electric powertrain specialists with established Health Canada certification pathways over combustion-engine legacy exposure. Long-term viability rests on hydrogen fuel cell pilot scalability and automated vehicle software stack ownership. Watch British Columbia refueling infrastructure deployment as inflection indicator for fuel cell forklift commercialization timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Technician Training Network Expansion | Addresses Prairie province service scarcity that extends equipment downtime for electric fleets. |
| Lithium-Ion Battery Supply Agreement | Secures cell allocation from South Korean manufacturers amid warehousing electrification mandates. |
| Automated Guided Vehicle Platform Integration | Captures Quebec manufacturing demand for just-in-sequence material delivery systems. |
| Telematics Data Monetization Partnership | Enables outcome-based leasing models with Ontario third-party logistics operators. |
| Hydrogen Refueling Infrastructure Joint Venture | Supports British Columbia fuel cell forklift pilots lacking provincial station networks. |
Methodological Framework
The analysis maps electric powertrain adoption, automated vehicle integration, and aftermarket service networks, each validated through maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads. Primary fieldwork combined structured interviews with fleet operators across Ontario, Quebec, and British Columbia with secondary validation against Transport Canada emissions filings, provincial procurement registries, and Health Canada PMRA certification databases. Bottom-up unit deployment estimates triangulated against top-down provincial logistics employment and warehouse square footage expansion.
Consistency checks validated volume and value outputs against third-party logistics capital expenditure disclosures and Crown corporation fleet procurement announcements. The analytical framework modeled product type, end-use vertical, capacity tier, and technology sophistication across the projection horizon. CAGRs derived from provincial regulatory mandate timelines and e-commerce fulfillment density trajectories incorporated lithium-ion energy density improvement curves and hydrogen infrastructure investment signals as industry-specific forecast inputs.
Forecasts assume regulatory continuity in British Columbia zero-emission procurement mandates and Health Canada PMRA certification standards; material policy shifts would require re-modeling fleet replacement timelines and powertrain mix assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Trommel Screen Market
Material Handling Equipment
Hot-Rolling Mill and Cold-Rolling Mill Market
Material Handling Equipment
Sorting Machines Market
Material Handling Equipment
Global Cargo Handling Equipment Market
Material Handling Equipment
Chain-Driven Roller Conveyors Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Drive-In Pallet Racking Market
Material Handling Equipment
Industrial Piggable Wye Fitting Market
Material Handling Equipment
Eye and Eye Turnbuckle Market
Material Handling Equipment
Lever Hoist Market
Material Handling Equipment
Push-Back Racking System Market
Material Handling Equipment
Hook Lifts and Skip Loaders Market
Material Handling Equipment
Global Metal Shredder Machine Market
Material Handling Equipment
Hydraulics Components Market
Material Handling Equipment
Rotating Fork Clamp Market
Material Handling Equipment
Forklift Truck Market