
 Weather Radar Market | 2026-2036
Weather Radar Market Size, Share, and Industry Trends Forecast 2026-2036
Weather Radar Market Intelligence
The gap between solid-state Doppler systems and legacy magnetron pulse radars is rebalancing procurement budgets across aviation and meteorology agencies. Collins Aerospace leverages its integrated avionics portfolio to anchor airborne weather radar contracts with major carriers. Furuno Electric Co., Ltd. competes aggressively in maritime deployment with specialized X-band systems for coastal surveillance. Vaisala Oyj dominates ground-based meteorological installations through its WSR-series dual-polarization platforms.
Weather radar comprises active remote sensing equipment that transmits microwave pulses—typically 3–10 cm wavelength in S, C, or X-band—and analyzes backscattered signals to detect precipitation intensity, storm motion, and atmospheric turbulence. Solid-state transmitters now achieve peak powers exceeding 250 kW with improved reliability over vacuum-tube magnetrons, enabling longer maintenance intervals critical for unattended meteorological stations. Doppler radar retains the largest installed base but phased array architectures are capturing defense and aviation upgrade cycles due to electronic beam steering eliminating mechanical antenna inertia. Ground-based deployment generates the steadiest replacement revenue while airborne segments concentrate margin in integrated cockpit weather suites.
The FAA mandates terminal Doppler weather radar coverage at commercial airports under 14 CFR Part 139 safety regulations, directly shaping procurement timelines for pulse and Doppler replacements. EASA's CS-25 airworthiness requirements govern airborne weather radar certification thresholds for European-registered aircraft, while China's CAAC enforces GB standards for civil aviation meteorological equipment. Stakeholders must monitor divergence between national spectrum allocation policies and emerging C-band 5G interference mitigation protocols.
Market Dynamics
Solid-state transmitter architectures are compressing procurement cycles across aviation and meteorological agencies by eliminating magnetron vacuum-tube maintenance burdens and extending unattended station operational lifespans.
Growth Catalysts
- 14 CFR Part 139 Mandates:The FAA requires terminal Doppler weather radar coverage at commercial airports, forcing systematic replacement of aging pulse radar infrastructure and anchoring steady procurement volumes.
- Dual-Polarization Upgrades:Meteorological agencies in Germany, France, and the United Kingdom are retrofitting WSR-series installations to improve precipitation classification accuracy and severe weather warning lead times.
- Civil Aviation Modernization:Airport authorities in China, India, and Japan are expanding terminal Doppler radar networks to reduce weather-related flight disruptions as passenger volumes recover.
Market Restraints
- GaN Semiconductor Supply Concentration:Gallium nitride substrates for solid-state transmitters concentrate among limited foundry capacity in Taiwan and South Korea, creating input cost volatility and delivery uncertainty.
- Spectrum Interference Friction:C-band 5G deployment in the United States and Europe is forcing meteorological agencies to implement costly interference mitigation protocols and filter upgrades.
- Phased Array Cost Barriers:Electronic beam-steering architectures remain structurally expensive versus mechanical antenna systems, limiting adoption outside defense and premium aviation segments.
Strategic Opportunities
- Maritime X-Band Expansion:Coastal surveillance authorities in Indonesia, Vietnam, and the Philippines are procuring specialized compact radars for port security and severe weather monitoring.
- Integrated Cockpit Convergence:Avionics suites combining weather radar with terrain awareness and traffic collision avoidance are capturing retrofit contracts among regional carriers.
- Unattended Station Automation:Solid-state reliability enables remote meteorological installations in the Australian Outback, Canadian Arctic, and Siberian corridors without on-site technical staffing.
Industry Challenges
- Doppler Signal Processing Expertise Gap:Universities in Brazil, South Africa, and Mexico produce insufficient RF engineering graduates to staff meteorological agency upgrade programs.
- Legacy System Integration Complexity:Phased array retrofits must interface with existing FAA and EASA air traffic management protocols, extending certification timelines and testing costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weather Radar Market |
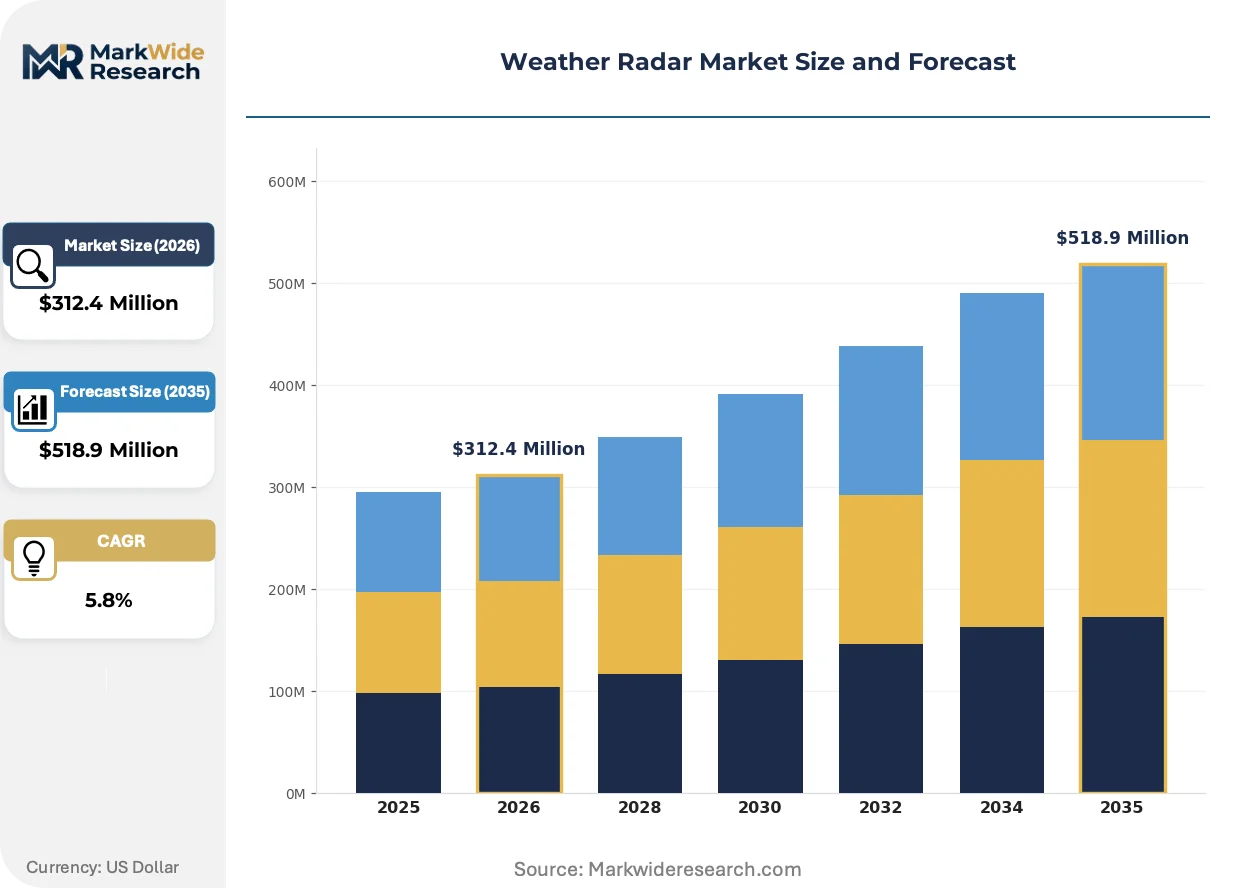
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $518.9 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Doppler Radar, Pulse Radar, Phased Array Radar, Scanning Radar Technology: Solid-State Technology, Magnetron Technology, Frequency Modulated, Digital Signal Processing End User: Aviation, Maritime, Meteorology, Defense Deployment: Ground-Based, Airborne, Spaceborne, Mobile |
| Companies Covered | Collins Aerospace, Honeywell International Inc., Leonardo Germany GmbH, Vaisala Oyj, Furuno Electric Co., Ltd., EWR Radar Systems Inc., Enterprise Electronics Corporation, Garmin International Ltd., Beijing Minstar Radar Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weather Radar Market Strategic Shifts & Innovations
Active electronically scanned arrays are compressing mechanical radar replacement cycles while software-defined signal processing is unbundling hardware-software procurement bundles across defense and civil applications.
Phased array weather radar is modularizing ground-based meteorological infrastructure by enabling rapid beam repositioning without mechanical antenna inertia. National meteorological services in Norway, Sweden, and Finland are adopting these systems to track fast-evolving convective storms across Nordic latitudes. The technology is modularizing supplier ecosystems by separating antenna hardware from proprietary signal processing software, allowing agencies to mix component vendors.
The EU AI Act is classifying weather radar data fusion algorithms as high-risk AI systems requiring conformity assessments before operational deployment. European meteorological agencies must now document training data provenance and algorithmic transparency for automated severe weather warning systems. Aviation weather service providers in Germany and France are restructuring R&D roadmaps to accommodate these documentation burdens.
Airlines are unbundling weather radar maintenance from original equipment manufacturer service contracts, instead procuring third-party predictive analytics subscriptions. Low-cost carriers in Southeast Asia and Middle Eastern hubs are leading this shift, purchasing real-time turbulence data streams from specialized meteorological data aggregators rather than maintaining proprietary radar calibration programs. This pattern concentrates most visibly in Dubai, Singapore, and Istanbul hub operations.
Weather Radar Market Segmentation
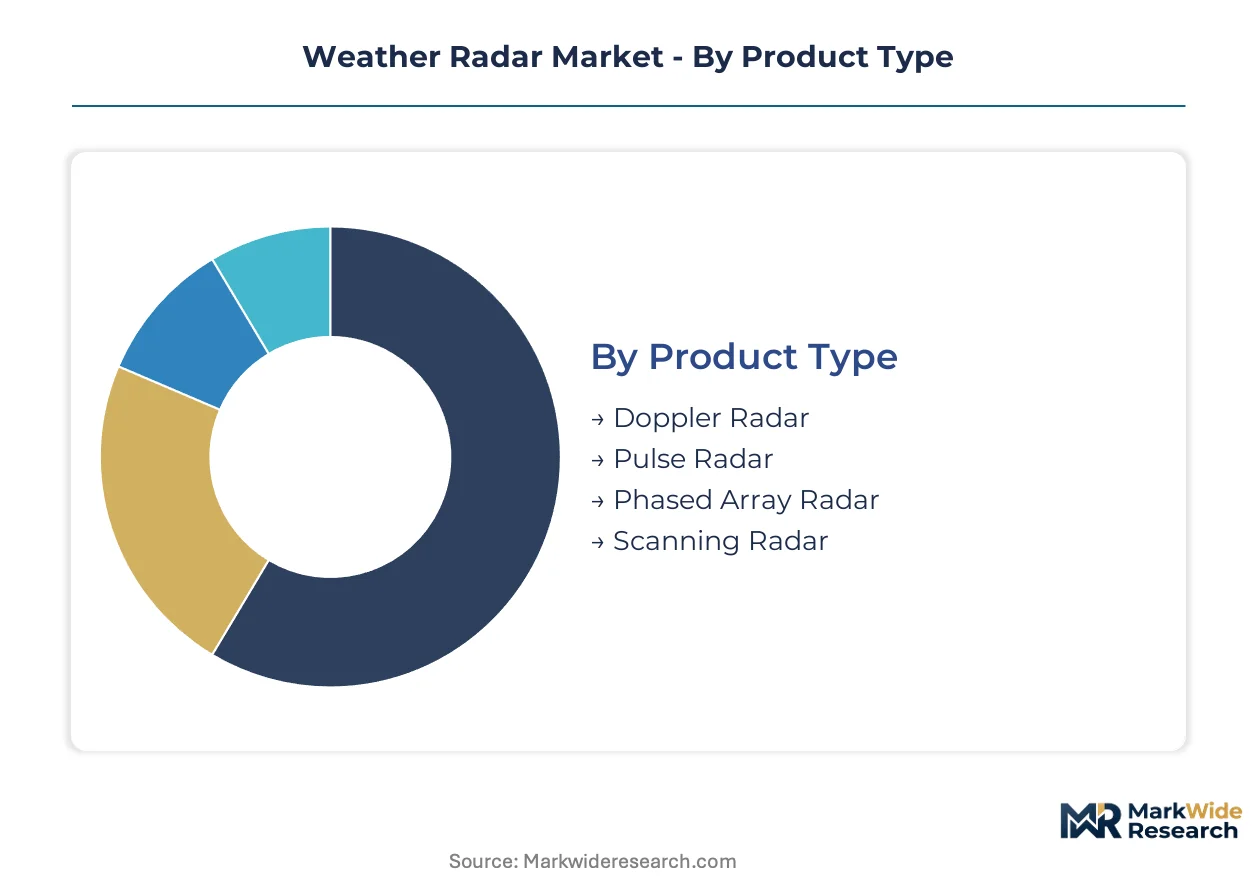
Weather radar procurement patterns diverge sharply across aviation, maritime, and meteorological agencies, with each end-use imposing distinct technical specifications on transmitter architecture, beam-steering mechanisms, and signal processing requirements. Understanding these segment boundaries clarifies why solid-state Doppler systems dominate airport installations while phased arrays capture defense budgets.
Product Type:
Aviation authorities prioritize detection range and update frequency when selecting radar architecture, while meteorological agencies weigh precipitation classification accuracy against capital expenditure constraints.
- Doppler Radar:Measures velocity shifts in backscattered signals to detect storm motion and wind shear, with terminal installations mandated by FAA at commercial airports across the United States. Demand concentrates among airport authorities in China, India, and Japan modernizing civil aviation infrastructure to reduce weather-related flight disruptions.
- Phased Array Radar:Employs electronic beam steering through active electronically scanned arrays, eliminating mechanical antenna inertia and enabling rapid repositioning. Defense agencies in Norway, Sweden, and Finland adopt these systems to track fast-evolving convective storms across Nordic latitudes where mechanical scan rates prove insufficient.
- Pulse Radar:Legacy magnetron-based systems requiring regular vacuum-tube replacement and calibration.
- Scanning Radar:Mechanical antenna rotation platforms with established supply chains in maritime applications.
Volume sits with Doppler Radar; growth tilts toward Phased Array Radar.
Technology:
Transmitter reliability determines total cost of ownership for unattended meteorological stations, creating procurement tension between proven magnetron designs and emerging solid-state platforms.
- Solid-State Technology:Gallium nitride transmitters achieve peak powers exceeding 250 kW with maintenance intervals extending across years rather than months. Meteorological services in the Australian Outback, Canadian Arctic, and Siberian corridors deploy these for remote installations lacking on-site technical staffing.
- Magnetron Technology:Vacuum-tube transmitters with established repair infrastructure and lower upfront capital requirements. Budget-constrained agencies in Brazil, South Africa, and Mexico retain these systems where RF engineering expertise gaps complicate solid-state transitions.
- Frequency Modulated:Continuous-wave variants enabling compact form factors for airborne and mobile deployments.
- Digital Signal Processing:Software-defined architectures unbundling hardware from proprietary algorithms, particularly relevant under EU AI Act documentation requirements for automated severe weather warnings.
Magnetron Technology retains installed base dominance; solid-state platforms are expanding most quickly in new procurement cycles.
End User:
Regulatory mandates shape procurement timelines more than technical specifications across aviation and maritime applications, with certification requirements varying by operational domain.
- Aviation:Terminal Doppler weather radar coverage required under FAA 14 CFR Part 139 and EASA CS-25 airworthiness standards. Low-cost carriers in Southeast Asia and Middle Eastern hubs are unbundling maintenance from OEM contracts, purchasing real-time turbulence data streams from meteorological aggregators instead.
- Meteorology:Ground-based networks generating steadiest replacement revenue through dual-polarization retrofits. Agencies in Germany, France, and the United Kingdom upgrade WSR-series installations to improve precipitation classification accuracy and severe weather warning lead times.
- Maritime:Coastal surveillance authorities in Indonesia, Vietnam, and the Philippines procure specialized X-band compact radars for port security and severe weather monitoring.
- Defense:Electronic warfare integration requirements driving phased array adoption with beam-steering agility prioritized over cost minimization.
Meteorology captures replacement volume; aviation demonstrates the steepest expansion trajectory for integrated cockpit weather suites.
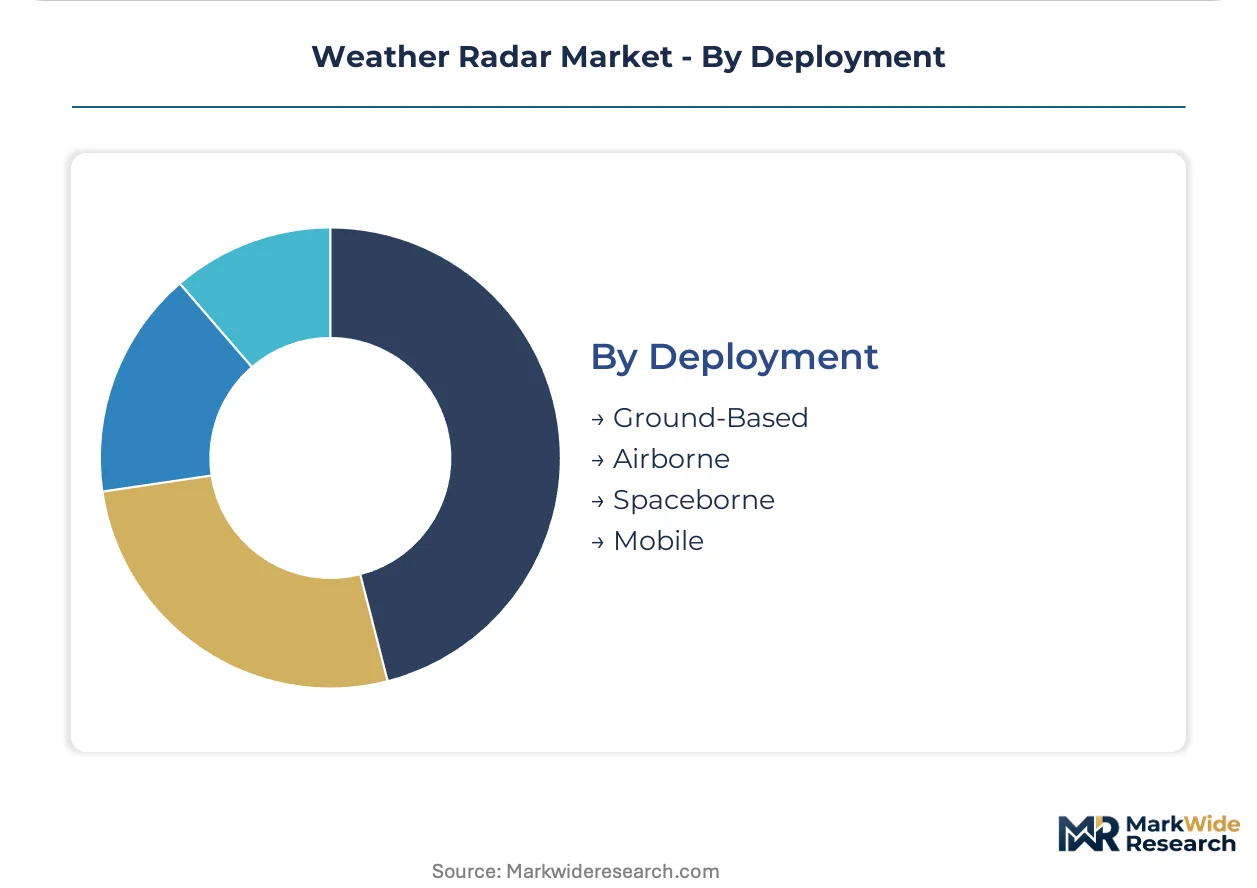
Deployment:
Physical installation constraints determine antenna size, power availability, and maintenance access, segmenting procurement between fixed infrastructure and mobile platforms.
- Ground-Based:Fixed meteorological installations with dedicated power and communication infrastructure. C-band 5G deployment in the United States and Europe forces costly interference mitigation protocols and filter upgrades at existing sites.
- Airborne:Integrated cockpit systems combining weather radar with terrain awareness and traffic collision avoidance. Regional carriers drive retrofit demand as avionics suites converge around unified display architectures.
- Mobile:Deployable units for emergency response and field meteorology with rapid setup requirements.
- Spaceborne:Satellite precipitation radars with specialized launch constraints and orbital maintenance limitations.
Ground-Based deployment anchors revenue stability; airborne segments concentrate margin in premium integrated suites.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beijing anchors terminal Doppler radar deployment as China's civil aviation authority mandates weather surveillance upgrades across 241 commercial airports. Airport authorities in Shanghai, Guangzhou, and Chengdu are accelerating solid-state transmitter procurement to reduce weather-related flight disruptions.
United States
The FAA maintains terminal Doppler weather radar coverage requirements under 14 CFR Part 139 across 500+ commercial airports. Dallas-Fort Worth and Atlanta Hartsfield-Jackson anchor the largest ground-based radar replacement programs. Solid-state retrofits concentrate in the Midwest corridor where unattended meteorological stations require extended maintenance intervals.
Germany
Deutscher Wetterdienst operates Europe's densest meteorological radar network with dual-polarization upgrades across Bavaria and North Rhine-Westphalia. EASA CS-25 airworthiness standards govern airborne weather radar certification for Lufthansa and Eurowings fleets. Frankfurt and Munich airports coordinate regional severe weather warning systems with adjacent national networks.
India
The Airports Authority of India is expanding Doppler coverage across 125 operational airports under civil aviation modernization directives. Mumbai Chhatrapati Shivaji and Delhi Indira Gandhi international airports lead terminal radar procurement. Bengaluru and Hyderabad anchor solid-state transmitter deployment in southern corridor meteorological stations.
Japan
Japan Meteorological Agency maintains phased array pilot programs in Hokkaido and Tohoku regions for fast-evolving convective storm tracking. Narita and Haneda airports operate integrated terminal Doppler systems under CAAC-influenced GB standard harmonization. Osaka Kansai anchors maritime X-band radar procurement for coastal surveillance applications.
Weather Radar Market Key Industry Players
Premium-margin players sit above commodity-margin players across transmitter architecture and signal processing sophistication. The vendor base stratifies between integrated avionics conglomerates, specialized meteorological equipment fabricators, and regional defense-electronics contractors. Three archetypes dominate: full-stack avionics suppliers bundling weather radar into cockpit suites, ground-based meteorological specialists with dual-polarization platforms, and maritime-focused compact radar developers. Competitive moves concentrate on solid-state technology licensing partnerships and unattended station automation capabilities.
Among North American avionics conglomerates, Collins Aerospace and Honeywell International Inc. represent the integrated cockpit convergence archetype, anchoring airborne weather radar contracts through unified terrain awareness and traffic collision avoidance bundling. Vaisala Oyj exemplifies the ground-based meteorological specialist tier, occupying a position in dual-polarization platform supply for national weather services. Furuno Electric Co., Ltd. sits within the maritime compact radar segment, reflecting coastal surveillance specialization across Asia-Pacific port authorities.
| Leading Market Players |
|---|
| Collins Aerospace |
| Honeywell International Inc. |
| Leonardo Germany GmbH |
| Vaisala Oyj |
| Furuno Electric Co., Ltd. |
| EWR Radar Systems Inc. |
| Enterprise Electronics Corporation |
| Garmin International Ltd. |
| Beijing Minstar Radar Co., Ltd. |
| Others |
Cost & Logistics Intelligence
FAA 14 CFR Part 139 compliance mandates gate qualified supplier access and premium-tier pricing for terminal Doppler radar installations, compressing procurement pools to certified manufacturers while elevating total cost of ownership benchmarks for airport authorities.
Pricing Analysis
Outcome-based pricing anchored to operational uptime guarantees dominates solid-state transmitter procurement, with meteorological agencies in Germany and Japan paying premiums for unattended station reliability. Price differentiation separates dual-polarization certified platforms from legacy magnetron systems, while C-band 5G interference mitigation costs are intensifying pricing pressure across United States ground-based deployments. Regional carriers in Southeast Asia exhibit highest price sensitivity, prioritizing per-unit capital expenditure over lifecycle maintenance bundling.
Supply Chain Analysis
Refurbishment flows for magnetron vacuum tubes sustain aftermarket revenue streams while solid-state transmitter adoption shifts value toward semiconductor fabrication stages. Gallium nitride substrate supply concentrates in Taiwan and South Korea, with radar system assembly anchored in United States, Germany, and Japan facilities. Single-source vulnerability in GaN foundry capacity creates structural risk, while distribution runs through national meteorological procurement frameworks and defense-electronics contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a cost-of-compliance story where EASA CS-25 airworthiness certification creates a barrier-to-entry moat that rewards incumbent investment in dual-polarization platforms and phased array architectures.
For Market Incumbents: To counter solid-state technology licensing erosion, anchor procurement relationships through predictive maintenance service contracts and deepen backward integration into GaN semiconductor sourcing. Collins Aerospace and Vaisala Oyj demonstrate this defensive posture by bundling signal processing software with hardware platforms to lock in meteorological agency upgrade cycles. For New Entrants and Emerging Players: Enter via maritime X-band coastal surveillance white-space in Indonesia, Vietnam, and Philippines port authorities, where compact radar specifications favor specialized fabricators over integrated avionics conglomerates. Target unattended station automation in Australian Outback and Canadian Arctic corridors as the most penetrable deployment segment, leveraging solid-state reliability to displace legacy magnetron maintenance contracts. For Investors and Strategic Acquirers: Phased array pilot program announcements from Japan Meteorological Agency and Nordic national services are the leading indicator that electronic beam-steering architectures are crossing from defense into civil meteorology viability. Long-term positioning favors acquisition targets with software-defined signal processing capabilities and EU AI Act documentation infrastructure, as automated severe weather warning systems face escalating conformity assessment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| GaN Transmitter Technology Licensing | Enables solid-state radar reliability for unattended meteorological stations in remote geographies. |
| Dual-Polarization Platform Retrofit | Extends WSR-series installed base revenue through precipitation classification accuracy upgrades. |
| Integrated Cockpit Suite Convergence | Captures regional carrier retrofit demand by unifying weather radar with terrain awareness systems. |
| Maritime X-Band Compact Radar Deployment | Addresses port security and severe weather monitoring requirements across Asia-Pacific coastal authorities. |
| EU AI Act Compliance Documentation | Structures R&D roadmaps for automated severe weather warning algorithm transparency requirements. |
Research Approach
Multi-period observation of solid-state transmitter procurement cycles, dual-polarization retrofit timelines, and phased array pilot program disclosures anchored the trend analysis, supplemented by interviews with airport authority procurement directors, meteorological agency technical officers, avionics platform engineers, and defense-electronics program managers. Secondary validation drew from FAA 14 CFR Part 139 enforcement records, EASA CS-25 certification databases, EU AI Act implementation guidance, and national weather service capital expenditure disclosures. Bottom-up segment sizing triangulated against top-down aviation infrastructure modernization budget aggregates.
Segment-weighting across product type, technology architecture, end-user vertical, and deployment mode shaped the analytical framework, with CAGRs derived from installation base replacement curves and new procurement cycle trajectories across the projection horizon. Modeled inputs incorporated solid-state transmitter reliability benchmarks, magnetron vacuum tube aftermarket decay rates, and C-band spectrum interference mitigation cost escalators specific to meteorological radar applications.
Revisions become necessary when GaN semiconductor foundry capacity constraints intensify, C-band 5G interference protocols diverge across national regulators, or phased array cost curves compress faster than mechanical antenna replacement cycles. Practitioners should monitor FAA and EASA certification backlog durations, Taiwan and South Korea substrate export licensing shifts, and EU AI Act automated warning system enforcement thresholds for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
NB-IoT Smart Meter Market
Sensors and Controls
Digital Barometer Market
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Contact Steering Torque Sensor Market
Sensors and Controls
Solid Flow Rate Valve Control Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
United States Gas Sensors Market
Sensors and Controls
Thermal Flow Meter Market
Sensors and Controls
UV Sensors Market
Sensors and Controls
Digital Pool Thermometers Market
Sensors and Controls
Global RFID Sensor Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Door Control Modules Market
Sensors and Controls
Ultrasound Sensors Market