
 Doppler Wind Lidar System Market | 2026-2036
Doppler Wind Lidar System Market Size, Share, and Industry Trends Forecast 2026-2036
Doppler Wind Lidar System Market Outlook
China is narrowing its gap with European suppliers in Doppler wind lidar manufacturing capacity. Vaisala leverages its meteorological heritage to dominate calibration protocols for ground-based installations. HALO Photonics specializes in compact coherent systems for research institutions requiring high temporal resolution. ZX Lidars anchors its position in the Chinese domestic market through proximity to major wind farm developers.
A Doppler wind lidar system emits laser pulses and measures frequency shifts in backscattered light from atmospheric aerosols to calculate wind velocity vectors with precision ranging from meters to kilometers. These instruments enable real-time wind field characterization for aviation safety, power grid forecasting, and turbine yaw control. Ground-based lidar occupies the largest installed base for wind resource assessment campaigns, while airborne platforms represent the fastest-growing category as drone-mounted systems reduce campaign costs for offshore site surveys. Pulsed lidar technology leads unit shipments due to proven range performance, though FMCW architectures are gaining traction where continuous-wave precision benefits turbine control loops.
The FAA mandates wake vortex and wind shear detection capabilities at major US airports, creating recurring demand for certified lidar installations. EASA's evolving standards for offshore helicopter operations are expanding meteorological sensor requirements on North Sea platforms. China's GB standards for wind power forecasting are tightening data quality thresholds that favor systems with demonstrated turbulence profiling accuracy. Stakeholders must weigh certification timelines against technology refresh cycles as coherent detection architectures mature.
Market Dynamics
Offshore wind farm developers are consolidating procurement around nacelle-mounted lidar systems that feed real-time yaw control algorithms, compressing the traditional separation between meteorological assessment and turbine automation.
Growth Catalysts
- EU Green Deal renewable targets:Grid operators in Denmark and Germany now mandate turbulence profiling for interconnecting wind farms, creating recurring hardware refresh cycles.
- FAA wake vortex mandates:Major US airports must install certified lidar for wind shear detection, generating sustained replacement demand as certification standards tighten.
- Pulsed-FMCW architecture convergence:Hybrid systems combining range performance with continuous-wave precision are capturing turbine control loop applications previously served by separate instrument categories.
Market Restraints
- Optical component supply concentration:Single-mode fiber amplifiers and narrow-linewidth laser seeds concentrate among German and Japanese specialty suppliers, exposing lead time volatility.
- EASA helicopter platform certification:Evolving standards for North Sea meteorological sensors create timeline uncertainty for platform-mounted installations awaiting type approval.
- Radar substitution in aviation:Terminal Doppler Weather Radar retains installed base advantages for airport coverage, limiting lidar penetration in legacy infrastructure environments.
Strategic Opportunities
- Drone-mounted offshore surveys:Lightweight coherent systems reduce campaign costs for pre-construction wind resource assessment in floating wind lease areas.
- China wind corridor densification:State-backed projects in Gansu and Inner Mongolia require meteorological sensor networks at spacing intervals below current installation density.
- Power purchase agreement forecasting:Utility-scale solar-wind hybrid developers seek lidar-derived ramp prediction to satisfy merchant contract penalty clauses.
Industry Challenges
- Coherent detection engineering talent:The intersection of laser physics and atmospheric science produces candidate pools shallow relative to deployment timelines.
- Multi-jurisdiction certification sequencing:Systems requiring FAA, EASA, and GB standard compliance face staggered approval cycles that compress product refresh windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Doppler Wind Lidar System Market |
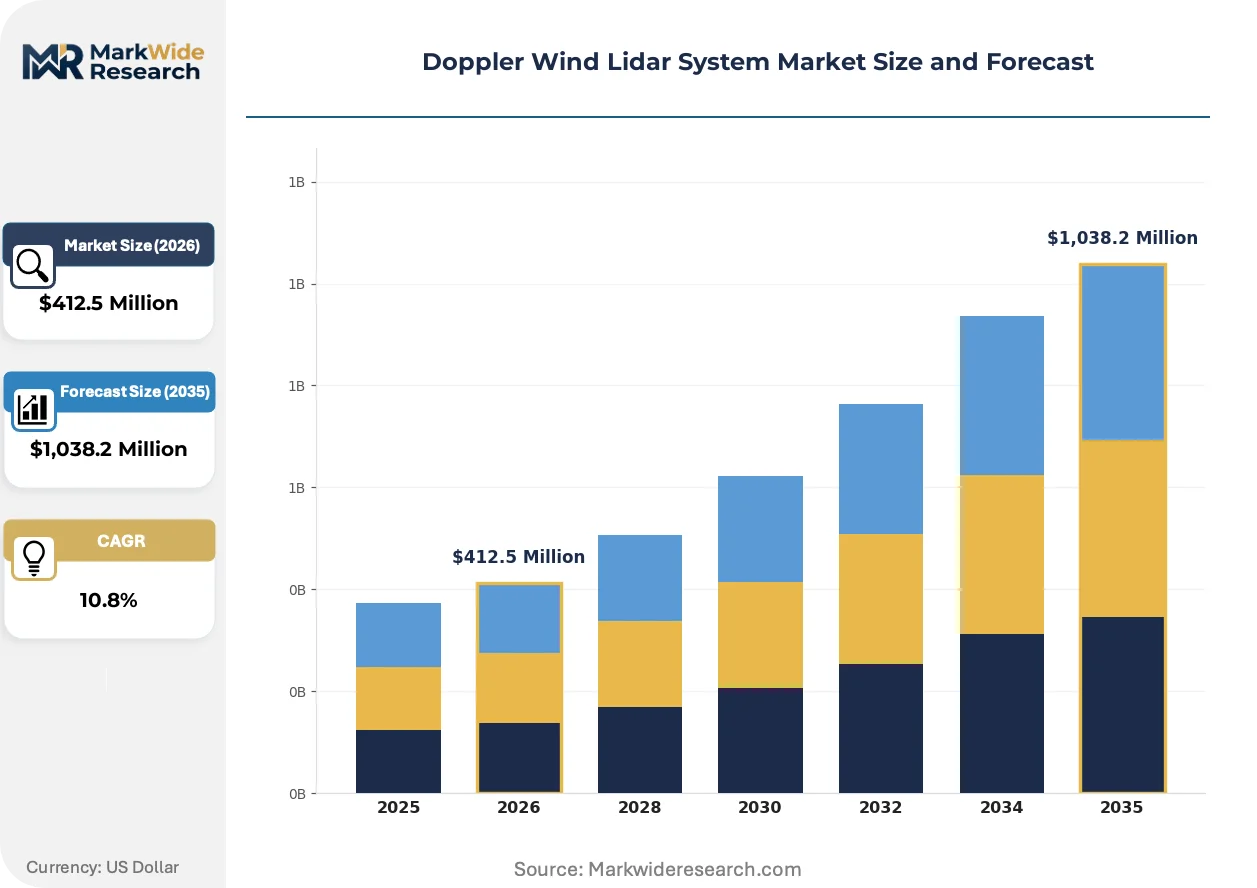
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,038.2 Million |
| CAGR (2026 – 2036) | 10.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Lidar, Ground-based Lidar, Airborne Lidar, Fixed Lidar End User: Aerospace, Meteorology, Renewable Energy, Research Institutions Application: Weather Forecasting, Wind Resource Assessment, Environmental Monitoring, Turbine Optimization Technology: FMCW Lidar, Pulsed Lidar, Coherent Lidar, DOP Lidar |
| Companies Covered | Vaisala, Leosphere, ZX Lidars, NRG Systems, Mitsubishi Electric, Deutsche WindGuard GmbH, HALO Photonics, Movelaser, Windar Photonics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Doppler Wind Lidar System Market Strategic Shifts
Detection architectures and deployment modalities are converging in ways that blur traditional boundaries between research-grade instrumentation and industrial automation hardware.
Frequency-modulated continuous-wave lidar is hybridizing with pulsed architectures to deliver both long-range wind profiling and high-temporal-resolution turbine control inputs from single hardware platforms. Offshore wind farm operators in the North Sea are piloting these hybrid systems for simultaneous wake steering and power forecasting. The convergence is compressing supplier differentiation previously based on range-versus-resolution tradeoffs.
China's GB standards for wind power forecasting are tightening data quality thresholds that favor systems with demonstrated turbulence profiling accuracy. Domestic developers in Gansu and Xinjiang provinces now specify lidar-derived shear and turbulence intensity metrics in equipment procurement tenders. Foreign suppliers are localizing calibration protocols to satisfy these evolving technical specifications.
Equipment procurement for offshore wind resource campaigns is fragmenting from integrated service contracts toward unbundled hardware and data processing subscriptions. Danish and German developers now lease lidar units separately from meteorological consultancy services. The shift pressures traditional bundled providers to restructure pricing and service architectures.
Doppler Wind Lidar System Market Segmentation
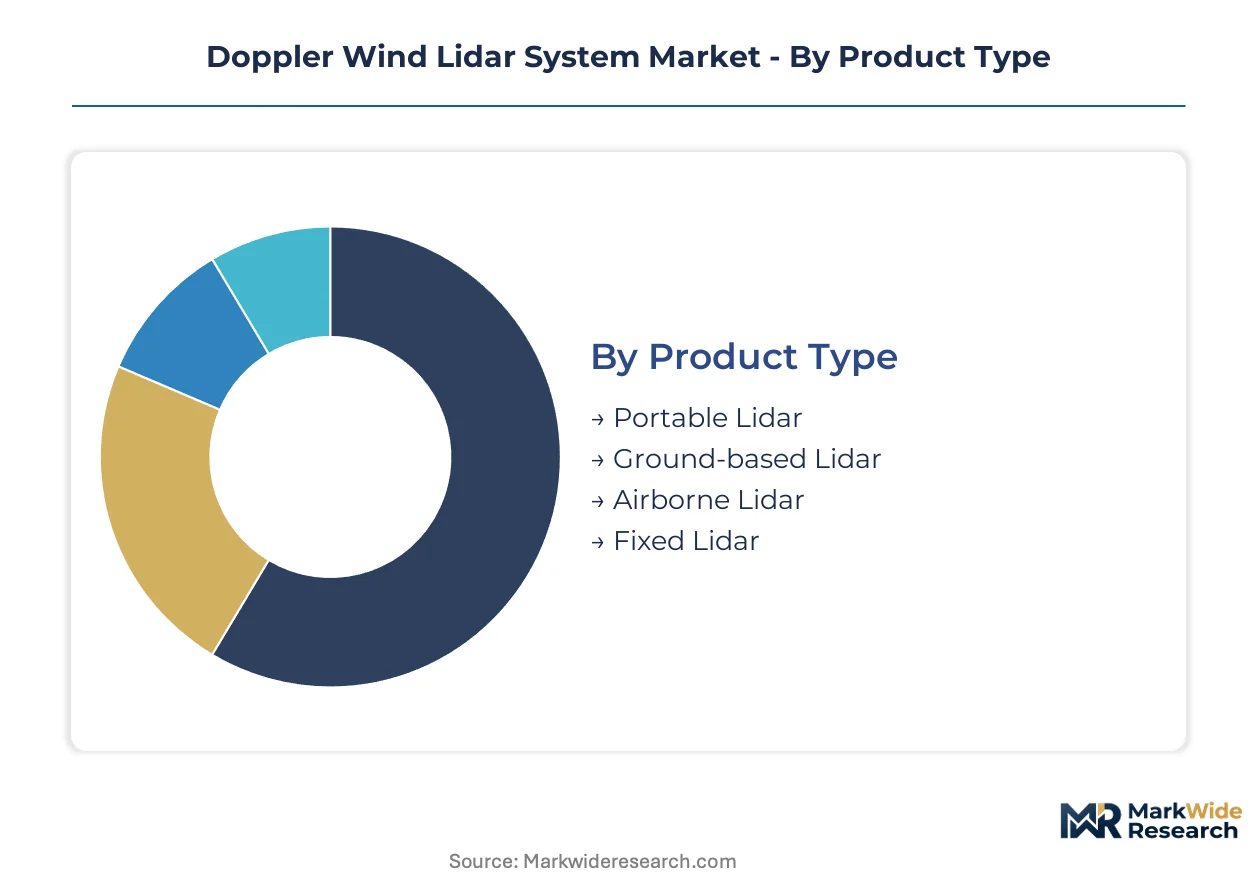
Deployment modality and detection architecture determine procurement economics and operational envelope for Doppler wind lidar systems. End-use concentration in offshore wind and aviation safety creates divergent specification requirements across segments.
Product Type:
Physical form factor dictates installation logistics, calibration protocols, and mobility constraints for field deployment.
- Ground-based Lidar:Permanent installations on towers or dedicated pads deliver continuous vertical wind profiling up to boundary-layer heights. Danish and German grid operators mandate these for turbulence assessment at offshore wind interconnection points.
- Airborne Lidar:Drone-mounted coherent systems reduce offshore site survey costs by eliminating fixed platform requirements. Floating wind lease areas in the North Sea are driving procurement as developers seek campaign flexibility.
- Portable Lidar:Rapid-deployment units serve temporary meteorological campaigns and emergency aviation weather monitoring.
- Fixed Lidar:Hardened installations for airport wind shear detection meet FAA certification timelines for sustained replacement cycles.
Ground-based Lidar holds installed capacity. Airborne Lidar is rotating up the share rankings.
End User:
Customer type determines specification stringency, certification burden, and contract structure for equipment suppliers.
- Renewable Energy:Wind farm developers in China and Northern Europe specify nacelle-mounted systems for real-time yaw control. State-backed corridor projects in Gansu and Inner Mongolia require dense sensor networks with demonstrated turbulence profiling accuracy.
- Aerospace:FAA mandates at major US airports and EASA's evolving North Sea helicopter platform standards create recurring hardware demand with extended approval timelines.
- Meteorology:National weather services deploy networks for numerical weather prediction validation and severe weather monitoring.
- Research Institutions:High temporal resolution requirements favor compact coherent systems from specialized suppliers.
Renewable Energy commands procurement volume. Aerospace maintains pricing premiums through certification barriers.
Application:
Use case determines range, resolution, and refresh rate specifications that segment hardware architectures.
- Wind Resource Assessment:Pre-construction campaigns require validated shear and turbulence intensity metrics. Chinese GB standards tightening data quality thresholds favor systems with proven profiling accuracy.
- Turbine Optimization:Nacelle-mounted lidar feeding yaw control algorithms compresses the separation between meteorological assessment and turbine automation. North Sea offshore operators pilot hybrid pulsed-FMCW architectures for simultaneous wake steering.
- Weather Forecasting:Grid integration standards under the EU Green Deal require ramp prediction for utility-scale wind power forecasting.
- Environmental Monitoring:Atmospheric boundary layer research and pollution dispersion studies employ long-range profiling capabilities.
Wind Resource Assessment anchors historical deployment. Turbine Optimization is climbing the fastest as control loop integration accelerates.
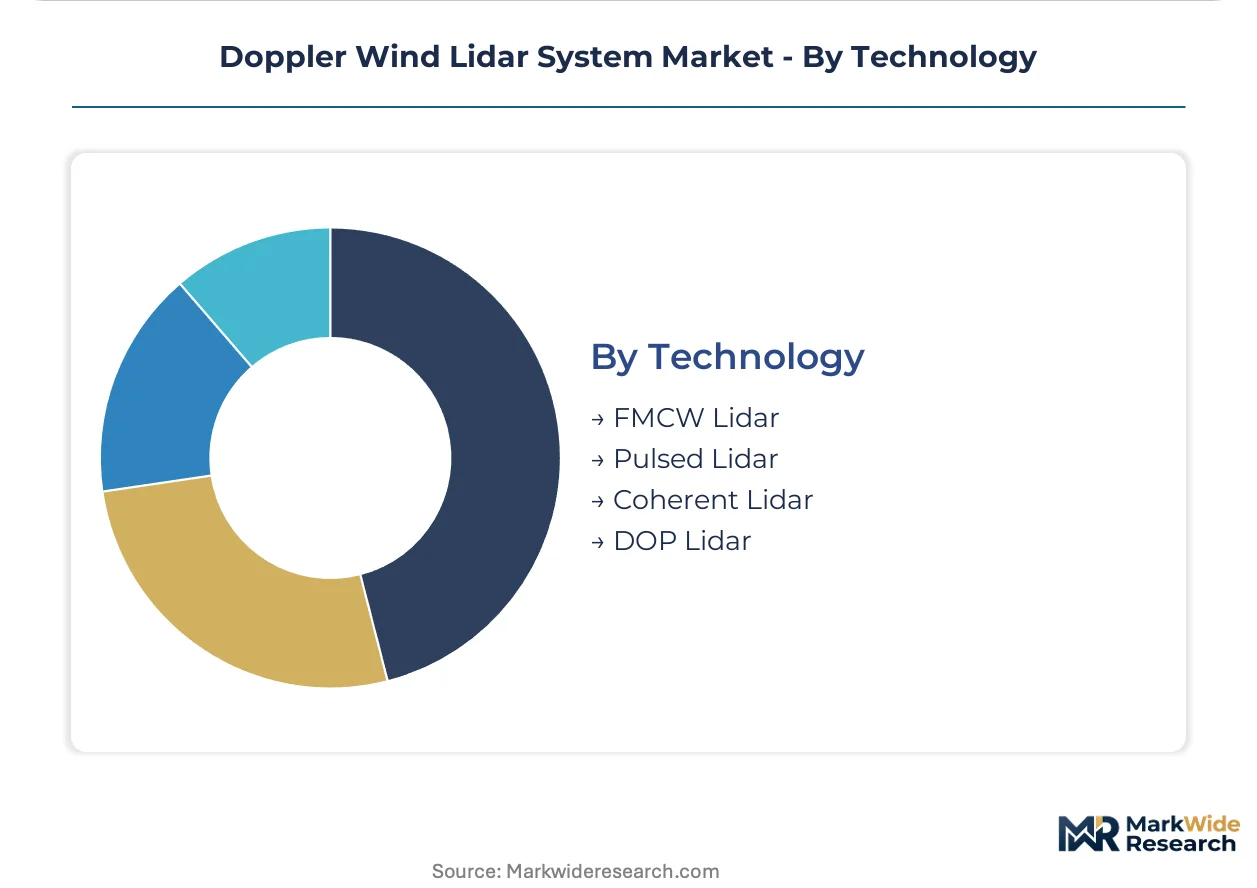
Technology:
Detection architecture determines range performance, precision, and suitability for continuous versus campaign deployment.
- Pulsed Lidar:Proven range performance dominates unit shipments for wind resource assessment and aviation safety applications. Established calibration protocols support regulatory certification cycles.
- FMCW Lidar:Continuous-wave precision benefits turbine control loops where high temporal resolution outweighs maximum range requirements. Hybrid architectures combining FMCW with pulsed capabilities are capturing applications previously served by separate instrument categories.
- Coherent Lidar:Signal processing from atmospheric aerosol backscatter enables compact system designs for drone-mounted offshore surveys.
- DOP Lidar:Differential optical path configurations serve specialized research applications requiring multi-angle wind vector reconstruction.
Pulsed Lidar maintains shipment leadership. FMCW Lidar is gaining share through architecture convergence with pulsed systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Single-mode fiber amplifiers and narrow-linewidth laser seeds concentrate among German and Japanese specialty suppliers, creating lead time volatility that ripples through system integrators worldwide. This upstream concentration shapes regional deployment timelines and certification sequencing across major demand centers.
United States
FAA mandates at major airports drive recurring demand for certified wind shear detection installations. The agency's tightening certification standards compress product refresh windows for legacy systems. Texas and California host the densest clusters of aviation safety deployments and renewable energy forecasting networks.
China
State-backed wind corridor projects in Gansu and Inner Mongolia require meteorological sensor networks at spacing intervals below current installation density. GB standards for wind power forecasting tighten data quality thresholds favoring turbulence profiling accuracy. Domestic developers in Xinjiang province now specify lidar-derived shear metrics in procurement tenders.
Germany
Grid operators mandate turbulence profiling for interconnecting wind farms under EU Green Deal renewable targets. The country's specialty suppliers dominate optical component production for single-mode fiber amplifiers. North Sea offshore developers in Lower Saxony and Schleswig-Holstein consolidate procurement around nacelle-mounted systems for turbine optimization.
Denmark
Offshore wind farm operators pilot hybrid pulsed-FMCW architectures for simultaneous wake steering and power forecasting. Danish developers now lease lidar units separately from meteorological consultancy services. Copenhagen and Aarhus anchor the unbundling shift from integrated service contracts toward hardware subscriptions.
United Kingdom
EASA's evolving standards for North Sea helicopter platforms expand meteorological sensor requirements. Aberdeen and Scottish offshore clusters drive platform-mounted installation demand awaiting type approval. English Channel floating wind lease areas generate campaign flexibility requirements for drone-mounted survey systems.
Doppler Wind Lidar System Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in optical and laser subsystems. The vendor base spans three tiers: multinational meteorological instrument houses with calibration heritage, regional wind energy specialists with nacelle integration expertise, and research-grade coherent system boutiques. Two dominant competitive moves reshape positioning: hybrid architecture development combining pulsed range with FMCW precision, and geographic localization of calibration protocols to satisfy tightening national standards.
Among meteorological heritage players, Vaisala anchors the calibration protocol tier for ground-based installations. ZX Lidars occupies a position within the Chinese domestic market through proximity to major wind farm developers. HALO Photonics exemplifies the compact coherent specialist archetype serving research institutions requiring high temporal resolution. These three represent distinct competitive vectors—heritage calibration, geographic anchoring, and research specialization—that structure rivalry across deployment modalities.
| Leading Market Players |
|---|
| Vaisala |
| Leosphere |
| ZX Lidars |
| NRG Systems |
| Mitsubishi Electric |
| Deutsche WindGuard GmbH |
| HALO Photonics |
| Movelaser |
| Windar Photonics |
| Others |
Value Chain & Pricing Dynamics
Rotterdam-Hamburg freight corridors impose cost volatility that amplifies pricing power for German optical component suppliers while compressing margins for system integrators serving price-sensitive Chinese wind farm developers.
Pricing Analysis
FAA certification mandates dictate the pricing tier structure across aviation safety deployments, separating FAA-validated installations from uncertified research-grade units. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales calibration bundling. Cost compression in the economy tier is intensifying because Chinese domestic suppliers are localizing production of pulsed architectures. Research institutions exhibit highest price sensitivity, while offshore wind farm operators absorbing turbine control integration costs show lowest sensitivity.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk planning for narrow-linewidth laser seed procurement. Single-mode fiber amplifiers concentrate in Germany and Japan, while final system assembly draws from China, Denmark, and the United States. Raw material dependencies include rare-earth-doped fiber, precision optical coatings, and hermetic packaging substrates. Single-source vulnerability in specialty laser diode supply creates lead time volatility. Distribution runs through direct OEM relationships for nacelle-mounted systems and meteorological service contracts for ground-based installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Doppler wind lidar market sits in early-cycle expansion as nacelle-mounted turbine control integration accelerates hardware refresh cycles beyond traditional meteorological assessment replacement rates.
For Market Incumbents: Entrench calibration protocol dominance by embedding turbulence profiling algorithms into grid operator software stacks before Chinese GB standards fully mature. Deepen backward integration into single-mode fiber amplifier production to neutralize German supplier lead time volatility. Lock in multi-year service contracts with North Sea offshore developers piloting hybrid pulsed-FMCW architectures. For New Entrants and Emerging Players: Establish a beachhead in drone-mounted offshore survey services for floating wind lease areas where campaign flexibility outweighs incumbent calibration heritage. Target research institutions in Asia-Pacific requiring compact coherent systems with high temporal resolution. Lead with unbundled hardware subscription pricing to exploit the procurement shift away from integrated meteorological service contracts. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coherent detection specialists with proven FMCW-pulsed hybrid architectures over pure-play pulsed incumbents. Five-to-ten year viability hinges on certification throughput velocity across FAA, EASA, and GB standard regimes. Watch for inflection signals in Chinese state-backed corridor project tender specifications that mandate turbulence profiling accuracy thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Architecture Development | Combining pulsed range with FMCW precision captures turbine control loop applications previously split across separate instrument categories. |
| Calibration Protocol Localization | Adapting turbulence profiling validation to Chinese GB standards satisfies tightening data quality thresholds in state-backed wind corridor tenders. |
| Unbundled Hardware Subscriptions | Separating lidar unit leasing from meteorological consultancy services aligns with Danish and German offshore developer procurement restructuring. |
| Vertical Integration into Optical Components | In-house production of single-mode fiber amplifiers reduces exposure to German and Japanese specialty supplier lead time volatility. |
| Drone-Mounted Survey Platform Certification | EASA type approval for lightweight coherent systems unlocks floating wind lease area campaigns in the North Sea and English Channel. |
Study Parameters
Operator-level perspectives from wind farm control engineers, aviation safety officers, meteorological service procurement leads, and optical subsystem R&D directors anchored the qualitative base. Primary interview findings were cross-validated against secondary sources including FAA certification databases, EASA technical documentation, Chinese GB standard filings, and EU Green Deal implementation reports. Bottom-up unit shipment estimates triangulated with top-down market sizing derived from grid operator interconnection mandates and offshore lease area development pipelines.
Scenario-bracketing framed the analytical approach across the analysis window, with segmentation modeling across deployment modality, detection architecture, end-use sector, and geographic regulatory cluster. CAGRs were derived from installation density requirements in Chinese wind corridors, FAA-mandated replacement cycles, and hybrid architecture adoption curves in North Sea offshore projects. Forecast inputs incorporated turbulence profiling accuracy thresholds, certification timeline distributions, and unbundled procurement transition rates.
Stress conditions across optical component supply concentration, multi-jurisdiction certification sequencing, and hybrid architecture reliability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EASA helicopter platform standard evolution and Chinese state-backed project tender specifications. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Global Sonar Systems and Technology Market
Sensors and Controls
Global Biosensors Market
Sensors and Controls
Middle East and Africa Vibration Sensors Market
Sensors and Controls
Micropump Market
Sensors and Controls
Marine Sensors Market
Sensors and Controls
Portable Air Purifier Market
Sensors and Controls
Seismic Monitoring Equipment Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Oxygen Sensor Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
TMAH Concentration Monitor Market
Sensors and Controls
APAC Vibration Sensors Market
Sensors and Controls
Global Refrigeration Leak Detector Market