
 Industrial Transmitters Market | 2026-2036
Industrial Transmitters Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Transmitters Market Analysis
Aftermarket service revenue is tilting from break-fix contracts toward predictive maintenance subscriptions. Emerson Electric Co leverages its Plantweb digital ecosystem to anchor long-term service relationships. Yokogawa Electric Corporation competes through deep calibration and lifecycle support capabilities in Asia-Pacific installations.
An industrial transmitter converts physical process variables into standardized electrical signals for monitoring and control, typically outputting 4-20 mA, digital HART, or fieldbus protocols with accuracy ratings from 0.025% to 0.1% of span. Pressure transmitters dominate installed bases across hydrocarbon processing, while wireless transmitters represent the fastest-expanding technology segment as battery-powered devices reduce cabling costs in remote installations. Smart transmitters with embedded diagnostics now capture premium pricing by enabling self-calibration and anomaly detection.
OSHA process safety mandates in the United States and ATEX/IECEx hazardous area certifications in Europe shape product design requirements for explosion-proof housings. The EU AI Act and emerging cybersecurity frameworks are forcing firmware architecture changes in connected devices. Buyers must evaluate supplier roadmaps for protocol interoperability and cloud-native diagnostics before committing to multi-year transmitter fleets.
Market Dynamics
Wireless HART and ISA100.11a protocols are dismantling decades of analog 4-20 mA dominance across hydrocarbon processing, forcing incumbent suppliers to re-architect firmware for battery-powered mesh networks while maintaining hazardous area certifications.
Growth Catalysts
- OSHA Process Safety Management:Mandated safety instrumented systems in US refineries are compelling upgrades to smart transmitters with embedded diagnostics and SIL-rated redundancy.
- Shale field automation:Permian Basin operators are deploying wireless pressure transmitters on wellheads to eliminate trenching costs and accelerate pad drilling timelines.
- Edge computing convergence:Transmitters with onboard analytics are compressing latency for closed-loop control in chemical reactor vessels.
Market Restraints
- Semiconductor supply concentration:ASIC fabrication for signal conditioning chips relies heavily on Taiwan-based foundries, exposing lead times to geopolitical friction.
- ATEX certification costs:European explosion-proof testing adds 18-24 months to product launches for intrinsically safe designs.
- Optical sensing substitution:Fiber-optic pressure sensors are capturing niche applications in subsea umbilicals where electromagnetic interference immunity is paramount.
Strategic Opportunities
- India's PLI scheme for manufacturing:Local assembly incentives are attracting transmitter OEMs to Gujarat and Tamil Nadu industrial corridors for domestic oil and gas demand.
- Hydrogen economy infrastructure:High-pressure transmitters rated for 700 bar are opening new product lines at German electrolyzer and storage facilities.
- Cloud-native diagnostics:Azure IoT and AWS Greengrass integrations are enabling subscription revenue streams that bypass traditional distributor markups.
Industry Challenges
- Firmware security hardening:IEC 62443 certification for industrial cybersecurity is extending development cycles and requiring dedicated penetration testing resources.
- Legacy system integration:Brownfield installations with 1980s-era DCS architectures demand protocol gateways that add cost and failure points.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Transmitters Market |
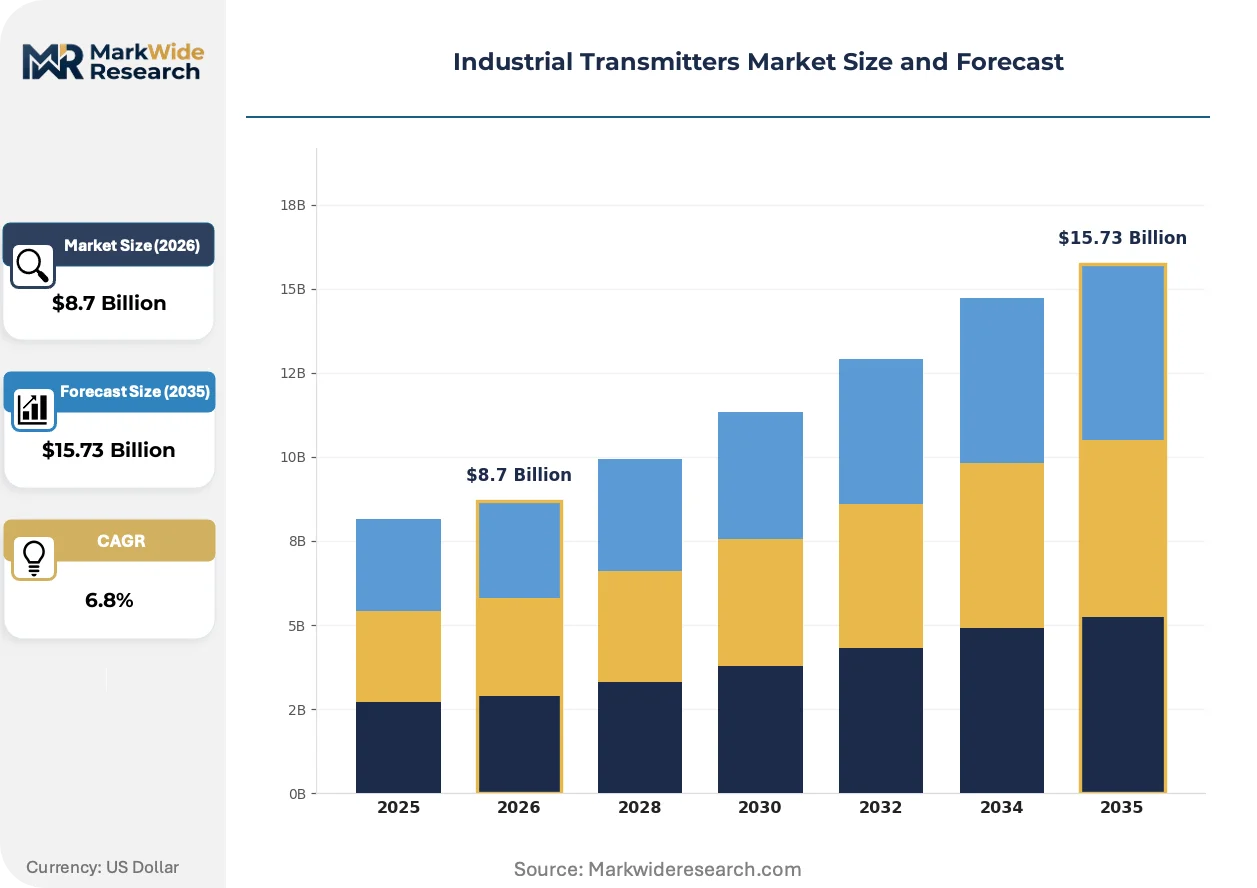
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pressure Transmitters, Level Transmitters, Flow Transmitters, Temperature Transmitters Technology: Wired, Wireless, Smart Transmitters, Analog End User: Oil & Gas, Water & Wastewater, Chemicals, Power Generation Installation: Field-mounted, Panel-mounted, Rack-mounted, Portable |
| Companies Covered | Emerson Electric Co, ABB Ltd, Honeywell International Inc., Yokogawa Electric Corporation, Siemens AG, Schneider Electric, Endress+Hauser, Danfoss A/S, WIKA Alexander Wiegand SE & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Transmitters Market Emerging Trajectories
Digital twin architectures and predictive algorithms are redefining how physical measurement points generate value, transforming transmitters from passive sensors into active decision nodes within process control hierarchies.
Multivariable transmitters that simultaneously calculate differential pressure, static pressure, and process temperature are rendering obsolete single-variable installations in natural gas custody transfer applications. US pipeline operators are standardizing on these devices to reduce instrument count and wiring density. The consolidation is compressing maintenance schedules and spare parts inventory requirements across compressor stations.
EU AI Act classification rules for high-risk industrial systems are mandating algorithmic transparency in smart transmitter diagnostic engines. Manufacturers must now document training data provenance and decision logic for anomaly detection models. German chemical producers are demanding compliance roadmaps before qualifying suppliers for multi-year framework agreements.
Asset-as-a-service contracting is displacing capital purchase models in North American water utilities. Municipal operators in California and Texas are subscribing to pressure and level monitoring networks with guaranteed uptime SLAs rather than owning transmitter fleets. The shift is concentrating vendor relationships around integrated service capabilities rather than hardware specifications alone.
Industrial Transmitters Market Segmentation
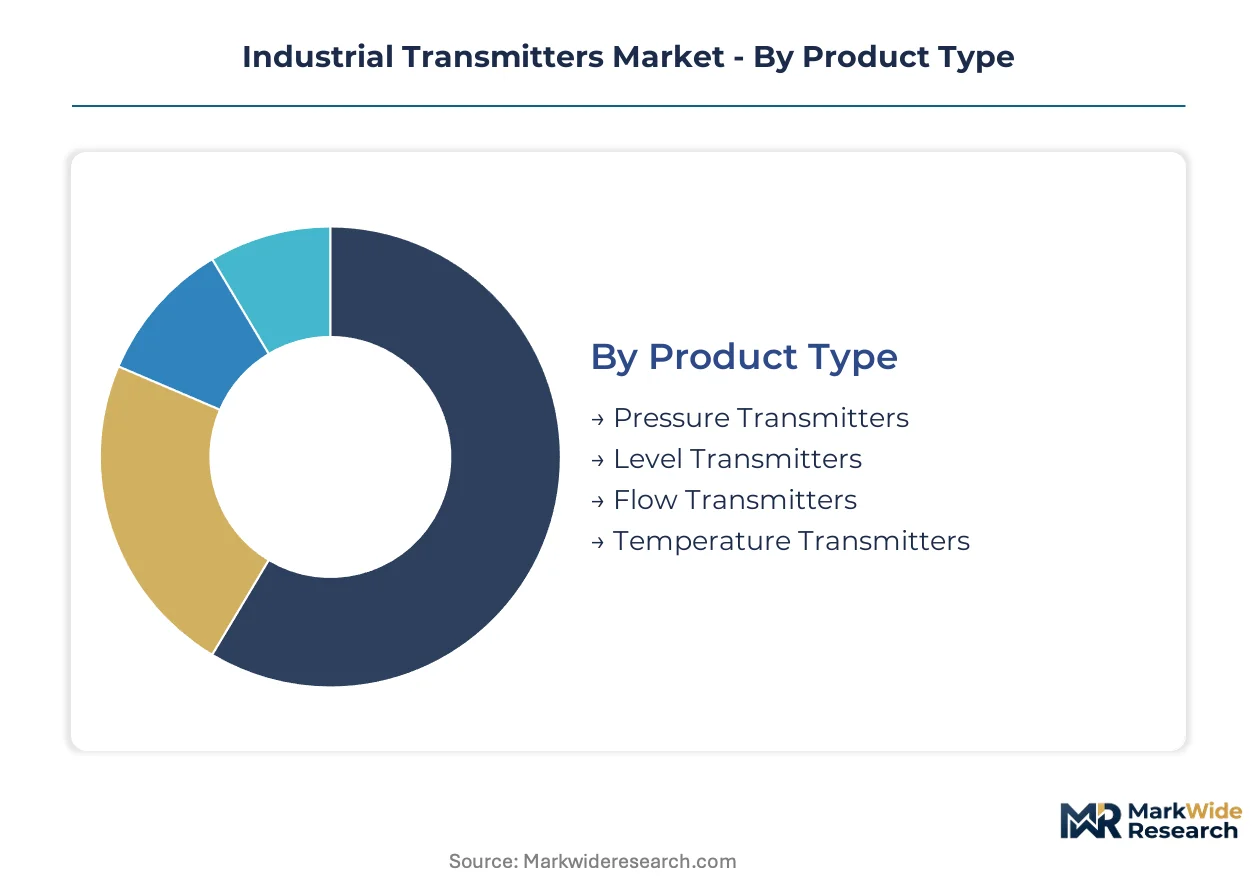
Industrial transmitter procurement varies sharply by process criticality, hazardous environment exposure, and legacy infrastructure compatibility. Buyers segment investments across pressure, level, flow, and temperature measurement points with distinct accuracy, protocol, and certification requirements. Understanding these divisions reveals where suppliers can command premium pricing versus competing on replacement cost.
Product Type:
Process engineers specify transmitters based on the physical variable requiring measurement, with each type carrying distinct calibration protocols and failure modes.
- Pressure Transmitters:These devices convert mechanical pressure into standardized electrical signals, typically employing piezoelectric or capacitive sensing elements rated for absolute, gauge, or differential pressure ranges. Hydrocarbon processing facilities in the United States and Germany concentrate procurement for wellhead monitoring, distillation column control, and pipeline custody transfer applications where SIL-rated safety loops are mandatory.
- Level Transmitters:Guided wave radar, ultrasonic, and hydrostatic technologies measure liquid or solid inventory in tanks and silos. Water utilities across California and Texas are standardizing on non-contact radar units for municipal reservoir monitoring to eliminate maintenance-intensive float mechanisms and reduce operator exposure to confined spaces.
- Flow Transmitters:Differential pressure, electromagnetic, and Coriolis technologies quantify mass or volumetric flow rates. Chemical producers in the German Rhine-Ruhr cluster specify Coriolis devices for reactor feed control where multi-phase flow accuracy determines batch yield consistency.
- Temperature Transmitters:Thermocouple and RTD input conditioning units convert millivolt or resistance signals to process control outputs. Power generation utilities in Japan deploy these for steam turbine bearing monitoring where drift tolerance below 0.1°C prevents thermal damage.
Established volume favors pressure instrumentation; emerging adoption favors level measurement in water infrastructure.
Technology:
Communication architecture determines installation economics, diagnostic depth, and cybersecurity exposure across brownfield and greenfield deployments.
- Wired:4-20 mA and fieldbus installations dominate existing process plants where cable infrastructure is already amortized. Refineries along the US Gulf Coast maintain extensive HART-over-analog populations to preserve DCS compatibility while accessing digital diagnostics.
- Wireless:Battery-powered ISA100.11a and WirelessHART devices eliminate trenching and conduit costs in geographically dispersed assets. Permian Basin shale operators in Texas deploy these for wellhead pressure monitoring where pad drilling timelines compress installation windows.
- Smart Transmitters:Embedded microprocessors enable self-diagnostics, multivariable calculation, and predictive maintenance algorithms. EU chemical producers under AI Act compliance timelines are qualifying these for anomaly detection transparency requirements.
- Analog:Pure 4-20 mA devices without digital overlay persist in safety instrumented systems requiring deterministic response. Aging US refineries with 1980s-era DCS architectures retain these for SIL-rated loops where firmware updates introduce unacceptable verification burden.
Replacement cycles favor wired infrastructure; greenfield investment favors wireless architectures.
End User:
Industry-specific process conditions dictate hazardous area certification, material compatibility, and accuracy specifications.
- Oil & Gas:Exploration, production, refining, and distribution operations require explosion-proof housings and wide operating temperature ranges. Upstream operators in India's Gujarat state are expanding transmitter deployments under PLI scheme incentives for domestic manufacturing.
- Water & Wastewater:Municipal treatment and distribution systems prioritize corrosion-resistant wetted materials and low-maintenance designs. California utilities are adopting subscription-based monitoring services with guaranteed uptime SLAs rather than capital purchases.
- Chemicals:Aggressive media and batch reactor control demand high-accuracy measurement with material certifications. German producers are mandating AI Act compliance roadmaps for smart transmitter diagnostics before multi-year framework agreements.
- Power Generation:Steam cycle efficiency and emissions monitoring drive specification for high-stability temperature and pressure measurement. Japanese utilities under METI efficiency directives are upgrading turbine instrumentation.
Capital intensity favors oil and gas procurement; service model transformation favors water utilities.
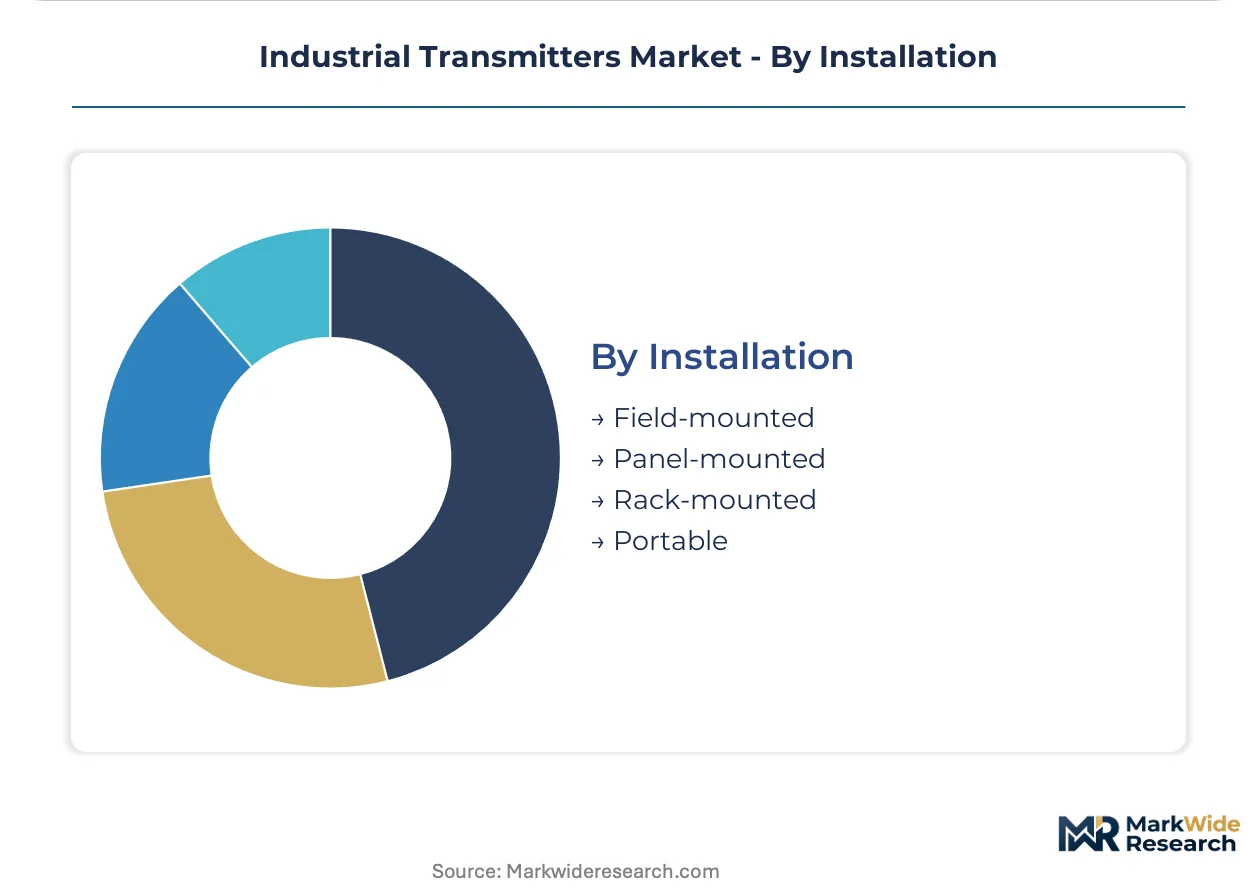
Installation:
Mounting configuration determines environmental protection, accessibility for calibration, and integration with existing control architectures.
- Field-mounted:Weatherproof enclosures with local indicators serve outdoor process equipment. Pipeline compressor stations across the United States specify these for remote isolation valve control.
- Panel-mounted:Control room integration with standardized cutout dimensions supports centralized operator interfaces. German chemical facilities favor these for batch control rooms.
- Rack-mounted:High-density installations in integrated control and safety systems accommodate marshalling cabinets. Indian refinery expansions in Tamil Nadu industrial corridors are adopting these for space-constrained control buildings.
- Portable:Battery-powered calibration and temporary measurement units support maintenance and commissioning activities. Japanese power utilities deploy these for turbine outage verification.
Permanent infrastructure favors field-mounted designs; maintenance optimization favors portable configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Germany and Japan demonstrate the lowest price elasticity, prioritizing SIL-rated safety compliance and AI Act transparency over unit cost. Indian and US shale operators exhibit the highest elasticity, driving procurement toward wireless architectures that eliminate trenching expenses.
United States
Permian Basin shale operators deploy wireless pressure transmitters on wellheads to compress pad drilling timelines and eliminate conduit installation costs. OSHA Process Safety Management mandates compel Gulf Coast refineries to upgrade to smart transmitters with embedded diagnostics and SIL-rated redundancy loops. Houston-area control system integrators anchor the domestic supply chain for hydrocarbon processing instrumentation.
Germany
Rhine-Ruhr chemical producers mandate AI Act compliance roadmaps for smart transmitter diagnostics before executing multi-year framework agreements. ATEX certification requirements for explosion-proof housings extend product launch timelines by 18-24 months for intrinsically safe designs. Bavarian electrolyzer facilities drive specification for 700 bar pressure transmitters serving hydrogen economy infrastructure buildouts.
China
Domestic oil and gas operators expand transmitter deployments across upstream and downstream facilities under national energy security directives. GB standards and MIIT cybersecurity frameworks shape firmware architecture requirements for connected devices in process industries. Yangtze River Delta manufacturing clusters concentrate assembly capacity for export-oriented instrumentation.
India
Gujarat and Tamil Nadu industrial corridors attract transmitter OEM assembly operations under PLI scheme incentives for domestic oil and gas demand. Central Electricity Authority regulations govern power generation instrumentation specifications for grid-connected facilities. Refinery expansions in the Jamnagar complex drive rack-mounted transmitter procurement for space-constrained control buildings.
Japan
METI efficiency directives compel power generation utilities to upgrade turbine instrumentation with high-stability temperature and pressure measurement. JIS standards certification requirements filter supplier qualification for nuclear and thermal power applications. Kansai region chemical producers anchor demand for multivariable transmitters in natural gas custody transfer operations.
Industrial Transmitters Market Vendor Landscape
Capability concentration sits with specialized safety instrumented system suppliers; scale advantage sits with diversified industrial automation conglomerates. The vendor base organizes around three strategic archetypes: integrated platform providers bundling transmitters with DCS ecosystems, component specialists dominating calibration and lifecycle services, and emerging wireless-native challengers. Dominant competitive moves include cloud-native diagnostics integration and predictive maintenance subscription bundling.
Among diversified industrial automation groups, Emerson Electric Co, ABB Ltd, and Honeywell International Inc. exemplify the integrated platform archetype. Emerson anchors long-term service relationships through its Plantweb digital ecosystem. ABB occupies a position spanning both wired fieldbus infrastructure and emerging wireless protocol support. Honeywell represents the scale-driven end with broad hydrocarbon processing penetration. Yokogawa Electric Corporation sits within the lifecycle service specialist tier, competing through deep calibration capabilities in Asia-Pacific installations. Siemens AG and Schneider Electric exemplify European-headquartered conglomerates with cross-sector automation portfolios.
| Leading Market Players |
|---|
| Emerson Electric Co |
| ABB Ltd |
| Honeywell International Inc. |
| Yokogawa Electric Corporation |
| Siemens AG |
| Schneider Electric |
| Endress+Hauser |
| Danfoss A/S |
| WIKA Alexander Wiegand SE & Co. KG |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta manufacturing clusters concentrate transmitter assembly capacity, creating tiered pricing power that favors scale incumbents over specialized challengers in procurement negotiations. Cost compression in wireless module sourcing feeds directly into aggressive entry-level positioning for battery-powered field devices.
Pricing Analysis
Aftermarket service contracts and predictive maintenance subscriptions now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium SIL-certified, standard HART-enabled, and economy analog tiers reflects certification burden and diagnostic depth. Pricing pressure stems from wireless-native challengers commoditizing battery-powered mesh devices for shale field deployment. Municipal water utilities exhibit highest price sensitivity through asset-as-a-service contracting, while German chemical producers under EU AI Act timelines show lowest elasticity for transparent diagnostic engines.
Supply Chain Analysis
Taiwan-based foundries and Yangtze River Delta EMS providers hold concentrated capacity for signal conditioning ASICs and transmitter assembly operations. Semiconductor fabrication draws from Taiwan, South Korea, and Japan; enclosure machining rests on China, Germany, and India; battery cell supply hinges on China and South Korea. Single-source vulnerability in advanced node semiconductor fabrication exposes lead times to geopolitical friction. Distribution runs through authorized distributor networks and direct OEM service organizations to end-user maintenance departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through municipal water utility consolidation and supermajor oil company framework agreements, shifting procurement leverage toward integrated service capabilities and away from pure hardware specifications.
For Market Incumbents: Insulate installed base relationships by embedding cloud-native diagnostics into existing Plantweb-style ecosystems before wireless-native challengers capture greenfield wireless HART deployments. Prioritize IEC 62443 cybersecurity certification investment to extend firmware development timelines that smaller competitors cannot absorb. Defend margin position through backward integration into sensor element manufacturing rather than outsourcing to Taiwan-based foundries. For New Entrants and Emerging Players: Pursue white-space opportunity in India's PLI scheme corridors where domestic assembly incentives attract OEM partnerships for Gujarat refinery expansions. Target California and Texas water utilities with subscription-based monitoring services that bypass capital budget constraints. Deploy direct sales teams to municipal operators rather than competing through established distributor markups. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors lifecycle service specialists with deep calibration capabilities over diversified automation conglomerates facing portfolio complexity drag. Five-to-ten year viability hinges on AI Act compliance roadmaps and cloud-native diagnostic integration. Watch for inflection signals in hydrogen economy infrastructure procurement for 700 bar pressure transmitters at German electrolyzer facilities.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Diagnostics Integration | Azure IoT and AWS Greengrass integrations enable subscription revenue streams that bypass distributor markups. |
| Backward Integration into Sensor Elements | In-house piezoelectric element production reduces Taiwan foundry dependency and compresses lead times. |
| Cybersecurity Certification Investment | IEC 62443 compliance creates development barriers that filter smaller competitors from connected device tenders. |
| Hydrogen Economy Product Line Expansion | 700 bar pressure transmitter qualification opens German electrolyzer and storage facility procurement channels. |
| Asset-as-a-Service Contracting | Guaranteed uptime SLAs with California and Texas water utilities convert capital purchases to recurring revenue. |
Methodological Framework
A standing panel of plant engineers, maintenance directors, OEM procurement managers, and aftermarket service heads provided ongoing calibration across primary interview programs. Secondary validation drew from OSHA enforcement databases, ATEX certification registries, SEC 10-K filings of listed automation suppliers, and customs trade data for transmitter component flows. Bottom-up unit economics triangulated against top-down energy sector capex forecasts to anchor volume assumptions.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specifying year-end points. Segmentation modeling spanned product type, communication architecture, end-use industry, and regional regulatory cluster dimensions. CAGRs derived from installed base replacement cycles, greenfield project pipelines, and technology substitution curves for wireless versus wired protocols. Hydrogen infrastructure buildout timelines and EU AI Act compliance deadlines served as industry-specific demand inputs.
Macroeconomic conditions sit as an overlay; deviation in hydrocarbon capital expenditure cycles, semiconductor fabrication capacity utilization, or European energy transition funding would shift the trajectory. Forecasts reflect documented assumptions regarding wireless protocol adoption rates and certification timeline stability. Quarterly review of OSHA enforcement patterns, ATEX approval backlogs, and Permian Basin drilling permit activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Global Hall Effect Current Sensor Market
Sensors and Controls
Magnetic Sensor Market
Sensors and Controls
Earth and Space Mining Sensors Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Atomic Clock Market
Sensors and Controls
Digital Pump Controller Market
Sensors and Controls
Aspiration Control Systems Market
Sensors and Controls
Magnetometer Market
Sensors and Controls
Sound Sensor Market
Sensors and Controls
Distributed Temperature Sensing Market
Sensors and Controls
Battery Leakage Detection Sensor Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Electronic Differential Control Module Market
Sensors and Controls
Speech Intelligibility Devices Market
Sensors and Controls
MEMS Combo Sensors Market
Sensors and Controls
Europe Advanced CO2 Sensor Market