
 Asia Pacific Fingerprint Sensor Market | 2026-2036
Asia Pacific Fingerprint Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Fingerprint Sensor Market Outlook
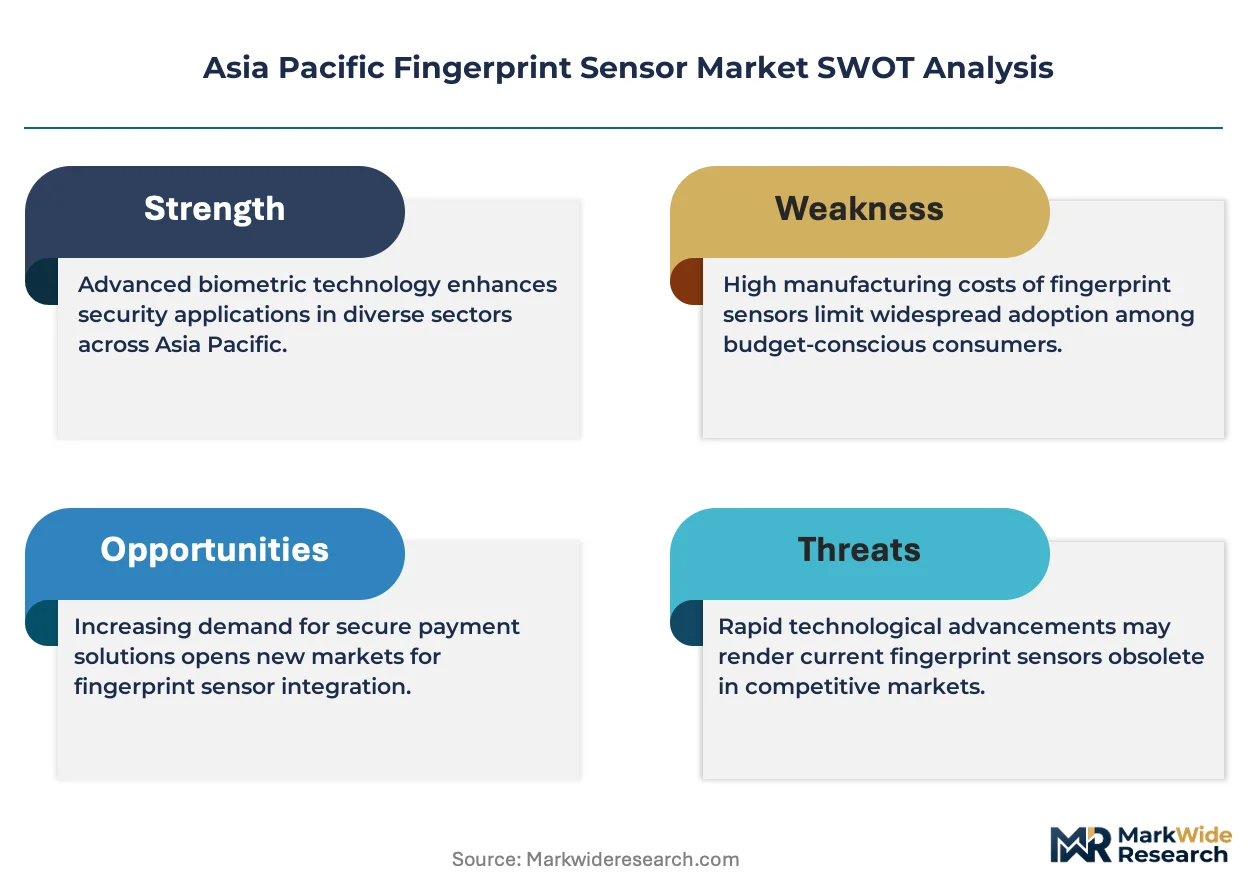
A widening R&D-to-manufacturing capability gap between semiconductor foundry-dependent designers and vertically integrated module houses is unwinding competitive stability across the Asia Pacific fingerprint sensor supply base. Shenzhen Goodix Technology Co. Ltd leverages captive packaging lines to dominate capacitive sensor shipments for Chinese smartphone OEMs. Egis Technology Inc. anchors its position through specialized optical sensor architectures for access control systems. Qualcomm Technologies Inc. competes by extending ultrasonic sensing intellectual property into premium-tier mobile device platforms.
Asia Pacific fingerprint sensors are solid-state or MEMS-based biometric transducers that convert ridge-and-valley skin topography into electrical signals, typically operating at capacitances below 100 femtofarads or acoustic impedances matched to human tissue. These devices authenticate identity for physical and digital access across consumer, enterprise, and government systems. Capacitive sensors retain the largest installed base across mobile devices, though ultrasonic modules are gaining fastest in premium smartphone segments due to wet-finger reliability and under-display compatibility. Optical sensors sustain dominant share in access control and banking applications where large-area acquisition pads remain cost-effective.
China's SAMR enforces GB standards for biometric data security, while India's BIS mandates product certification for imported sensor modules, and South Korea's MFDS regulates healthcare biometric deployments. These frameworks elevate compliance costs for non-domestic suppliers while creating preferential market access for certified local manufacturers. Stakeholders must monitor evolving data-localization requirements and cross-border certification reciprocity agreements as governments tighten sovereignty over biometric databases.
Market Dynamics
Capacitive-to-ultrasonic technology migration is compressing module ASPs while expanding under-display penetration, forcing suppliers to recalibrate foundry partnerships and packaging investments across the Asia Pacific fingerprint sensor value chain.
Growth Catalysts
- India's BIS certification mandates:Import restrictions on uncertified biometric modules accelerate local assembly investments by Chinese and Taiwanese suppliers seeking market access.
- Optical sensor architectures:Large-area acquisition pads sustain cost advantages in banking and access control deployments across Southeast Asian commercial real estate.
- Guangdong province clustering:Shenzhen-Dongguan electronics corridors concentrate die-bonding and testing capacity, shortening logistics loops for smartphone OEM procurement.
Market Restraints
- Silicon wafer input volatility:300mm foundry capacity constraints at TSMC and Samsung Foundry extend lead times for capacitive sensor ASICs.
- Single-source packaging concentration:Flip-chip and WLCSP capability concentrates in Taiwanese OSATs, creating supply vulnerability during regional disruptions.
- Moisture sensitivity limitations:Capacitive modules fail reliability thresholds in tropical climates, restricting deployment in Indonesian and Philippine outdoor access systems.
Strategic Opportunities
- Vietnam electronics manufacturing:Samsung and Apple supplier migration creates greenfield demand for localized sensor module assembly and calibration services.
- Healthcare biometric convergence:Patient identification systems in South Korean hospitals integrate fingerprint sensors with EMR platforms under MFDS guidelines.
- Dual-frequency ultrasonic architectures:Qualcomm and domestic Chinese designers converge 3D sensing IP with fingerprint authentication for automotive steering wheel integration.
Industry Challenges
- ASIC-firmware co-design talent scarcity:Mixed-signal design expertise for femtofarad-level capacitance detection concentrates in Shanghai and Hsinchu, constraining second-tier module house expansion.
- Cross-border certification reciprocity gaps:India's BIS and China's SAMR maintain non-mutual recognition frameworks, forcing redundant testing cycles for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Fingerprint Sensor Market |
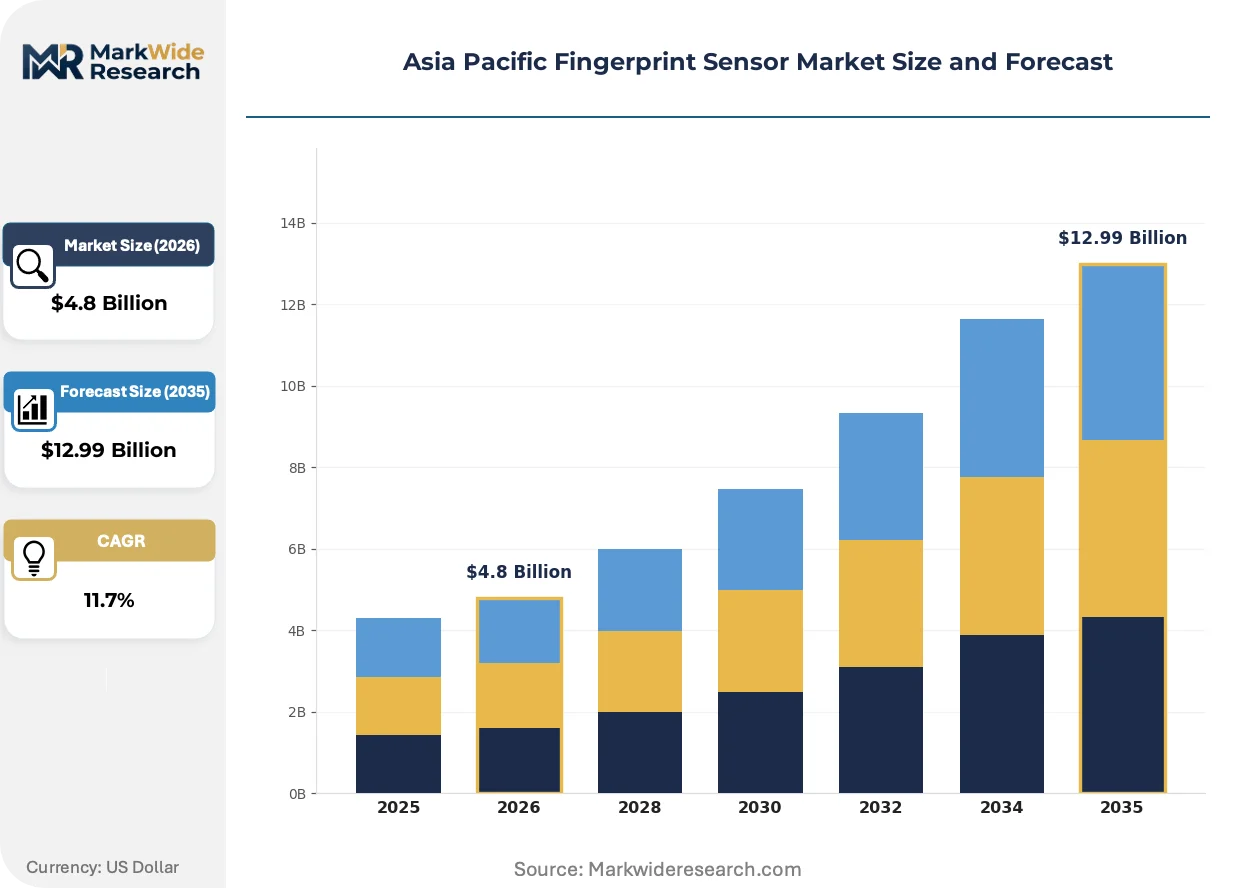
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical, Capacitive, Ultrasonic, Thermal Application: Mobile Devices, Access Control, Banking, Automotive End User: Consumer Electronics, Government, Financial Services, Healthcare Integration Level: Standalone, Integrated, Embedded, Biometric Systems |
| Companies Covered | Shenzhen Goodix Technology Co. Ltd, Egis Technology Inc., Qualcomm Technologies Inc., TDK Corporation, Fingerprint Cards AB, Synaptics Incorporated, Suprema Inc., NEC Corporation, CrucialTec Co. Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Fingerprint Sensor Market Strategic Shifts
Sensor modality competition is restructuring procurement priorities across mobile, automotive, and enterprise verticals, with performance specifications diverging sharply between cost-optimized and premium-tier deployment contexts.
Ultrasonic fingerprint sensing is bifurcating the premium smartphone segment from mid-tier capacitive dominance. Piezoelectric transducer arrays operating at 20-40 MHz penetrate under-display glass stacks up to 2mm thickness. Chinese flagship OEMs in the 4,000-6,000 RMB tier adopt Qualcomm's 3D Sonic Max architecture, compressing optical under-display alternatives into sub-2,500 RMB price bands.
China's SAMR enforcement of GB/T 35273 biometric data security standards is elevating encryption requirements for sensor-to-host communication. Module suppliers must implement AES-256 secure elements and localized template storage, increasing BOM costs by 8-12% for non-compliant legacy designs. Premium smartphone OEMs absorb these costs; access control manufacturers delay product refreshes pending certification clarity.
Enterprise procurement patterns are consolidating around integrated biometric-identity platforms rather than discrete sensor transactions. Banking and facility security buyers in Australia and Singapore bundle fingerprint modules with cloud-based authentication APIs, displacing standalone hardware distributors. Channel restructuring concentrates volume through systems integrators such as NEC and Idemia, compressing margins for component-only suppliers serving these markets.
Asia Pacific Fingerprint Sensor Market Segmentation
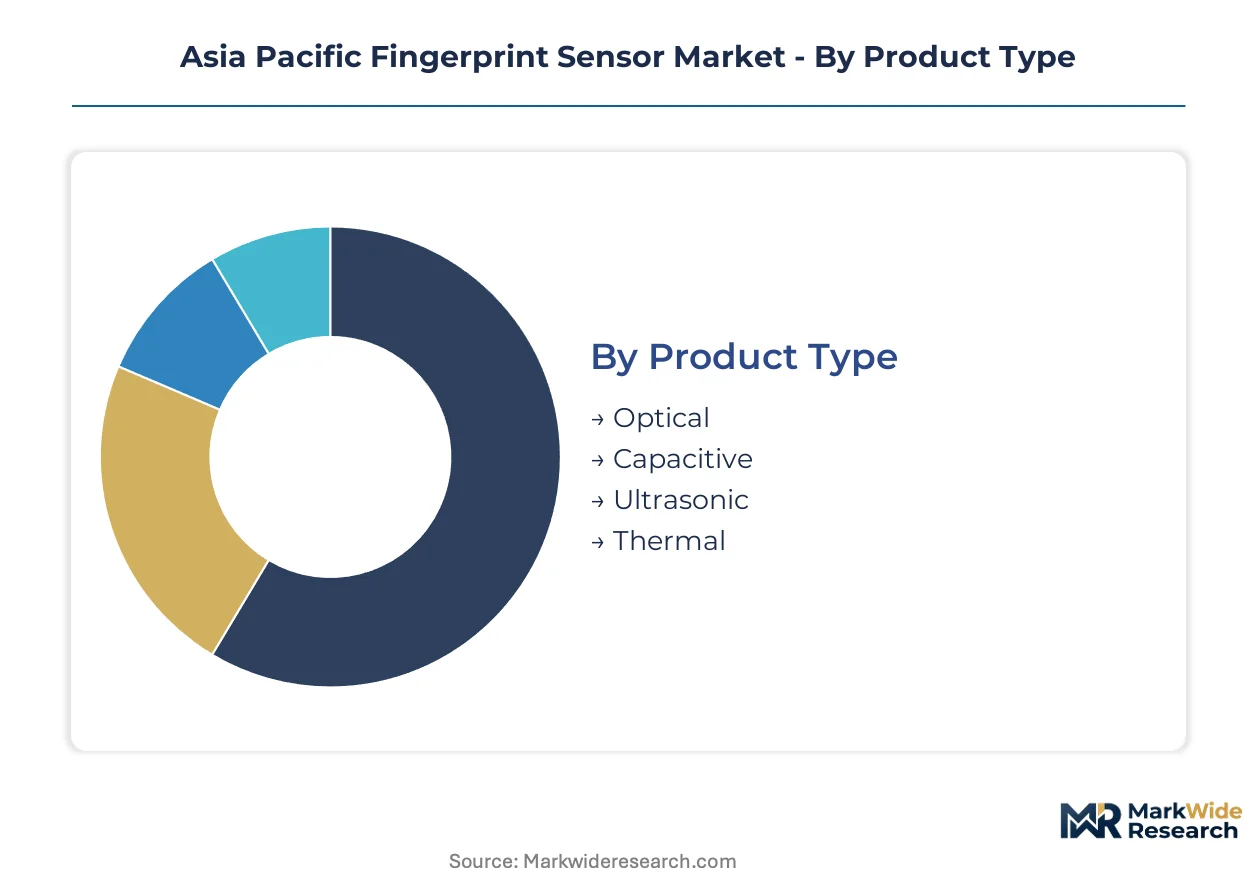
Technology modality and integration depth determine procurement channel structures across the Asia Pacific fingerprint sensor supply base. Suppliers calibrate foundry partnerships and packaging investments based on which segments flow through smartphone OEM direct sourcing versus security systems integrators.
Product Type:
Channel mix splits sharply between mobile device OEM direct procurement and security systems distribution, with capacitive and ultrasonic modules dominating smartphone supply chains while optical sensors flow through access control integrators.
- Capacitive:Solid-state sensors detect ridge-valley topography through sub-100 femtofarad capacitance variations. China's Guangdong province concentrates die-bonding capacity for these modules, with wet-finger reliability limitations restricting outdoor deployment in Indonesia and the Philippines.
- Ultrasonic:Piezoelectric transducer arrays operating at 20-40 MHz penetrate under-display glass stacks up to 2mm thickness. South Korean and Chinese flagship smartphone OEMs in premium tiers drive fastest adoption due to wet-finger performance and under-display compatibility.
- Optical:Large-area acquisition pads using CMOS image sensors dominate banking and commercial access control installations across Southeast Asian real estate developments.
- Thermal:Pyroelectric arrays measuring heat differential between ridges and valleys serve specialized forensic and high-security government applications with limited commercial scale.
Capacitive sensors dominate installed base across mobile devices. Ultrasonic modules are where expansion concentrates in premium smartphone segments.
Application:
Volume concentration versus margin structure varies sharply by application, with mobile devices driving scale economies and automotive steering wheel integration commanding engineering premiums.
- Mobile Devices:Smartphone OEMs in India and China account for dominant procurement volume, with under-display integration requirements forcing sensor-to-display stack co-design. Qualcomm's 3D Sonic Max architecture penetrates 4,000-6,000 RMB flagship tiers.
- Access Control:Commercial real estate and facility security deployments across Australia and Singapore sustain optical sensor demand through systems integrators bundling hardware with cloud authentication APIs.
- Banking:ATM and branch authentication systems in India and Southeast Asia require BIS-certified modules with localized template storage under tightening data localization mandates.
- Automotive:Dual-frequency ultrasonic architectures for steering wheel biometric integration emerge in South Korean and Chinese electric vehicle platforms, converging 3D sensing with driver identification.
Mobile devices anchor procurement volume. Automotive applications are climbing the fastest as human-machine interface security requirements harden.
End User:
Compliance burden and certification reciprocity shape supplier economics across end user categories, with government and healthcare deployments imposing steepest regulatory barriers.
- Consumer Electronics:Smartphone, tablet, and wearable OEMs in China and India drive dominant volume, absorbing GB standards and BIS certification costs into premium tier pricing.
- Financial Services:Banks and payment processors across Singapore, Australia, and Hong Kong demand AES-256 encryption and localized template storage, elevating module BOM costs.
- Government:National ID and border control systems impose stringent data sovereignty requirements, with India's BIS and China's SAMR maintaining non-mutual recognition frameworks forcing redundant testing.
- Healthcare:South Korean hospitals integrate fingerprint sensors with EMR platforms under MFDS guidelines, creating specialized demand for patient identification systems.
Consumer electronics dominates shipment volume. Healthcare is gaining share fastest as biometric-EMR convergence accelerates under clinical data protection frameworks.
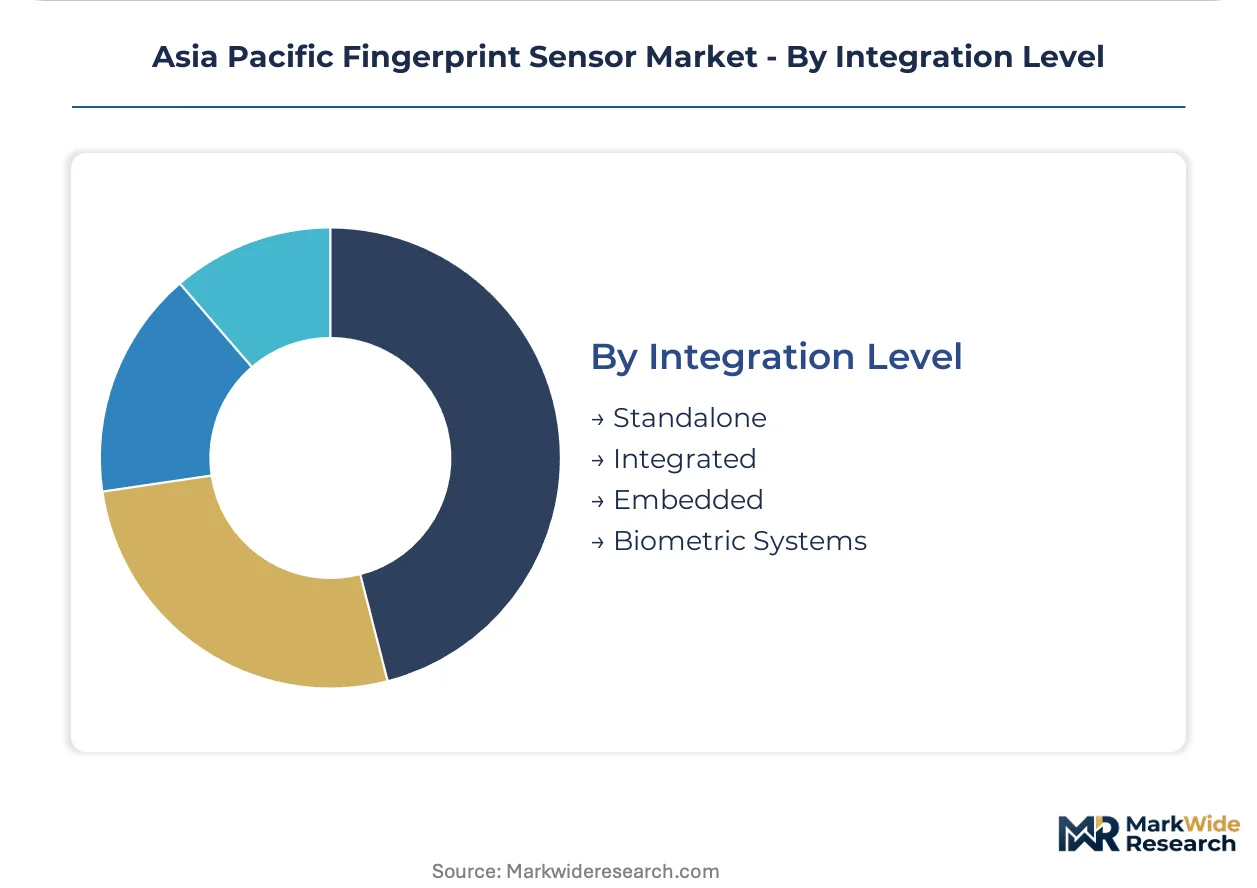
Integration Level:
Supply chain configuration and customer technical capability determine integration preference, with embedded modules concentrating in vertically integrated OEMs and standalone sensors serving retrofit markets.
- Embedded:Die-level integration into smartphone application processors and display driver ICs dominates Chinese flagship OEM procurement, requiring ASIC-firmware co-design expertise concentrated in Shanghai and Hsinchu.
- Integrated:Module-level packaging with secure elements and antennae serves mid-tier smartphone manufacturers and automotive Tier 1s seeking reduced design complexity.
- Standalone:Discrete USB and serial-interface sensors sustain aftermarket and retrofit demand across Southeast Asian small-business access control installations.
- Biometric Systems:Complete enrollment-capture-match subsystems bundle software, hardware, and cloud APIs, consolidating procurement through NEC and Idemia for Australian and Singaporean enterprise buyers.
Embedded modules dominate value concentration in premium mobile devices. Biometric systems are expanding most quickly as enterprise procurement shifts toward integrated identity platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across the Asia Pacific fingerprint sensor market. Indian and Southeast Asian buyers prioritize certified low-cost capacitive modules, while South Korean and Australian healthcare and automotive procurement absorbs premium ultrasonic pricing.
China
Guangdong province anchors sensor die-bonding and testing capacity, with Shenzhen-Dongguan corridors shortening logistics loops for domestic smartphone OEMs. SAMR enforces GB/T 35273 biometric data security standards, elevating AES-256 encryption requirements for sensor-to-host communication. Shanghai and Hsinchu concentrate ASIC-firmware co-design expertise for femtofarad-level capacitance detection.
India
Smartphone manufacturers in Karnataka state drive dominant procurement volume for under-display integration. BIS certification mandates restrict uncertified biometric module imports, accelerating local assembly investments by Chinese and Taiwanese suppliers. Electronics manufacturing clusters in Tamil Nadu and Telangana expand sensor calibration and testing operations to satisfy compliance requirements.
South Korea
Flagship smartphone OEMs and electric vehicle platforms drive fastest ultrasonic adoption for wet-finger reliability and steering wheel biometric integration. MFDS regulates healthcare biometric deployments, creating specialized demand for patient identification systems in Seoul Capital Area hospitals. Busan-Ulsan automotive corridors pilot dual-frequency ultrasonic architectures converging 3D sensing with driver identification.
Australia
Enterprise banking and facility security buyers in Sydney and Melbourne consolidate procurement around integrated biometric-identity platforms. Systems integrators bundle fingerprint modules with cloud-based authentication APIs, displacing standalone hardware distributors. AES-256 encryption and localized template storage requirements elevate module BOM costs for financial services deployments.
Vietnam
Samsung and Apple supplier migration creates greenfield demand for localized sensor module assembly and calibration services. Northern industrial provinces attract Chinese and Taiwanese packaging houses seeking tariff-advantaged export platforms. Ho Chi Minh City corridors develop testing capacity to serve Southeast Asian access control retrofit markets.
Asia Pacific Fingerprint Sensor Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the Asia Pacific fingerprint sensor supply base. Vertically integrated module houses with captive packaging lines dominate high-volume capacitive shipments, while semiconductor foundry-dependent designers compete on ultrasonic and optical architecture specialization. Three archetypes define competitive positioning: captive-packaging specialists, fabless IP licensors, and systems integrators bundling hardware with software platforms. M&A activity concentrates in packaging capacity acquisitions, while strategic partnerships proliferate around ASIC-foundry alliances and cross-border certification reciprocity.
Within the captive-packaging tier, Shenzhen Goodix Technology Co. Ltd exemplifies vertical integration into module assembly, leveraging Guangdong province clustering to compress logistics loops for Chinese smartphone OEMs. Egis Technology Inc. and Qualcomm Technologies Inc. occupy positions on the fabless-specialist vector, with the former representing optical architecture expertise for access control systems and the latter anchoring ultrasonic IP extension into premium-tier mobile platforms. These three companies illustrate how supplier economics diverge between cost-optimized scale production and performance-driven premium positioning.
| Leading Market Players |
|---|
| Shenzhen Goodix Technology Co. Ltd |
| Egis Technology Inc. |
| Qualcomm Technologies Inc. |
| TDK Corporation |
| Fingerprint Cards AB |
| Synaptics Incorporated |
| Suprema Inc. |
| NEC Corporation |
| CrucialTec Co. Ltd |
| Others |
Value Chain & Pricing Dynamics
Long-term capacity reservation contracts with Taiwanese OSATs lock in flip-chip and WLCSP packaging access while capping module ASP erosion for Chinese smartphone OEMs. These arrangements tether sensor designers to fixed-volume commitments through 2027, compressing flexibility for second-tier suppliers competing on spot-market silicon.
Pricing Analysis
After-sales calibration and firmware update subscriptions drive lifetime value for embedded module suppliers serving automotive Tier 1s. Pricing stratifies across premium ultrasonic, standard optical, and economy capacitive tiers, with AES-256 encryption compliance adding 8-12% BOM premiums for banking deployments. Cost compression in mid-tier capacitive modules intensifies as Guangdong packaging houses expand die-bonding capacity. Indian BIS-certified suppliers absorb compliance costs into premium pricing; uncertified imports face margin-crushing retesting cycles.
Supply Chain Analysis
Just-in-time inventory preferences dominate smartphone OEM procurement, though automotive steering wheel integrators maintain strategic stockpiles of ultrasonic ASICs given 300mm foundry capacity constraints. Supply concentrates in Taiwan, China, and South Korea, with silicon wafer inputs and piezoelectric transducer materials anchoring cost structures. Single-source packaging vulnerability at Taiwanese OSATs creates tariff-exposure risk during regional disruptions. Distribution runs through Shenzhen-Dongguan corridors for mobile devices and Singapore-based systems integrators for enterprise access control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by smartphone inventory destocking, with ultrasonic penetration in premium tiers signaling renewed capital deployment.
For Market Incumbents: Secure captive packaging capacity in Vietnam and India to preempt tariff escalation and BIS localization mandates. Defend against fabless ultrasonic specialists by deepening ASIC-foundry alliances with Samsung Foundry and SMIC. Reinforce channel control through direct OEM co-design relationships for under-display stack integration. For New Entrants and Emerging Players: Post-certification technical support gaps in Indonesian and Philippine outdoor access systems offer service-layer entry points. Target Vietnam's northern industrial provinces for greenfield module assembly serving Samsung and Apple supplier ecosystems. Pursue white-label partnerships with Chinese capacitive designers seeking ASEAN tariff-advantaged export platforms. For Investors and Strategic Acquirers: The market sits at a capacity-expansion phase that favors packaging-specialist acquisitions over fabless IP plays. Long-term viability hinges on regulatory reciprocity resolution between India's BIS and China's SAMR. Watch cross-border certification mutual recognition agreements as the inflection signal for consolidated supplier economics.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Packaging Capacity Expansion | Vietnam and India assembly investments satisfy BIS mandates and tariff-advantaged export requirements for Chinese designers. |
| ASIC-Foundry Alliance Formation | Samsung Foundry and SMIC partnerships secure 300mm wafer allocation for ultrasonic sensor designers competing in premium tiers. |
| Certification Reciprocity Negotiation | BIS-SAMR mutual recognition frameworks would eliminate redundant testing costs for suppliers serving both India and China. |
| Dual-Frequency Ultrasonic R&D | Converging fingerprint authentication with 3D sensing IP targets automotive steering wheel integration in South Korean EV platforms. |
| Healthcare Biometric Platform Integration | MFDS-compliant patient identification systems in Seoul hospitals create specialized demand for EMR-converged sensor deployments. |
Study Parameters
A spread of perspectives from smartphone OEM procurement managers, OSAT operations directors, biometric systems integrators, and BIS certification consultants converged on the working assumptions. Primary interviews combined with secondary validation against SAMR enforcement notices, BIS product registry databases, and TSMC capacity allocation disclosures. Bottom-up module shipment tallies triangulated against top-down smartphone production forecasts from IHS Markit and Counterpoint Research.
Technology modality, application vertical, integration level, and end-user compliance burden formed the segmentation dimensions modeled across the analysis window. CAGRs derived from unit shipment trajectories and module ASP erosion curves, with foundry capacity utilization and certification timeline assumptions feeding the analytical framework. Regional price sensitivity differentials and encryption compliance cost pass-through rates served as industry-specific forecast inputs.
Underlying assumptions cover stable India-China trade relations and continued ultrasonic yield improvements at Samsung Foundry, with deviation risk concentrated in regulatory reciprocity failures and 300mm wafer supply disruptions. Revision becomes warranted when BIS-SAMR mutual recognition crosses implementation thresholds or when automotive steering wheel biometric mandates accelerate beyond current MFDS guidance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
GPS Tracking Device Market
Sensors and Controls
Europe Pressure Sensors Market
Sensors and Controls
Control Network Modules Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Barometer Market
Sensors and Controls
ADAS Sensors Market
Sensors and Controls
Europe Acoustic Sensors Market
Sensors and Controls
Capacitive Ceramic Pressure Sensors Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
CO Gas Sensors Market
Sensors and Controls
MEMS Microphones Market
Sensors and Controls
Gyroscope Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Rangefinder Market
Sensors and Controls
Safety Laser Scanner Market