
 Europe Sensors Market | 2026-2036
Europe Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sensors Market Insights
CE marking under the EU Machinery Directive is rotating vendor eligibility across the Europe Sensors Market, forcing non-compliant suppliers out of industrial automation procurement channels. Infineon Technologies AG leverages its MEMS fabrication scale in Germany to dominate automotive pressure sensing for electric powertrains. TE Connectivity Ltd anchors transducer supply for aerospace and medical device OEMs through vertically integrated ceramic substrate production. NXP Semiconductors NV differentiates its portfolio by embedding AI-ready edge processing into automotive radar and lidar modules.
A sensor converts physical stimuli—temperature, pressure, proximity, or humidity—into measurable electrical signals through piezoelectric, capacitive, or resistive transduction mechanisms, typically operating across ranges from -40°C to 150°C with millisecond response times for closed-loop industrial control. Pressure sensors and proximity sensors command the largest revenue share within product type segments, reflecting their embedded role in automotive safety systems and robotic assembly lines. Smart sensors and wireless sensors represent the fastest-expanding technology categories, as edge-computing architectures and Industry 4.0 retrofit cycles displace legacy analog instrumentation across European factory floors.
REACH enforcement by ECHA and the EU AI Act's risk-classification framework are tightening material disclosure and algorithmic transparency requirements for sensor-enabled autonomous systems. The EU Green Deal's carbon-border adjustments are redirecting procurement toward suppliers with verified lifecycle emissions data. Stakeholders must monitor how EFSA and national metrology institutes recalibrate certification timelines for next-generation biometric and environmental monitoring applications.
Market Dynamics
Automotive electrification programs across Germany and France are accelerating demand for pressure and temperature sensing modules, while REACH compliance requirements and the EU Green Deal's decarbonization mandates reshape material specifications and supplier qualification protocols.
Growth Catalysts
- Automotive Electrification:Electric powertrain architectures require multi-point thermal monitoring and battery management sensors, driving procurement volumes for pressure and temperature modules across German and French OEM supply chains.
- EU Green Deal Carbon-Border Adjustments:Verified lifecycle emissions data is becoming a procurement gate, redirecting sensor sourcing toward suppliers with transparent supply chain carbon accounting.
- Industry 4.0 Retrofit Cycles:Edge-computing architectures are displacing legacy analog instrumentation across European factory floors, creating replacement demand for smart and wireless sensor categories.
Market Restraints
- Raw Material Concentration:Rare earth elements and specialized ceramics for MEMS substrates concentrate in limited supplier geographies, exposing European fabricators to input cost volatility and supply disruption.
- CE Marking Compliance Friction:The EU Machinery Directive's rotating vendor eligibility requirements force non-compliant suppliers out of industrial automation procurement channels, narrowing the qualified vendor base.
- Technical Limitation in Harsh Environments:Standard sensing elements face reliability degradation beyond 150°C operating thresholds, constraining deployment in high-temperature automotive powertrain zones.
Strategic Opportunities
- Eastern European Manufacturing Expansion:Poland and Czech Republic industrial corridors present underpenetrated demand for factory automation sensors as automotive and electronics OEMs diversify production footprint.
- EU AI Act Risk-Classification Framework:Algorithmic transparency mandates for autonomous systems create certification service opportunities and premium positioning for sensor vendors with embedded edge-processing capabilities.
- Wireless-Edge Convergence:Integration of LoRaWAN and 5G-RedCap connectivity with on-sensor inference engines opens retrofit applications in legacy industrial infrastructure without control system replacement.
Industry Challenges
- Metrology Calibration Backlogs:National metrology institutes across Germany, France, and Italy face extended recertification timelines for next-generation biometric and environmental monitoring applications, delaying product launches.
- Legacy System Integration Complexity:Analog-to-digital interface mismatches between smart sensors and existing PLC architectures in brownfield industrial sites require costly middleware development and field engineering.
- REACH Material Disclosure Burden:ECHA enforcement of substance-of-very-high-concern reporting imposes documentation overhead on sensor manufacturers with complex multi-tier supply chains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sensors Market |
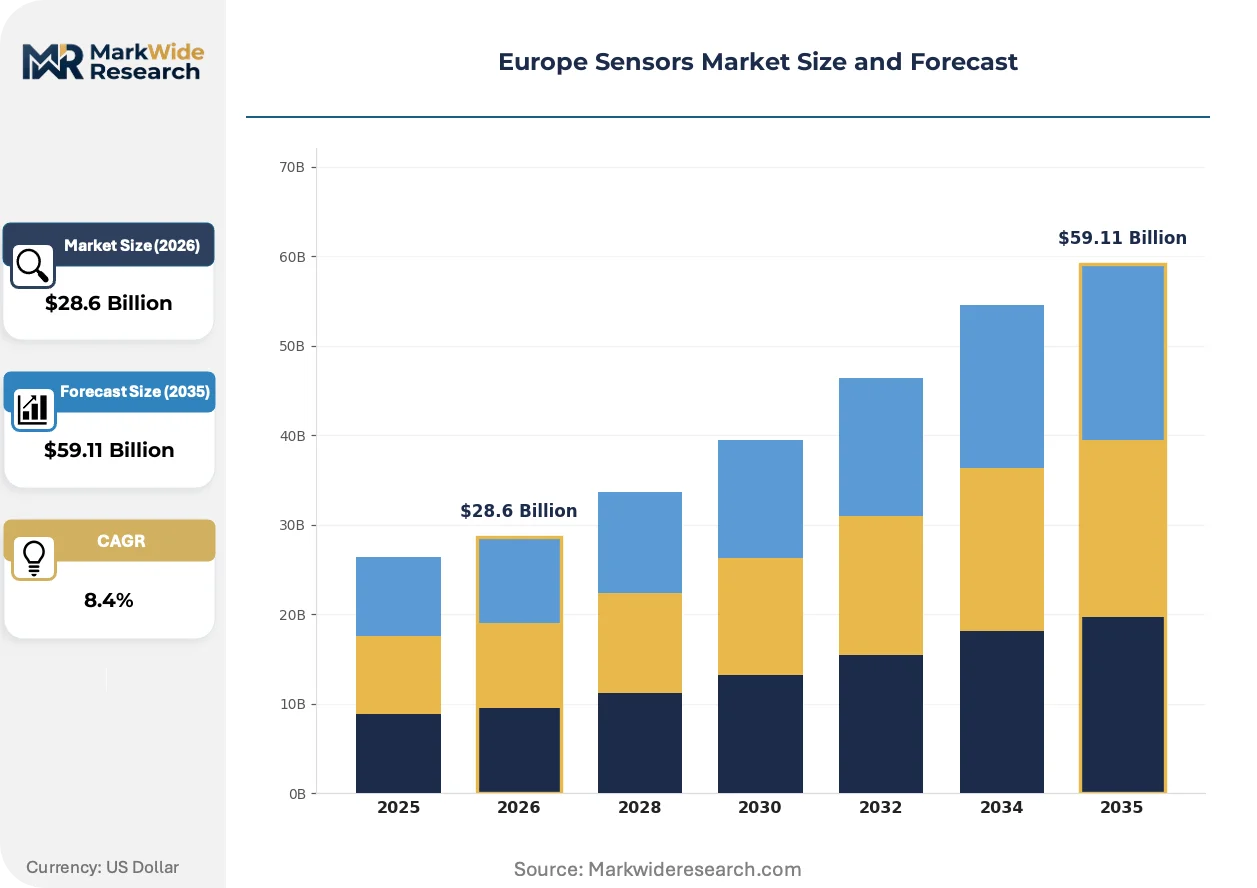
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperature Sensors, Pressure Sensors, Proximity Sensors, Humidity Sensors Technology: Analog Sensors, Digital Sensors, Smart Sensors, Wireless Sensors End User: Automotive Industry, Industrial Automation, Healthcare Sector, Consumer Electronics Application: Monitoring Systems, Control Systems, Safety Systems, Environmental Monitoring |
| Companies Covered | TE Connectivity Ltd, NXP Semiconductors NV, Infineon Technologies AG, Texas Instruments Incorporated, Robert Bosch GmbH, Siemens AG, Honeywell International Inc., ABB Limited, STMicroelectronics NV, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sensors Market Trends and Innovations
Edge-computing architectures are decomposing traditional sensor-processor boundaries, while regulatory mandates on algorithmic transparency and carbon accountability reconfigure vendor qualification criteria.
MEMS-based pressure sensing is decomposing conventional piezoelectric transducer architectures in automotive powertrain applications. German OEMs are adopting these modules at compressed development cycles for electric vehicle thermal management. The technology is decomposing legacy supply relationships as foundry-scale producers capture design-in decisions previously held by discrete component specialists.
REACH enforcement by ECHA is tightening material disclosure requirements for sensor-enabled autonomous systems. Industrial consequence includes mandatory substance-of-very-high-concern reporting across multi-tier supply chains. Automotive and medical device segments are responding by qualifying alternative substrate materials and captive ceramic production to maintain market access.
Buying organizations are consolidating sensor procurement under category-management functions with lifecycle-cost evaluation criteria. Industrial automation distributors face margin compression as direct OEM-vendor frameworks displace traditional channel relationships. This pattern is most visible in Germany's industrial corridor, where Siemens AG and Robert Bosch GmbH anchor consolidated sensor procurement for factory automation programs.
Europe Sensors Market Segmentation
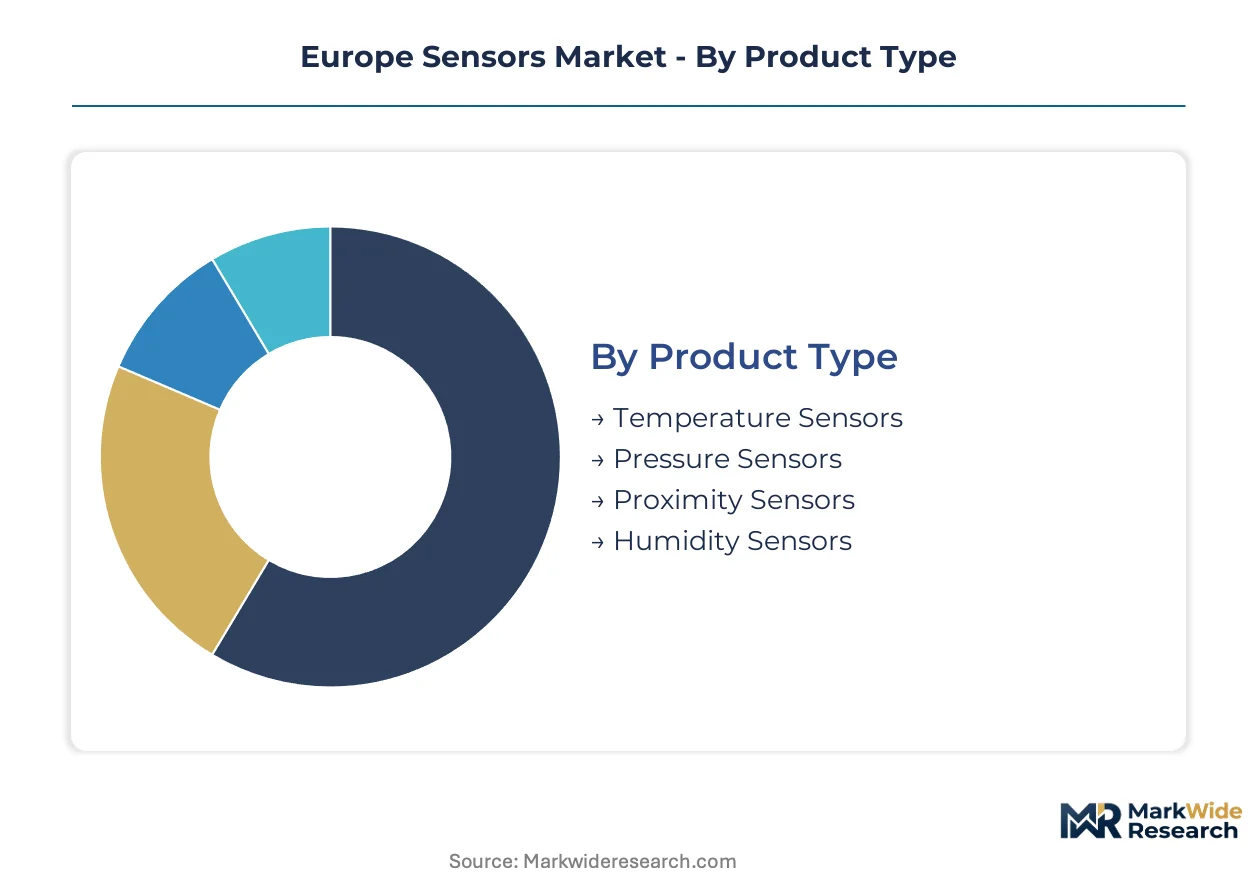
Sensor procurement across Europe fragments along technical capability, connectivity architecture, and end-use certification requirements. Understanding where margin pools concentrate within each dimension reveals which specifications command premium positioning versus commodity pricing.
Product Type:
Pressure and temperature modules capture the deepest margin pools, driven by automotive electrification mandates and REACH-compliant material specifications.
- Pressure Sensors:Piezoelectric and capacitive transduction elements convert mechanical stress into electrical signals across -40°C to 150°C operating ranges. German and French OEM procurement for electric powertrain thermal management is concentrating demand for multi-point monitoring modules.
- Proximity Sensors:Inductive and photoelectric variants detect object presence without physical contact, enabling robotic assembly line positioning. Industrial automation retrofit cycles across Germany's industrial corridor are displacing legacy mechanical limit switches.
- Temperature Sensors:Thermocouple and RTD architectures provide millisecond response times for closed-loop industrial control.
- Humidity Sensors:Capacitive polymer and resistive ceramic elements measure moisture levels for HVAC and environmental monitoring.
The dominant share belongs to pressure sensors, while proximity sensors are closing the gap fastest through Industry 4.0 deployment.
Technology:
Smart and wireless variants command pricing premiums as edge-computing architectures displace legacy analog instrumentation.
- Smart Sensors:Embedded microprocessors enable on-device signal conditioning and diagnostic capabilities. Factory automation programs in Germany require AI-ready edge processing for predictive maintenance applications.
- Wireless Sensors:LoRaWAN and 5G-RedCap connectivity eliminates cabling infrastructure in brownfield industrial sites. Poland and Czech Republic manufacturing corridors present underpenetrated demand for retrofit deployments without PLC replacement.
- Digital Sensors:Direct binary output interfaces simplify microcontroller integration for consumer electronics.
- Analog Sensors:Continuous voltage or current outputs persist in legacy industrial control systems.
Smart sensors hold the revenue lead, with wireless sensors expanding most quickly through retrofit-friendly connectivity protocols.
End User:
Automotive and industrial automation segments concentrate procurement volumes, while healthcare commands the steepest certification premiums.
- Automotive Industry:Battery management systems and electric powertrain architectures require multi-point thermal and pressure monitoring. ECHA REACH enforcement and CE marking under the EU Machinery Directive are rotating vendor eligibility for German and French OEM supply chains.
- Industrial Automation:Robotic assembly lines and process control systems demand millisecond-response sensing for closed-loop operation. Siemens AG and Robert Bosch GmbH anchor consolidated procurement for factory automation programs.
- Healthcare Sector:Biometric and patient monitoring applications face extended recertification timelines from Germany's national metrology institute.
- Consumer Electronics:Miniaturized MEMS devices enable smartphone and wearable device functionality.
Automotive procurement generates the largest revenue base, though healthcare is gaining share fastest through MDR compliance requirements.
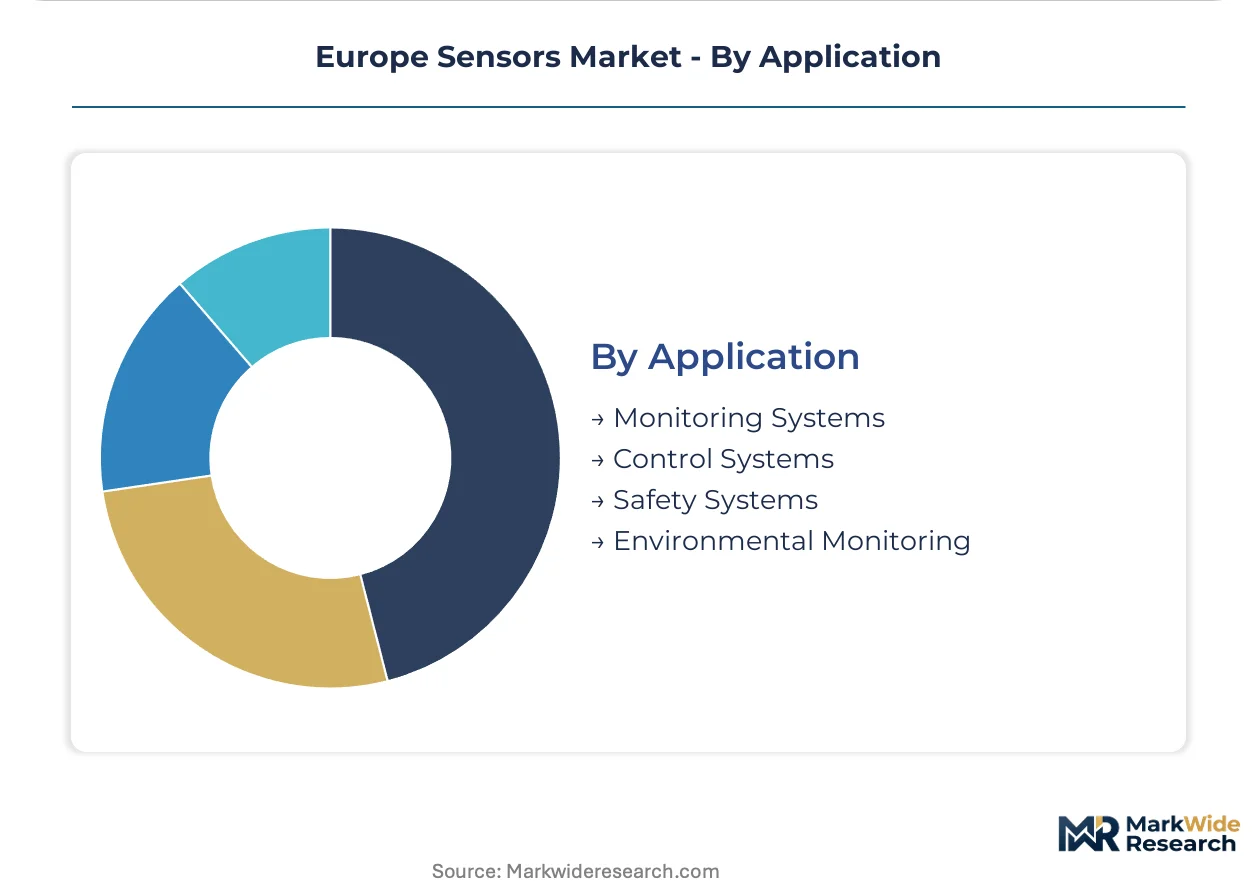
Application:
Safety and control system deployments concentrate in regulated industries where CE marking and EU AI Act risk-classification create procurement gates.
- Safety Systems:Redundant sensing architectures prevent hazardous conditions in automotive and industrial environments. The EU AI Act's algorithmic transparency mandates are tightening qualification protocols for autonomous system sensors.
- Control Systems:Real-time feedback loops regulate process variables in manufacturing and power generation. Analog-to-digital interface mismatches with existing PLC architectures create middleware development costs in brownfield sites.
- Monitoring Systems:Continuous data acquisition enables predictive maintenance and quality assurance.
- Environmental Monitoring:Air quality and emissions sensing supports EU Green Deal carbon-border adjustment compliance.
Safety systems dominate procurement value, while environmental monitoring is climbing the fastest on decarbonization mandate tailwinds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement concentration across the Europe Sensors Market clusters around automotive OEMs in Germany and France, industrial automation hubs in Central Europe, and emerging manufacturing corridors in Eastern Europe seeking Industry 4.0 retrofit solutions.
Germany
Battery management systems for electric powertrains drive multi-point thermal and pressure sensor procurement from Stuttgart and Munich OEMs. ECHA REACH enforcement mandates substance-of-very-high-concern documentation across multi-tier supply chains. Bavaria's industrial corridor anchors consolidated sensor procurement for factory automation programs led by Siemens AG and Robert Bosch GmbH.
France
Automotive electrification programs from Paris and Lyon manufacturers accelerate demand for MEMS-based pressure sensing modules. CE marking under the EU Machinery Directive rotates vendor eligibility for industrial automation channels. The Auvergne-Rhône-Alpes cluster concentrates aerospace sensor demand through vertically integrated ceramic substrate production.
United Kingdom
Healthcare biometric applications face extended recertification timelines from national metrology institutes. The EU AI Act's risk-classification framework tightens algorithmic transparency requirements for autonomous system sensors. London and Southeast England concentrate procurement for medical device OEMs seeking MDR-compliant sensing architectures.
Italy
Robotic assembly lines across Lombardy and Emilia-Romagna displace legacy mechanical limit switches with photoelectric proximity sensors. The EU Green Deal's carbon-border adjustments redirect sourcing toward suppliers with verified lifecycle emissions data. Milan's industrial automation distributors face margin compression as direct OEM-vendor frameworks consolidate procurement.
Poland
Underpenetrated factory automation demand in Warsaw and Krakow manufacturing corridors creates retrofit opportunities for wireless sensor deployments. LoRaWAN and 5G-RedCap connectivity eliminates cabling infrastructure in brownfield industrial sites without PLC replacement. Eastern European expansion by automotive and electronics OEMs diversifies production footprint and concentrates sensor demand.
Europe Sensors Market Competitive Landscape
Player mix skews toward diversified industrial conglomerates with captive sensor divisions alongside specialized MEMS fabricators and connectivity-focused component suppliers. Market structure exhibits tiered consolidation with premium positioning held by vertically integrated European manufacturers and scale-driven competition from global semiconductor houses. Two strategic archetypes dominate: foundry-scale MEMS producers capturing design-in decisions and connectivity specialists anchoring transducer supply for regulated end-uses. Competitive moves center on backward integration into ceramic substrate production and strategic partnerships for edge-processing capabilities.
Among Germany-based fabricators, Infineon Technologies AG and Robert Bosch GmbH exemplify the vertically integrated archetype with MEMS fabrication scale and captive automotive supply relationships. TE Connectivity Ltd represents the connectivity-specialist position, anchoring transducer supply through substrate production control. NXP Semiconductors NV sits within the semiconductor-scale tier, differentiating through embedded processing capabilities.
| Leading Market Players |
|---|
| TE Connectivity Ltd |
| NXP Semiconductors NV |
| Infineon Technologies AG |
| Texas Instruments Incorporated |
| Robert Bosch GmbH |
| Siemens AG |
| Honeywell International Inc. |
| ABB Limited |
| STMicroelectronics NV |
| Others |
Pricing and Supply Chain Analysis
MEMS fabrication scale replacing discrete piezoelectric transducers is redistributing procurement power toward German and Taiwanese foundry operators while compressing margin pools for component specialists. This substitution dynamic simultaneously concentrates supply geography in Bavarian industrial corridors and forces pricing discipline through volume-scale contract structures.
Pricing Analysis
Cost-plus contracts indexed to rare earth element spot prices dominate procurement between German OEMs and MEMS substrate suppliers. Pricing stratifies across REACH-certified premium tiers, standard CE-marked industrial grades, and economy analog alternatives without embedded processing. Cost compression in economy tiers is intensifying because Eastern European distributors are bypassing traditional channel markups. Automotive OEMs exhibit lowest price sensitivity due to thermal reliability requirements, while consumer electronics procurement teams drive hardest bargain on MEMS miniaturization.
Supply Chain Analysis
Strait of Malacca transit underwrites ceramic substrate feedstock flows from Southeast Asian refineries to German fabrication plants. Supply geography centers on Germany for MEMS design, Taiwan for wafer foundry capacity, and China for rare earth element processing. Raw material dependencies include neodymium for magnetic sensing elements, alumina for ceramic substrates, and palladium for contact plating. Single-source vulnerability concentrates in ECHA-certified precursor chemical supply. Distribution runs through vertically integrated OEM direct frameworks that displace independent distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense against solid-state optical sensing architectures that threaten electromechanical transducer incumbency in automotive safety systems. MEMS vendors must navigate this technology transition while preserving foundry-scale economics.
For Market Incumbents: Compound captive ceramic substrate production to secure REACH-compliant material flows against ECHA disclosure mandates. Deepen backward integration into alumina precursor supply to offset rare earth price volatility. Anchor design-in relationships through embedded AI-ready edge processing that optical substitutes cannot yet replicate at automotive reliability grades. For New Entrants and Emerging Players: Anchor in Polish and Czech industrial corridors where brownfield retrofit demand for wireless sensors outpaces incumbent coverage. Target proximity sensing modules for robotic assembly lines in Warsaw manufacturing zones. Pursue LoRaWAN certification partnerships with industrial automation distributors facing margin compression from direct OEM frameworks. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed connectivity specialists holding aerospace and medical device transducer positions. Five-to-ten year viability hinges on EU AI Act compliance infrastructure and carbon-border adjustment readiness. Watch ECHA substance-of-very-high-concern list revisions as inflection signals for material substitution capex cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Substrates | Captive alumina production secures REACH compliance against ECHA disclosure mandates. |
| Embedded Edge-Processing Development | On-sensor inference engines differentiate automotive radar modules for EU AI Act risk-classification. |
| Eastern European Manufacturing Expansion | Poland and Czech Republic corridors capture underpenetrated wireless sensor retrofit demand. |
| Carbon-Border Adjustment Readiness | Verified lifecycle emissions data preserves German and French OEM procurement access. |
| 5G-RedCap Connectivity Certification | RedCap protocol integration opens brownfield industrial deployments without PLC replacement. |
Research Methodology
A standing panel of MEMS fabrication executives, automotive Tier 1 procurement directors, industrial automation plant engineers, and ECHA regulatory affairs specialists provided ongoing calibration throughout the study period. Primary interview findings triangulated against secondary sources including EU customs trade databases, ECHA substance registration filings, SEC 10-K disclosures from listed component suppliers, and national metrology institute certification timelines. Bottom-up segment sizing across product type, technology, and end-use dimensions validated through top-down production volume reconciliation from German and French automotive registration data.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. Segmentation modeling incorporated pressure transducer specifications, connectivity architecture, certification grade tiers, and regional production cluster dynamics. CAGRs derived from regression analysis of historical procurement volumes correlated with electric vehicle platform rollout schedules and Industry 4.0 retrofit cycle timing. Forecast inputs included battery management system sensor content per vehicle and brownfield automation infrastructure replacement rates.
Decision-makers should treat outputs as directional under base assumptions of sustained EU Green Deal enforcement and REACH compliance continuity; material deviation in ECHA substance restrictions or carbon-border adjustment scope would warrant model refresh. Practitioners should keep alternative scenarios live as MEMS-to-optical substitution rates and Eastern European manufacturing migration patterns evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Nano Radiation Sensors Market
Sensors and Controls
Global Solid State Lidar Sensor Market
Sensors and Controls
Pressure Transmitter Market
Sensors and Controls
Europe Wireless Sensors Market
Sensors and Controls
Europe Human Machine Interface Market
Sensors and Controls
Earthquake Sensor Market
Sensors and Controls
Middle East and Africa Occupancy Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
Asia-Pacific Smart Glove Market
Sensors and Controls
Millimeter Wave Sensors Market
Sensors and Controls
PM2.5 Sensors Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Micro-Electro Mechanical Systems Market
Sensors and Controls
Pressure Monitoring Market
Sensors and Controls
High-End Accelerometer Market
Sensors and Controls
Piezoelectric Sensor Market