
 Corrosion Monitoring Market | 2026-2036
Corrosion Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
Corrosion Monitoring Market Intelligence
The basis of competition is shifting as integrated, real-time wireless systems diverge from lower-cost portable inspection devices. Emerson Electric Co. specializes in advanced wireless sensor networks for complex industrial facilities. In contrast, Bureau Veritas S.A. leverages its extensive service network to offer inspection and certification for pipeline integrity. Baker Hughes Company competes with a focus on ultrasonic and eddy current technologies for the oil and gas sector.
Corrosion monitoring encompasses a set of non-destructive and intrusive techniques used to quantify material degradation, often measured in mils per year. Its primary purpose is to provide data for predictive maintenance, ensuring the structural integrity and safety of critical assets like pipelines and pressure vessels. Ultrasonic and eddy current technologies represent mature segments, while demand for electrochemical noise systems grows for sensitive applications. Oil refining and power generation remain the dominant applications, driving volume for both inline systems and portable devices.
Regulatory frameworks from the U.S. EPA and compliance with the EU’s REACH directive mandate stringent asset integrity management, directly driving adoption. International standards, such as those from ISO, establish benchmarks for the performance and calibration of monitoring technologies. The critical decision for operators now involves transitioning from periodic, compliance-based checks to integrated, predictive analytics platforms for asset lifetime optimization.
Market Dynamics
The market's central dynamic is the transition from periodic, compliance-driven inspections to continuous, data-driven predictive maintenance. This shift is driven by the need for asset lifetime optimization in capital-intensive industries like oil refining and power generation.
Growth Catalysts
- Stringent Regulations:Mandates like the EU's Industrial Emissions Directive compel continuous monitoring in power generation and chemical processing, directly stimulating demand for compliant inline systems.
- Asset Integrity Management:In petrochemical hubs like the U.S. Gulf Coast and Saudi Arabia, operators invest in advanced monitoring to prevent catastrophic failures and ensure the integrity of critical pipelines and pressure vessels.
- Technology Maturation:Electrochemical noise and advanced ultrasonic systems are becoming more accessible, enabling their use for sensitive applications in aerospace and pharmaceutical manufacturing where precise material degradation data is critical.
Market Restraints
- High Capital Outlay:The significant upfront investment required for integrated, real-time wireless sensor networks presents a barrier for operators of smaller or older facilities, particularly for brownfield retrofits.
- Data Interpretation Complexity:Advanced techniques like electrochemical noise generate complex datasets that require specialized materials scientists or data analysts for accurate interpretation, creating a knowledge gap.
- Legacy Method Viability:The continued use of lower-cost, established portable inspection devices for periodic checks can delay investment in more sophisticated, continuous monitoring platforms, slowing market conversion.
Strategic Opportunities
- Renewable Energy Infrastructure:Applying corrosion monitoring to new assets like offshore wind turbine foundations and geothermal plants represents a significant growth vector beyond traditional fossil fuel applications.
- AI and Predictive Analytics:Integrating machine learning algorithms with sensor data offers the potential to create highly accurate predictive models for asset failure, transitioning from monitoring to true prognostics.
- Geographic Expansion:Underpenetrated markets in Southeast Asia, particularly Indonesia and Vietnam, offer substantial opportunities as they expand their oil and gas and chemical processing infrastructure.
Industry Challenges
- Specialized Talent Shortage:A scarcity of technicians and engineers who possess dual expertise in both materials science and data analytics hinders the effective deployment and interpretation of advanced monitoring systems.
- Legacy System Integration:Integrating modern wireless monitoring technologies with older, proprietary distributed control systems (DCS) and SCADA platforms in existing plants is a significant technical hurdle.
- Data Standardization Gaps:The absence of universal data format standards across different vendors' platforms creates interoperability issues, complicating the creation of a unified asset management view for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrosion Monitoring Market |
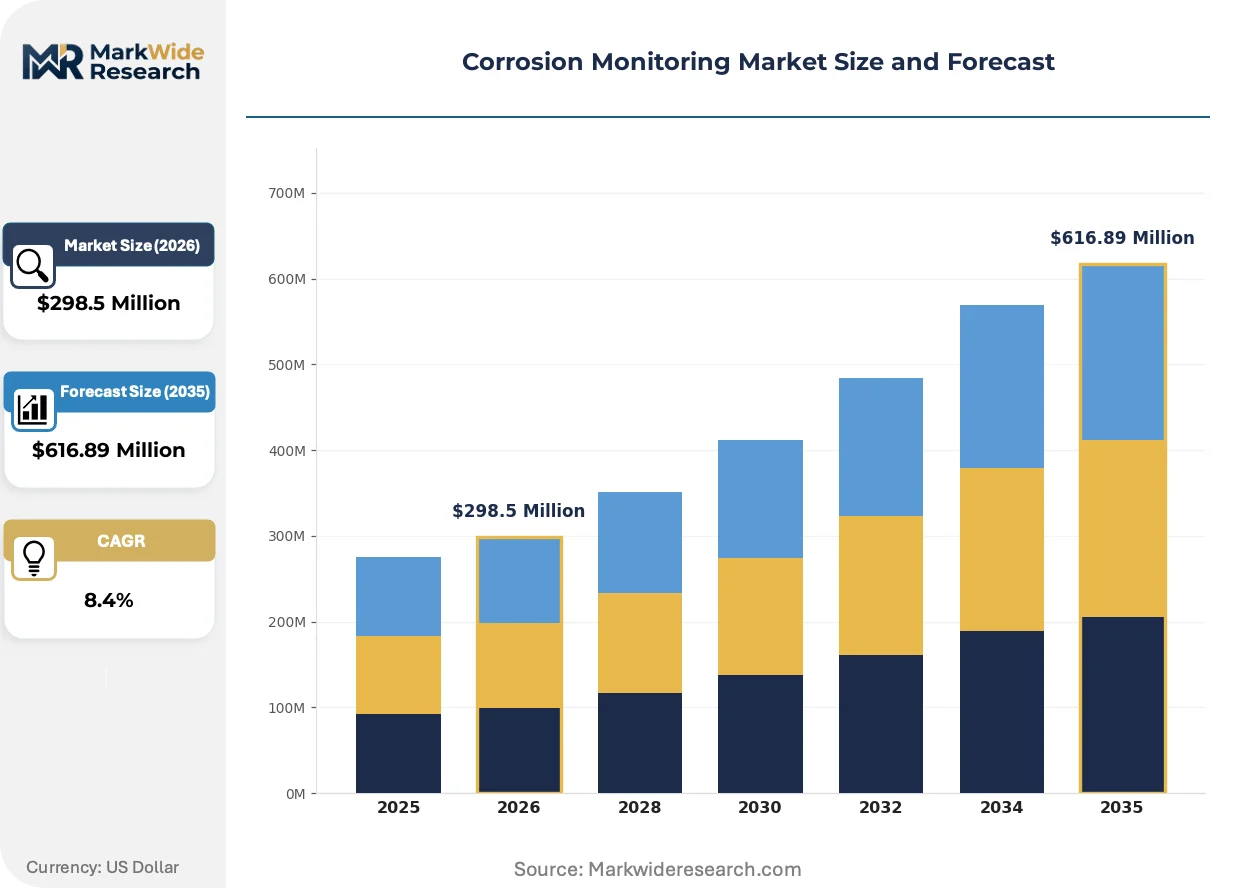
| Market Size in 2026 | $298.5 Million |
| Market Size in 2035 | $616.89 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Eddy Current, Ultrasonic, Electrochemical Noise, Linear Polarization, Weight Loss, Infrared Thermography Application: Oil Refining, Chemical Processing, Marine Operations, Power Generation, Water Treatment, Pipeline Integrity Deployment: Inline Systems, Portable Devices, Remote Monitoring, Wireless Sensors, Fixed Point Monitoring End User: Petrochemical Companies, Energy Producers, Utilities, Research Institutions, EPC Contractors |
| Companies Covered | SGS S.A., Intertek Group plc, Emerson Electric Co., ClampOn AS, Bureau Veritas S.A., Baker Hughes Company, Cosasco Corporation, Corrpro Companies Inc., Honeywell International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrosion Monitoring Market Strategic Shifts & Innovations
The evolution of the market is defined by the integration of sensor data into broader operational intelligence platforms. This transforms corrosion monitoring from a standalone inspection activity into an integral component of predictive asset management and enterprise risk reduction.
Wireless sensor networks (WSNs) combine multiple non-destructive testing techniques, including ultrasonic thickness and electrochemical measurements. Oil refining and chemical processing facilities are the primary adopters, seeking comprehensive real-time data across complex piping and vessel systems. This technology is unifying previously siloed data from periodic inspections and various point sensors into a single, cohesive asset health dashboard.
International standards, particularly ISO guidelines for asset integrity, establish globally recognized benchmarks for technology performance and calibration. This regulatory pressure compels a shift away from proprietary, unverified methods toward certified and traceable measurement systems. The pipeline integrity sector is most affected, as operators in Australia and the Middle East increasingly require ISO compliance to secure project financing and insurance.
A transition from capital expenditure on hardware to subscription-based Monitoring-as-a-Service (MaaS) models is becoming more prevalent. This approach unbundles the cost of sensors, software, and expert analysis, making advanced systems more accessible to mid-sized operators. This model is gaining traction in the North American power generation sector, where utilities seek to reduce operational overhead and transfer technology risk to specialized vendors.
Corrosion Monitoring Market Segmentation
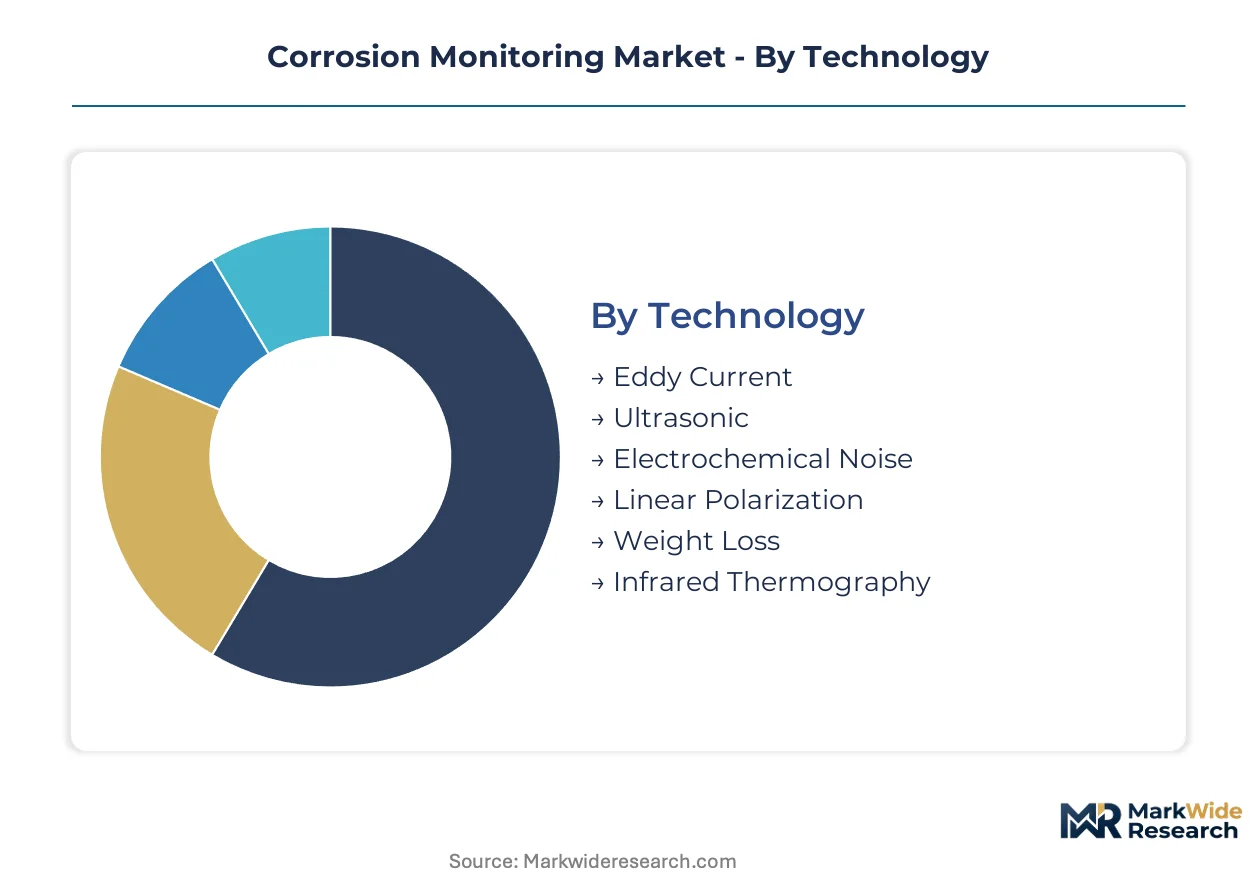
Understanding the market's segmentation reveals the diverse technological approaches and application areas driving adoption of corrosion monitoring solutions. This granular view helps identify specific demand pockets and the competitive dynamics within each sub-segment.
Technology:
Supply concentration in corrosion monitoring technology currently favors established methods, though specialized systems are gaining traction for sensitive applications.
- Ultrasonic:This non-destructive technique measures material thickness and detects internal flaws using high-frequency sound waves. Its demand concentrates in pipeline integrity across the U.S. Gulf Coast, driven by stringent asset integrity regulations.
- Electrochemical Noise:This advanced method detects localized corrosion by measuring spontaneous, low-level fluctuations in current or potential. Its application is expanding in sensitive pharmaceutical manufacturing facilities in Germany, where precise degradation data is critical.
- Eddy Current:This electromagnetic technique detects surface and near-surface flaws in conductive materials, particularly in aerospace components.
- Linear Polarization:This intrusive method measures corrosion rates in conductive liquids by applying a small potential to a probe.
- Weight Loss:This direct measurement technique involves exposing material coupons to a corrosive environment and calculating mass loss over time.
- Infrared Thermography:This non-contact method detects temperature variations indicative of corrosion-related heat changes or material loss.
Today's leader: Ultrasonic. Tomorrow's challenger: Electrochemical Noise.
Application:
The volume of corrosion monitoring applications is heavily influenced by the capital intensity and regulatory scrutiny of various industrial sectors.
- Oil Refining:This sector extensively uses corrosion monitoring for pipelines, heat exchangers, and storage tanks due to aggressive chemical environments. Demand is particularly high in Saudi Arabia, driven by the need to ensure continuous operation and prevent catastrophic failures.
- Power Generation:Critical infrastructure like boilers, turbines, and cooling systems in power plants require continuous monitoring to prevent material degradation. Utilities in the North American market adopt these systems to enhance operational efficiency and comply with environmental mandates.
- Pipeline Integrity:This application focuses on safeguarding extensive pipeline networks against internal and external corrosion, crucial for oil and gas transport.
- Chemical Processing:Facilities handling corrosive chemicals utilize monitoring to protect reactors, tanks, and piping from material degradation.
- Marine Operations:This segment includes ships, offshore platforms, and port infrastructure, demanding robust monitoring for saltwater environments.
- Water Treatment:Monitoring systems prevent corrosion in water distribution networks, purification plants, and wastewater facilities.
Oil refining represents the fastest-growing application segment, while marine operations are steadily gaining market share.
Deployment:
The maturity of deployment solutions spans from established periodic checks to advanced, integrated real-time systems.
- Inline Systems:Permanently installed sensors provide continuous, real-time data directly from process streams or asset surfaces. Their adoption is critical in chemical processing plants in Germany, where continuous process control is mandated by the Industrial Emissions Directive.
- Wireless Sensors:These networks transmit data without physical cabling, enabling flexible installation and remote monitoring in complex facilities. Petrochemical companies on the U.S. Gulf Coast are integrating wireless sensors for comprehensive asset health dashboards.
- Portable Devices:Handheld instruments are used for periodic, on-site inspections by technicians.
- Remote Monitoring:Systems transmit data from distant locations to a central control room, enabling oversight of geographically dispersed assets.
- Fixed Point Monitoring:Sensors are strategically placed at specific locations on assets to track localized corrosion over time.
Continuous monitoring solutions demonstrate the steepest expansion trajectory, displacing traditional portable devices.
End User:
Customer types vary significantly based on their operational scale, regulatory exposure, and technical capabilities.
- Petrochemical Companies:These entities operate large-scale facilities with extensive piping and vessel networks, requiring comprehensive monitoring to manage highly corrosive substances. Major players in the Middle East prioritize advanced systems to ensure asset integrity and operational safety.
- Energy Producers:This segment includes oil and gas exploration and production companies, investing in monitoring solutions for offshore platforms and upstream infrastructure. Companies in Norway implement these technologies to mitigate risks in harsh environments and comply with strict safety standards.
- Utilities:Power generation and water treatment utilities use corrosion monitoring to maintain critical infrastructure and ensure reliable service.
- Research Institutions:Academic and private research bodies utilize monitoring equipment for material science studies and technology development.
- EPC Contractors:Engineering, Procurement, and Construction firms integrate monitoring solutions into new projects and facility upgrades.
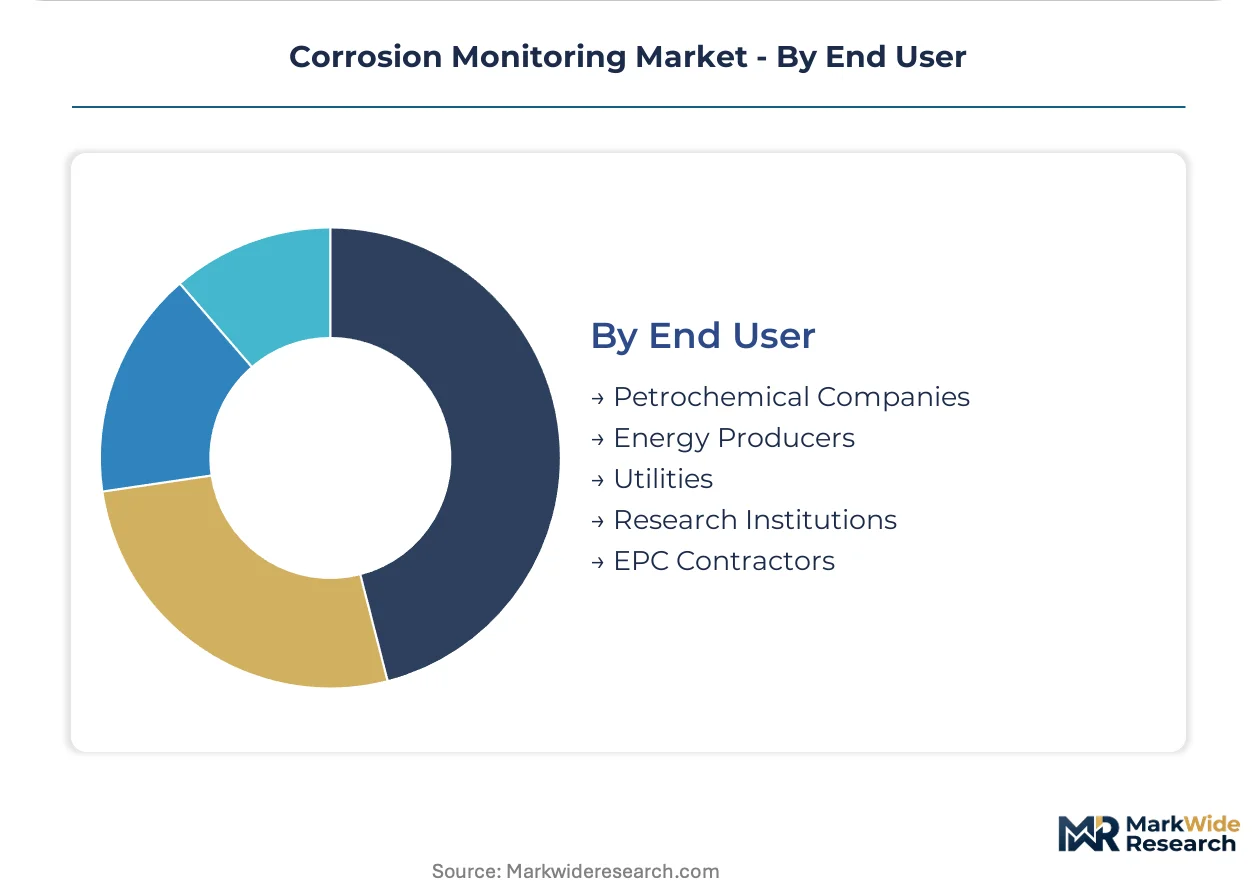
Petrochemical companies drive the largest segment volume, with EPC contractors showing significant procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Highly skilled engineering talent pools in established industrial hubs anchor significant demand for corrosion monitoring solutions. These specialized workforces drive innovation and adoption of advanced systems in critical infrastructure. This expertise is crucial for managing complex asset integrity challenges across diverse geographies.
United States
Demand for corrosion monitoring in the United States centers on extensive pipeline networks and petrochemical facilities. The U.S. EPA mandates stringent asset integrity regulations, compelling continuous monitoring solutions. Petrochemical companies along the U.S. Gulf Coast integrate wireless sensors for comprehensive asset health dashboards.
Germany
Germany's advanced manufacturing and chemical processing sectors require precise material degradation data. Compliance with the EU's Industrial Emissions Directive mandates continuous monitoring in its chemical plants. Sensitive pharmaceutical manufacturing facilities in Germany expand electrochemical noise applications for critical assets.
Saudi Arabia
The oil refining sector in Saudi Arabia drives substantial demand for corrosion monitoring to ensure continuous operation. The Saudi national oil company enforces strict safety standards for its vast infrastructure. Major players in the Middle East prioritize advanced systems to ensure asset integrity and operational safety across their petrochemical complexes.
Australia
Australia's extensive pipeline integrity sector and mining operations require robust corrosion monitoring solutions. Operators increasingly require ISO compliance to secure project financing and insurance for critical infrastructure. The country's resource-rich regions implement advanced systems for safeguarding remote assets.
Indonesia
Indonesia's expanding oil and gas and chemical processing infrastructure presents substantial opportunities for corrosion monitoring. The country's regulatory bodies are strengthening oversight of industrial safety and environmental protection. Underpenetrated markets in Southeast Asia, particularly Indonesia, are expanding their industrial bases.
Corrosion Monitoring Market Key Industry Players
Capital-heavy producers compete with asset-light service providers in the corrosion monitoring market. The industry structure shows a bifurcation between established hardware manufacturers and specialized software/service firms. Key strategic archetypes include integrated solution providers, niche technology specialists, and broad inspection service networks. Dominant competitive moves involve strategic partnerships for technology integration and portfolio diversification into predictive analytics platforms.
Within the integrated solutions archetype, companies like Emerson Electric Co. exemplify a focus on advanced wireless sensor networks for complex industrial facilities, providing comprehensive real-time data platforms. Bureau Veritas S.A. represents the extensive service network model, leveraging its global presence to offer inspection and certification services across various industrial assets. Baker Hughes Company anchors the niche technology specialist segment, concentrating on ultrasonic and eddy current technologies primarily for the demanding oil and gas sector, offering specialized equipment and expertise. These players collectively address diverse client needs, from continuous monitoring to periodic asset integrity assessments.
| Leading Market Players |
|---|
| SGS S.A. |
| Intertek Group plc |
| Emerson Electric Co. |
| ClampOn AS |
| Bureau Veritas S.A. |
| Baker Hughes Company |
| Cosasco Corporation |
| Corrpro Companies Inc. |
| Honeywell International Inc. |
| Others |
Cost & Logistics Intelligence
The London Metal Exchange (LME) copper price directly impacts sensor manufacturing costs, cascading into differentiated pricing tiers for advanced wireless networks versus basic portable devices. This commodity benchmark influences the bill of materials for electronic components and wiring harnesses used in corrosion monitoring systems.
Pricing Analysis
Bundled sensor hardware with expert analysis contrasts with unbundled device sales and separate consulting fees. The dominant pricing model is shifting towards subscription-based Monitoring-as-a-Service (MaaS), alongside project-based hardware sales. Price differentiation stems from technology sophistication, such as advanced electrochemical noise systems, and the level of integrated data analytics. Pricing pressure on advanced integrated systems arises from high capital outlay requirements for brownfield retrofits. Mid-sized operators demonstrate higher price sensitivity compared to large petrochemical companies investing in asset lifetime optimization.
Supply Chain Analysis
Single-source vulnerability sits with specialized sensor component manufacturers in East Asia, particularly China and Taiwan, for critical microcontrollers and rare earth elements. Geographic supply concentration for advanced probes also extends to Germany for precision manufacturing. The supply chain draws from specialized alloys and advanced ceramics for intrusive sensors. Geopolitical tensions represent a significant structural risk, potentially disrupting component availability. Distribution runs through a blend of direct sales to large operators and specialized industrial distributors, often integrated by EPC contractors for new projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The corrosion monitoring market presents a geographic-arbitrage play, as stringent EU Industrial Emissions Directive mandates in Germany create higher demand for continuous monitoring than in regions with less prescriptive regulations.
For Market Incumbents:Extend integrated wireless sensor network capabilities to include AI-driven predictive analytics, mitigating the threat from emerging software-centric competitors. Consolidate market share through strategic acquisitions of niche technology specialists, particularly in electrochemical noise systems. Invest in advanced materials science R&D to develop next-generation probes resistant to aggressive chemical environments, bolstering asset integrity offerings. Focus on achieving ISO compliance for all product lines to meet international benchmarks and regulatory demands.
For New Entrants and Emerging Players:Enter via specialized electrochemical noise systems for pharmaceutical manufacturing, leveraging precise degradation data requirements. Target underpenetrated markets in Southeast Asia, particularly Indonesia, by offering flexible Monitoring-as-a-Service models. Focus on developing AI and machine learning algorithms for asset failure prognostics, creating a niche in predictive maintenance platforms. A go-to-market angle could involve partnering with local EPC contractors to integrate solutions into new infrastructure projects.
For Investors and Strategic Acquirers:Asymmetric upside sits with software-centric analytics providers capable of integrating diverse sensor data. The market demonstrates long-term viability over the next decade due to increasing regulatory pressure and asset lifetime optimization demands. Acquisition targets should include firms specializing in AI and predictive analytics platforms, particularly those with strong data interpretation capabilities. The signal to watch is the rate of conversion from capital expenditure on hardware to subscription-based MaaS models in North America.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand MaaS Offerings | Increases accessibility for mid-sized operators and shifts revenue to recurring models. |
| Acquire AI/Analytics Specialists | Enhances predictive capabilities for asset failure, transforming monitoring into prognostics. |
| Develop Next-Gen Wireless Sensors | Improves real-time data collection across complex piping and vessel systems. |
| Target Renewable Energy Infrastructure | Diversifies revenue streams beyond traditional fossil fuel applications, targeting offshore wind. |
| Strengthen ISO Compliance | Secures project financing and insurance for pipeline integrity in global markets. |
Research Approach
Coverage spans North America, Europe, Asia-Pacific, and the Middle East, with primary inputs from each region. The analysis combines in-depth interviews with plant managers, asset integrity engineers, and materials scientists, validated by secondary research. Secondary sources include U.S. EPA mandates, EU Industrial Emissions Directive documents, ISO guidelines, and company annual reports. This approach ensures robust bottom-up data collection and top-down market sizing.
Market forecasts were modeled at granular levels for technology, application, deployment, and end-user segments, alongside regional economic growth. The analytical framework projects volume and value across the analysis window, deriving compound annual growth rates from historical trends and anticipated technological adoption. Key forecast inputs include capital expenditure trends in oil refining and power generation, and the evolution of global regulatory frameworks for asset integrity.
Inputs from major industry associations and regulatory bodies were available through the study window; gaps in comprehensive global deployment data introduce uncertainty bands. Forecasts reflect assumptions regarding technological maturation and regulatory enforcement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Speed Sensor Market
Sensors and Controls
Odor Detection Equipment Market
Sensors and Controls
Global Collision Avoidance Sensors Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
LAMEA Active Sensor Market
Sensors and Controls
Weather Radar Market
Sensors and Controls
Multi-Axis Sensor Market
Sensors and Controls
Global Load Cell Market
Sensors and Controls
Middle East and Africa Water Detection Sensors Market
Sensors and Controls
United States Pressure Transmitter Market
Sensors and Controls
Europe Electric Vehicle Sensor Market
Sensors and Controls
Eye Tracking Systems Market
Sensors and Controls
Battery Module Sensors Market
Sensors and Controls
Thermal Scanners Market
Sensors and Controls
Europe Smart Glove Market
Sensors and Controls
Mexico Pressure Sensor Market