
 Glucose Sensor Market | 2026-2036
Glucose Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Glucose Sensor Market Outlook
Multi-source procurement for enzyme and electrode materials is broadening as manufacturers reduce dependency on single suppliers. Abbott Laboratories leverages captive biopolymer supply chains to stabilize sensor membrane costs. Dexcom sustains R&D intensity through dedicated cleanroom fabrication in San Diego. Medtronic anchors European distribution through established diabetes care networks in Germany and the Netherlands.
A glucose sensor is an analytical device that quantifies blood glucose concentration through enzymatic or non-enzymatic transduction, typically employing glucose oxidase immobilized on platinum or carbon electrodes with operating potentials between 0.3 and 0.6 volts versus Ag/AgCl reference. Its primary commercial purpose is to enable real-time metabolic monitoring for insulin dosing decisions in diabetic patients and emerging applications in closed-loop artificial pancreas systems. Continuous Glucose Monitors capture the dominant margin pool due to recurring transmitter and sensor-applicator revenues, while Flash Glucose Monitors compete aggressively on price-per-test in European retail pharmacy channels. Electrochemical technology dominates manufacturing scale, though optical platforms using near-infrared spectroscopy occupy select non-invasive research segments.
The FDA enforces Class II medical device controls with 510(k) premarket notification for novel glucose sensors, while ISO 15197 governs accuracy thresholds for self-monitoring systems in Europe and Asia-Pacific export markets. The EU MDR recertification timeline pressures smaller manufacturers to consolidate technical documentation or exit the market. Stakeholders must monitor reimbursement coding decisions by CMS and parallel agencies in Germany and Japan, as these determine patient out-of-pocket exposure and directly shape volume trajectories for next-generation sensor platforms.
Market Dynamics
The glucose sensor market pivots on tightening accuracy mandates from the FDA and EMA, which are compressing development timelines while elevating electrochemical platform performance thresholds. Manufacturers now face simultaneous pressure to reduce sensor drift below 8% MARD while scaling production for home care channels.
Growth Catalysts
- Reimbursement Maturation:CMS coverage expansion for continuous glucose monitors in the United States eliminates patient cost barriers for Type 1 and intensive Type 2 populations. Volume thresholds accelerate as out-of-pocket exposure drops below $75 monthly.
- Enzyme Stabilization Advances:Cross-linked glucose oxidase formulations extend sensor functional life from 10 to 14 days, reducing per-test costs for payers. Manufacturing yields improve as thermal stability broadens shipping tolerances.
- Closed-Loop Integration:Artificial pancreas systems in Germany and Japan demand real-time glucose-insulin algorithm synchronization. Sensor latency below 5 minutes becomes a procurement specification for endocrinology practices.
Market Restraints
- Platinum Electrode Cost Volatility:Spot market prices for sputtered platinum fluctuate with automotive catalyst demand, squeezing gross margins on disposable sensor applicators. Manufacturers lack hedging instruments for thin-film precious metal inputs.
- Single-Source Enzyme Dependency:Recombinant glucose oxidase production concentrates in three contract fermentation facilities across Switzerland and Denmark. Supply interruption risks force 90-day inventory buffers.
- Non-Invasive Optical Substitution:Near-infrared spectroscopy platforms from university spinouts threaten electrochemical incumbents in wellness monitoring segments. Accuracy gaps persist but consumer preference for fingerstick elimination grows.
Strategic Opportunities
- Underpenetrated Indian Outpatient Networks:Tier-2 and Tier-3 cities lack continuous glucose monitor distribution through endocrinology chains. Local pharmacy kiosk models could replicate European Flash Glucose Monitor retail penetration.
- EU MDR Recertification Exodus:Smaller manufacturers abandon European markets due to technical documentation burdens. First movers with notified body relationships capture abandoned market share in the Netherlands and Belgium.
- Wearable Convergence:Integration of glucose sensing with Apple Watch and Samsung Galaxy ecosystems creates consumer-grade demand channels. Optical sensor miniaturization enables multi-analyte wrist-worn devices.
Industry Challenges
- Cleanroom Fabrication Talent Scarcity:Electrochemical sensor production requires thin-film deposition technicians with semiconductor process experience. San Diego and Boston clusters compete for limited personnel pools.
- ISO 15197 Recertification Compression:Self-monitoring blood glucose systems face 18-month renewal cycles with expanded clinical trial requirements. Documentation burdens delay product refresh schedules.
- Legacy Hospital IT Integration:Continuous glucose monitor data streams lack standardized HL7 FHIR connectivity with Epic and Cerner electronic health records. Manual data entry persists in 40% of US health systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Glucose Sensor Market |
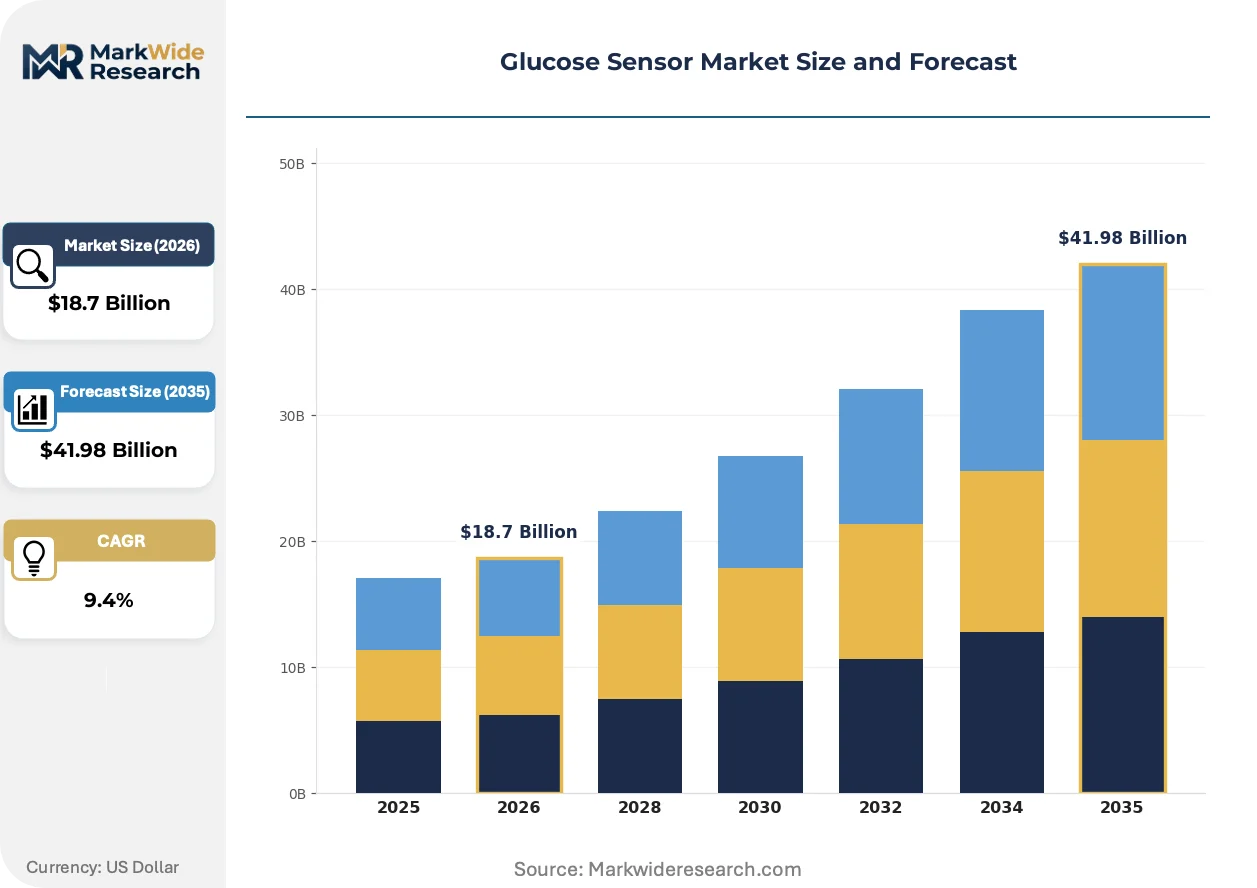
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Continuous Glucose Monitors, Self-Monitoring Blood Glucose Meters, Flash Glucose Monitors, Implantable Glucose Sensors Technology: Electrochemical, Optical, Thermal, Piezoelectric, Ultrasonic Application: Diabetes Management, Hypoglycemia Detection, Ketone Monitoring, Nutritional Monitoring End User: Home Care Settings, Clinical Laboratories, Specialty Clinics, Diabetes Care Centers |
| Companies Covered | Abbott Laboratories, Dexcom, F. Hoffmann-La Roche, Medtronic, Ascensia Diabetes Care Holdings, Senseonics, Novo Nordisk, Sanofi, LifeScan, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Glucose Sensor Market Strategic Shifts
Electrochemical sensing architectures are converging with semiconductor manufacturing methods, compressing sensor form factors while elevating measurement density. Three parallel developments are restructuring competitive positioning.
Microfabricated needle arrays with integrated reference electrodes are integrating glucose oxidase through vapor-phase silanization, achieving 3-micron membrane thickness uniformity. Home care patients in Germany and Japan adopt these platforms for 14-day wear cycles without calibration. The technology is integrating factory-calibrated accuracy into disposable formats, eliminating patient-mediated drift correction and reducing support call volumes.
The EU MDR recertification timeline pressures manufacturers to consolidate technical documentation across sensor generations. Class IIa device reclassification demands clinical evidence for software-as-a-medical-device algorithm updates. European notified bodies in Germany and the Netherlands prioritize submissions from manufacturers with established quality management system certifications, creating queue advantages for incumbents.
Pharmacy chain procurement in France and the United Kingdom now bundles continuous glucose monitor transmitters with insulin pen needle subscriptions. Retail buyers extract volume commitments in exchange for preferred shelf positioning. This channel consolidation shifts margin capture toward distributors and away from direct-to-patient models that dominated early continuous glucose monitor commercialization.
Glucose Sensor Market Segmentation
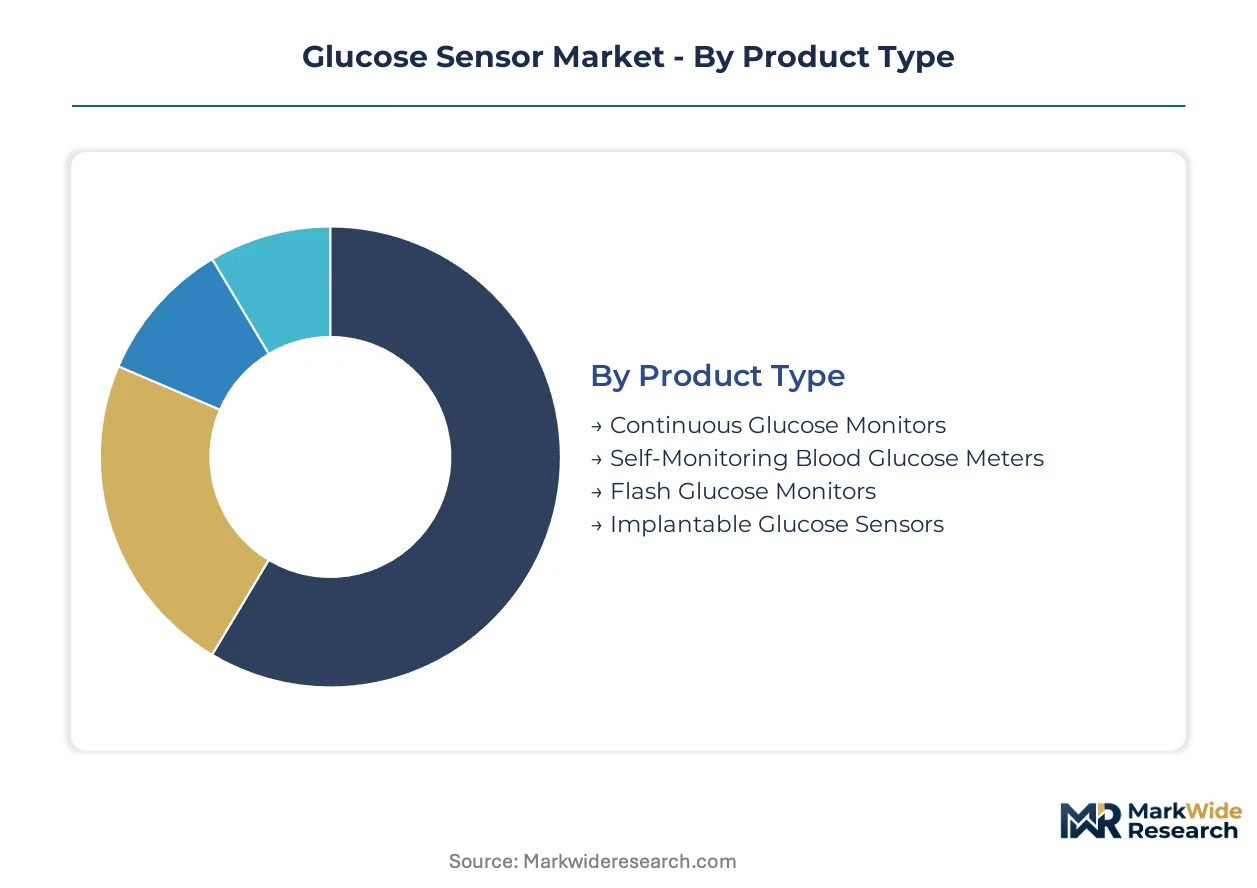
Product architecture and technology modality determine reimbursement pathways and margin structures in glucose sensing. Electrochemical platforms dominate manufacturing scale while optical alternatives challenge in wellness segments. Application focus and care setting dictate regulatory classification and procurement channel access.
Product Type:
Electrochemical sensing architectures anchor the product landscape, with form factor and wear duration defining competitive positioning across reimbursement tiers.
- Continuous Glucose Monitors:Factory-calibrated electrochemical sensors with 10-14 day wear cycles transmit data to insulin pumps or smartphones. Demand concentrates in Germany and the United States where CMS and statutory health insurance eliminate patient cost barriers for Type 1 populations.
- Self-Monitoring Blood Glucose Meters:Test strip-based electrochemical systems require 0.3-1.0 microliter blood samples with 5-second readout times. Pharmacy chain procurement in France and the United Kingdom bundles these with insulin pen needle subscriptions, extracting volume commitments for preferred shelf positioning.
- Flash Glucose Monitors:Factory-calibrated 14-day wearable sensors with optional real-time alarms compete aggressively on price-per-test in European retail channels.
- Implantable Glucose Sensors:Long-term subcutaneous devices with 90-180 day functional life target intensive insulin users seeking reduced insertion frequency.
Continuous Glucose Monitors lead on scale; Flash Glucose Monitors lead on momentum.
Technology:
Transduction modality determines accuracy thresholds, calibration requirements, and manufacturing capital intensity.
- Electrochemical:Glucose oxidase immobilized on platinum or carbon electrodes operates at 0.3-0.6 volts versus Ag/AgCl reference, achieving sub-10% MARD through microfabricated membrane control. FDA Class II 510(k) pathways and ISO 15197 compliance anchor commercialization in the United States and European export markets.
- Optical:Near-infrared spectroscopy and fluorescence-based transduction enable non-invasive measurement through skin or interstitial fluid. University spinouts in Germany and Japan advance wearable convergence with Apple Watch and Samsung Galaxy ecosystems, though accuracy gaps persist against enzymatic benchmarks.
- Thermal:Calorimetric detection measures glucose-oxidase reaction heat release for calibration-free operation in select research applications.
- Piezoelectric:Quartz crystal microbalance platforms detect mass changes from glucose binding, occupying niche laboratory segments.
- Ultrasonic:Acoustic wave propagation through interstitial fluid offers non-invasive potential but lacks clinical validation for therapeutic decision-making.
Electrochemical platforms capture dominant manufacturing scale; optical alternatives expand most quickly in consumer wellness channels.
Application:
Clinical indication severity shapes accuracy requirements, reimbursement coding, and integration with therapeutic decision support.
- Diabetes Management:Real-time glucose-insulin algorithm synchronization for closed-loop artificial pancreas systems demands sensor latency below 5 minutes. Endocrinology practices in Germany and Japan specify this performance threshold in procurement contracts.
- Hypoglycemia Detection:Predictive alert algorithms with 20-30 minute advance warning target nocturnal glucose excursions in pediatric and elderly populations.
- Ketone Monitoring:Beta-hydroxybutyrate electrochemical sensors integrated with glucose platforms address diabetic ketoacidosis prevention in Type 1 intensive management.
- Nutritional Monitoring:Postprandial glucose excursion tracking serves prediabetic and wellness populations seeking metabolic optimization without therapeutic insulin dosing.
Diabetes Management leads on scale; Nutritional Monitoring leads on momentum.
End User:
Care setting determines regulatory classification, data integration requirements, and distribution channel economics.
- Home Care Settings:Patients perform self-monitoring with factory-calibrated devices transmitting data to caregivers via cloud platforms. CMS coverage expansion in the United States reduces out-of-pocket exposure below $75 monthly, accelerating volume thresholds for Type 1 and intensive Type 2 populations.
- Clinical Laboratories:Centralized reference analyzers with hexokinase or glucose oxidase methods provide diagnostic confirmation and quality control benchmarking.
- Specialty Clinics:Endocrinology practices in the Netherlands and Belgium integrate continuous glucose monitor data streams with Epic and Cerner electronic health records, though manual data entry persists in 40% of US health systems lacking standardized HL7 FHIR connectivity.
- Diabetes Care Centers:Multidisciplinary facilities in Germany combine sensor data with retinal imaging and nephrology screening for comprehensive complication management.
Home Care Settings lead on scale; Specialty Clinics lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Diego anchors the global glucose sensor manufacturing base through concentrated cleanroom fabrication capacity and specialized talent pools. Germany and Japan drive reimbursement-enabled demand expansion for continuous glucose monitors. India presents underpenetrated outpatient networks where pharmacy kiosk models could replicate European retail penetration rates.
United States
CMS coverage expansion eliminates patient cost barriers for Type 1 and intensive Type 2 populations, accelerating volume thresholds as out-of-pocket exposure drops below $75 monthly. The FDA enforces Class II medical device controls with 510(k) premarket notification for novel glucose sensors. San Diego and Boston clusters compete for limited thin-film deposition technicians with semiconductor process experience.
Germany
Statutory health insurance eliminates patient cost barriers for Type 1 populations, driving demand concentration comparable to the United States. The EMA tightens accuracy standards for electrochemical sensing platforms through MDR recertification timelines. Diabetes care centers in Munich and Berlin combine sensor data with retinal imaging and nephrology screening for comprehensive complication management.
Japan
Reimbursement pathways for continuous glucose monitors have matured, enabling real-time glucose-insulin algorithm synchronization for artificial pancreas systems. METI and PMDA govern accuracy thresholds and software-as-a-medical-device classifications. Endocrinology practices in Tokyo and Osaka specify sensor latency below 5 minutes as a procurement specification.
India
Tier-2 and Tier-3 cities lack continuous glucose monitor distribution through endocrinology chains, creating whitespace for local pharmacy kiosk models. CDSCO regulates medical device imports and domestic manufacturing quality standards. Maharashtra and Gujarat host emerging diagnostic device assembly operations serving price-sensitive outpatient networks.
Netherlands
Established diabetes care networks anchor European distribution for sensor manufacturers seeking EU market access. The EU MDR recertification timeline pressures smaller manufacturers to consolidate technical documentation or exit the market. Eindhoven's semiconductor ecosystem supplies microfabrication expertise for next-generation sensor membrane development.
Glucose Sensor Market Competitive Environment
Global majors compete with regional champions across reimbursement pathway access and cleanroom fabrication scale. The vendor base stratifies between integrated diabetes care conglomerates, sensor technology specialists, and pharmaceutical companies extending into device ecosystems. Three archetypes dominate: vertically integrated health technology conglomerates, pure-play continuous glucose monitor developers, and diversified pharmaceutical-device hybrids. Capacity expansion in San Diego and Boston clusters competes with strategic partnerships for enzyme supply security.
Among US-based health technology conglomerates, Abbott Laboratories and Medtronic exemplify the vertically integrated archetype through captive biopolymer supply chains and established European distribution networks. Dexcom occupies a position within the pure-play continuous glucose monitor tier, representing dedicated cleanroom fabrication intensity. F. Hoffmann-La Roche anchors the European diversified pharmaceutical-device segment, sitting within a broader diabetes care portfolio that spans diagnostics and therapeutics.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Dexcom |
| F. Hoffmann-La Roche |
| Medtronic |
| Ascensia Diabetes Care Holdings |
| Senseonics |
| Novo Nordisk |
| Sanofi |
| LifeScan |
| Others |
Value Chain & Pricing Dynamics
Private-equity-rolled-up contract manufacturers in Switzerland and Denmark anchor recombinant glucose oxidase supply, concentrating pricing power among three fermentation facilities while forcing sensor makers to absorb cost volatility through inventory buffers rather than contractual pass-through clauses.
Pricing Analysis
Input-cost pass-through from platinum electrode spot markets compresses gross margins on disposable sensor applicators, with sputtered thin-film precious metal prices fluctuating alongside automotive catalyst demand. Pricing stratifies across factory-calibrated continuous systems, calibration-required self-monitoring strips, and economy-tier Flash monitors competing on price-per-test. Cost compression in European retail channels intensifies as pharmacy chains bundle transmitters with insulin pen subscriptions. Price-sensitive Type 2 intensive management populations in India drive economy-tier volume, while least-sensitive closed-loop artificial pancreas adopters in Germany and Japan absorb premium positioning.
Supply Chain Analysis
Freight cost escalation from Swiss and Danish enzyme fermentation facilities to San Diego cleanroom clusters elevates working capital requirements for 90-day inventory buffers against single-source interruption risks. Manufacturing concentrates in the United States, Germany, and Japan, with microfabricated needle arrays drawing from platinum sputtering targets, glucose oxidase biocatalysts, and medical-grade silicone adhesives. Single-source enzyme dependency constitutes the dominant structural vulnerability. Distribution runs through hospital procurement committees, retail pharmacy chains, and direct-to-patient subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The glucose sensor market reads as a late-cycle quality story, with demand shifting toward sub-5-minute latency specifications for artificial pancreas integration that only electrochemical incumbents with cleanroom fabrication scale can reliably deliver.
For Market Incumbents: Acquire thin-film deposition technician pipelines from semiconductor talent clusters in San Diego and Boston to defend against cleanroom fabrication scarcity. Secure captive biopolymer supply chains for sensor membrane cost stabilization. Invest in EU MDR notified body queue positioning before smaller competitors abandon European technical documentation burdens. For New Entrants and Emerging Players: Direct-to-patient digital subscription platforms offer the lowest-friction route around entrenched hospital procurement and pharmacy chain gatekeepers. Target Tier-2 and Tier-3 Indian outpatient networks lacking continuous glucose monitor distribution through endocrinology chains. Deploy local pharmacy kiosk models replicating European Flash Glucose Monitor retail penetration rates. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play continuous glucose monitor developers lacking diversified diabetes care portfolios. Five-to-ten-year viability hinges on reimbursement pathway maturation rather than technology differentiation alone. Watch CMS coding decisions for Type 2 expansion signals as the primary inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Strategy | CMS coverage expansion eliminates patient cost barriers below $75 monthly thresholds. |
| CE Marking Pathway | EU MDR recertification timelines pressure consolidation of technical documentation across sensor generations. |
| Hospital System Partnership | Epic and Cerner HL7 FHIR connectivity gaps persist in 40% of US health systems requiring manual entry. |
| Software Companion Development | Real-time glucose-insulin algorithm synchronization demands sensor latency below 5 minutes for artificial pancreas procurement. |
| Backward Integration | Captive biopolymer supply chains stabilize sensor membrane costs against enzyme price volatility. |
Study Parameters
Multiple input streams — primary interviews with biomedical engineers, hospital GPO contracts managers, and regulatory affairs leads at notified bodies; secondary validation through FDA 510(k) filings, EMA MDR submission databases, and CMS Medicare reimbursement coding records; plus customs data on platinum sputtering target imports — were reconciled through bottom-up sensor shipment modeling and top-down diabetes prevalence calibration.
Historical volume trajectories were cross-referenced against panel input from endocrinology practice procurement officers across Germany, Japan, and the United States. Segmentation dimensions spanned product architecture, transduction modality, clinical indication severity, and care setting regulatory classification. CAGRs were derived from installed base expansion modeling and replacement cycle compression. Forecast inputs incorporated enzyme stabilization technology adoption curves and closed-loop artificial pancreas penetration assumptions.
Platinum price volatility, EU MDR recertification delays, and non-invasive optical substitution threats are the dominant revision risks to electrochemical platform volume assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Digital Automation Temperature Regulator Market
Sensors and Controls
Global Linear Encoder Market
Sensors and Controls
Bulk Acoustic Wave Sensors Market
Sensors and Controls
Global Sensors and Actuators Market
Sensors and Controls
Russia Digital Thermometer Market
Sensors and Controls
United States Sensor Market
Sensors and Controls
Capacitive Position Sensors Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
China Sensors Market
Sensors and Controls
Millimeter Wave Sensors and Modules Market
Sensors and Controls
India Digital Thermometer Market
Sensors and Controls
North America Acoustic Sensors Market
Sensors and Controls
Environmental Noise Cancellation Microphones Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
Non-Contact Sensor Market
Sensors and Controls
Global Ultrasonic Gas Leak Detector Market