
 Chest Sensors Market | 2026-2036
Chest Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Chest Sensors Market Outlook
Flexible polymer substrates are rebalancing cost structures against traditional rigid PCB assemblies in chest sensor manufacturing. Medtronic leverages in-house semiconductor fabrication to control chip supply for implantable cardiac monitors. Abbott sustains R&D intensity across optical and bioelectrical impedance modalities. iRhythm Technologies specializes in algorithm-driven arrhythmia detection, differentiating its service model from hardware-centric competitors.
Chest sensors are electromechanical devices affixed to the thoracic region to capture physiological signals including electrical cardiac activity, respiratory rate, and thoracic impedance, typically operating at sampling frequencies of 250–1000 Hz for diagnostic-grade ECG. Their primary purpose spans continuous patient surveillance in acute care settings, ambulatory cardiac monitoring, and athletic performance optimization. Wireless sensors and wearable monitors lead volume shipments, while Holter monitors retain higher average selling prices in reimbursed diagnostic workflows. Optical monitoring technology is gaining fastest in fitness tracking applications where consumer price sensitivity favors LED-photodiode architectures over clinical-grade bioelectrical systems.
FDA software-as-medical-device frameworks and EU MDR conformity requirements are tightening clinical validation standards for algorithm-based arrhythmia detection, directly shaping product development timelines and market access costs. HIPAA in the United States and GDPR in Europe impose parallel constraints on cloud-transmitted patient data, forcing infrastructure investments that favor established players with compliance resources. Stakeholders must monitor evolving reimbursement codes for remote patient monitoring, as coverage decisions by Medicare and analogous European statutory insurers will determine whether home-based chest sensor deployments achieve economic viability at scale.
Market Dynamics
Software-as-medical-device frameworks are compressing development timelines while simultaneously elevating validation burdens, forcing manufacturers to restructure R&D pipelines around algorithmic rather than hardware-centric differentiation.
Growth Catalysts
- FDA 510(k) Pathway Modernization:Streamlined clearance for AI-enabled arrhythmia detection accelerates commercialization timelines for algorithm-driven chest sensor platforms in the United States.
- Germany's Statutory Health Insurance Reimbursement Expansion:Remote cardiac monitoring coverage under GKV-SV agreements creates immediate demand pull for ambulatory chest sensor deployments in Europe's largest healthcare market.
- Flexible Polymer Substrate Adoption:Roll-to-roll manufacturing of thin-film electrodes reduces per-unit material costs against rigid PCB assemblies while enabling conformal skin contact.
Market Restraints
- EU MDR Conformity Assessment Bottlenecks:Notified body capacity constraints extend certification timelines for bioelectrical impedance devices, delaying market access by 12-18 months.
- Semiconductor Supply Concentration:Discrete analog front-end chips for ECG signal conditioning depend on concentrated Asian foundry capacity, exposing manufacturers to allocation volatility.
- Optical PPG Substitution in Consumer Tiers:LED-photodiode architectures at sub-$50 price points capture fitness tracking demand that bioelectrical systems cannot economically address.
Strategic Opportunities
- Post-Acute Care Settings in the United States:Medicare's remote patient monitoring billing codes (CPT 99453-99458) enable reimbursement for home-based chest sensor monitoring outside traditional hospital workflows.
- AI-ECG Convergence with Electronic Health Records:Direct API integration between cloud-analyzed cardiac data and Epic/Cerner systems reduces clinical workflow friction for health system buyers.
- India's PLI Scheme for Medical Electronics:Production-linked incentives for wearable health devices attract contract manufacturing investment to serve price-sensitive South Asian markets.
Industry Challenges
- Clinical Validation Talent Scarcity:Biostatisticians with FDA predicate device experience command premium compensation, constraining startup hiring pipelines.
- Multi-Jurisdiction Data Sovereignty Compliance:Simultaneous HIPAA, GDPR, and emerging state-level privacy laws fragment cloud infrastructure architectures, elevating DevOps complexity.
- Legacy Holter Monitor Integration:Health system procurement committees demand backward compatibility with existing 12-lead ECG interpretation workflows, slowing wireless sensor adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chest Sensors Market |
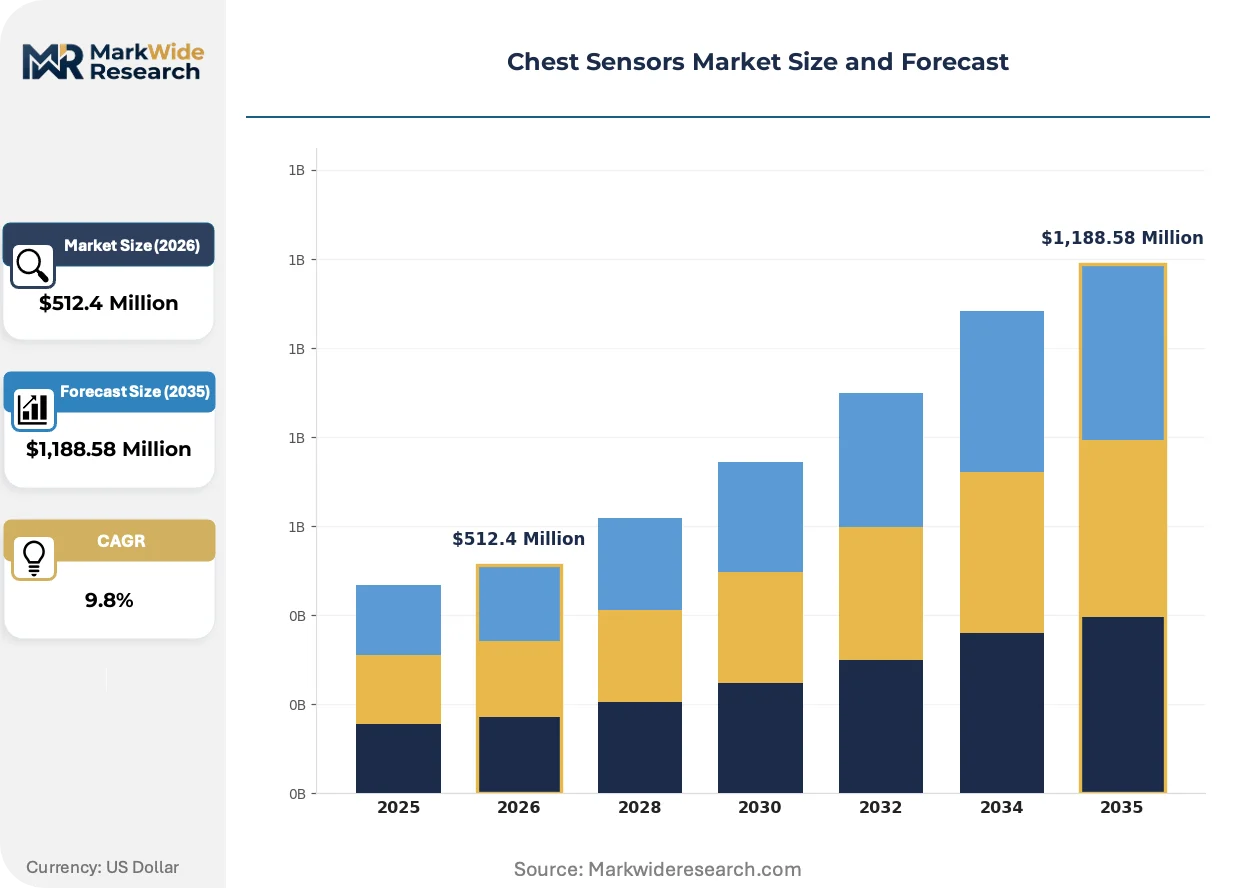
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $1,188.58 Million |
| CAGR (2026 – 2036) | 9.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wireless Sensors, Wearable Monitors, Holter Monitors, ECG Strips Technology: Bioelectrical Impedance, Optical Monitoring, Thermal Imaging, Ultrasound End User: Hospitals, Home Care, Fitness Centers, Research Laboratories Application: Cardiac Monitoring, Fitness Tracking, Patient Surveillance, Emergency Response |
| Companies Covered | Medtronic, Abbott, iRhythm Technologies, AliveCor, Philips Healthcare, Garmin, Polar Electro, ZOLL Medical Corporation, Hexoskin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chest Sensors Market Strategic Shifts
Algorithmic signal processing is displacing hardware feature differentiation as the primary competitive axis, compressing margins on sensor hardware while expanding value capture in data analytics services.
Flexible printed circuit technologies are overtaking rigid PCB assemblies in next-generation chest sensor designs. Cardiology departments in German hospital systems specify conformal electrode arrays for 72-hour ambulatory monitoring. This shift is overtaking traditional Holter form factors by enabling patient compliance through reduced skin irritation and garment compatibility.
EU MDR software classification guidance reclassifies AI-enabled arrhythmia detection as Class IIa medical devices, elevating clinical evidence requirements. Manufacturers must submit prospective validation studies against 12-lead ECG gold standards. Wireless patch monitors with embedded algorithms face the steepest compliance cost increases, favoring established players with regulatory affairs infrastructure.
Hospital procurement committees now unbundle hardware acquisition from algorithm licensing, forcing vendors to price transparency across sensor, cloud, and clinical decision support components. Health systems in the United States negotiate three-year total cost of ownership contracts rather than capital equipment purchases. This restructuring concentrates buying power among integrated delivery networks with sufficient patient volume to justify enterprise-wide deployments.
Chest Sensors Market Segmentation
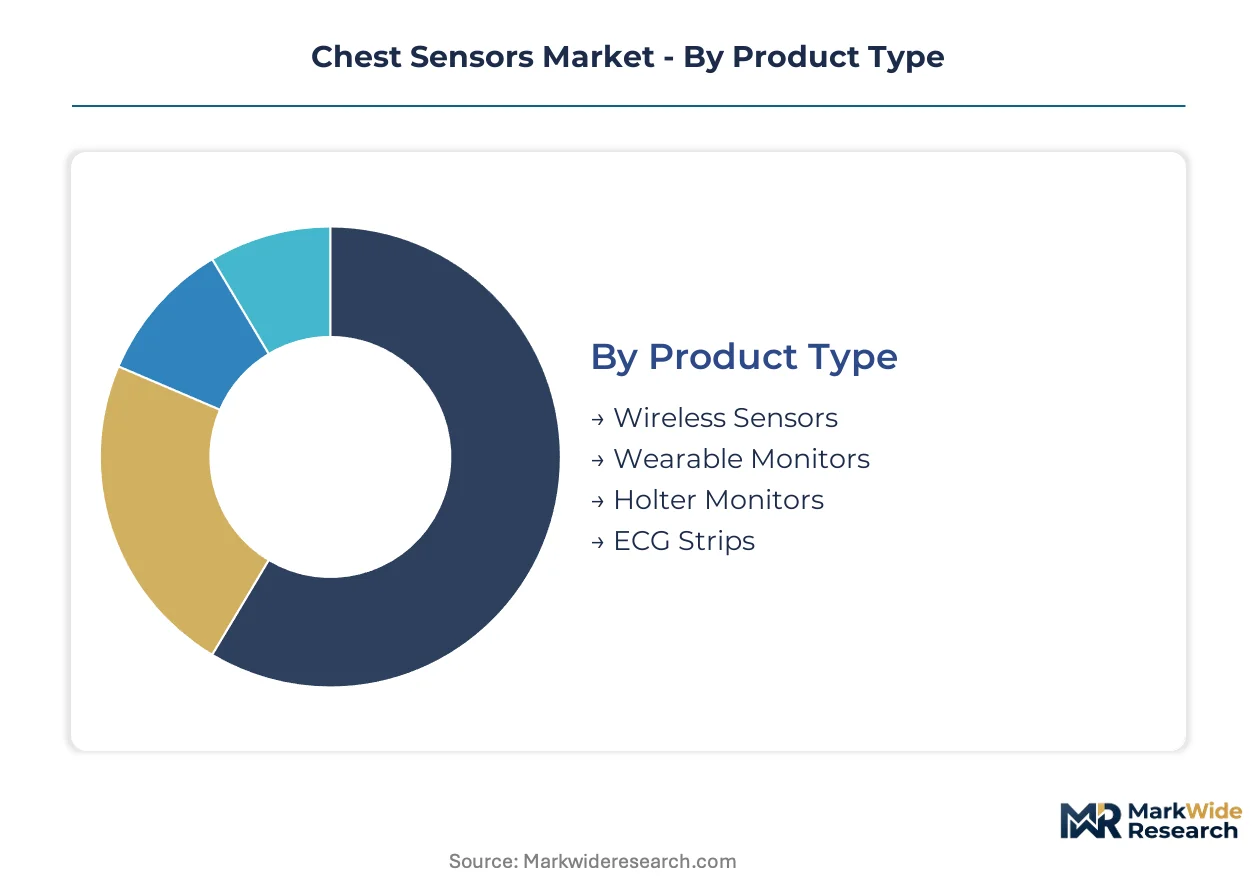
Product architecture in chest sensors spans standalone disposable patches through reusable wearable systems, each carrying distinct margin profiles and integration requirements. Understanding where each segment sits on the hardware-software boundary clarifies competitive positioning and procurement patterns across clinical and consumer tiers.
Product Type:
Wireless sensors and wearable monitors dominate ambulatory deployments where patient mobility is essential, while Holter monitors and ECG strips retain anchored positions in reimbursed diagnostic workflows.
- Wireless Sensors:Adhesive patch form factors with integrated Bluetooth Low Energy transmitters enable 7-14 day continuous monitoring without patient intervention. German statutory health insurance reimbursement expansion is pulling volume into ambulatory cardiology programs where patch-based systems reduce clinic visit burden.
- Wearable Monitors:Reusable chest straps and garment-integrated electrodes pair with consumer smartphones or clinical gateways. Fitness centers in the United States specify these for member retention programs, though clinical-grade variants face procurement scrutiny over data interoperability with Epic and Cerner systems.
- Holter Monitors:Traditional 24-48 hour recording devices with wired lead sets maintain premium pricing in Medicare-reimbursed arrhythmia diagnosis.
- ECG Strips:Single-use disposable electrodes for spot-check monitoring in acute care settings.
Volume placements concentrate in wireless sensors; the faster expansion belongs to wearable monitors.
Technology:
Signal acquisition methods separate clinical-grade diagnostic platforms from consumer wellness devices, with bioelectrical and optical modalities diverging on regulatory pathway and price point.
- Bioelectrical Impedance:Electrode-based ECG signal conditioning at 250-1000 Hz sampling frequencies delivers diagnostic-grade arrhythmia detection. FDA 510(k) pathway modernization is accelerating algorithm-enabled variants, though EU MDR Class IIa reclassification elevates clinical validation costs for wireless patch systems.
- Optical Monitoring:LED-photodiode PPG architectures at sub-$50 bill-of-materials capture fitness tracking demand. India's PLI scheme for medical electronics is attracting contract manufacturing investment to serve price-sensitive South Asian consumer markets.
- Thermal Imaging:Infrared thermography for respiratory rate estimation through chest wall motion analysis.
- Ultrasound:Miniaturized phased arrays for point-of-care cardiac function assessment.
Revenue concentrates in bioelectrical impedance; optical monitoring is climbing the fastest on unit shipments.
End User:
Procurement authority and reimbursement status fragment the customer base, with hospital systems negotiating enterprise contracts while home care and fitness channels operate on transactional purchasing.
- Hospitals:Integrated delivery networks in the United States unbundle hardware from algorithm licensing, demanding three-year total cost of ownership contracts and direct API integration with electronic health records. Cardiology departments specify conformal electrode arrays for 72-hour ambulatory monitoring programs.
- Home Care:Medicare remote patient monitoring billing codes enable reimbursement for home-based chest sensor deployments outside traditional hospital workflows.
- Fitness Centers:Corporate wellness programs and gym chains purchasing consumer-tier devices for member engagement.
- Research Laboratories:Academic medical centers and contract research organizations procuring devices for clinical trial endpoints.
Contract value concentrates in hospitals; home care is expanding most quickly on policy tailwinds.
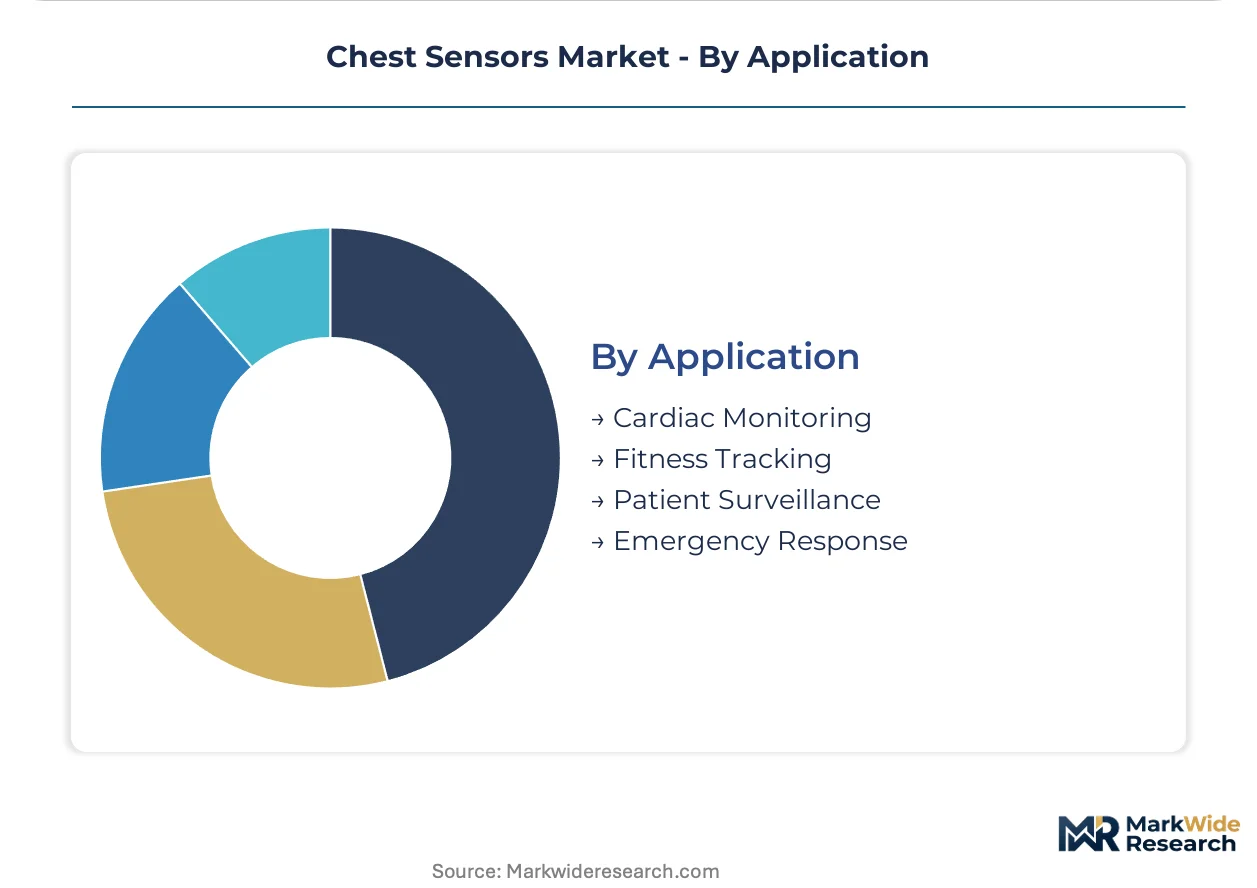
Application:
Use case specificity determines regulatory classification, with diagnostic applications facing FDA and EU MDR medical device frameworks while fitness tracking operates under consumer product regimes.
- Cardiac Monitoring:Continuous ECG surveillance for atrial fibrillation detection and post-ablation monitoring. FDA software-as-medical-device frameworks compress development timelines while elevating algorithm validation burdens against 12-lead ECG gold standards.
- Fitness Tracking:Heart rate variability and recovery metrics for athletic performance optimization. Consumer price sensitivity favors optical PPG substitution over bioelectrical systems.
- Patient Surveillance:Post-acute care monitoring for early deterioration detection in step-down units.
- Emergency Response:First responder triage and pre-hospital cardiac event identification.
Revenue concentration sits with cardiac monitoring; fitness tracking shows the steepest volume trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in Germany where statutory health insurance reimbursement for remote cardiac monitoring has expanded, while the United States and India emerge as high-growth deployment zones on policy tailwinds and manufacturing incentives respectively.
Germany
German hospital systems are expanding ambulatory monitoring programs through cardiology departments. GKV-SV agreements now cover remote cardiac monitoring, creating immediate demand pull for patch-based chest sensor deployments. Manufacturing clusters in Baden-Württemberg and Bavaria host precision electronics fabricators supplying conformal electrode arrays.
United States
Medicare's remote patient monitoring billing codes enable reimbursement for home-based chest sensor monitoring outside traditional hospital workflows. FDA 510(k) pathway modernization compresses clearance timelines for AI-enabled arrhythmia detection platforms. Integrated delivery networks in California and Texas negotiate three-year total cost of ownership contracts unbundling hardware from algorithm licensing.
India
India's PLI scheme for medical electronics attracts contract manufacturing investment to serve price-sensitive South Asian consumer markets. The central government's production-linked incentives specifically target wearable health devices. Electronics manufacturing clusters in Karnataka and Tamil Nadu host assembly operations for optical PPG-based fitness monitors.
Japan
Japan's aging population drives demand for continuous cardiac surveillance in post-acute care settings. PMDA regulatory frameworks maintain stringent clinical validation requirements for bioelectrical impedance devices. Medical device innovation corridors in Kansai and Kanto regions concentrate R&D activities for next-generation conformal sensors.
United Kingdom
NHS long-term plan commitments expand remote monitoring capacity for cardiovascular disease management. MHRA post-Brexit regulatory autonomy enables tailored software-as-medical-device frameworks. London and Southeast England health systems pilot direct API integration between cloud-analyzed cardiac data and electronic health record systems.
Chest Sensors Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with diagnostic-grade platforms consolidating around established medical device houses while consumer fitness tiers fragment among electronics OEMs. Three archetypes dominate: vertically integrated semiconductor fabricators controlling chip supply, algorithm-centric service platforms unbundling hardware from analytics, and contract manufacturers leveraging India's PLI incentives for cost-sensitive consumer tiers. M&A activity concentrates on software capabilities and regulatory affairs infrastructure, while strategic partnerships focus on electronic health record interoperability.
Within the vertically integrated tier, Medtronic anchors positions through in-house semiconductor fabrication for implantable cardiac monitors. Abbott exemplifies sustained R&D intensity across multiple sensing modalities. iRhythm Technologies occupies a specialist position in algorithm-driven arrhythmia detection, differentiating through service models rather than hardware-centric competition. These three represent distinct strategic postures: captive supply control, portfolio diversification, and software-based service unbundling.
| Leading Market Players |
|---|
| Medtronic |
| Abbott |
| iRhythm Technologies |
| AliveCor |
| Philips Healthcare |
| Garmin |
| Polar Electro |
| ZOLL Medical Corporation |
| Hexoskin |
| Others |
Value Chain & Pricing Dynamics
Biomedical engineers with FDA predicate device experience in the Boston and San Francisco metro areas command compensation premiums that widen spreads between diagnostic-grade and consumer-tier chest sensor pricing. Labor-cost differentials between these specialized clinical validation hubs and contract manufacturing zones in Karnataka and Tamil Nadu stratify final product tiers.
Pricing Analysis
Volume shipments concentrate in wireless adhesive patches while margin capture favors algorithm-licensing service models over hardware sales. Three-tier pricing structure across premium diagnostic, standard clinical, and economy fitness levels separates FDA-cleared bioelectrical systems from CE-marked wellness devices and uncertified optical monitors. Cost compression in consumer tiers stems from India's PLI scheme attracting assembly investment for sub-$50 LED-photodiode architectures. Fitness centers exhibit highest price sensitivity; integrated delivery networks in the United States demonstrate lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Workforce availability for precision electronics fabrication clusters in Baden-Württemberg, Bavaria, and Karnataka shapes regional manufacturing capacity allocation. Discrete analog front-end chips for ECG signal conditioning draw from concentrated Asian foundry capacity, while flexible polymer substrates and conformal electrode arrays source from German precision fabricators. Single-source vulnerability in semiconductor allocation exposes manufacturers to supply volatility. Distribution runs through hospital procurement committees, GPO contracts, and direct-to-consumer channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a supply-constrained environment where clinical validation talent scarcity props pricing power for established players with regulatory affairs infrastructure.
For Market Incumbents: Cement algorithmic differentiation through direct API integration with Epic and Cerner systems, locking in health system switching costs. Expand captive semiconductor fabrication capacity to insulate against Asian foundry allocation volatility threatening implantable cardiac monitor supply.
For New Entrants and Emerging Players: Post-acute care settings in the United States represent an underserved buyer archetype where Medicare remote patient monitoring billing codes enable reimbursement without entrenched competitor relationships. India's price-sensitive consumer markets offer penetrable white-space for optical PPG-based fitness monitors leveraging PLI scheme manufacturing incentives.
For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-centric service platforms given FDA software-as-medical-device framework compression of commercialization timelines. Long-term viability in this market hinges on regulatory affairs infrastructure depth. Watch EU MDR notified body capacity constraints as inflection indicator for certification timeline risk.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Accelerates clearance for AI-enabled arrhythmia detection platforms in the United States. |
| Hospital System Partnership | Enables three-year total cost of ownership contracts with integrated delivery networks. |
| Software Companion Development | Supports unbundled algorithm licensing separate from hardware acquisition. |
| CE Marking Pathway | Navigates EU MDR Class IIa reclassification for wireless patch systems. |
| Reimbursement Strategy | Secures coverage under Germany's GKV-SV agreements and Medicare billing codes. |
Study Parameters
SEC filings, FDA 510(k) clearance databases, and CMS Medicare reimbursement records formed the secondary backbone, supplemented by customs trade data and hospital procurement contracts. Primary interviews with biomedical engineers, hospital purchasing committee members, regulatory affairs specialists, and GPO contracts managers validated demand assumptions. Bottom-up and top-down triangulation reconciled unit shipment estimates with revenue aggregation across product tiers.
Bottom-up modeling built from country-level reimbursement policy analysis and health system procurement pattern assessment, while top-down approaches cross-checked against statutory insurance coverage expansion trajectories. Segmentation dimensions spanned product architecture, signal acquisition technology, end-user procurement authority, and application regulatory classification. CAGRs derived from fitted growth curves against policy tailwinds and manufacturing cost trajectories. Forecast inputs incorporated notified body capacity constraints and semiconductor allocation volatility.
Revisions become necessary when EU MDR notified body bottlenecks extend certification timelines, when semiconductor supply concentration triggers allocation crises, or when reimbursement code changes alter home-based deployment economics. Forecasts reflect documented assumptions about regulatory pathway efficiency and manufacturing scale-up feasibility. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Middle East and Africa Wireless Sensors Market
Sensors and Controls
SQUID Sensor Market
Sensors and Controls
Distributed Fiber Optic Sensing Market
Sensors and Controls
Digestible Sensors Market
Sensors and Controls
Electronic Sentry Market
Sensors and Controls
Global Sensors Market
Sensors and Controls
Safety Sensors Market
Sensors and Controls
VOC Sensors and Monitors Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Touch Sensor Market
Sensors and Controls
Mass Flow Controller Market
Sensors and Controls
Fingerprint Identification Chip Market
Sensors and Controls
Europe Advanced CO2 Sensor Market
Sensors and Controls
Wireless IoT Sensors Market
Sensors and Controls
Smart Pressure Gauge Market
Sensors and Controls
Industrial Sensors Market