
 Inductive Proximity Sensors Market | 2026-2036
Inductive Proximity Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
Inductive Proximity Sensors Market Foresight
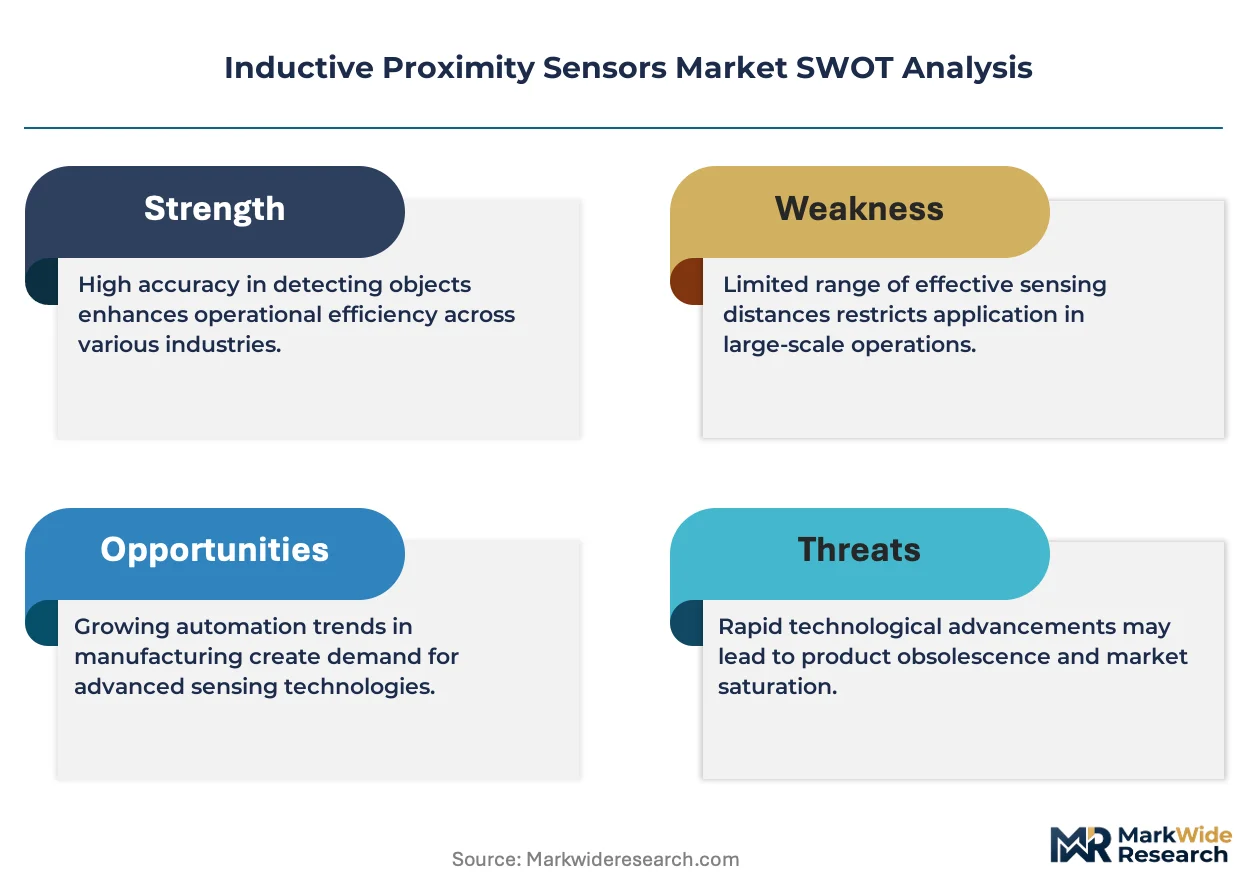
Industrial distributor networks across Central Europe is rewriting how inductive proximity sensors reach end users, with regional stocking partners consolidating technical support and inventory holding. Pepperl+Fuchs SE leverages its factory automation heritage to dominate hazardous-area applications. SICK AG competes through laser-focused positioning in safety-certified sensor portfolios. Balluff GmbH anchors mid-market volume with RFID-integrated inductive solutions for traceability workflows.
Inductive proximity sensors detect metallic objects via electromagnetic field disturbance without physical contact, typically operating at switching frequencies from 10 Hz to 5 kHz and sensing ranges from 0.8 mm to 40 mm depending on coil geometry and target material. These devices serve primarily as non-contact position switches in automated machinery, replacing mechanical limit switches to eliminate wear and enable higher cycle rates. Smart sensor variants with IO-Link connectivity command premium positioning as factories prioritize predictive maintenance and real-time diagnostics over basic digital switching. Wireless inductive sensors represent the fastest-expanding technology segment, though analog output types retain margin strength in precision motion control applications where continuous position feedback replaces discrete on-off signaling.
IEC 60947-5-2 governs low-voltage switchgear performance for proximity devices across European installations, while OSHA machinery guarding standards shape sensor selection in US manufacturing environments. The EU Machinery Directive's updated functional safety requirements push OEMs toward certified safety-rated inductive sensors with redundant outputs. China's GB/T 14048.10 standard creates a parallel compliance pathway for equipment exported to or manufactured within its industrial base. Stakeholders must monitor how IIoT protocol fragmentation between EtherNet/IP, PROFINET, and OPC UA affects sensor platform roadmaps and R&D allocation across vendor engineering teams.
Market Dynamics
Electric vehicle assembly lines are forcing a wholesale replacement of mechanical limit switches with inductive proximity sensors capable of sustaining 10,000+ cycles per hour in high-temperature weld environments.
Growth Catalysts
- IEC 60947-5-2 compliance mandates:European OEMs must certify all proximity devices for low-voltage switchgear performance, creating pull for certified safety-rated variants with redundant outputs in automated machinery.
- Automotive electrification:Battery pack assembly and motor winding operations require non-contact position sensing to eliminate contamination risks from mechanical switch debris.
- IO-Link protocol penetration:Smart sensor variants with real-time diagnostics capability command premium positioning as factories prioritize predictive maintenance over basic digital switching.
Market Restraints
- Copper and ferrite core volatility:Coil winding materials face price instability from mining supply disruptions, compressing margins for standard-duty sensor manufacturers.
- Capacitive and ultrasonic substitution:Non-metallic target detection applications increasingly migrate to alternative sensing technologies that bypass inductive limitations on material type.
- REACH substance restrictions:European chemical regulations constrain potting compound formulations used in harsh-environment sensor housings, extending qualification timelines.
Strategic Opportunities
- Wireless inductive sensing:Battery-free energy harvesting variants eliminate cable maintenance in rotating equipment and mobile robotics applications.
- India's PLI scheme for manufacturing:Production-linked incentives for industrial automation create localized assembly opportunities for mid-range sensor portfolios.
- RFID-integrated traceability:Converged inductive-position and identification platforms capture workflow data for quality audit trails in automotive Tier 1 supply chains.
Industry Challenges
- Functional safety certification backlog:SIL-rated inductive sensors face extended validation queues at TÜV and other notified bodies, delaying product launches.
- Legacy PLC integration friction:IO-Link-enabled smart sensors require gateway infrastructure investments that conflict with installed base of analog-input controllers in brownfield plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Inductive Proximity Sensors Market |
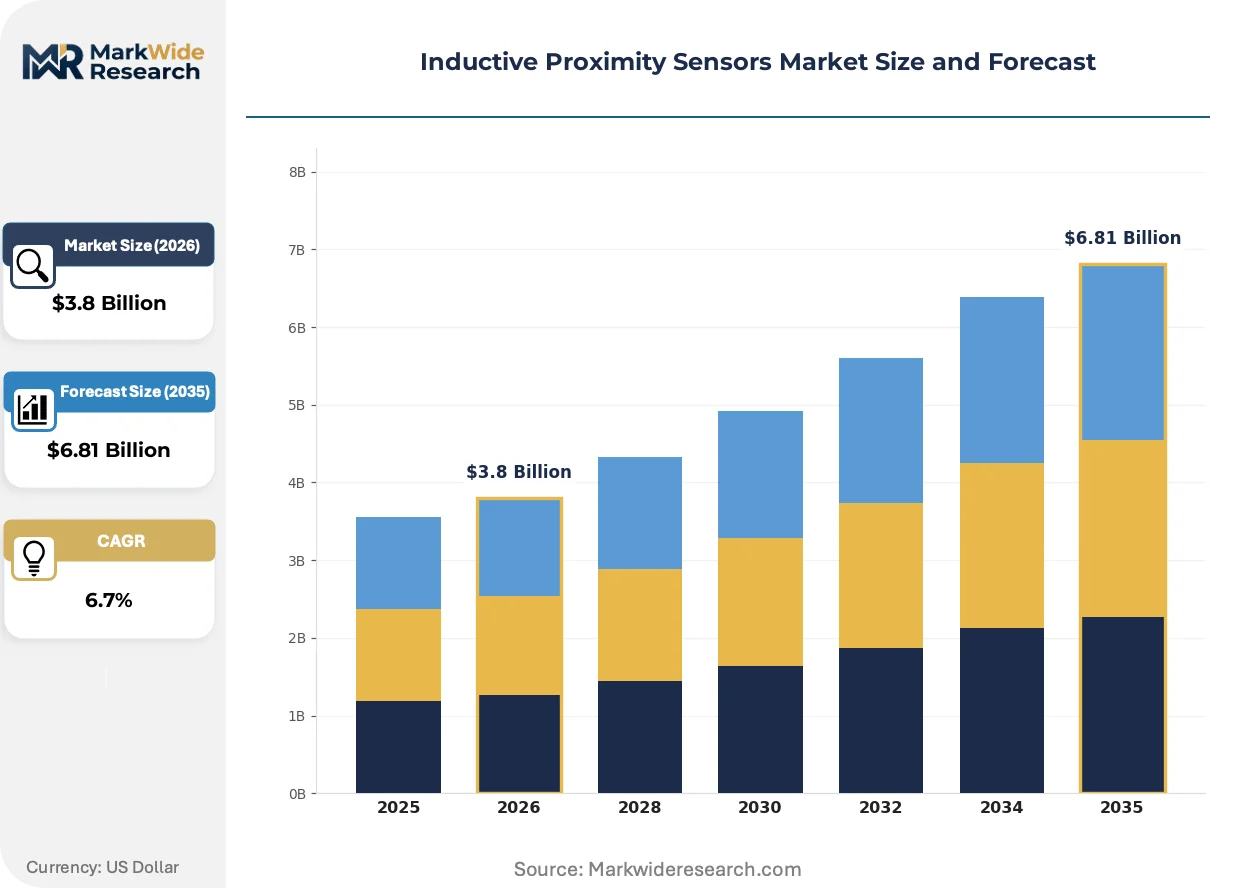
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ground Sensors, Capacitive Sensors, Magnetic Sensors, Photoelectric Sensors Technology: Analog, Digital, Smart Sensors, Wireless End User: Manufacturing, Automotive, Aerospace, Consumer Electronics Application: Position Detection, Object Counting, Level Measurement, Safety Systems |
| Companies Covered | Pepperl+Fuchs SE, Rockwell Automation, Inc., Panasonic Holdings Corporation, Eaton Corporation plc, SICK AG, Omron Corporation, Keyence Corporation, Hans Turck GmbH & Co. KG, Balluff GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Inductive Proximity Sensors Market Shifts & Advancements
Sensor architecture is bifurcating between cost-optimized standard devices and intelligent platforms capable of edge diagnostics, with the middle tier eroding as procurement prioritizes either bare functionality or full predictive capability.
Inductive sensing coils are migrating from traditional wound copper constructions to printed circuit board-integrated flat coil designs. Automotive body-in-white lines at BMW and Volkswagen Group facilities have adopted these planar sensors for weld cell proximity detection. The shift is compressing mechanical assembly steps and enabling sub-millimeter sensing range consistency across high-volume production.
OSHA machinery guarding standards are tightening interpretation of safety-rated sensor fault detection requirements. US automotive and packaging machinery builders must now demonstrate redundant channel monitoring for personnel protection applications. This regulatory pressure is accelerating demand for certified safety inductive sensors with dual-output architectures in North American manufacturing environments.
Buying patterns among German machine tool OEMs are consolidating annual sensor procurement into framework agreements with integrated distributors. Regional stocking partners now hold buffer inventory and provide same-day technical support previously managed by manufacturer field engineers. This channel transformation is most visible in Bavaria's industrial corridor, where Balluff and Pepperl+Fuchs have restructured direct sales coverage to focus on specification rather than fulfillment.
Inductive Proximity Sensors Market Segmentation
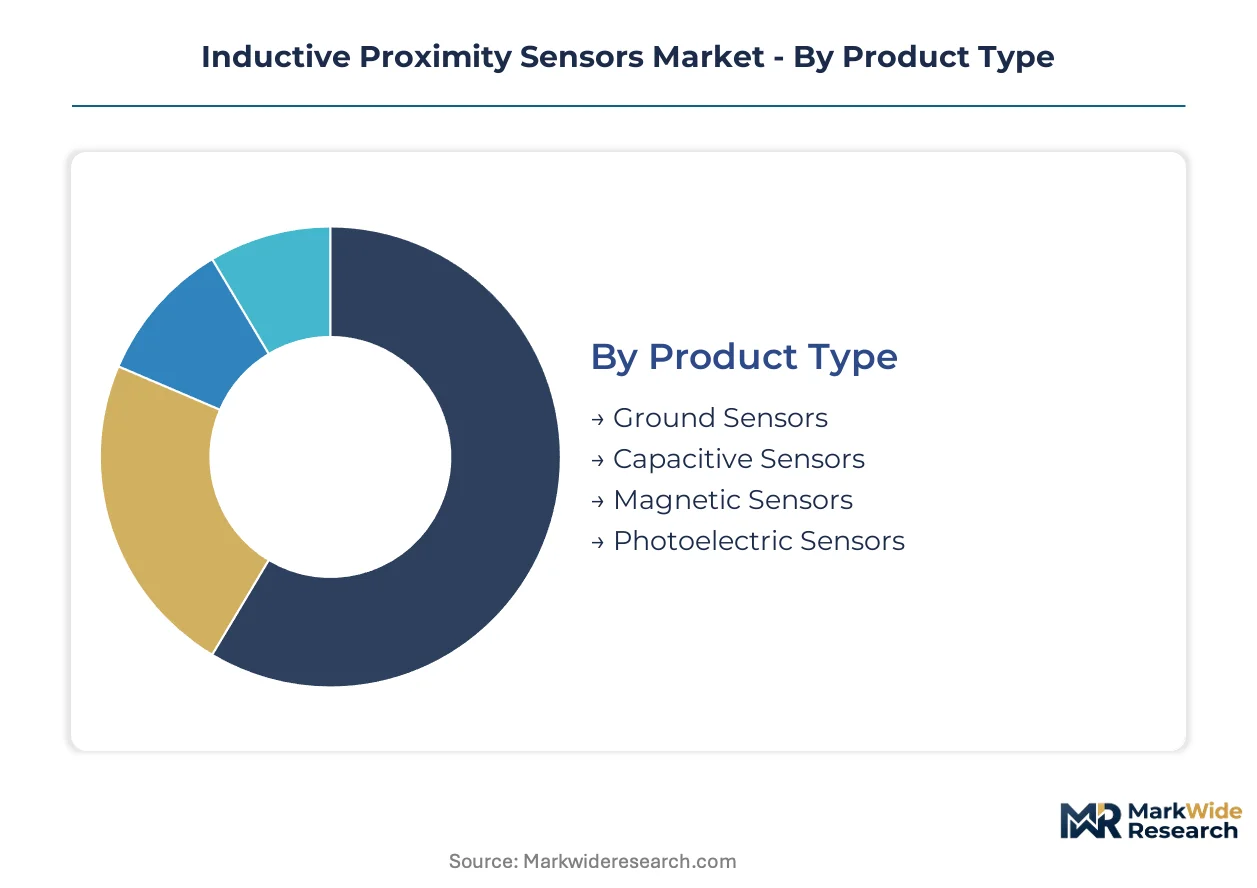
Segmentation in the inductive proximity sensors market reveals how electromagnetic sensing technologies fragment across performance tiers, connectivity protocols, and industrial use cases. Procurement patterns diverge sharply between cost-driven standard deployments and premium intelligent platforms with predictive diagnostics.
Product Type:
Ground sensors anchor heavy-duty installations where moisture ingress and mechanical shock dominate operational constraints, while capacitive variants extend proximity detection to non-metallic targets that inductive coils cannot sense.
- Ground Sensors:Encapsulated coil assemblies with reinforced cable glands withstand submersion and vibration in mining conveyors and outdoor material handling. German bulk material handling OEMs specify these for potash extraction facilities where standard housings fail within months.
- Capacitive Sensors:Electrode-based detection circuits sense plastics, liquids, and powders through dielectric property changes, bypassing inductive limitations on target material. Demand concentrates in packaging machinery for pharmaceutical blister counting where metallic contamination must be avoided.
- Magnetic Sensors:Hall-effect and magnetoresistive elements detect ferromagnetic targets at extended ranges, serving position feedback in hydraulic cylinder applications.
- Photoelectric Sensors:Light-beam interruption methods compete for non-contact detection where color contrast or transparent object sensing matters.
The dominant share belongs to ground sensors, while capacitive variants are closing the gap fastest.
Technology:
Connectivity architecture determines whether sensors feed simple PLC inputs or integrate into edge-computing diagnostics networks.
- Analog:Continuous voltage or current output proportional to target distance provides position feedback for servo-controlled motion systems. Machine tool builders in Stuttgart's industrial cluster specify these for tool length measurement where discrete switching lacks resolution.
- Digital:Binary PNP/NPN outputs dominate high-speed counting applications with switching frequencies exceeding 5 kHz.
- Smart Sensors:IO-Link-enabled devices embed parameter storage, temperature monitoring, and cycle counters for predictive maintenance algorithms. Battery assembly lines at BMW Leipzig deploy these for weld cell position verification with real-time thermal drift compensation.
- Wireless:Battery-free energy harvesting from the switching signal eliminates cable fatigue in rotating indexing tables and mobile robotics.
Smart sensors command the steepest expansion trajectory as factories retrofit brownfield equipment with IIoT infrastructure.
End User:
Industry verticals impose distinct certification, environmental, and lifecycle requirements that reshape sensor specification priorities.
- Manufacturing:General automation applications span food processing, textile machinery, and material handling with emphasis on IP69K washdown ratings.
- Automotive:Body-in-white welding and battery pack assembly drive demand for high-temperature-resistant sensors with immunity to electromagnetic interference from resistance welding equipment. Volkswagen Group's Zwickau EV plant sources exclusively from suppliers with weld-splash-resistant ceramic faceplates.
- Aerospace:MRO applications and component manufacturing require traceability documentation and extended calibration intervals.
- Consumer Electronics:Miniaturized sensors for assembly robotics prioritize sub-millimeter repeatability in cleanroom environments.
Automotive procurement volumes outweigh other verticals combined, though aerospace specifications pull premium pricing multiples.
Application:
Functional use cases determine sensing range, response time, and output configuration requirements across industrial workflows.
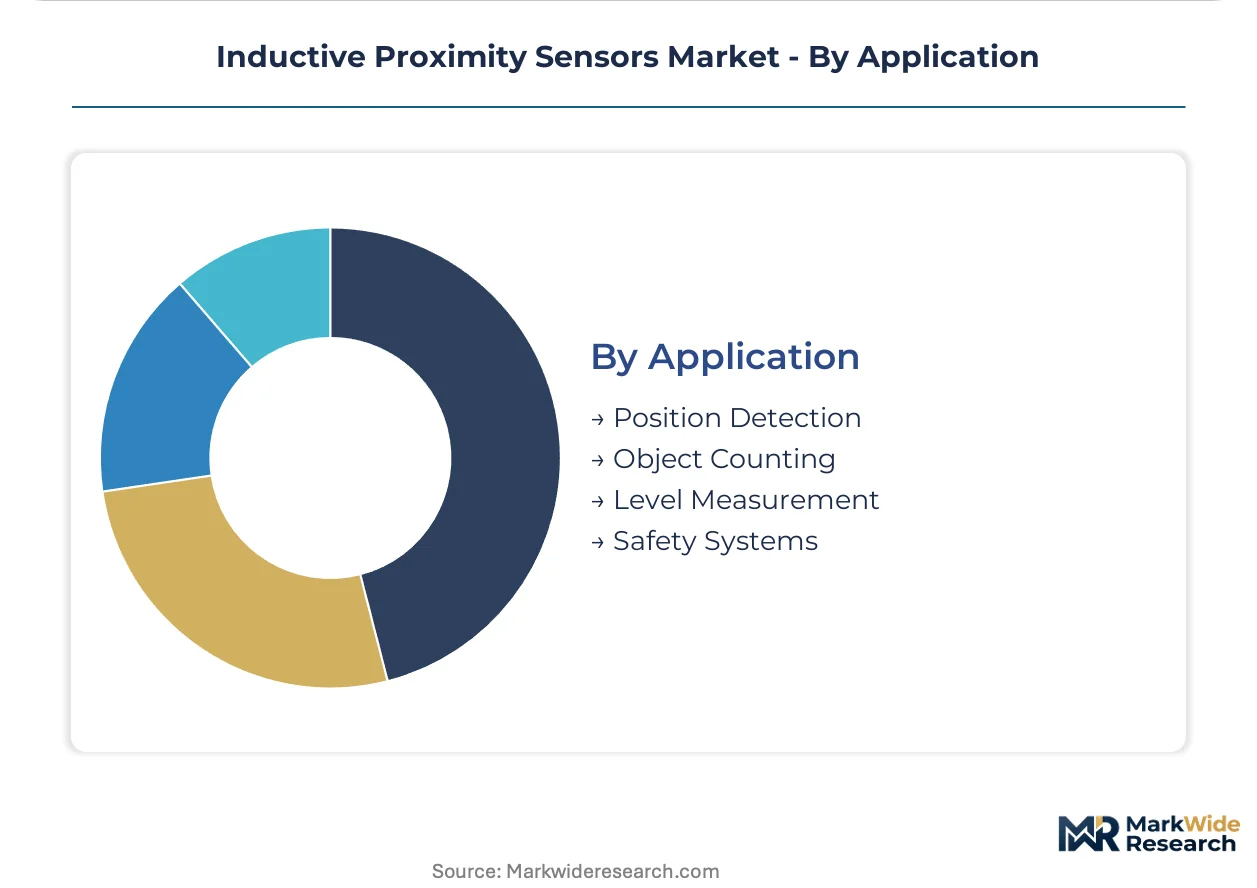
- Position Detection:Piston end-position sensing in pneumatic cylinders and slide table homing operations constitute the largest installed base.
- Object Counting:High-speed bottle and package detection on conveyor lines demands switching frequencies above 2 kHz with minimal response time jitter.
- Level Measurement:Through-wall tank sensing using external mounting avoids process contamination in chemical and pharmaceutical batch operations.
- Safety Systems:SIL-rated redundant-output sensors monitor guard doors and light curtain muting in personnel protection applications. OSHA's tightened fault-detection interpretations are accelerating specification of dual-channel inductive devices in North American packaging machinery.
Position detection retains the largest share, while safety systems are gaining share fastest on regulatory compliance mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's automated container handling systems anchor Europe's sensor procurement networks, while Germany's Rhine-Main industrial corridor channels component flows into Central European machine tool builders.
Germany
BMW Group's Leipzig and Regensburg EV plants drive specification of weld-splash-resistant inductive sensors for body-in-white automation. IEC 60947-5-2 compliance mandates from the EU Machinery Directive force OEMs toward SIL-rated redundant-output devices. Bavaria's industrial corridor concentrates procurement through framework agreements with regional distributors holding buffer inventory for same-day technical support.
United States
OSHA's tightened machinery guarding standards accelerate demand for dual-channel safety-rated sensors in automotive and packaging machinery. Ford's Rouge Electric Vehicle Center and GM's Factory ZERO deploy high-temperature inductive devices for battery pack assembly lines. Michigan's automotive supplier cluster sources through integrated distributors consolidating previously manufacturer-managed field engineering.
China
GB/T 14048.10 standards create parallel compliance pathways for equipment exported to or manufactured within domestic industrial bases. BYD and CATL battery gigafactories in Shenzhen and Ningbo scale non-contact position sensing to eliminate contamination risks from mechanical switch debris. Yangtze River Delta automation integrators specify IO-Link-enabled variants for predictive maintenance retrofit programs.
Japan
Toyota's Motomachi and Tsutsumi plants pioneer printed circuit board-integrated flat coil designs for sub-millimeter sensing consistency. METI's Smart Factory initiatives channel subsidies toward IIoT sensor infrastructure in SME manufacturing clusters. Nagoya's industrial corridor concentrates precision motion control applications where analog output types retain pricing strength.
India
PLI scheme production-linked incentives for industrial automation create localized assembly opportunities for mid-range sensor portfolios. Tata Motors' Pune EV facility and Mahindra's Chakan plant deploy inductive sensors for motor winding operations. Gujarat's Sanand automotive cluster sources through regional stocking partners consolidating technical support and inventory holding.
Inductive Proximity Sensors Market Competitive Landscape
On the supply side, the industry is bifurcating between heritage factory automation specialists and diversified industrial conglomerates, with mid-market volume players occupying a narrowing middle tier. Three strategic archetypes dominate: hazardous-area certification leaders, safety-rated portfolio specialists, and RFID-integrated traceability providers. Competitive intensity concentrates on M&A for IIoT protocol capabilities and backward integration into coil winding materials.
Among German-based automation specialists, Pepperl+Fuchs SE and SICK AG exemplify the heritage archetype, with Balluff GmbH occupying a position in the mid-market volume tier. These entities represent the geographic clustering of sensor engineering competence around Stuttgart and Mannheim industrial corridors, where machine tool OEM relationships anchor specification influence.
| Leading Market Players |
|---|
| Pepperl+Fuchs SE |
| Rockwell Automation, Inc. |
| Panasonic Holdings Corporation |
| Eaton Corporation plc |
| SICK AG |
| Omron Corporation |
| Keyence Corporation |
| Hans Turck GmbH & Co. KG |
| Balluff GmbH |
| Others |
Supply & Pricing Matrix
Stuttgart's industrial corridor anchors coil winding capacity for European sensor manufacturers, concentrating supply-side leverage among heritage automation specialists who dictate pricing terms to mid-market distributors. Bavarian machine tool OEMs negotiate framework agreements that compress margins for standard-duty devices while preserving premium positioning for SIL-certified variants with redundant outputs.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume scale. Price differentiation hinges on IEC 60947-5-2 compliance tier and IO-Link connectivity integration, with automotive Tier 1 suppliers showing least price sensitivity for weld-splash-resistant variants. Cost compression in economy-grade analog sensors is intensifying because copper and ferrite core volatility feeds through coil material costs.
Supply Chain Analysis
Export-control restrictions on advanced ferrite core formulations and precision winding equipment limit technology transfer to emerging manufacturing bases. Supply concentrates in Germany, China, and Japan, with coil assemblies drawing from copper mining operations in Chile and rare earth processing in China. Single-source vulnerability in ceramic faceplate substrates for high-temperature automotive applications creates supply chain risk. Distribution runs through regional stocking partners consolidating inventory holding and technical support previously managed by manufacturer field engineers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is recovering from a cyclical trough driven by automotive electrification capital expenditure waves. Battery gigafactory buildouts are resetting demand baselines for high-temperature inductive sensing platforms.
For Market Incumbents: Entrench specification influence at German machine tool OEMs through backward integration into printed circuit board-integrated flat coil designs. Deepen certification investment for SIL-rated redundant-output architectures before TÜV validation queues extend further. Defend against capacitive and ultrasonic substitution by emphasizing weld-environment immunity that alternative technologies cannot replicate. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme-subsidized manufacturing automation segment where localized assembly requirements disadvantage imported premium brands. Target wireless energy-harvesting variants for mobile robotics applications where cable fatigue creates unmet need. Pursue distributor partnership models bypassing direct sales infrastructure investments. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors IIoT protocol capability specialists over commodity switchgear manufacturers. Long-term viability over the next decade rests on edge diagnostics integration rather than discrete switching hardware. Acquisition targets should demonstrate proven IO-Link parameter storage and thermal drift compensation algorithms. Monitor weld-splash-resistant ceramic faceplate supply agreements as inflection indicator for automotive share capture.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coil Materials | Captive ferrite core supply insulates margin compression from mining volatility. |
| IO-Link Protocol Certification | Smart sensor variants command premium positioning in predictive maintenance retrofit programs. |
| SIL-Rated Safety Certification Investment | Dual-output architectures satisfy tightened OSHA machinery guarding interpretations. |
| Regional Distributor Consolidation | Framework agreements with Bavarian stocking partners reduce field engineering overhead. |
| Wireless Energy Harvesting Development | Battery-free designs eliminate cable maintenance in rotating equipment applications. |
Research Methodology
Initial hypotheses were tested against primary input from plant engineers at automotive OEMs, procurement leads at Tier 1 suppliers, maintenance directors in bulk material handling, distribution channel partners, and technical R&D directors at sensor manufacturers and refined through secondary validation. Sources included IEC 60947-5-2 certification databases, EU Machinery Directive compliance filings, customs and trade data for coil winding materials, SEC filings of listed automation conglomerates, and automotive production databases. Bottom-up segment sizing triangulated against top-down industrial automation expenditure estimates.
Demand-supply balance modeling across the projection horizon incorporated product type segmentation by sensing technology, connectivity protocol tier, end-use vertical certification requirements, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and electrification-driven new equipment demand. Industry-specific inputs included EV assembly line cycle rate specifications and weld cell electromagnetic interference tolerance thresholds.
Sensitivities concentrate around copper and ferrite core commodity volatility, REACH substance restriction extensions affecting potting compounds, and IIoT protocol standardization outcomes between EtherNet/IP and PROFINET. Forecasts reflect documented assumptions about automotive electrification penetration and functional safety certification timeline normalization. Material shifts in EU Machinery Directive enforcement intensity or battery gigafactory construction delays would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Rotary Encoders Market
Sensors and Controls
Condition Monitoring Equipment Market
Sensors and Controls
Subcool Metering Device Market
Sensors and Controls
Blue-Green Algae Sensors Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Virtual Sensors Market
Sensors and Controls
Global MEMS and Sensors Market
Sensors and Controls
France Air Purifier Market
Sensors and Controls
3D Sensors Market
Sensors and Controls
Bio-FET Market
Sensors and Controls
Biometric Sensors Market
Sensors and Controls
Smart Sensor Market
Sensors and Controls
Europe Nano Sensors Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Digital Radiography Sensor Market
Sensors and Controls
MEMS Microphones Market