
 Handheld Thermal Imaging Equipment Market | 2026-2036
Handheld Thermal Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Thermal Imaging Equipment Market Foresight
Equipment leasing and performance-based rental contracts is rewriting competitive entry dynamics for mid-tier buyers who previously faced high capital barriers. Teledyne FLIR leverages its vertically integrated sensor foundry to sustain margin control across the value chain. L3Harris Technologies anchors its position through defense-grade certification pathways that civilian competitors cannot easily replicate. Testo SE & Co. KGaA specializes in building inspection workflows, occupying a differentiated channel in European contractor markets.
Handheld thermal imaging equipment comprises portable electro-optical systems that detect infrared radiation across the 7.5–14 micrometer spectral band, converting thermal gradients into visible images for non-contact temperature measurement and anomaly detection. These devices employ vanadium oxide or amorphous silicon microbolometer arrays fabricated on silicon substrates, enabling real-time thermal mapping for predictive maintenance, safety inspection, and diagnostic applications. Standalone devices dominate current procurement volumes due to their all-in-one durability and calibrated accuracy for professional field use. Smartphone attachments represent the fastest-expanding category as iOS and Android thermal modules lower the cost floor for intermittent users. Software solutions increasingly capture recurring revenue streams through cloud-based image analysis and fleet management dashboards.
FDA 510(k) clearance requirements shape medical diagnostic applications in the United States, while the EU AI Act imposes conformity obligations on devices with embedded diagnostic algorithms sold in European markets. REACH compliance governs the restricted substances in microbolometer manufacturing, directly affecting sensor supply chains and production location decisions. Stakeholders must monitor the divergence between medical-grade regulatory pathways and industrial tool classifications, as this boundary determines pricing power and channel access for emerging product categories.
Market Dynamics
The handheld thermal imaging equipment sector is undergoing a fundamental sensor architecture transition as solid-state uncooled microbolometers displace legacy cooled systems, compressing unit economics while expanding addressable use cases across industrial inspection workflows.
Growth Catalysts
- EU F-Gas Regulation:The European Union's phasedown of hydrofluorocarbon refrigerants is accelerating migration toward solid-state uncooled sensors that eliminate cryogenic cooling requirements entirely.
- Predictive maintenance mandates:Germany's industrial automation corridor now specifies handheld thermal units as standard equipment in asset reliability programs across automotive and chemical processing facilities.
- Vanadium oxide microbolometer advances:Improved thermal sensitivity in uncooled arrays is enabling medical diagnostic applications previously requiring expensive cooled infrared systems.
Market Restraints
- Microbolometer supply concentration:Foundry capacity for vanadium oxide and amorphous silicon sensor fabrication concentrates among a limited set of specialized semiconductor manufacturers.
- REACH compliance costs:Restricted substance regulations governing microbolometer manufacturing materials directly elevate production costs and constrain supplier location flexibility.
- Smartphone thermal module substitution:Low-cost iOS and Android attachments satisfy intermittent user needs, capping pricing power for entry-level standalone devices.
Strategic Opportunities
- Cloud-based fleet management platforms:Software subscriptions for thermal image analysis and device management are capturing recurring revenue streams beyond hardware sales.
- EU AI Act conformance services:Embedded diagnostic algorithms in European markets create demand for compliance consulting and certified algorithm validation.
- Firefighting procurement expansion:Industrialized economies are expanding portable thermal camera acquisition for search and rescue operations in structural fire response.
Industry Challenges
- FDA 510(k) clearance timelines:Medical diagnostic applications in the United States face extended regulatory review periods that delay product commercialization.
- Sensor calibration expertise gap:Field service organizations struggle to recruit technicians capable of maintaining NIST-traceable temperature measurement accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Thermal Imaging Equipment Market |
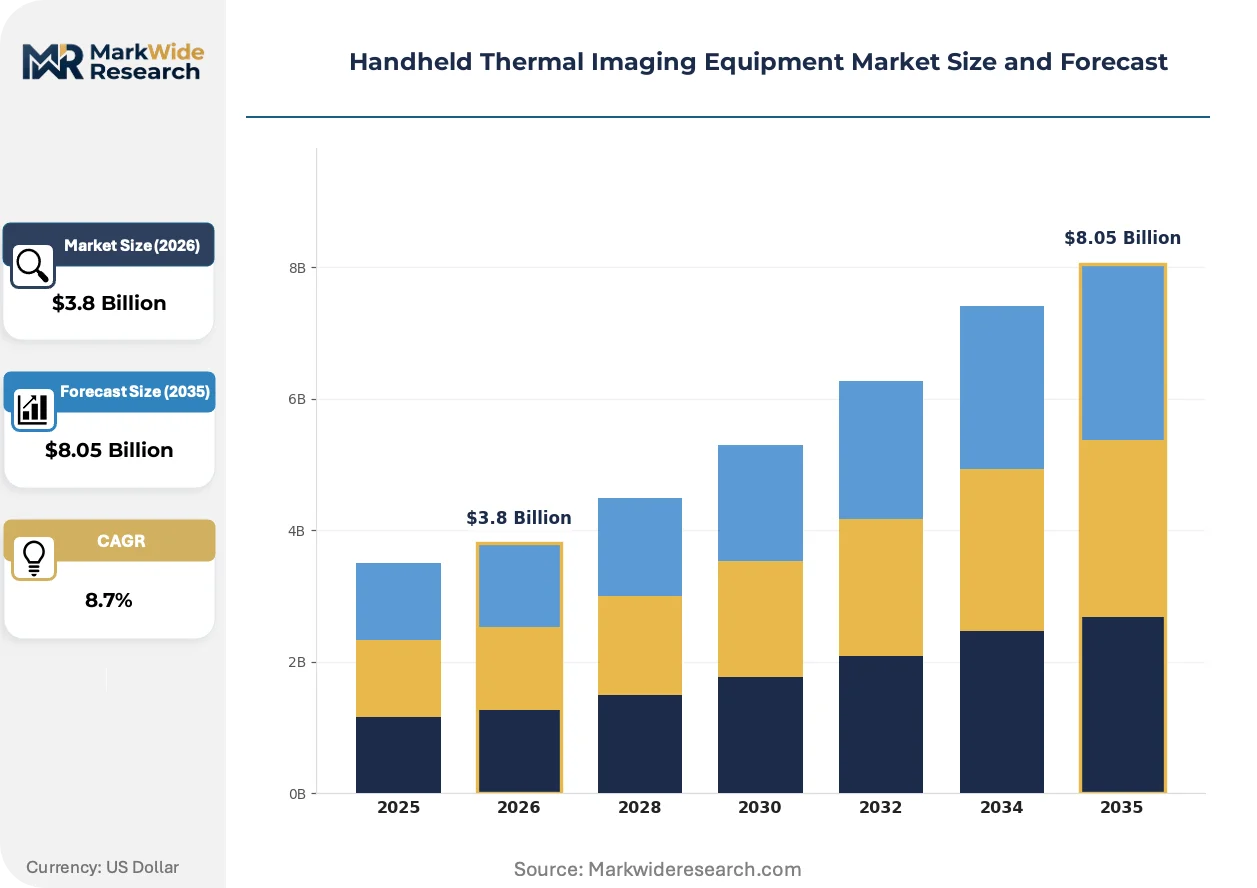
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Devices, Smartphone Attachments, Internet of Things (IoT) Devices, Software Solutions Application: Building Inspection, Electrical Inspection, Medical Diagnostics, Industrial Maintenance End User: Contractors, Healthcare Professionals, Facility Managers, Electrical Engineers Technology: Infrared Sensors, Thermal Sensors, Digital Imaging, Non-Contact Sensors |
| Companies Covered | Teledyne FLIR LLC, Fluke Corporation, L3Harris Technologies, Inc., BAE Systems, Leonardo S.p.A., Raytheon Technologies Corporation, Elbit Systems Ltd., Testo SE & Co. KGaA, Seek Thermal Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Thermal Imaging Equipment Market Shifts & Advancements
Three intersecting developments are reconfiguring how thermal imaging capabilities reach end users: sensor-level integration with mobile computing platforms, regulatory frameworks governing algorithmic diagnostics, and procurement models that unbundle hardware ownership from analytical access.
Multispectral sensor fusion is hybridizing thermal and visible-light imaging into unified handheld units. Industrial inspection teams in Germany's Ruhr manufacturing belt are adopting these combined systems for electrical and mechanical fault detection. The convergence is compressing the distinction between thermal specialists and general maintenance technicians, broadening the user base while reducing premium pricing for pure-play thermal hardware.
The EU AI Act imposes conformity obligations on devices with embedded diagnostic algorithms sold in European markets. Manufacturers must now document algorithm training data provenance and performance validation across demographic variations. Medical-grade thermal screening applications face the steepest compliance burden, driving some vendors to bifurcate product lines between regulated diagnostic and unregulated monitoring classifications.
Equipment leasing and performance-based rental contracts are displacing outright purchase for mid-tier industrial buyers. Firefighting departments and building inspection contractors in North America increasingly favor operational expenditure models that include calibration services and fleet analytics. This shift is concentrating procurement influence among specialized distributors capable of structuring multi-year service agreements.
Handheld Thermal Imaging Equipment Market Segmentation
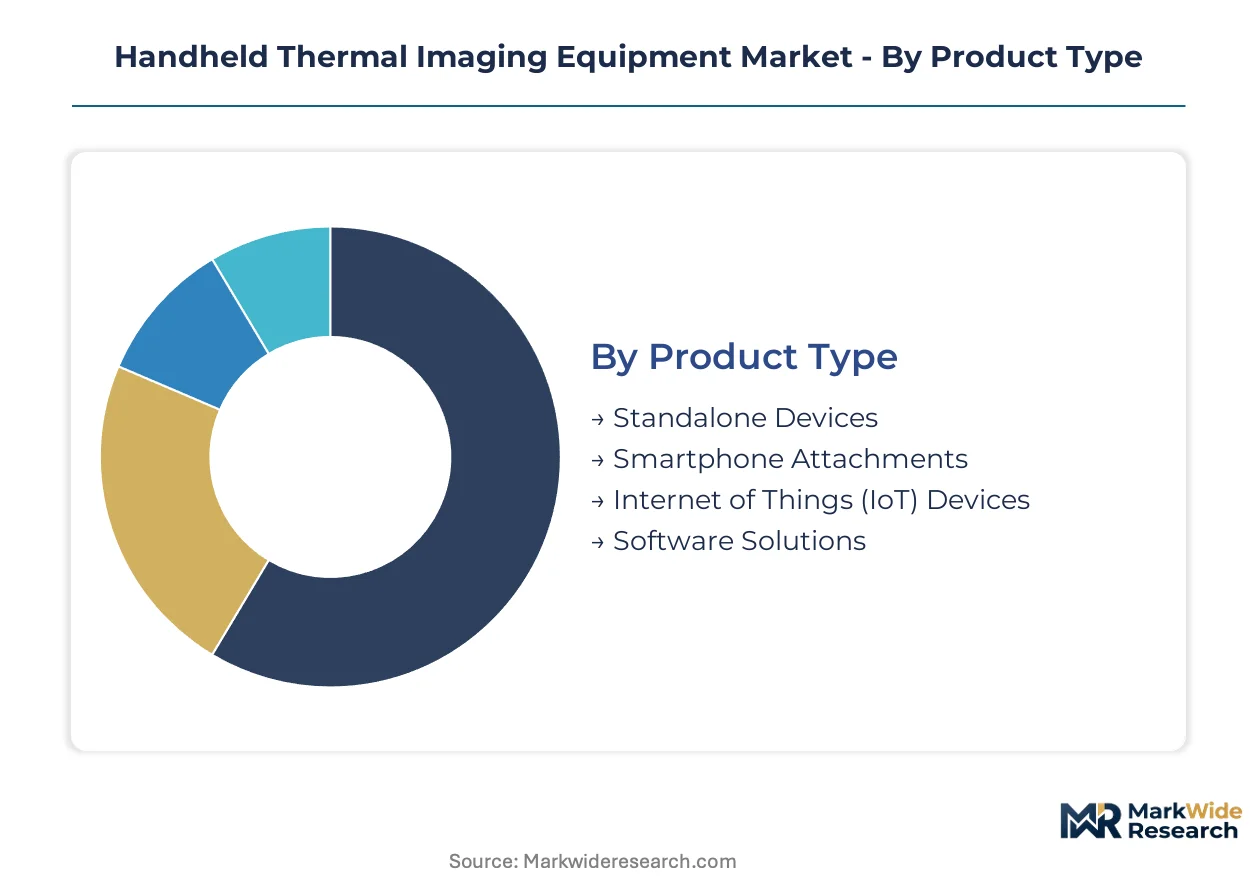
Segmentation in handheld thermal imaging equipment reveals how sensor miniaturization and software monetization are splitting value capture between hardware manufacturers and platform providers. Procurement patterns diverge sharply between capital-intensive industrial buyers and intermittent users seeking lower entry thresholds.
Product Type:
Mature standalone architectures coexist with emerging attachment formats that leverage external computing infrastructure.
- Standalone Devices:Integrated vanadium oxide microbolometer systems housed in ruggedized enclosures deliver calibrated thermal accuracy for professional field deployment. Firefighting departments across Germany, France, and Italy specify these units for structural search and rescue operations under EU F-Gas Regulation compliance mandates. REACH substance restrictions elevate manufacturing costs but lock in procurement preference where certification traceability matters.
- Smartphone Attachments:Modular thermal cameras interfacing with iOS and Android devices compress unit economics by eliminating dedicated displays and processors. Building inspection contractors in Spain and Poland adopt these for intermittent residential energy audits where capital constraints outweigh precision requirements. FDA 510(k) clearance gaps limit medical diagnostic deployment in the United States.
- Internet of Things (IoT) Devices:Network-connected thermal sensors enabling continuous remote monitoring in industrial asset management.
- Software Solutions:Cloud-based image analysis platforms and fleet management dashboards capturing recurring subscription revenue.
Standalone Devices retain volume leadership; Smartphone Attachments hold the steepest expansion curve.
Application:
Cost tier differentiation separates precision-critical diagnostics from routine inspection workflows.
- Building Inspection:Thermal envelope assessment and moisture intrusion detection in residential and commercial structures. German contractor markets specify handheld units for energy efficiency certification compliance under national building codes.
- Electrical Inspection:Non-contact detection of overloaded circuits, loose connections, and imbalanced loads in industrial power distribution. Predictive maintenance programs across automotive manufacturing clusters in Stuttgart and Wolfsburg mandate periodic thermal surveying of switchgear and motor control centers.
- Medical Diagnostics:Elevated skin temperature screening and peripheral vascular assessment requiring FDA 510(k) or EMA conformity pathways.
- Industrial Maintenance:Mechanical fault detection in rotating equipment and process vessel monitoring across chemical processing facilities.
Electrical Inspection commands premium pricing tiers; Smartphone-enabled Building Inspection gains share fastest.
End User:
Customer type fragmentation reflects diverging technical sophistication and procurement authority structures.
- Contractors:Independent building and electrical specialists purchasing through distributor channels with leasing options. North American firefighting contractors increasingly favor performance-based rental contracts including calibration services.
- Healthcare Professionals:Clinical staff deploying thermal screening under medical device regulatory frameworks. EU AI Act algorithmic conformity obligations impose documentation burdens on diagnostic algorithm deployments.
- Facility Managers:Corporate asset reliability teams integrating thermal inspection into scheduled maintenance protocols.
- Electrical Engineers:Design and commissioning specialists requiring NIST-traceable temperature measurement accuracy for system validation.
Contractors drive attachment-format volume; Healthcare Professionals face the steepest regulatory compliance barriers.
Technology:
Supply concentration in sensor foundries determines competitive access to core imaging capabilities.
- Infrared Sensors:Microbolometer arrays detecting 7.5–14 micrometer spectral radiation for thermal gradient visualization. Vanadium oxide fabrication capacity concentrates among specialized semiconductor foundries, constraining supply flexibility.
- Thermal Sensors:Solid-state uncooled architectures displacing legacy cryogenic cooled systems under EU F-Gas Regulation phasedown schedules.
- Digital Imaging:Visible-light fusion processors enabling multispectral hybrid systems for unified fault documentation.
- Non-Contact Sensors:Pyrometer and thermopile alternatives for single-point temperature measurement without spatial imaging.
Infrared Sensors anchor revenue concentration; Thermal Sensors climb the fastest on regulatory substitution effects.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation is accelerating sensor architecture transitions across industrialized markets. Firefighting procurement expansion and predictive maintenance mandates are concentrating demand in specific manufacturing corridors.
Germany
Industrial automation corridors in Stuttgart and Wolfsburg mandate handheld thermal units for electrical switchgear inspection. The EU F-Gas Regulation enforces solid-state uncooled sensor adoption. The Ruhr manufacturing belt deploys multispectral fusion systems for unified fault documentation in mechanical maintenance workflows.
United States
Firefighting departments expand portable thermal camera acquisition for structural search and rescue operations. FDA 510(k) clearance requirements shape medical diagnostic application pathways. Building inspection contractors in the Pacific Northwest favor performance-based rental contracts with embedded calibration services.
China
Industrial asset reliability programs specify continuous thermal monitoring for chemical processing facilities. GB standards and MIIT directives govern sensor manufacturing quality protocols. The Yangtze River Delta manufacturing cluster integrates handheld units into predictive maintenance protocols for automotive production lines.
France
Energy efficiency certification compliance drives residential building inspection procurement. The EU AI Act imposes conformity obligations on embedded diagnostic algorithms. The Île-de-France region specifies thermal envelope assessment tools for commercial structure audits under national building codes.
Japan
Automotive manufacturing clusters deploy thermal inspection for quality control in electric vehicle battery assembly. METI industrial standards guide non-contact temperature measurement accuracy requirements. The Kansai region around Osaka integrates handheld units into semiconductor fabrication facility maintenance protocols.
Handheld Thermal Imaging Equipment Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways. The vendor base separates into defense-grade certification holders, industrial workflow specialists, and mobile-integrated module providers. Three archetypes dominate: vertically integrated sensor foundries, distributor-network-dependent regional suppliers, and software-platform-anchored service providers. Capacity expansion in microbolometer fabrication and strategic partnerships for cloud-based fleet analytics represent the dominant competitive moves.
Within the defense-grade certification tier, Teledyne FLIR LLC and L3Harris Technologies, Inc. exemplify players leveraging foundry control and military clearance pathways respectively. Testo SE & Co. KGaA occupies a differentiated position among European industrial workflow specialists. Seek Thermal Inc. represents the mobile-integrated module archetype targeting intermittent users through smartphone attachment formats.
| Leading Market Players |
|---|
| Teledyne FLIR LLC |
| Fluke Corporation |
| L3Harris Technologies, Inc. |
| BAE Systems |
| Leonardo S.p.A. |
| Raytheon Technologies Corporation |
| Elbit Systems Ltd. |
| Testo SE & Co. KGaA |
| Seek Thermal Inc. |
| Others |
Supply & Pricing Matrix
Vanadium oxide microbolometer foundry capacity concentrates among specialized semiconductor manufacturers in the United States and Japan, anchoring margin capture at the sensor tier while compressing assembly-level returns for downstream device integrators.
Pricing Analysis
Certification level creates the primary spread between medical-grade FDA 510(k) cleared units and industrial tool classifications. Three-tier pricing structure across premium, standard, and economy levels reflects NIST-traceable calibration depth, ruggedization ratings, and embedded software analytics. Cost compression in entry-level standalone devices intensifies as smartphone thermal modules satisfy intermittent users. Contractors purchasing through distributor channels exhibit highest price sensitivity; healthcare professionals deploying under diagnostic pathways demonstrate lowest elasticity due to regulatory compliance requirements.
Supply Chain Analysis
Silicon wafer feedstock draws from foundry operations concentrated in Taiwan, South Korea, and the United States. Amorphous silicon deposition equipment and vanadium oxide sputtering targets constitute critical input dependencies. Single-source vulnerability characterizes specialized microbolometer lithography tooling. Distribution runs through industrial instrumentation distributors and defense procurement channels serving firefighting departments and predictive maintenance programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The handheld thermal imaging equipment sector is accelerating through solid-state uncooled sensor substitution mandated by EU F-Gas Regulation phasedown schedules, creating asymmetric returns for foundry-controlled players versus assembly-dependent competitors.
For Market Incumbents: Build certification moats through defense-grade clearance pathways that civilian competitors cannot replicate. Deepen backward integration into vanadium oxide sensor fabrication to sustain margin control across the value chain. Anchor position through multi-year fleet management service agreements with firefighting departments and industrial asset reliability programs. For New Entrants and Emerging Players: Mid-market commercial building inspection contractors in Spain and Poland represent the most penetrable entry point where capital constraints outweigh precision requirements. Smartphone-integrated thermal modules for intermittent residential energy auditors offer lowest competitive friction. Pursue cloud-based image analysis platform partnerships to capture recurring revenue without hardware manufacturing scale. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial instrumentation platforms lacking sensor foundry control. Five-to-ten year viability hinges on regulatory substitution tailwinds persisting through EU F-Gas and REACH compliance evolution. Watch for divergence between medical-grade diagnostic algorithm valuations and unregulated monitoring tool multiples as EU AI Act enforcement crystallizes.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Foundry Capacity Expansion | Captures margin concentration as EU F-Gas Regulation accelerates uncooled architecture adoption. |
| Cloud-Based Fleet Analytics Platform | Locks recurring revenue from firefighting departments and predictive maintenance programs. |
| EU AI Act Conformance Services | Monetizes compliance burden for embedded diagnostic algorithms in European medical applications. |
| Performance-Based Rental Contracts | Converts capital-constrained contractors from transactional purchases to operational expenditure models. |
| Multispectral Sensor Fusion Development | Broadens user base beyond thermal specialists to general maintenance technicians in German manufacturing clusters. |
Research Methodology
The analysis maps standalone devices, smartphone attachments, IoT sensors, and software solutions, each validated through primary interviews with maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads combined with secondary triangulation against SEC filings, customs trade data, EU F-Gas regulatory filings, and hospital procurement databases. Bottom-up unit demand modeling and top-down value chain verification ensure cross-method consistency.
Assumptions held fixed include EU F-Gas Regulation phasedown schedules, REACH substance restriction enforcement, and FDA 510(k) clearance pathway stability; variables tested include smartphone thermal module substitution rates and predictive maintenance program adoption intensity. The projection horizon spans product type, application, end user, and technology dimensions with CAGRs derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporate microbolometer foundry capacity expansion timelines and cloud-based fleet management platform penetration curves.
Macroeconomic conditions sit as an overlay; deviation in industrial capital expenditure cycles, chemical processing facility construction rates, or automotive manufacturing output would shift the trajectory. Forecasts reflect documented assumptions without guarantee of realization. Cross-checking against external benchmarks including industrial instrumentation trade association data and semiconductor foundry utilization reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global High-Speed Digital Camera Market
Imaging
Hyperspectral Imaging Market
Imaging
North America Digital Camera Market
Imaging
Wide Field Imaging Devices Market
Imaging
3D Sensing and Imaging Market
Imaging
Small CCTV Camera Market
Imaging
Middle East and Africa Thermal Imaging Systems Market
Imaging
PET Scanners Market
Imaging
Infrared Laser Night Vision Devices Market
Imaging
Pico Projector Market
Imaging
Live Cell Imaging Market
Imaging
360-Degree Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Global in Ceiling Camera Market
Imaging
Europe CT Market