
 Semiconductor CD-SEM Systems Market | 2026-2036
Semiconductor CD-SEM Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Semiconductor CD-SEM Systems Market Insights
REACH compliance is rebalancing the cost-of-entry calculus for CD-SEM vendors serving European fabs, forcing reformulation of electron-beam column materials and vacuum-system chemistries. Hitachi High-Tech leverages its installed base in Japan and Taiwan to sustain service revenue density across aging tool fleets. Applied Materials competes through process-tool integration, anchoring CD-SEM modules inside broader metrology suites. KLA Corporation dominates bare-wafer inspection, extending its architecture into patterned-wafer critical-dimension measurement.
Semiconductor CD-SEM systems are charged-particle microscopes that measure circuit feature dimensions at sub-nanometer precision using secondary-electron detection, with typical resolution below 0.5 nanometer and throughput rates calibrated to production-line takt times; their primary purpose is to verify that lithographic and etch processes hit target critical dimensions before downstream processing commits wafers to expensive fabrication steps. Standalone systems capture the largest share of capital expenditure as foundries segregate measurement from process equipment to maximize utilization flexibility. Electron-beam technology leads the technology dimension, though optical measurement competes for less demanding layers where speed outweighs resolution. Wafer inspection anchors application demand, while defect analysis represents the fastest-growing segment as yield-learning cycles compress at advanced nodes.
FDA oversight of semiconductor-based medical devices indirectly shapes CD-SEM requirements for diagnostic chip suppliers, while EPA regulations govern hazardous-material handling in electron-beam column manufacturing. Japan's METI coordinates national metrology standards that propagate through JIS documentation into vendor qualification protocols. Stakeholders must monitor how EU AI Act documentation requirements for automated measurement algorithms reshape software validation workflows without explicit hardware mandates.
Market Dynamics
Sub-3nm lithography roadmaps are compressing measurement cycle times, forcing foundries to decouple CD-SEM stations from process tools to sustain wafer throughput without sacrificing dimensional fidelity.
Growth Catalysts
- EUV lithography expansion:High-NA EUV deployment at logic fabs in Taiwan and South Korea multiplies critical-dimension verification points per wafer, expanding dedicated metrology footprints.
- EU Chips Act capital flows:European fabs in Dresden and Leuven are qualifying CD-SEM infrastructure under sovereignty mandates, redirecting procurement toward standalone measurement architectures.
- Yield-learning acceleration:Defect analysis cycles at advanced nodes now demand sub-nanometer repeatability, pulling electron-beam systems into frontline process control.
Market Restraints
- Column material scarcity:REACH restrictions on lead-bearing alloys and fluorinated vacuum greases constrain European vendor supply chains, elevating qualification costs for beam-column assemblies.
- Electron-beam throughput ceilings:Secondary-electron detection physics limits measurement speed to approximately 10-20 sites per wafer per hour, creating bottlenecks against optical alternatives for mature nodes.
- Specialized technician dependence:Vacuum-system maintenance and electron-optics alignment require rare skill sets concentrated in Japan and Germany, inflating service response times elsewhere.
Strategic Opportunities
- India semiconductor manufacturing:Gujarat and Karnataka fabs under the PLI scheme lack qualified metrology infrastructure, creating first-mover positioning for CD-SEM deployment.
- Multi-beam electron microscopy convergence:Arrayed beam architectures promise parallel measurement without resolution sacrifice, potentially collapsing throughput gaps with optical systems.
- Service revenue unbundling:Aging tool fleets in Japan and Taiwan create aftermarket parts and upgrade contracts independent of new system sales.
Industry Challenges
- Algorithm validation complexity:EU AI Act documentation requirements for automated edge-detection routines impose software verification workflows without explicit hardware mandates, stretching engineering resources.
- Legacy fleet integration:200mm and early 300mm CD-SEMs lack modern data interfaces, complicating fab-wide metrology-data lake architectures and requiring costly retrofit programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Semiconductor CD-SEM Systems Market |
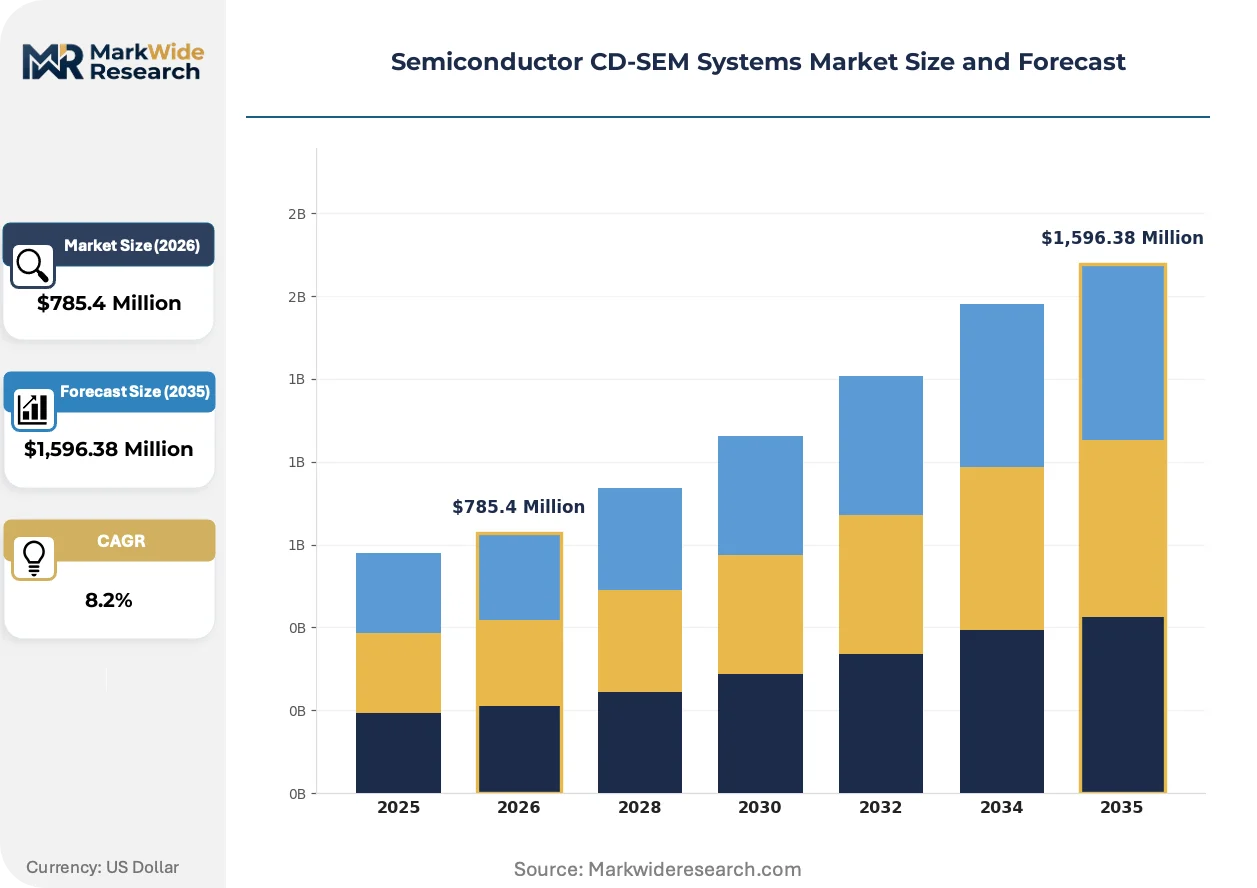
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,596.38 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Systems, Integrated Systems, Automated Systems, Hybrid Systems Technology: Electron Beam, Optical Measurement, X-ray Diffraction, Atomic Force End User: Semiconductor Manufacturers, Research Institutions, Electronics Firms, Firmware Developers Application: Wafer Inspection, Process Control, Quality Assurance, Defect Analysis |
| Companies Covered | Hitachi High-Tech, Applied Materials, Advantest, Holon, TCK, Wuhan Jingce Electronic Technology, Dongfang Jingyuan Electron, Wellrun Technology, KLA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Semiconductor CD-SEM Systems Market Trends and Innovations
Measurement architectures are fragmenting across resolution-throughput tradeoffs, with electron-beam systems defending precision-critical layers while optical and X-ray alternatives encroach on speed-sensitive applications.
Machine-learning-assisted image reconstruction is decentralizing human operator dependence in edge-detection workflows. Foundries in Taiwan are deploying neural-network-based measurement recipes that reduce recipe-development time from weeks to days. This compression is decentralizing metrology engineering expertise from centralized R&D hubs to individual fab sites.
Japan's METI has revised JIS B 7261 metrology standards to incorporate uncertainty quantification for sub-nanometer measurements, effective across all qualified supplier audits. Vendors must now submit extended gauge-study documentation for electron-beam systems. European fabs adopting these protocols are extending qualification timelines by four to six months.
Device makers are unbundling long-term service contracts from initial equipment purchases, treating metrology uptime as a separately negotiable operational expenditure. Memory manufacturers in South Korea are piloting performance-based maintenance agreements tied to measurement availability metrics rather than fixed preventive schedules. This shift is most pronounced among fabs operating mixed-vendor tool fleets where captive service capabilities reduce vendor lock-in.
Semiconductor CD-SEM Systems Market Segmentation
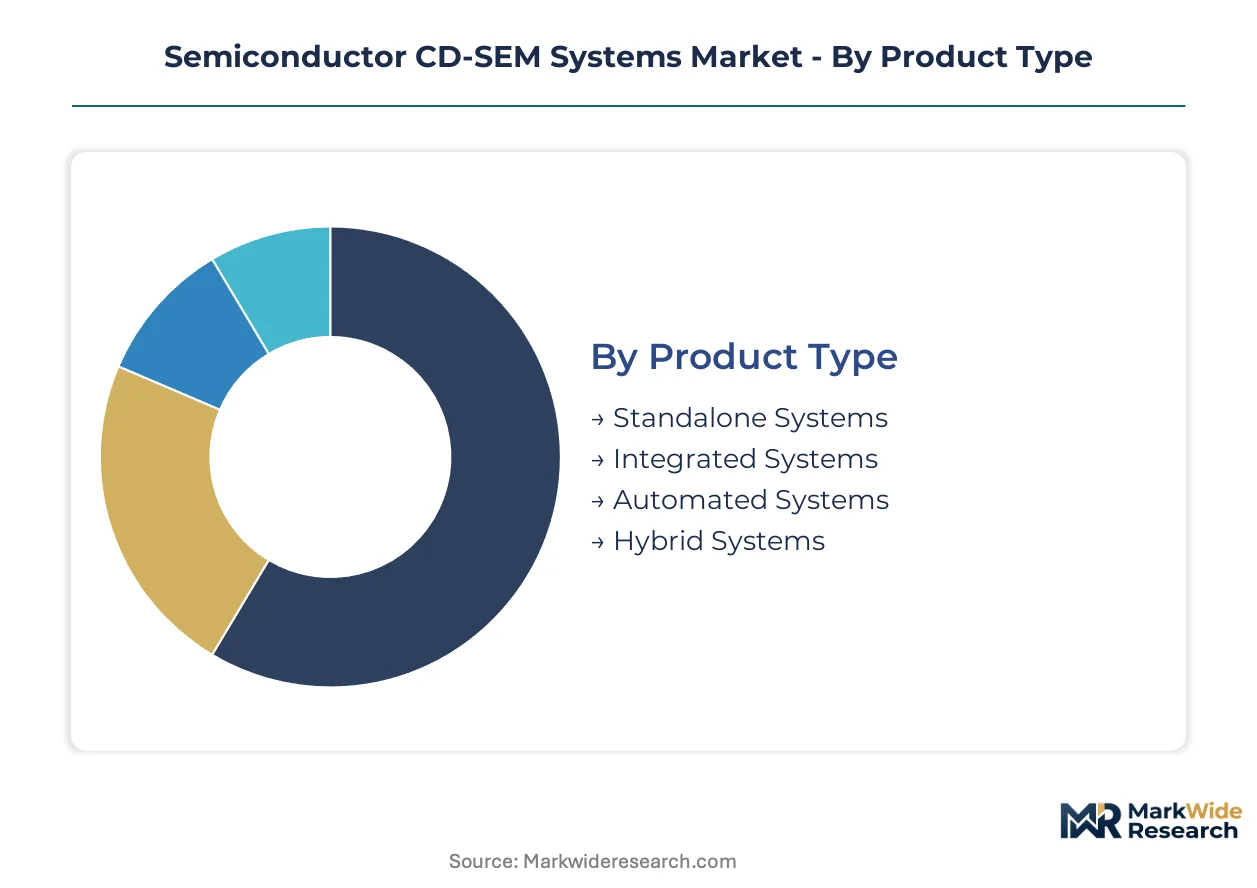
CD-SEM procurement patterns fragment sharply across equipment architecture, measurement physics, and operational workflows. Each segmentation axis reveals distinct capital allocation priorities among foundries, research consortia, and equipment suppliers.
Product Type:
Supply concentration in electron-beam column manufacturing tilts procurement toward configurations that maximize utilization flexibility and minimize vendor dependency.
- Standalone Systems:Dedicated measurement stations decouple critical-dimension verification from process equipment, enabling 24/7 metrology utilization independent of lithography or etch tool schedules. Taiwan and South Korea foundries anchor demand as sub-3nm nodes multiply measurement points per wafer.
- Integrated Systems:Modules embedded within broader process-tool suites sacrifice flexibility for footprint reduction and data latency advantages. Applied Materials anchors this architecture through metrology-suite integration at logic fabs prioritizing cleanroom space constraints.
- Automated Systems:Robotic wafer handling and recipe-driven operation reduce operator intervention for high-volume production lines.
- Hybrid Systems:Configurable architectures switch between standalone and integrated modes based on fab workflow requirements.
Standalone systems absorb the bulk of installed capacity; automated systems are expanding most quickly as labor costs climb in East Asian manufacturing clusters.
Technology:
Resolution-throughput tradeoffs drive divergent technology adoption, with precision requirements at advanced nodes defending electron-beam dominance despite speed penalties.
- Electron Beam:Secondary-electron detection delivers sub-0.5 nanometer resolution essential for EUV lithography verification. Physics-limited throughput of 10-20 sites per hour constrains deployment to critical layers where dimensional fidelity outweighs speed.
- Optical Measurement:Scatterometry and ellipsometry sacrifice resolution for throughput advantages at mature nodes where 1-2 nanometer precision suffices. Memory manufacturers in South Korea deploy optical systems for bulk metrology on repetitive array structures.
- X-ray Diffraction:Non-destructive lattice parameter measurement addresses stress and composition analysis in III-V compound semiconductors.
- Atomic Force:Mechanical probe scanning captures three-dimensional profiles for EUV mask defect characterization and process development.
Electron beam technology commands the dominant share of advanced-node qualification budgets; optical measurement is gaining share fastest in mature-node capacity expansions.
End User:
Capital intensity and technical sophistication requirements concentrate supply relationships among entities with sustained R&D commitments.
- Semiconductor Manufacturers:Foundries and IDMs in Taiwan, South Korea, and the United States drive volume procurement for production-line process control. EU Chips Act subsidies are redirecting some demand toward European fabs in Dresden and Leuven.
- Research Institutions:National laboratories and university cleanrooms prioritize flexibility and multi-technique compatibility over throughput. Japan's METI-funded consortia qualify new measurement protocols before industrial adoption.
- Electronics Firms:Fabless design houses and system companies deploy CD-SEM for failure analysis and supplier qualification.
- Firmware Developers:Algorithm vendors and software houses access electron-beam systems for training data generation and edge-detection validation.
Semiconductor manufacturers absorb the bulk of installed capacity; research institutions are expanding most quickly as public funding for domestic metrology infrastructure accelerates.
Application:
Yield economics and defect visibility requirements shape application prioritization across technology nodes and product categories.
- Wafer Inspection:Patterned-wafer critical-dimension mapping verifies lithography and etch process windows before committing wafers to costly downstream steps. Logic fabs in Taiwan deploy dedicated inspection stations at each EUV exposure layer.
- Defect Analysis:Root-cause identification for yield excursions demands sub-nanometer repeatability and three-dimensional reconstruction capabilities. Compression of yield-learning cycles at 2nm nodes is pulling electron-beam systems into frontline troubleshooting.
- Process Control:Statistical process control loops feed CD-SEM data back to lithography scanners for real-time overlay correction.
- Quality Assurance:Final verification before wafer shipment ensures customer specification compliance for automotive and medical device chip suppliers subject to FDA oversight.
Wafer inspection absorbs the bulk of installed capacity; defect analysis is climbing the fastest as advanced-node yield ramps intensify measurement frequency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hsinchu Science Park tax incentives concentrate Taiwan's CD-SEM procurement at leading-edge logic fabs, while South Korea's Yongin cluster drives memory-focused metrology demand. European Chips Act subsidies redirect capital toward Dresden and Leuven infrastructure, and India's PLI scheme seeds Gujarat and Karnataka for first-mover equipment positioning.
Taiwan
Sub-3nm EUV ramp at TSMC's Fab 18 and Fab 20 multiplies critical-dimension verification points per wafer. The National Development Council's Forward-Looking Infrastructure Plan funds domestic metrology qualification protocols. Hsinchu Science Park anchors standalone CD-SEM deployment density, with dedicated measurement stations decoupled from lithography tool schedules to maximize utilization flexibility.
South Korea
High-NA EUV adoption at Samsung's Pyeongtaek complex and SK hynix's Yongin campus expands electron-beam metrology footprints. The Ministry of Trade, Industry and Energy's K-Semiconductor Belt program subsidizes yield-learning infrastructure. Suwon and Icheon clusters prioritize defect analysis applications as 2nm yield ramps compress measurement cycle times.
United States
CHIPS and Science Act disbursements to Intel's Arizona and Ohio fabs reshore advanced-node process control capabilities. FDA oversight of diagnostic chip suppliers indirectly shapes CD-SEM requirements for medical device semiconductor manufacturers. Phoenix and Columbus metropolitan areas concentrate new fab construction with integrated metrology suite procurement.
Germany
EU Chips Act capital flows qualify Dresden's Bosch and Infineon fabs for standalone measurement architectures. REACH restrictions on lead-bearing alloys and fluorinated vacuum greases constrain beam-column assembly supply chains, elevating vendor qualification costs. Saxony's Silicon Saxony cluster extends qualification timelines by four to six months as ECHA compliance documentation requirements propagate.
India
Semiconductor PLI scheme disbursements seed Gujarat's Dholera and Karnataka's Mysuru fabs without qualified metrology infrastructure. BIS standards adoption for electron-beam systems lags industrial qualification needs. Ahmedabad and Bengaluru metropolitan areas create first-mover positioning opportunities for CD-SEM deployment as domestic manufacturing capacity scales from zero.
Semiconductor CD-SEM Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three discernible tiers. Electron-beam column manufacturing concentration in Japan and Germany creates supply-side bottlenecks that favor established incumbents with captive component sourcing. Strategic archetypes include integrated process-tool vendors, standalone metrology pure-plays, and emerging Chinese equipment suppliers. Dominant competitive moves center on service revenue unbundling from initial equipment sales and multi-beam architecture development to collapse throughput gaps with optical alternatives.
Within the diversified conglomerate tier, Hitachi High-Tech and Applied Materials exemplify contrasting strategic positions. Hitachi High-Tech leverages its installed base across aging tool fleets in Japan and Taiwan to sustain service revenue density independent of new system sales. Applied Materials anchors CD-SEM modules inside broader metrology suites, competing through process-tool integration rather than standalone measurement station dominance. Among pure-play specialists, KLA Corporation occupies a position extending bare-wafer inspection architectures into patterned-wafer critical-dimension measurement.
| Leading Market Players |
|---|
| Hitachi High-Tech |
| Applied Materials |
| Advantest |
| Holon |
| TCK |
| Wuhan Jingce Electronic Technology |
| Dongfang Jingyuan Electron |
| Wellrun Technology |
| KLA Corporation |
| Others |
Pricing and Supply Chain Analysis
Leading-edge logic foundries in Taiwan and South Korea concentrate procurement power through multi-system blanket orders, anchoring contract-based long-term offtake pricing with volume-scaled discounts and premium tiers for expedited beam-column delivery.
Pricing Analysis
Short-lead-time premiums of fifteen to twenty percent apply to electron-beam column assemblies sourced from Japanese suppliers, while spot inventory discounts emerge for refurbished vacuum-system components. Three-tier pricing structure across premium, standard, and economy levels separates EUV-qualified systems from mature-node configurations and legacy-tool upgrades. Cost compression in standard-tier equipment is intensifying because optical alternatives encroach on less demanding metrology layers. Memory manufacturers in South Korea exhibit highest price sensitivity due to repetitive array structures favoring throughput over resolution, while EU sovereignty-mandated fabs accept premium positioning to secure supply chain independence.
Supply Chain Analysis
Refurbishment flows from aging tool fleets in Japan and Taiwan feed secondary parts markets, extending component lifecycles and creating price benchmarks for new column assemblies. Electron-beam column manufacturing concentrates in Japan and Germany, with vacuum-system subcomponents sourcing from South Korean specialty gas suppliers and Swiss precision-machining houses. Single-source vulnerability constrains European vendor qualification timelines as REACH documentation requirements propagate through ECHA compliance channels. Distribution runs through direct vendor-fab relationships anchored by long-term service contracts, bypassing distributor intermediaries for critical metrology infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electron-beam column foundry capacity constraints prop pricing power for incumbent vendors, creating supply-constrained market dynamics favoring established players with captive component sourcing.
For Market Incumbents: Acquire multi-beam electron microscopy patent portfolios to defend against throughput disadvantages versus optical alternatives. Consolidate service infrastructure in Taiwan and South Korea to capture unbundled maintenance revenue from aging tool fleets. Capacity addition in Germany addresses REACH compliance bottlenecks while securing European qualification pathways. For New Entrants and Emerging Players: Domestic fab operators in Gujarat and Karnataka represent the most penetrable geography given absent qualified metrology infrastructure under India's PLI scheme. Partner with Japanese electron-optics specialists for beam-column technology licensing to bypass proprietary foundry relationships. Target defect analysis applications where yield-learning compression demands sub-nanometer repeatability unavailable from optical systems. For Investors and Strategic Acquirers: The window for entry favors pure-play metrology specialists with multi-beam development programs over diversified process-tool conglomerates. Long-term viability hinges on unbundled service revenue streams independent of cyclical equipment sales. Monitor EU AI Act documentation requirements as inflection indicator for software-validation cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Beam Architecture Development | Parallel electron-beam measurement collapses throughput gaps with optical scatterometry at EUV layers. |
| Service Revenue Unbundling | Standalone maintenance contracts reduce customer lock-in while capturing lifecycle value from aging tool fleets. |
| Backward Integration into Column Manufacturing | In-house electron-optics production insulates against Japanese supplier concentration and REACH material restrictions. |
| Geographic Expansion to India | First-mover positioning in Gujarat and Karnataka fabs seeds installed base before domestic competition emerges. |
| Regulatory Compliance Investment | EU AI Act documentation capabilities differentiate vendors for European sovereignty-mandated procurement. |
Research Methodology
SEC filings, Japanese industrial standards documentation, and EU regulatory databases formed the secondary backbone, cross-referenced against primary interviews with fab metrology directors, electron-beam system service engineers, and semiconductor procurement leads. Bottom-up equipment shipment tracking combined with top-down fab capex analysis enabled triangulation across vendor-reported bookings and customer-announced capacity expansions.
Historical trendline analysis of CD-SEM deployment intensity per thousand wafer starts informed projection frameworks across the analysis window, with segmentation modeling across equipment architecture, technology physics, end-user vertical, and application workflow. CAGRs derived from equipment replacement cycles, node-transition timelines, and metrology point multiplication at sub-3nm lithography stages incorporated EUV layer count expansion and yield-learning acceleration parameters.
Caveats apply where REACH material restriction enforcement, multi-beam technology maturation, or India fab construction delays could materially shift the outlook. Practitioners should monitor EU AI Act implementation timelines and High-NA EUV deployment schedules for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
APAC Image Sensors Market
Imaging
Camera Lens Market
Imaging
Fiducial Markers Market
Imaging
Ultra-Wide Field Imaging Device Market
Imaging
Global Mobile Image Sensor Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Compact Camera Module Market
Imaging
Event Camera Market
Imaging
Global Microbolometer Market
Imaging
Middle East and Africa IP Camera Market
Imaging
CCD Image Sensors Market
Imaging
Computer Aided Detection Market
Imaging
Photography Ring Flash Market
Imaging
PET Scanners Market
Imaging
Latin America IP Camera Market
Imaging
Photography Equipment Market