
 Handheld Imaging Systems Market | 2026-2036
Handheld Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Handheld Imaging Systems Market Foresight
The price-performance boundary between premium handheld imaging and commodity-grade devices is hardening. GE Healthcare leverages its deep installed base in radiology to sustain premium positioning across hospital systems. Butterfly Network anchors the democratization tier with semiconductor-based ultrasound architectures that undercut traditional transducer costs. Teledyne FLIR competes in thermal imaging by dominating defense and industrial channels with uncooled microbolometer supply chains.
Handheld imaging systems integrate compact sensor arrays, low-power signal processors, and wireless data pipelines into portable form factors weighing under two kilograms. These systems deliver real-time anatomical visualization, material defect detection, or thermographic mapping at the point of need rather than centralized laboratory infrastructure. Ultrasound product types command the largest revenue pool due to their clinical versatility across cardiac, abdominal, and musculoskeletal screening. AI integration technology captures the fastest expansion trajectory as on-device inference reduces dependency on cloud connectivity and enables sub-second diagnostic support in bandwidth-constrained environments. Wireless transmission technology remains mature but essential, forming the connectivity backbone that field technicians and research labs require for remote consultation workflows.
FDA 510(k) premarket notification requirements shape product development timelines and predicate device selection strategies for manufacturers targeting the United States. CE marking under the EU Medical Device Regulation imposes post-market surveillance obligations that favor larger players with established quality management systems. China's NMPA classification rules for innovative medical devices create accelerated review pathways for domestically developed handheld ultrasound systems. Stakeholders must monitor how divergent cybersecurity standards across FDA guidance, EU MDR annexes, and NMPA technical review principles reshape software validation costs and time-to-market for connected imaging platforms.
Market Dynamics
Semiconductor-based ultrasound architectures are compressing transducer manufacturing costs while FDA 510(k) clearance pathways compress time-to-market for connected imaging platforms. This dual squeeze is redrawing competitive boundaries between premium hospital-grade systems and democratized point-of-care devices.
Growth Catalysts
- Point-of-care diagnostics:Emergency medicine departments in the United States deploy portable ultrasound for triage acceleration. Real-time cardiac and abdominal screening at bedside reduces CT scan dependency.
- FDA 510(k) pathway:Streamlined premarket notification for portable ultrasound predicates accelerates commercialization timelines. Predicate device strategies favor iterative hardware-software combinations.
- AI on-device inference:Sub-second diagnostic support in bandwidth-constrained environments reduces cloud dependency. Edge computing architectures enable real-time anatomical annotation without connectivity.
Market Restraints
- CMOS sensor supply concentration:Semiconductor fabrication for ultrasound-on-a-chip concentrates in Taiwan and South Korea foundries. Geopolitical friction risks input cost volatility.
- EU MDR post-market surveillance:Quality management system obligations under CE marking favor larger players with established regulatory infrastructure. Smaller manufacturers face compliance cost barriers.
- Smartphone camera substitution:Dermatoscopy and superficial lesion imaging face displacement from high-resolution mobile optics with AI augmentation. Consumer-grade devices encroach on low-end clinical applications.
Strategic Opportunities
- Rural China penetration:County-level hospitals and township health centers remain underpenetrated for handheld ultrasound. NMPA accelerated review pathways for domestically developed systems lower entry barriers.
- Telemedicine integration:Wireless transmission pipelines enable remote consultation workflows for field technicians. Real-time specialist guidance expands addressable markets beyond hospital walls.
- AI-thermal convergence:Fusion of thermographic mapping with machine learning pattern recognition opens industrial predictive maintenance applications. Uncooled microbolometer data streams train on-device defect classification models.
Industry Challenges
- Software validation complexity:Divergent cybersecurity standards across FDA guidance, EU MDR annexes, and NMPA technical review principles reshape connected imaging platform development costs. Multi-jurisdiction submissions require parallel validation tracks.
- Legacy PACS integration:Hospital information system compatibility demands DICOM conformance testing and HL7 FHIR interface development. Procurement committees prioritize seamless electronic health record connectivity over standalone device performance.
- Specialized sonographer shortage:Point-of-care ultrasound adoption outpaces training pipeline capacity for image acquisition competency. Competency certification programs struggle to scale with device deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Handheld Imaging Systems Market |
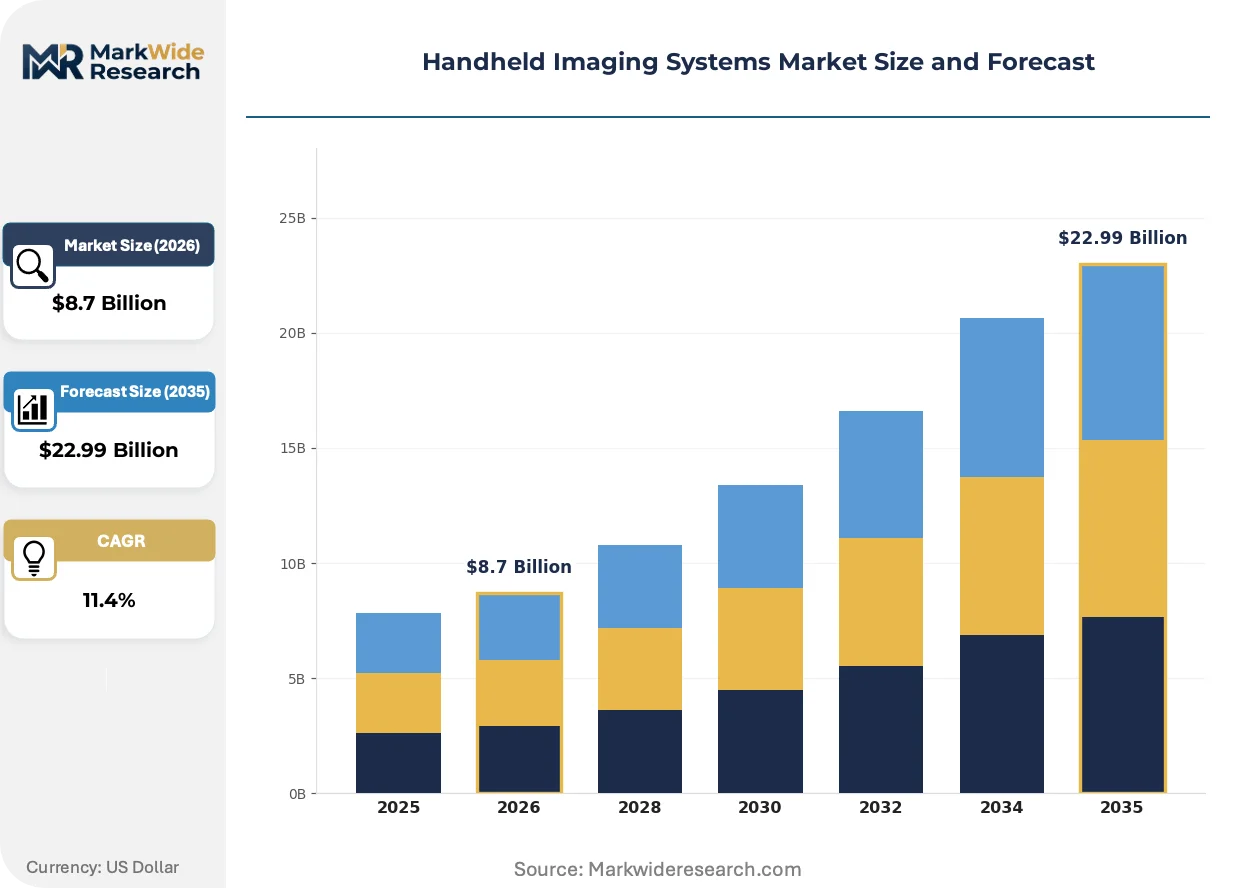
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound, X-ray, MRI, Thermography Application: Medical Diagnostics, Industrial Inspection, Veterinary Care, Research End User: Hospitals, Clinics, Research Labs, Field Technicians Technology: Digital Imaging, Wireless Transmission, AI Integration, 3D Rendering |
| Companies Covered | GE Healthcare, Siemens Healthineers, Philips Healthcare, Teledyne FLIR, Butterfly Network, Fujifilm Holdings, Samsung Electronics, Canon Medical Systems, Zebra Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Handheld Imaging Systems Market Shifts & Advancements
AI integration is compressing diagnostic timelines while regulatory divergence across jurisdictions fragments software validation approaches. Device manufacturers face simultaneous pressure to embed intelligence at the edge and navigate multiplying compliance frameworks.
Capacitive micromachined ultrasonic transducer (CMUT) technology is consolidating discrete piezoelectric element architectures into monolithic semiconductor fabrication. Cardiology departments in German university hospitals adopt CMUT-based handheld systems for point-of-care echocardiography. The technology is consolidating premium transducer supply chains by eliminating ceramic machining and acoustic matching layer assembly.
China's NMPA classification rules for innovative medical devices create accelerated review pathways for domestically developed handheld ultrasound systems. Domestic manufacturers gain timeline advantages over foreign competitors submitting through standard registration channels. Shenzhen and Shanghai medical device clusters exploit this regulatory asymmetry to capture hospital procurement tenders.
Subscription-based hardware access models displace capital equipment purchasing in US outpatient clinic chains. Per-scan pricing aligns device costs with utilization rates, reducing stranded asset risk for low-volume sites. Texas and Florida multi-site physician groups pioneer this operational expenditure shift, pressuring traditional distributor financing arrangements.
Handheld Imaging Systems Market Segmentation
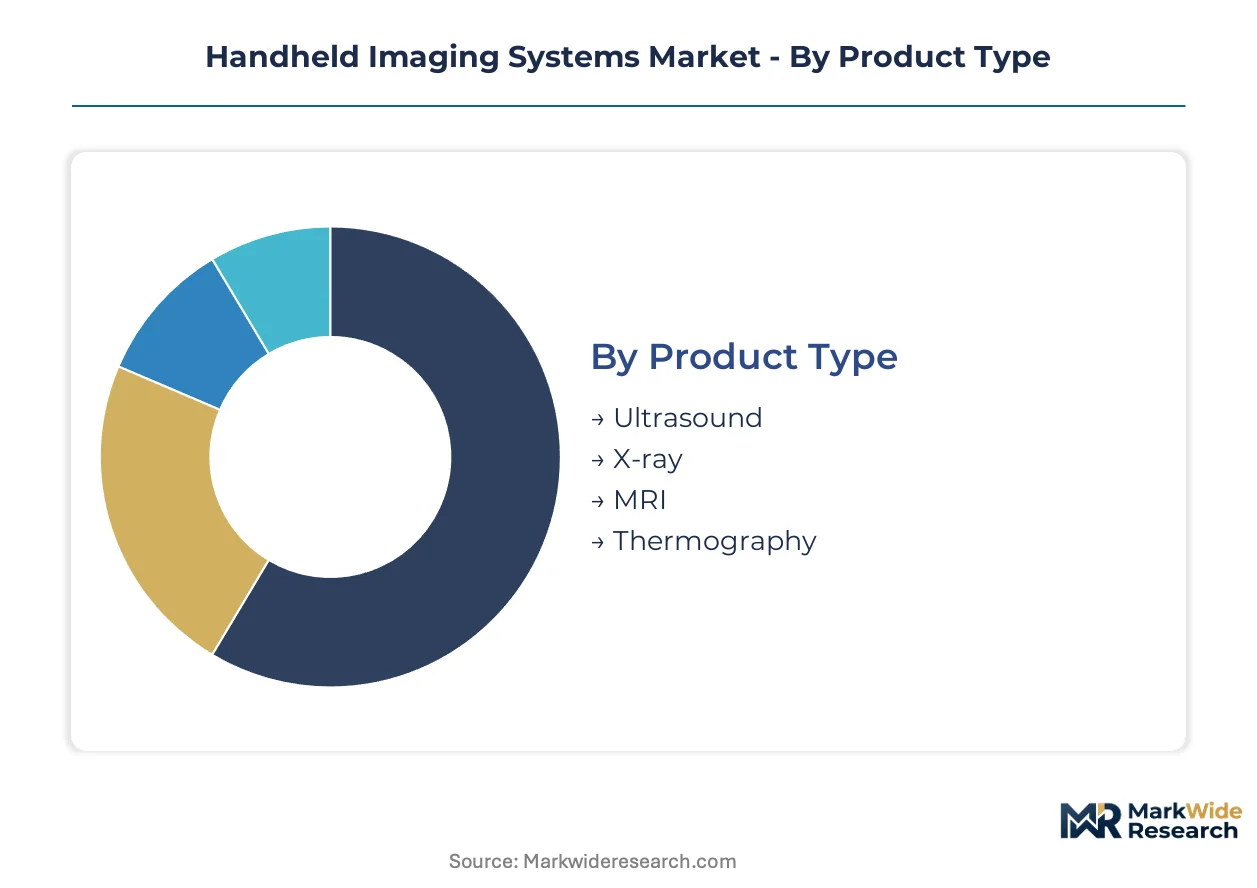
Handheld imaging systems fragment across four distinct taxonomies that reshape procurement patterns and R&D allocation. Product type determines sensor architecture and regulatory pathway complexity. Application focus dictates durability specifications and software feature sets. Understanding these intersections clarifies why certain configurations command premium positioning while others compete on unit economics.
Product Type:
Capital intensity varies sharply across modalities, with MRI and advanced ultrasound requiring semiconductor foundry partnerships while thermography leverages mature uncooled microbolometer supply chains.
- Ultrasound:Capacitive micromachined ultrasonic transducer architectures consolidate discrete piezoelectric elements into monolithic semiconductor fabrication. Cardiology departments in German university hospitals deploy these systems for point-of-care echocardiography, reducing CT scan dependency in emergency triage workflows.
- X-ray:Miniaturized cold cathode and carbon nanotube emitter technologies enable sub-kilogram form factors with diagnostic-grade resolution. Industrial inspection teams in Shenzhen manufacturing clusters adopt these for real-time weld quality verification on production lines.
- MRI:Compact permanent magnet designs and specialized radiofrequency coils deliver portable neurovascular imaging. The segment demands superconducting material supply chains and cryogenic cooling systems that limit manufacturer participation to well-capitalized players.
- Thermography:Uncooled microbolometer arrays packaged with edge AI processors enable predictive maintenance in Texas oilfield operations. The technology bypasses the ceramic machining and acoustic matching layer assembly required by premium ultrasound transducers.
Most installed capacity flows through Ultrasound. Expansion is steepest in Thermography.
Application:
Customer procurement criteria diverge across use cases, with medical diagnostics demanding FDA 510(k) clearance documentation and industrial inspection prioritizing IP67 environmental sealing and drop-test certification.
- Medical Diagnostics:Point-of-care deployment in United States emergency departments drives demand for wireless DICOM transmission and HL7 FHIR electronic health record integration. Real-time cardiac and abdominal screening at bedside accelerates triage decisions.
- Industrial Inspection:Predictive maintenance programs in German automotive manufacturing clusters require thermal pattern recognition for bearing failure detection. Field technicians in Texas energy corridors utilize portable ultrasound for pipeline corrosion assessment.
- Veterinary Care:Equine musculoskeletal screening and small animal abdominal imaging constitute the core demand pool. The segment tolerates lower resolution specifications than human diagnostics, opening entry points for cost-optimized sensor configurations.
- Research:Materials science laboratories in Shanghai academic clusters deploy handheld X-ray fluorescence for elemental composition analysis. Grant-funded procurement cycles create lumpy demand patterns distinct from commercial healthcare or industrial accounts.
Medical Diagnostics commands the dominant revenue share. Industrial Inspection is gaining share fastest.
End User:
Buying center composition varies by site type, with hospital procurement committees weighing PACS integration heavily while field technicians prioritize standalone operation and battery endurance.
- Hospitals:Radiology departments in United States health systems mandate seamless DICOM conformance and legacy PACS compatibility. Capital equipment committees prioritize electronic health record connectivity over standalone device performance metrics.
- Clinics:Outpatient chains in Texas and Florida pioneer subscription-based hardware access models with per-scan pricing. This operational expenditure shift reduces stranded asset risk for low-volume sites.
- Research Labs:Academic medical centers in Germany and China require programmable acquisition parameters and raw data export capabilities. Publication-grade image fidelity demands exceed clinical workflow requirements.
- Field Technicians:Remote oilfield and wind turbine maintenance crews in Saudi Arabia and the United Arab Emirates operate beyond reliable connectivity. On-device inference and extended battery operation become critical selection criteria.
Hospitals anchor the installed base. Clinics show the steepest adoption trajectory.
Technology:
Software validation complexity and hardware bill-of-materials costs concentrate investment requirements in AI integration and 3D rendering capabilities, while wireless transmission leverages commoditized radio modules.
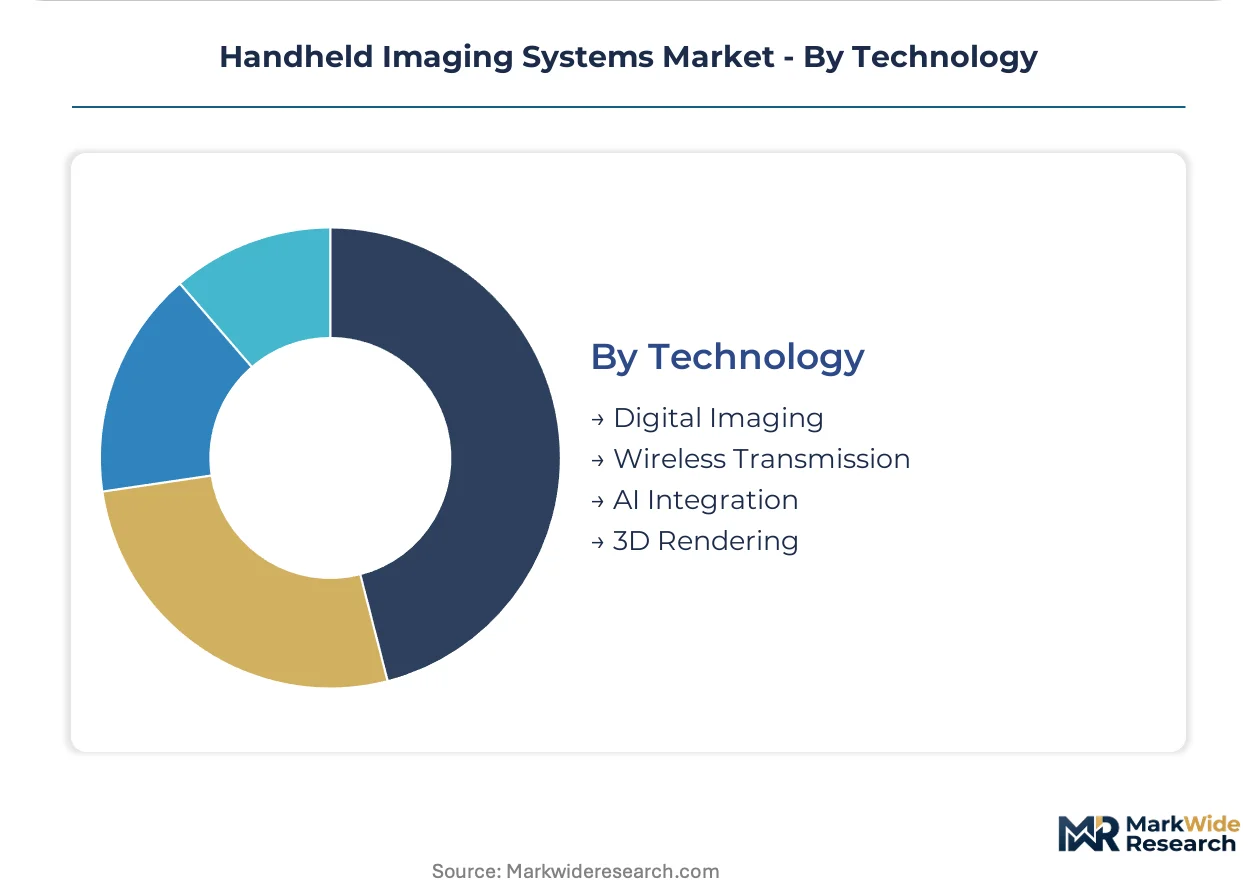
- Digital Imaging:CMOS and CCD sensor arrays with dedicated image signal processors deliver real-time anatomical visualization. The architecture underpins all other technology combinations as the foundational imaging layer.
- Wireless Transmission:Wi-Fi 6 and 5G NR modules enable remote consultation workflows for bandwidth-constrained environments. The technology forms the connectivity backbone that field technicians require for specialist guidance.
- AI Integration:On-device neural network inference reduces cloud dependency and enables sub-second diagnostic support. Edge computing architectures train on-device defect classification models using thermographic mapping data streams.
- 3D Rendering:Volumetric reconstruction from sequential 2D acquisitions creates navigable anatomical models. Cardiology departments deploy these capabilities for structural heart intervention planning.
Digital Imaging carries the largest installed base. AI Integration exhibits the most rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiology-trained sonographers concentrate in United States metropolitan hospital systems, while semiconductor fabrication talent pools in Taiwan and South Korea supply transducer components. This workforce geography shapes where handheld imaging systems achieve clinical penetration versus component sourcing.
United States
Emergency medicine departments deploy portable ultrasound for triage acceleration in Texas and Florida multi-site clinic chains. FDA 510(k) premarket notification requirements compress commercialization timelines for predicate device strategies. Boston academic medical centers pioneer AI-integrated point-of-care echocardiography workflows.
Germany
Cardiology departments in Bavarian university hospitals adopt CMUT-based handheld systems for structural heart intervention planning. CE marking under EU MDR imposes post-market surveillance obligations favoring established quality management systems. Stuttgart automotive manufacturing clusters utilize thermal imaging for predictive maintenance programs.
China
County-level hospitals and township health centers in Sichuan-Chongqing remain underpenetrated for handheld ultrasound deployment. NMPA classification rules create accelerated review pathways for domestically developed systems. Shenzhen medical device clusters exploit regulatory asymmetry to capture hospital procurement tenders.
Japan
Materials science laboratories in Kanto academic clusters deploy handheld X-ray fluorescence for elemental composition analysis. METI standards coordination shapes domestic device certification requirements. Osaka-based industrial inspection teams adopt miniaturized cold cathode systems for weld quality verification.
South Korea
Seoul Capital Area health systems integrate wireless DICOM transmission into legacy PACS infrastructure. MFDS medical device regulations align with international harmonization frameworks. Busan-Ulsan manufacturing corridors source CMOS sensor arrays from domestic foundry partnerships.
Handheld Imaging Systems Market Competitive Landscape
Top-tier vendors anchor hospital procurement committees through legacy PACS integration capabilities, while semiconductor-native entrants undercut traditional transducer economics. The market structures around three tiers: premium radiology-system incumbents, democratization-focused chip-architecture specialists, and thermal-imaging defense contractors repurposing uncooled microbolometer supply chains. Dominant competitive moves include strategic partnerships for AI training data access and backward integration into semiconductor foundry capacity.
Within the premium-tier vector, GE Healthcare and Siemens Healthineers occupy positions sustained by deep installed bases in radiology departments. Butterfly Network exemplifies the democratization archetype through semiconductor-based ultrasound architectures. Teledyne FLIR represents defense-channel thermal imaging specialists expanding into industrial predictive maintenance applications.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Philips Healthcare |
| Teledyne FLIR |
| Butterfly Network |
| Fujifilm Holdings |
| Samsung Electronics |
| Canon Medical Systems |
| Zebra Technologies |
| Others |
Supply & Pricing Matrix
Semiconductor fabrication engineers in Taiwan and South Korea command wage premiums that compress margin spreads between economy-tier handheld ultrasound devices and premium radiology-grade systems. Labor-cost differentials at foundry level propagate through to hospital procurement committees evaluating CMUT-based versus traditional piezoelectric architectures.
Pricing Analysis
Bundled hardware-subscription packages separate from unbundled capital equipment transactions across US outpatient clinic chains. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) predicate complexity and AI inference capability depth. Pricing pressure stems from semiconductor-native entrants undercutting ceramic transducer economics. Price-sensitive county-level hospitals in China favor domestically developed NMPA-accelerated systems over import premiums.
Supply Chain Analysis
Regional distribution centers in Shenzhen and Shanghai medical device clusters feed hub-and-spoke patterns into township health centers and county hospitals. Semiconductor fabrication concentrates in Taiwan, South Korea, and select US foundries for CMOS sensor arrays and CMUT wafers. Raw material dependencies span lithium niobate crystals, rare-earth magnet alloys, and uncooled microbolometer vanadium oxide layers. Single-source vulnerability in Taiwan foundry capacity threatens input cost stability. Distribution runs through authorized medical device distributors with NMPA or FDA establishment registration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in handheld imaging hinges on semiconductor cost-down curves compressing transducer economics while AI-augmented premium tiers sustain pricing power through diagnostic workflow integration.
For Market Incumbents: Anticipate semiconductor-native entrants disrupting ceramic transducer supply chains by securing captive foundry capacity or exclusive CMUT licensing arrangements. Defend hospital procurement relationships through accelerated HL7 FHIR interface development and legacy PACS seamlessness. Prioritize backward integration into edge-AI training data pipelines to differentiate on-device inference capabilities. For New Entrants and Emerging Players: The price-point gap between premium radiology-grade systems and economy-tier point-of-care devices creates white-space at mid-tier subscription pricing for US multi-site clinic chains. Target underpenetrated county hospitals in Sichuan-Chongqing with NMPA-accelerated domestic registration pathways. Pursue telemedicine-integrated go-to-market partnerships with rural health network operators. For Investors and Strategic Acquirers: Hospital system procurement consortia represent the most active acquirer in this space, seeking point-of-care ultrasound capabilities to reduce CT scan dependency. Long-term viability favors targets with semiconductor fabrication partnerships and FDA 510(k) predicate libraries. Watch for CMUT patent portfolio consolidation as inflection signal for transducer architecture transition.| Strategic Initiative | Industry Significance |
|---|---|
| Semiconductor Foundry Partnership | Secures CMUT wafer supply from Taiwan foundries for cost-competitive transducer production. |
| FDA 510(k) Predicate Expansion | Accelerates clearance timelines for iterative handheld ultrasound hardware-software combinations. |
| Hospital System Partnership | Locks in multi-year subscription contracts with Texas and Florida outpatient clinic chains. |
| AI Training Data Acquisition | Builds proprietary echocardiography annotation libraries for on-device diagnostic support. |
| NMPA Accelerated Registration | Exploits regulatory asymmetry to capture county hospital procurement tenders in China. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged hospital procurement committee members, biomedical engineers specializing in point-of-care ultrasound, GPO contracts managers, and semiconductor foundry supply chain directors. Secondary sources included FDA 510(k) premarket notification databases, NMPA innovative medical device registration records, hospital procurement tender databases, and CMUT patent filing disclosures. Bottom-up unit shipment estimates triangulated against top-down revenue aggregation across product type and application segments.
Rate-of-change decomposition separates volume growth from price-mix effects across the analysis window. Segmentation dimensions modeled include product type, application focus, end-user category, and technology integration level. CAGRs derived from logistic diffusion curves fitted to adoption data across bandwidth-constrained and connected environments. Forecast inputs incorporated NMPA review pathway utilization rates and AI inference chip cost-down trajectories.
The model assumes a particular technology adoption path; alternative pathways for CMUT versus piezoelectric transducer architectures would alter the outlook. Forecasts reflect documented assumptions regarding regulatory clearance timelines, foundry capacity expansion, and reimbursement code adoption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Digital Microscope Market
Imaging
Industrial Machine Vision Market
Imaging
360-Degree Camera Market
Imaging
CMOS Smartphone Camera Lens Market
Imaging
Side View Camera System Market
Imaging
Photoacoustic Microscope Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Machine Vision System Market
Imaging
Wide Field Imaging Devices Market
Imaging
Mobile Imaging Services Market
Imaging
Gel Imaging Documentation Market
Imaging
Thermal Imaging Market
Imaging
Asia-Pacific Image Recognition Market
Imaging
Europe Image Sensors Market
Imaging
Infrared Imaging Market
Imaging
Middle East and Africa Thermal Imaging Systems Market