
 Thermoplastic Starch (TPS) Market | 2026-2036
Thermoplastic Starch (TPS) Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Starch (TPS) Market Analytics
Multi-source sourcing of native starch feedstocks is broadening across the TPS value chain as compounders seek supply security beyond traditional corn and potato bases. Novamont S.p.A. leverages its Italian agricultural partnerships to secure waxy maize supply chains, while BASF anchors European distribution through its Ludwigshafen polymer compounding infrastructure. Biome Bioplastics specializes in custom TPS alloy formulations for UK foodservice clients, competing against imported flexible film alternatives.
Thermoplastic Starch denotes a biodegradable thermoplastic derived from gelatinized native starch plasticized with polyols, typically processed via extrusion or injection molding at moisture-controlled temperatures between 120°C and 180°C to yield materials with tensile properties tunable from 5 MPa to 40 MPa depending on glycerol content and compatibilizer selection. Flexible Films within the product type dimension command the dominant volume position due to bread bag and produce wrap conversions, whereas Rigid Containers capture higher margin pools in premium chilled ready-meal trays. The Application split shows Packaging absorbing the majority of current output, with Agriculture emerging as the fastest-expanding destination through mulch film and controlled-release fertilizer coating trials.
The EU Green Deal and REACH framework restrict persistent microplastic additives, while EFSA migration limits govern TPS contact with fatty food matrices, collectively elevating compliance costs for non-certified compounders. FDA food contact notifications and USDA bio-preferred procurement guidelines shape parallel qualification pathways for North American market entry. Stakeholders must monitor evolving compostability certification interoperability between EN 13432, ASTM D6400, and home-composting standards to avoid specification fragmentation across customer portfolios.
Market Dynamics
EU Green Deal enforcement is compressing petroleum-based plastic margins while redirecting procurement budgets toward certified biodegradable alternatives, forcing compounders to reconfigure feedstock sourcing and certification pipelines.
Growth Catalysts
- REACH microplastic restrictions:Persistent additive bans under ECHA guidance are eliminating conventional flexible film competitors from EU retail supply chains.
- Food packaging mandates:German, French, and Italian supermarket chains now specify EN 13432-certified trays and wraps in vendor contracts.
- Native starch diversification:Waxy maize and potato starch processing advances are reducing compounder dependence on corn price cycles.
Market Restraints
- Glycerol price volatility:Polyol plasticizer costs fluctuate with biodiesel byproduct markets, squeezing TPS compounder margins unpredictably.
- Moisture sensitivity:TPS films require barrier coatings or multilayer construction for high-humidity applications, adding processing complexity.
- Composting infrastructure gaps:Industrial composting facility coverage remains uneven across Eastern European member states.
Strategic Opportunities
- Agriculture mulch films:Controlled-release fertilizer coatings and soil-biodegradable mulch represent untapped volume pools beyond packaging.
- Home-composting certification:TÜV Austria OK Compost HOME and similar standards unlock premium positioning in consumer-facing applications.
- Polymer alloy development:TPS-PBAT and TPS-PLA blends are opening performance gaps that pure biopolymers cannot fill.
Industry Challenges
- Extrusion technician scarcity:Moisture-controlled processing between 120°C and 180°C demands specialized operators that compounders struggle to recruit.
- Certification timeline compression:EFSA migration studies and EN 13432 testing cycles extend product qualification to 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Starch (TPS) Market |
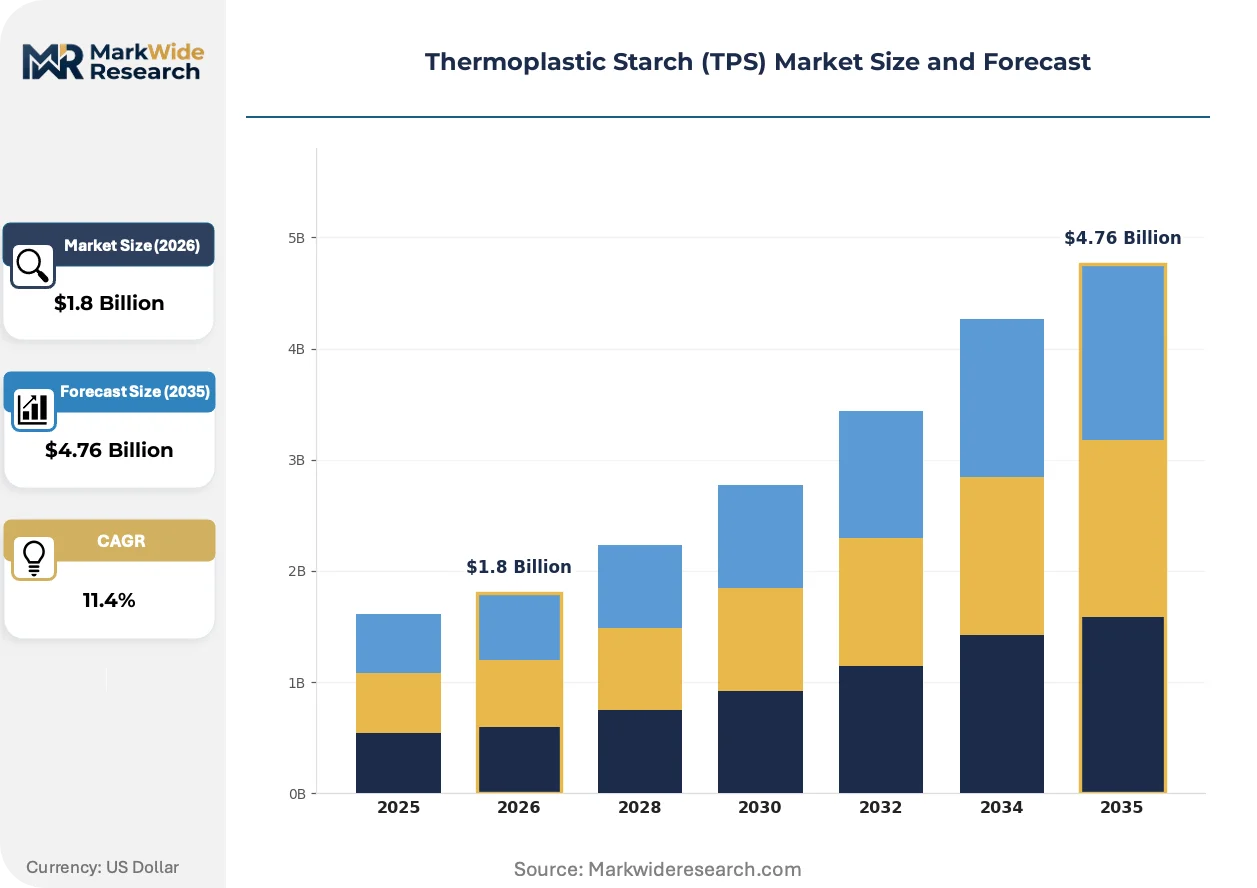
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Films, Rigid Containers, Coatings, Foams Application: Packaging, Agriculture, Automotive, Consumer Goods Form: Granules, Pellets, Sheets, Powders End User: Food Industry, Textile Sector, Electronics, Personal Care |
| Companies Covered | BIOTEC Biologische Naturverpackungen GmbH & Co. KG, Rodenburg Biopolymers, AGRANA, Kuraray Co., Ltd, BioLogiQ Inc., BASF, Novamont S.p.A, Grupa Azoty, Biome Bioplastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Starch (TPS) Market Evolving Landscape
Reactive extrusion with in-situ compatibilization is rewriting process economics, allowing compounders to substitute functionalized additives for costly multilayer film constructions while maintaining mechanical performance.
Twin-screw reactive extrusion systems with glycidyl methacrylate grafting is overtaking conventional single-screw lines in TPS-PBAT alloy production. Italian and German flexible film converters are retrofitting existing lines at pace. This technology is overtaking batch compounding by collapsing residence time from hours to minutes while improving phase dispersion.
EU Green Deal packaging and packaging waste regulations are mandating recycled content quotas and extended producer responsibility fees that disadvantage fossil-based plastics. Compounders are accelerating EN 13432 and ASTM D6400 dual certification to maintain transatlantic optionality. Flexible film specifications in French retail procurement are now requiring home-compostable grades alongside industrial certification.
Supermarket private-label sustainability scorecards are rewriting supplier selection criteria across Western European supply chains. Tier-one packaging vendors are consolidating specification-setting power while smaller compounders face exclusion without third-party certification. German discounters and French hypermarkets are the most aggressive in mandating biodegradable tray specifications from their film suppliers.
Thermoplastic Starch (TPS) Market Segmentation
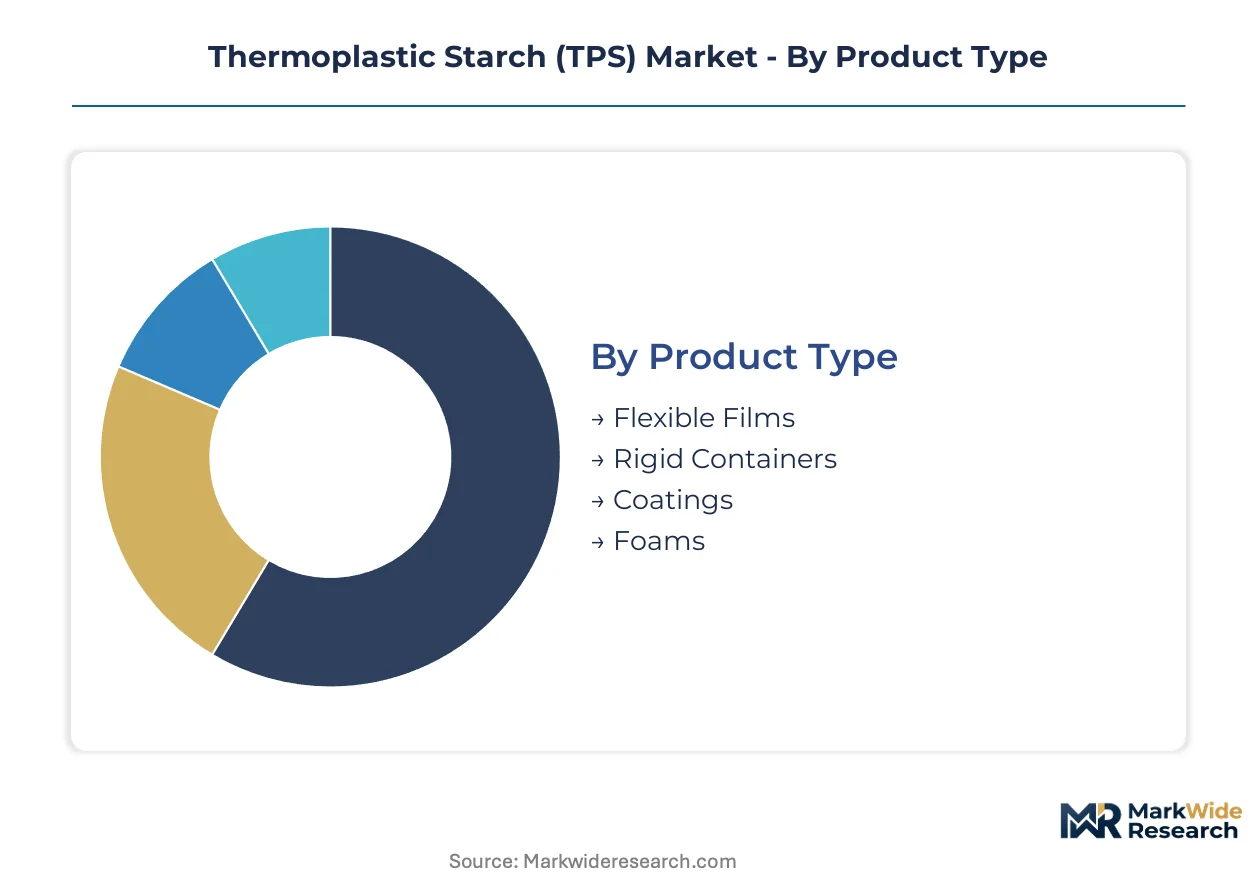
TPS market segmentation reveals how processing constraints and certification requirements fragment commercial opportunity across incompatible specification tiers. Compounders must align product development with distinct moisture sensitivity profiles and composting infrastructure availability in target geographies.
Product Type:
Supply concentration in flexible film extrusion lines across Germany and Italy shapes margin distribution, with converters prioritizing equipment compatibility over material innovation.
- Flexible Films:Extruded TPS sheets plasticized with glycerol achieve 10-25 MPa tensile strength for bread bags and produce wraps. German and French supermarket chains mandate EN 13432 certification for these specifications, compressing qualification timelines for compounders serving retail supply chains.
- Rigid Containers:Injection-molded trays with higher amylose content resist deformation at 4-8°C for chilled ready-meal applications. Italian converters capture premium pricing through multilayer constructions combining TPS with barrier coatings for fatty food contact compliance under EFSA migration limits.
- Coatings:Aqueous TPS dispersions provide paperboard grease resistance for fast-food packaging.
- Foams:Expanded starch structures serve protective packaging and seedling tray niches with limited current volume.
Today's leader: Flexible Films. Tomorrow's challenger: Rigid Containers.
Application:
Cost tier stratification separates commodity packaging from specialty agriculture trials, with certification burden determining viable entry points.
- Packaging:Food contact applications absorb the majority of TPS volume, spanning flexible wraps, rigid trays, and coated paperboard. EU Green Deal packaging waste regulations and REACH microplastic restrictions redirect procurement budgets from polyethylene toward certified biodegradable alternatives in Western European retail chains.
- Agriculture:Soil-biodegradable mulch films and controlled-release fertilizer coatings represent the steepest expansion trajectory, though industrial composting infrastructure gaps in Eastern European member states constrain near-term deployment at scale.
- Automotive:Interior trim panels and noise-dampening components utilize TPS-PLA blends for weight reduction targets.
- Consumer Goods:Disposable cutlery and tableware compete with PLA and bagasse alternatives on price-performance positioning.
Packaging commands current procurement volumes. Agriculture gains share fastest where soil-biodegradable certification aligns with regional composting infrastructure.
Form:
Volume concentration in pellet supply reflects compounder preference for standardized feedstock handling across diverse converter equipment bases.
- Granules:Irregular particles suit batch compounding operations and small-scale injection molding, prevalent in UK foodservice equipment trials.
- Pellets:Cylindrical extrudates with controlled moisture content enable continuous processing on twin-screw lines. German and Italian flexible film converters specify pellet diameter tolerances for automated feeding systems, consolidating procurement around established compounders with Ludwigshafen and Novara production assets.
- Sheets:Calendered TPS requires immediate thermoforming to prevent moisture absorption.
- Powders:Fine-ground starch serves coating applications and reactive extrusion feedstock.
Pellets dominate converter procurement. Granules retain niche relevance for custom alloy development.
End User:
Customer type fragmentation across food, textile, electronics, and personal care sectors forces compounders to maintain parallel certification portfolios with incompatible migration and compostability standards.
- Food Industry:Packaging vendors serving German discounters and French hypermarkets specify EN 13432-certified TPS for tray and wrap applications. EFSA fatty food contact limits and moisture barrier requirements drive multilayer film adoption with glycidyl methacrylate compatibilization.
- Textile Sector:Sizing agents and temporary fabric coatings utilize TPS water solubility for processing efficiency.
- Electronics:Antistatic packaging and biodegradable trays for component shipping remain underdeveloped.
- Personal Care:Capsules and encapsulation matrices for controlled ingredient release compete with microplastic-free alternatives.
Food Industry sets specification standards. Personal Care offers margin expansion through home-compostable certification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ludwigshafen's polymer compounding cluster anchors European TPS manufacturing capacity, with German flexible film converters supplying supermarket chains across Western Europe. Regulatory pressure from Brussels accelerates procurement shifts toward certified biodegradable alternatives in food packaging supply chains.
Germany
German discounters and hypermarkets mandate EN 13432-certified biodegradable trays from their packaging vendors. ECHA's REACH microplastic restrictions eliminate conventional petroleum-based film competitors from retail supply chains. Ludwigshafen's BASF compounding infrastructure and Bavarian flexible film extrusion lines concentrate production capacity for bread bag and produce wrap specifications.
France
French retail procurement now requires home-compostable TPS grades alongside industrial certification for private-label sustainability scorecards. EU Green Deal packaging waste regulations impose recycled content quotas that redirect budgets from polyethylene toward biodegradable alternatives. The Paris Basin and Rhône-Alpes regions host compounders serving hypermarket chains with chilled ready-meal tray specifications.
Italy
Italian converters capture premium pricing through multilayer TPS constructions with barrier coatings for fatty food contact compliance. Novamont S.p.A. leverages agricultural partnerships in the Po Valley to secure waxy maize feedstock supply chains. Northern Italian flexible film production clusters around Novara and Milan supply specifications for produce wrap and bakery applications.
United Kingdom
UK foodservice clients drive demand for custom TPS alloy formulations competing against imported flexible film alternatives. EFSA migration limits govern material contact with fatty food matrices, elevating compliance costs for non-certified compounders. Biome Bioplastics anchors development activity in the South East, with trial deployments spanning disposable cutlery and coated paperboard applications.
Netherlands
Dutch compounders benefit from Rotterdam's port infrastructure for native starch feedstock import diversification beyond corn and potato bases. The country's advanced industrial composting network supports EN 13432-certified product qualification for export markets. Randstad region converters specialize in pellet supply to German and French flexible film extrusion lines.
Thermoplastic Starch (TPS) Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue alloy formulation specialization and home-compostable certification premiums. The vendor base spans multinational chemical conglomerates with Ludwigshafen and Novara production assets alongside mid-cap biopolymer specialists with regional agricultural partnerships. Three archetypes dominate: integrated compounders controlling feedstock-to-pellet value chains, flexible film converters with specification-setting power over retail supply chains, and custom formulation houses serving niche foodservice and agriculture trials. Capacity expansion and strategic partnerships represent the dominant competitive moves as compounders retrofit twin-screw reactive extrusion lines.
Among German-anchored integrated producers, BASF exemplifies the scale-driven archetype through its Ludwigshafen polymer compounding infrastructure and European distribution networks. Italian specialist Novamont S.p.A. occupies a position within the agricultural partnership tier, leveraging Po Valley waxy maize supply security. UK-based Biome Bioplastics represents the custom formulation archetype, developing TPS alloy specifications for foodservice clients competing against imported alternatives. These three entities collectively illustrate how geographic feedstock access, certification portfolio breadth, and converter relationship depth stratify competitive positioning.
| Leading Market Players |
|---|
| BIOTEC Biologische Naturverpackungen GmbH & Co. KG |
| Rodenburg Biopolymers |
| AGRANA |
| Kuraray Co., Ltd |
| BioLogiQ Inc. |
| BASF |
| Novamont S.p.A |
| Grupa Azoty |
| Biome Bioplastics |
| Others |
Value Network & Pricing Analysis
Captive waxy maize supply chains anchored in Italy's Po Valley and Germany's Bavarian processing clusters confer distinct pricing power on integrated compounders, insulating them from biodiesel-driven glycerol volatility that squeezes non-integrated operators. BASF's Ludwigshafen infrastructure and Novamont's agricultural partnerships demonstrate how upstream feedstock control translates into contract pricing stability for EN 13432-certified pellet supply.
Pricing Analysis
Glycerol and native starch input costs pass through to converter pricing with 60-90 day lags, compressing margins when biodiesel byproduct markets spike. Three-tier pricing structure across premium home-compostable, standard industrial-certified, and economy uncertified grades reflects certification investment recovery timelines. Pricing pressure intensifies in flexible film grades as German discounters consolidate procurement volumes and demand volume rebates. Foodservice buyers exhibit highest price sensitivity, while French hypermarkets absorb premiums for home-compostable dual certification.
Supply Chain Analysis
EN 13432 and TÜV Austria OK Compost HOME qualification gates filter compounder access to Western European retail chains, extending onboarding timelines to 18-24 months. Supply concentrates in Germany, Italy, and the Netherlands, with Ludwigshafen and Novara compounding assets feeding flexible film extrusion lines across the region. Feedstock sourcing draws from corn, potato, and waxy maize bases vulnerable to agricultural commodity cycles. Single-source certification laboratory bottlenecks create qualification backlogs. Distribution runs through pellet supply to converter networks, with direct compounder-to-retail vendor relationships consolidating specification-setting power.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thermoplastic Starch functions as a stable compounder market where EU Green Deal enforcement provides predictable demand expansion through regulatory mandate rather than discretionary adoption. The analysis window rewards operators with certification breadth and feedstock integration.
For Market Incumbents: Anticipate glycerol price volatility and REACH additive restriction expansions by deepening captive waxy maize supply relationships and accelerating dual EN 13432/ASTM D6400 certification pipelines. Secure twin-screw reactive extrusion technician pipelines through Bavarian and Northern Italian technical training partnerships. Prioritize barrier coating R&D to defend rigid container margins against multilayer film competitors. For New Entrants and Emerging Players: Begin with soil-biodegradable mulch film trials in Dutch and Belgian agricultural cooperatives, where industrial composting infrastructure gaps matter less than in Eastern Europe. Target UK foodservice custom alloy formulations as the most penetrable segment, competing on specification flexibility against imported alternatives. Pursue TÜV Austria OK Compost HOME certification as a go-to-market differentiator for premium consumer-facing applications. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap compounders with single-certification portfolios because EFSA migration study and EN 13432 testing investments create scale disadvantages for sub-scale operators. The 5-10 year viability window favors targets with existing agricultural partnerships and reactive extrusion capabilities. Watch for inflection in German discounter private-label sustainability scorecard enforcement as the signal for accelerated procurement consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Waxy Maize Supply | Po Valley agricultural partnerships reduce Novamont's exposure to corn price cycles. |
| Dual Certification Acceleration | EN 13432 and ASTM D6400 portfolios maintain transatlantic optionality for Ludwigshafen compounders. |
| Reactive Extrusion Line Retrofit | Twin-screw glycidyl methacrylate systems collapse TPS-PBAT alloy residence times. |
| Home-Compostable Grade Development | TÜV Austria OK Compost HOME unlocks French hypermarket premium positioning. |
| Agricultural Application Expansion | Soil-biodegradable mulch trials in the Netherlands diversify beyond packaging volume concentration. |
Research Methodology
Coverage spans Western Europe, North America, and Asia-Pacific, with primary inputs from each region's converter networks and regulatory bodies. The approach combines interviews with TPS compounder technical directors, flexible film converter procurement leads, supermarket chain sustainability officers, and agricultural cooperative trial managers with secondary validation through ECHA REACH guidance documents, EFSA migration limit publications, EN 13432 certification registries, and customs trade data for native starch feedstock flows. Bottom-up pellet demand modeling and top-down packaging waste regulation impact assessment provide triangulation.
Granularity-level modeling operates at product type, application, form, and end-user dimensions, with additional disaggregation by certification tier and regional composting infrastructure availability. Value and volume outputs reflect segment-level CAGRs derived from converter capacity expansion announcements and retail procurement mandate timelines. Key inputs include glycerol price series from biodiesel byproduct markets, waxy maize contract pricing from Italian agricultural exchanges, and EN 13432 certification issuance rates from accredited laboratories.
Caveats apply where EFSA fatty food contact limit revisions or EU Green Deal packaging waste regulation enforcement delays could materially shift the outlook. Forecasts reflect assumptions about industrial composting facility rollout pace across Eastern European member states and home-composting standard adoption timelines. A model refresh is warranted upon material change in German discounter sustainability scorecard implementation schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Novolac Resins Market
Polymers & Resins
Basic Methacrylate Copolymer Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Global Polyethylene Market
Polymers & Resins
South America Engineering Plastics Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Long-Chain Polyamide Market
Polymers & Resins
Polymer Gel Market
Polymers & Resins
Polylysine Market
Polymers & Resins
Conductive Polymers Market