
 Hydrogenated Styrene Block Copolymers Market | 2026-2036
Hydrogenated Styrene Block Copolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogenated Styrene Block Copolymers Market Outlook
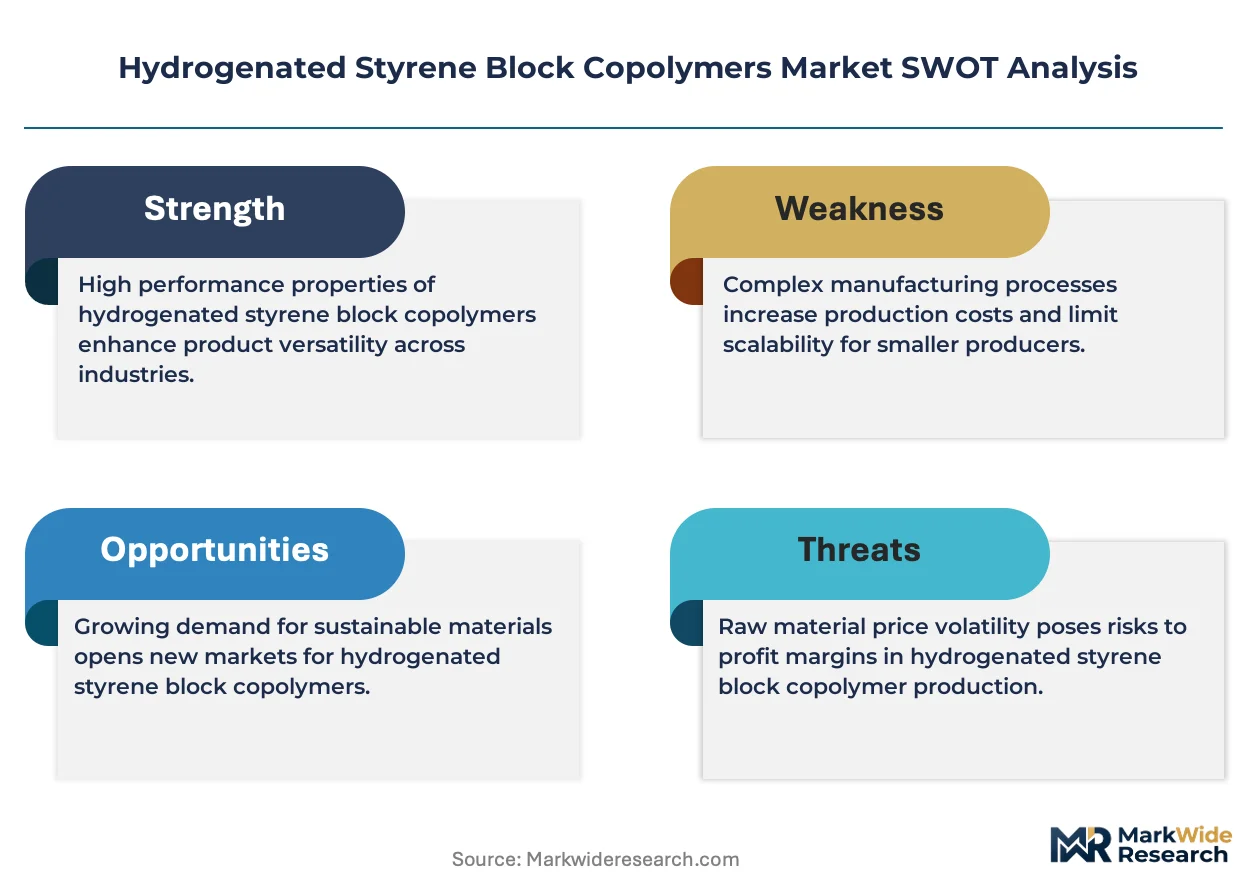
Multi-source procurement for hydrogenated styrene block copolymers is decoupling from the single-source contracts that dominated the last decade. Kraton Corporation leverages its integrated hydrogenation technology to sustain premium positioning in medical-grade SEBS. BASF SE competes through backward integration into butadiene feedstock, which anchors cost stability across European production.
Hydrogenated styrene block copolymers are thermoplastic elastomers produced by selective hydrogenation of styrene-butadiene-styrene or related diene midblocks, yielding saturated backbones with Shore A hardness ranging from 30 to 90 and service temperatures extending from -60°C to 135°C. Their primary industrial purpose centers on replacing vulcanized rubber and flexible PVC in applications requiring elasticity combined with thermoplastic processability. SEBS dominates value generation due to its oxidative stability and medical compliance, while SEPS captures faster expansion in high-clarity film and overmolding applications where lower hysteresis proves critical. The adhesives segment remains mature with thin margin pools, whereas automotive rubber modifiers concentrate profitability through long-term supply agreements with tier-one suppliers.
REACH registration through ECHA governs monomer residual limits and SVHC disclosure for European compounders, while FDA 21 CFR 177.2600 compliance dictates market access for medical tubing and seal applications in the United States. ISO 10993 biocompatibility testing protocols are becoming de facto requirements even for non-medical grades as brand owners preempt regulatory creep. Stakeholders must monitor hydrogenation catalyst cost volatility and the pace of bio-based styrene commercialization as these factors will determine which production configurations retain margin advantage through the forecast horizon.
Market Dynamics
Medical-grade certification requirements are compressing supplier margins while concentrating volume among compounders with captive hydrogenation capacity. The shift from flexible PVC toward SEBS in tubing applications is forcing compounders to absorb extended FDA 21 CFR 177.2600 compliance timelines.
Growth Catalysts
- Automotive lightweighting mandates:Germany's KBA enforcement of CO2 reduction targets is accelerating SEBS substitution for EPDM in underhood seals and grommets across Stuttgart and Wolfsburg supplier clusters.
- ISO 10993 biocompatibility creep:Brand owners in consumer goods are preemptively adopting medical-grade testing protocols, expanding addressable volume for certified SEBS grades beyond healthcare.
- Hydrogenation catalyst efficiency gains:Advanced nickel-aluminum catalyst systems are reducing hydrogen consumption per ton, improving process economics for mid-scale compounders.
Market Restraints
- Butadiene feedstock volatility:Crude-linked naphtha cracking economics transmit directly to SBC production costs, compressing margin visibility for non-integrated compounders.
- SEBS supply concentration:Hydrogenation reactor scarcity in North America and Western Europe limits qualified supply expansion, creating allocation risk during demand surges.
- SEPS technical limitations:Lower tensile strength versus SEBS restricts load-bearing applications, capping penetration in heavy-duty automotive components.
Strategic Opportunities
- India medical device manufacturing:CDSCO's phased alignment with ISO 13485 is creating first-mover advantage for SEBS compounders establishing local compounding presence.
- Bio-based styrene commercialization:Agricultural waste-derived styrene monomer is approaching cost parity, enabling circularity claims for premium footwear and personal care packaging.
- Overmolding convergence:Two-shot injection molding with SEBS soft-touch layers is electrifying consumer electronics assembly, displacing separate adhesive bonding steps.
Industry Challenges
- REACH SVHC disclosure complexity:ECHA's expanding candidate list requires continuous reformulation monitoring, extending product qualification cycles by 8-14 months.
- Hydrogenation reactor commissioning:Pressure vessel certification and catalyst loading protocols demand specialized field engineering talent that remains scarce in emerging production regions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogenated Styrene Block Copolymers Market |
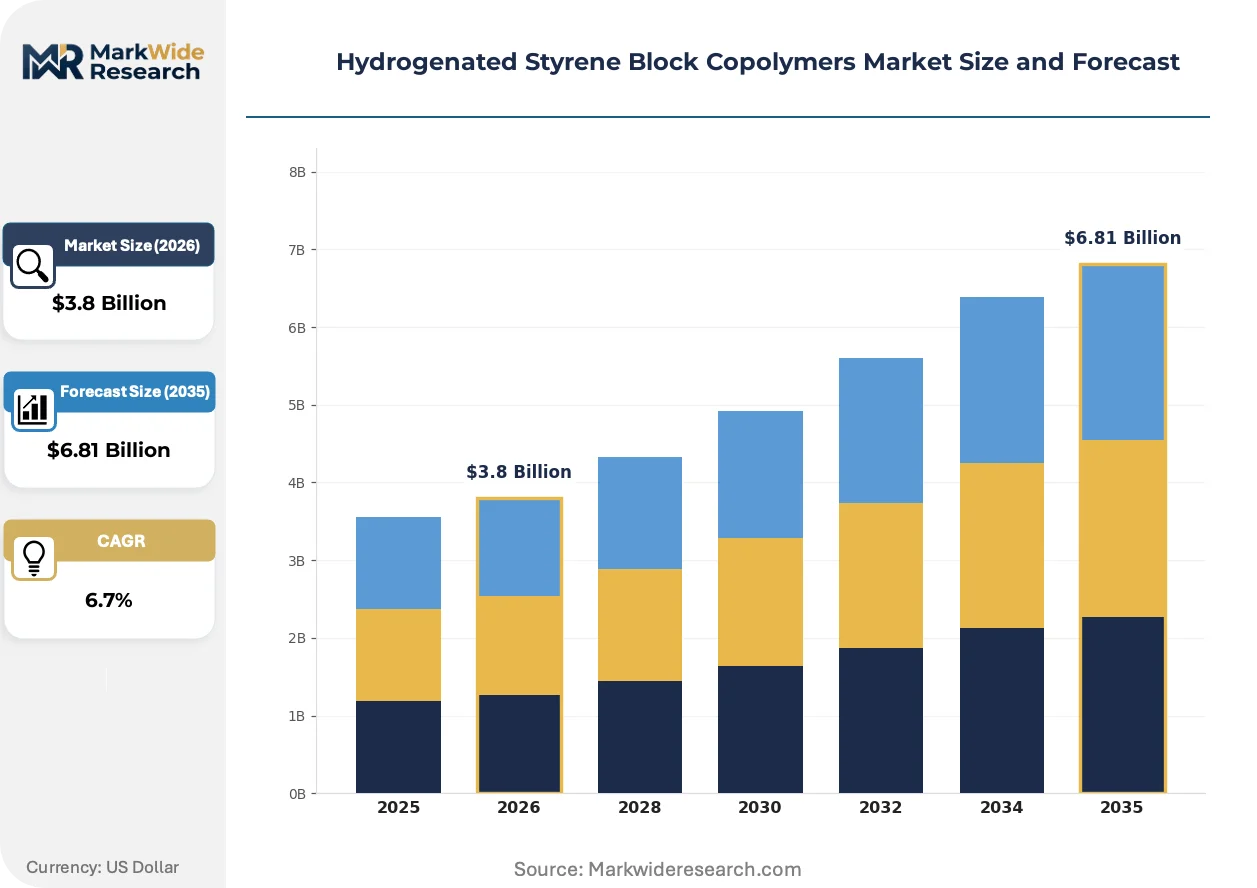
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SBS, SEPS, SIS, SEBS End Use Industry: Automotive, Adhesives, Medical, Footwear Application: Sealants, Coatings, Rubber Modifiers, Films Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Asahi Kasei Corporation, TSRC Corporation, Kraton Corporation, BASF SE, Evonik Industries, Sinopec (China Petrochemical Corporation), Dynasol Group, Kuraray Co Ltd, LG Chem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogenated Styrene Block Copolymers Market Strategic Shifts
Process intensification and regulatory harmonization are compressing development cycles while fragmenting specification requirements across end-use verticals. Material suppliers must now manage parallel certification tracks for automotive, medical, and consumer applications simultaneously.
Continuous hydrogenation reactor technology is electrifying SEBS production economics by eliminating batch turnaround losses and improving molecular weight distribution control. Tier-one automotive suppliers in Germany are qualifying continuous-process material for next-generation sealing systems. This process architecture is compressing capital intensity per ton of installed capacity, enabling mid-scale entrants to achieve viable unit economics.
REACH authorization requirements for residual monomer content are tightening disclosure obligations for European compounders serving medical and food-contact applications. ECHA's 2024-2025 substance evaluation work program is prioritizing styrene oligomer assessments, forcing reformulation investments ahead of regulatory deadlines. German compounders around Ludwigshafen are responding by advancing hydrogenation completeness beyond 99.5% to preempt restriction scenarios.
Specification-driven procurement is consolidating buyer power among medical device OEMs, who are unbundling compounding from device manufacturing to capture margin. Long-term supply agreements now incorporate indexed raw material pass-throughs and dedicated capacity reservations. This pattern is most visible in Minnesota and Massachusetts medical device clusters, where three OEMs now account for the majority of US medical-grade SEBS procurement volume.
Hydrogenated Styrene Block Copolymers Market Segmentation
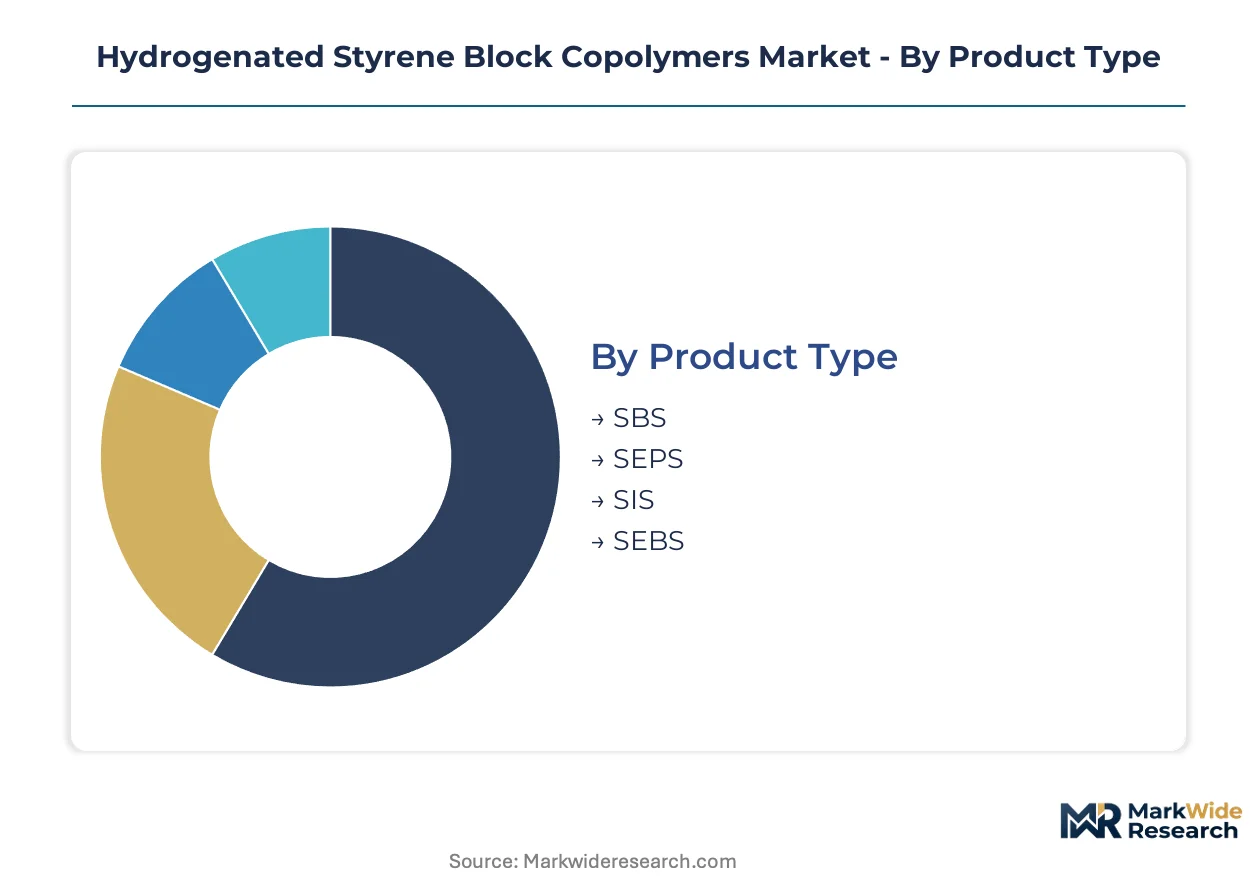
Segmentation in hydrogenated styrene block copolymers reveals how technical specifications and regulatory compliance requirements fragment procurement patterns. Buyers prioritize different performance attributes depending on whether they serve automotive sealing, medical tubing, or adhesive formulations.
Product Type:
Buyers in this category differentiate primarily by oxidative stability requirements and hydrogenation completeness levels.
- SEBS:Fully hydrogenated styrene-ethylene-butylene-styrene delivers saturated midblock architecture with Shore A hardness from 30 to 90. Medical device manufacturers in Minnesota and Massachusetts specify SEBS for tubing and seals under FDA 21 CFR 177.2600, absorbing extended qualification timelines for biocompatibility certification.
- SEPS:Styrene-ethylene-propylene-styrene offers lower hysteresis and superior optical clarity versus SEBS. High-clarity film producers and overmolding specialists in consumer electronics are qualifying SEPS for two-shot injection applications where reduced compression set proves critical.
- SBS:Unhydrogenated styrene-butadiene-styrene retains unsaturated midblocks with limited thermal stability. Asphalt modification and low-cost adhesive compounders specify SBS where oxidative degradation is manageable.
- SIS:Styrene-isoprene-styrene provides aggressive tack and low melt viscosity. Pressure-sensitive adhesive formulators leverage SIS for label and tape applications requiring room-temperature bond formation.
SEBS leads volumes today; SEPS is gaining share fastest.
End Use Industry:
Margin structures diverge sharply based on certification burden and contract duration.
- Automotive:Underhood seals, grommets, and interior soft-touch components specify SEBS for temperature resistance spanning -60°C to 135°C. Germany's KBA enforcement of CO2 reduction targets is accelerating substitution for EPDM across Stuttgart and Wolfsburg supplier clusters.
- Medical:Tubing, seals, and device housings require ISO 10993 biocompatibility testing and FDA compliance. Compounders with captive hydrogenation capacity capture concentrated volume as OEMs unbundle manufacturing to capture margin.
- Adhesives:Hot-melt and pressure-sensitive formulations represent mature demand with compressed margin pools. SIS and SBS dominate this segment where technical differentiation is limited.
- Footwear:Midsole cushioning and upper materials are transitioning toward bio-based styrene claims. Agricultural waste-derived monomer is approaching cost parity, enabling circularity positioning for premium brands.
Automotive generates the largest revenue pool; medical exhibits the steepest expansion trajectory.
Application:
Processing method and performance tier determine material selection within each application.
- Rubber Modifiers:SEBS and SEPS enhance impact resistance and flow characteristics in polyolefin compounds. Automotive tier-one suppliers in Germany are qualifying continuous-process material for next-generation sealing systems.
- Sealants:Construction and automotive sealing applications demand UV stability and elastic recovery. REACH registration through ECHA governs monomer residual limits for European compounders serving this segment.
- Films:High-clarity packaging and medical barrier films leverage SEPS for optical properties and sterilization compatibility. Brand owners are preemptively adopting medical-grade testing protocols beyond healthcare applications.
- Coatings:Protective and decorative coatings utilize SEBS for flexibility and chemical resistance. Industrial maintenance and transportation applications specify hydrogenated grades for extended service life.
Rubber modifiers anchor current demand; films demonstrate the most rapid climb.
Distribution Channel:
Procurement scale and technical service requirements shape channel preference.
- Direct Sales:Large automotive and medical OEMs negotiate long-term supply agreements with indexed raw material pass-throughs and dedicated capacity reservations. Three medical device OEMs now account for the majority of US medical-grade SEBS procurement volume.
- Wholesale:Regional compounders and mid-tier processors source through distributors for smaller lot sizes and technical support. CDSCO's phased alignment with ISO 13485 in India is creating first-mover advantage for compounders establishing local presence.
- Online:Standard grades and technical documentation are migrating to digital procurement platforms. Smaller adhesive formulators and footwear producers utilize e-commerce for spot purchasing.
- Retail:Limited to specialty chemical distributors serving research institutions and prototype developers. Low volume and high service requirements constrain this channel's expansion.
Direct sales commands the largest transaction value; wholesale maintains the broadest geographic penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive component cluster around Stuttgart and Wolfsburg anchors hydrogenated styrene block copolymer demand through SEBS substitution for EPDM in underhood sealing systems. Regional procurement concentrates among tier-one suppliers serving OEMs under KBA-enforced CO2 reduction mandates.
United States
Medical device OEMs in Minnesota and Massachusetts drive premium-grade SEBS consumption for tubing and seals under FDA 21 CFR 177.2600 compliance requirements. Three OEMs now account for the majority of domestic medical-grade procurement volume through long-term supply agreements with indexed raw material pass-throughs. Specification-driven procurement is unbundling compounding from device manufacturing to capture margin.
Germany
KBA enforcement of automotive CO2 reduction targets accelerates SEBS adoption for underhood seals and grommets across Stuttgart and Wolfsburg supplier clusters. REACH registration through ECHA governs monomer residual limits and SVHC disclosure obligations for compounders serving medical and food-contact applications. Ludwigshafen-based compounders are advancing hydrogenation completeness beyond 99.5% to preempt ECHA restriction scenarios.
China
Dual carbon goals under MEE oversight are reshaping material selection in automotive and consumer electronics manufacturing. Sinopec's integrated petrochemical operations supply feedstock to domestic SEBS compounders serving electric vehicle sealing applications. Yangtze River Delta manufacturers are qualifying continuous-process material for two-shot injection molding in consumer electronics assembly.
India
CDSCO's phased alignment with ISO 13485 is creating first-mover advantage for SEBS compounders establishing local compounding presence for medical device manufacturing. Domestic footwear producers are evaluating bio-based styrene claims as agricultural waste-derived monomer approaches cost parity. Maharashtra and Gujarat industrial corridors concentrate initial compounding investments.
Japan
METI industrial standards guide material qualification for automotive and electronics applications requiring Shore A hardness precision. Kansai and Chubu regional manufacturers specialize in high-clarity SEPS grades for optical film and overmolding applications. Domestic compounders maintain captive hydrogenation capacity to serve tier-one automotive suppliers with dedicated capacity reservations.
Hydrogenated Styrene Block Copolymers Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue medical-grade certification and bio-based feedstock differentiation. The supplier base concentrates around integrated petrochemical operators and specialty compounders with captive hydrogenation capacity. Three archetypes dominate: backward-integrated feedstock owners, technology-licensed regional compounders, and medical-grade certification specialists. Competitive moves center on continuous hydrogenation reactor commissioning and strategic partnerships for bio-based styrene sourcing.
Within the integrated petrochemical tier, BASF SE and Sinopec exemplify feedstock-anchored positioning through backward integration into butadiene supply chains. Kraton Corporation occupies a distinct archetype as a hydrogenation technology specialist serving premium medical-grade segments. These three entities represent divergent strategic vectors: European cost stability through feedstock control, Asian scale through state-affiliated petrochemical integration, and North American premium positioning through proprietary hydrogenation expertise.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| TSRC Corporation |
| Kraton Corporation |
| BASF SE |
| Evonik Industries |
| Sinopec (China Petrochemical Corporation) |
| Dynasol Group |
| Kuraray Co Ltd |
| LG Chem |
| Others |
Value Chain & Pricing Dynamics
Medical device OEMs in Minnesota and Massachusetts concentrate procurement through long-term supply agreements with indexed raw material pass-throughs, anchoring contract-based pricing across premium-grade SEBS segments. This buyer concentration compresses margin visibility for non-integrated compounders while rewarding suppliers with captive hydrogenation capacity.
Pricing Analysis
Butadiene feedstock costs transmit directly to SEBS production economics through crude-linked naphtha cracking, forcing compounders to absorb volatility or renegotiate contract terms. Pricing stratifies across medical-grade certification tiers, FDA 21 CFR 177.2600 compliance, and standard industrial grades with divergent hydrogenation completeness levels. Cost compression in standard-grade segments is intensifying because REACH registration requirements extend qualification timelines. Adhesive formulators exhibit highest price sensitivity due to thin margin pools, while medical device OEMs prioritize supply security over unit cost.
Supply Chain Analysis
SEBS supply rests on hydrogenation reactor capacity concentrated in Germany, the United States, and Japan, with emerging expansion in China through Sinopec's integrated operations. Key inputs include butadiene feedstock from naphtha crackers, nickel-aluminum hydrogenation catalysts, and styrene monomer from ethylbenzene dehydrogenation. Single-source vulnerability around specialized hydrogenation reactor engineering talent constrains qualified supply expansion. Distribution runs through direct sales to automotive and medical OEMs alongside wholesale channels serving regional compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The hydrogenated styrene block copolymers market represents a late-cycle quality story as ISO 10993 biocompatibility creep expands medical-grade specifications into consumer goods applications. This specification elevation favors compounders with established certification infrastructure.
For Market Incumbents: To counter hydrogenation reactor scarcity limiting qualified supply expansion, BASF SE and Kraton Corporation should deepen backward integration into butadiene feedstock and advance continuous hydrogenation reactor commissioning. Captive catalyst loading protocols and dedicated capacity reservations with tier-one automotive suppliers in Stuttgart and Wolfsburg will defend margin position against mid-scale entrants. For New Entrants and Emerging Players: Enter via CDSCO-aligned medical device manufacturing corridors in Maharashtra and Gujarat, where ISO 13485 convergence creates first-mover advantage for local compounding presence. Bio-based styrene commercialization for premium footwear claims and overmolding applications in consumer electronics assembly offer penetrable white-space targets with lower certification barriers than medical-grade SEBS. For Investors and Strategic Acquirers: Specialty chemical conglomerates with medical-grade polymer portfolios are the most active acquirer in this space, seeking hydrogenation technology specialists to fill capability gaps. The investment thesis centers on five-to-ten year demand visibility from automotive lightweighting mandates and medical device outsourcing trends. Watch ECHA substance evaluation timelines for styrene oligomer restrictions as the critical regulatory inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Hydrogenation Reactor Commissioning | Kraton Corporation leverages proprietary technology to compress capital intensity per ton for mid-scale entrants. |
| Backward Integration into Butadiene Feedstock | BASF SE anchors cost stability across European production through integrated petrochemical operations. |
| Medical-Grade Certification Investment | Compounders advancing ISO 10993 compliance capture concentrated volume from unbundling medical device OEMs. |
| Bio-Based Styrene Sourcing Partnership | Agricultural waste-derived monomer approaches cost parity, enabling circularity claims for premium footwear brands. |
| Long-Term Supply Agreement with Indexing | Three medical device OEMs in Minnesota and Massachusetts lock dedicated capacity through raw material pass-throughs. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hydrogenation technology directors, medical device procurement managers at Minnesota and Massachusetts OEMs, automotive tier-one supplier material engineers, and REACH compliance specialists at ECHA with secondary validation from SEC 10-K filings, customs trade data, FDA 510(k) submissions, and ACC polymer industry reports. Bottom-up production capacity modeling and top-down demand segmentation by end-use industry were cross-referenced for triangulation.
Segment-weighting across product type, end-use industry, application, and distribution channel governed value allocation throughout the projection horizon. The analytical framework modeled SEBS and SEPS grade tiers separately, with hydrogenation completeness levels and certification status as cross-cutting variables. CAGRs were derived from production capacity expansion timelines, automotive platform adoption curves, and medical device outsourcing intensity indices.
The model holds under stable butadiene feedstock pricing and continued REACH registration enforcement; deviation in ECHA restriction scenarios or hydrogenation catalyst supply disruptions would shift volume projections. Forecasts reflect documented assumptions about regulatory harmonization pace and continuous process technology adoption rates. A small set of triggers—ECHA styrene oligomer evaluations, CDSCO ISO 13485 implementation speed, and bio-based styrene cost parity achievement—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Bio-Polybutadiene Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Global Furan Resins Market
Polymers & Resins
Nylon 4-6 Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
Water Soluble Polymers Market
Polymers & Resins
Polymer Modified Bitumen (PMB) Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Global UV Curable Resins and Formulated Products Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
Asia-Pacific Opaque Polymers Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Modified Alkyd Resin Market
Polymers & Resins
Isosorbide-Based Engineering Polymer Monomers Market