
 Copolyesters Market | 2026-2036
Copolyesters Market Size, Share, and Industry Trends Forecast 2026-2036
Copolyesters Market Analysis
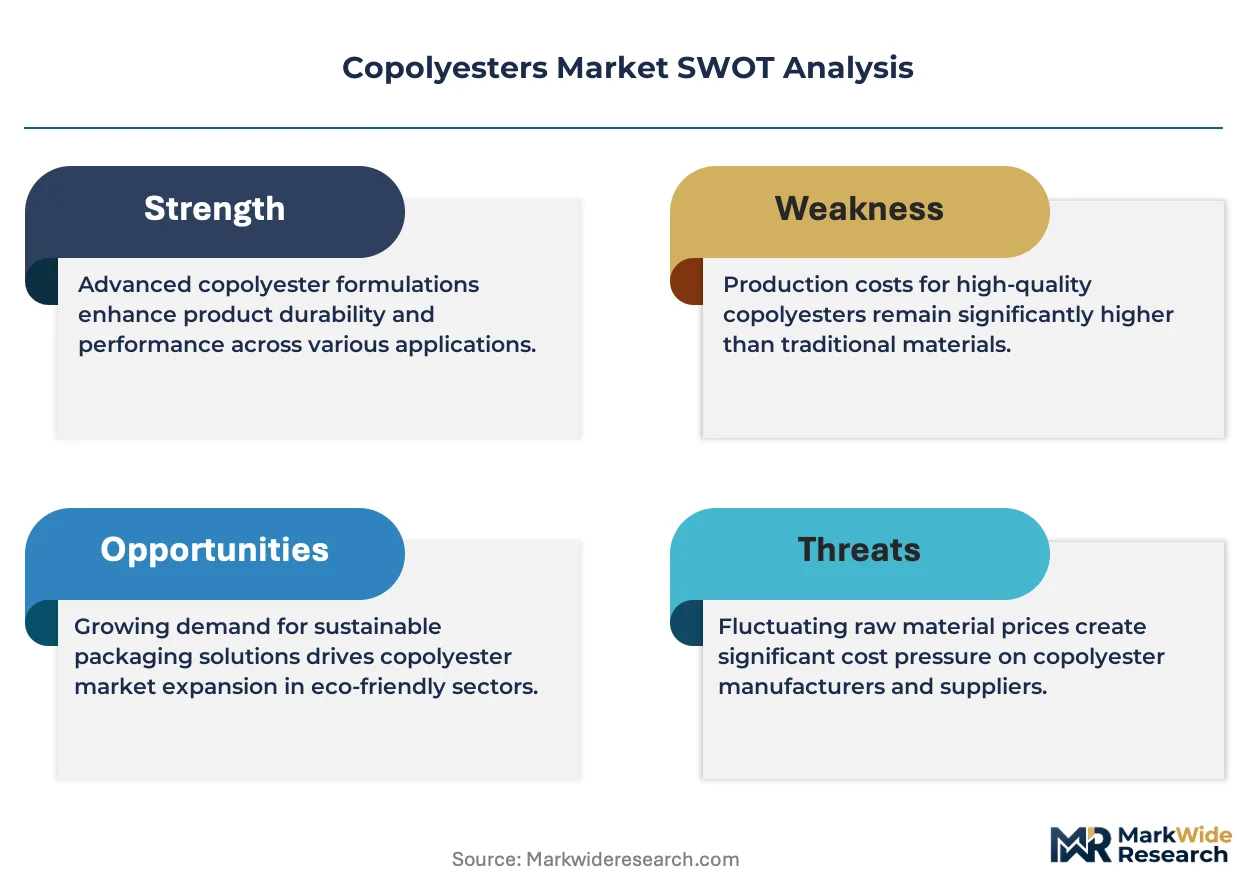
The copolyesters market is pivoting on a widening split between premium engineering grades and commodity packaging resins. Eastman Chemical Company leverages its molecular recycling technology to sustain supply of certified recycled-content copolyesters for cosmetics and food-contact applications. SK Chemicals Co., Ltd. anchors its position in Asia through proprietary bio-based monomer routes that differentiate its portfolio from fossil-derived alternatives. Covestro AG competes on high-clarity, high-durability grades targeting automotive interior laminates and electronic device housings where optical performance commands price premiums.
Copolyesters are amorphous or semi-crystalline thermoplastic polymers synthesized through polycondensation of multiple diols and dicarboxylic acids, typically exhibiting glass transition temperatures between 75°C and 110°C and inherent toughness without impact modifiers. Their primary commercial purpose spans blow-molded packaging, extruded films, and injection-molded durable goods where clarity, chemical resistance, and processability must coexist. Thermoplastic copolyesters dominate volume flows into packaging and textiles, yet biodegradable variants are capturing the fastest expansion as single-use plastics directives tighten across major economies. Engineering-grade copolyesters concentrate margin pools in electronics and automotive interiors, where flame-retardant certifications and dimensional stability under thermal cycling justify material premiums over standard grades.
REACH registration requirements and the EU Green Deal carbon-border adjustments shape copolyester formulation decisions for any supplier accessing European downstream markets. The FDA's food-contact notification process and EPA guidelines on recycled-content claims similarly govern market access for North American producers and importers. Stakeholders must monitor evolving Extended Producer Responsibility schemes and monomer-level carbon intensity disclosures, as these will increasingly determine which product grades qualify for preferential procurement by multinational OEMs and retail chains.
Market Dynamics
Copolyester formulation decisions now pivot on molecular recycling scalability and bio-based monomer certification costs, as packaging converters face binding circular-economy mandates from the EU Green Deal and equivalent frameworks.
Growth Catalysts
- REACH compliance deadlines:European converters accelerate specification shifts toward recycled-content and biodegradable copolyester grades to meet ECHA registration thresholds and carbon-border adjustment timelines.
- Automotive interior applications:German OEMs drive engineering-grade demand for high-clarity laminates and flame-retardant housings where dimensional stability under thermal cycling justifies material premiums.
- Molecular recycling infrastructure:Eastman's methanolysis and glycolysis platforms enable certified recycled-content supply for food-contact and cosmetics packaging without virgin-equivalent performance degradation.
Market Restraints
- PTA and bio-based diol volatility:Purified terephthalic acid and bio-propanediol feedstock costs swing with crude oil and agricultural commodity cycles, compressing margin predictability for specialty grades.
- Asian supply concentration:SK Chemicals and Chinese producers control disproportionate bio-based monomer capacity, creating geographic dependency risk for European and North American compounders.
- Polylactic acid substitution:PLA advances in rigid food packaging threaten commodity copolyester volumes where clarity requirements are secondary to biodegradability certification.
Strategic Opportunities
- Extended Producer Responsibility expansion:France's Citeo and Germany's Der Grüne Punkt schemes create preferential procurement channels for copolyesters with verified recycled content and end-of-life traceability.
- Medical device housings:Engineering-grade copolyesters with gamma-stability and USP Class VI compliance capture share from polycarbonate in diagnostic equipment and wearable drug delivery systems.
- Textile fiber grade development:Bio-based PETG and PCTG variants penetrate sportswear and automotive upholstery markets where moisture management and dyeability specifications align with sustainability claims.
Industry Challenges
- Food-contact notification timelines:FDA's FCN process for novel copolyester formulations stretches 12-18 months, delaying commercialization of recycled-content grades for beverage and food packaging.
- Compounding equipment retrofit costs:Legacy PET processing lines require screw and dryer modifications to handle copolyester hygroscopicity and shear sensitivity, raising capital barriers for mid-volume converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Copolyesters Market |
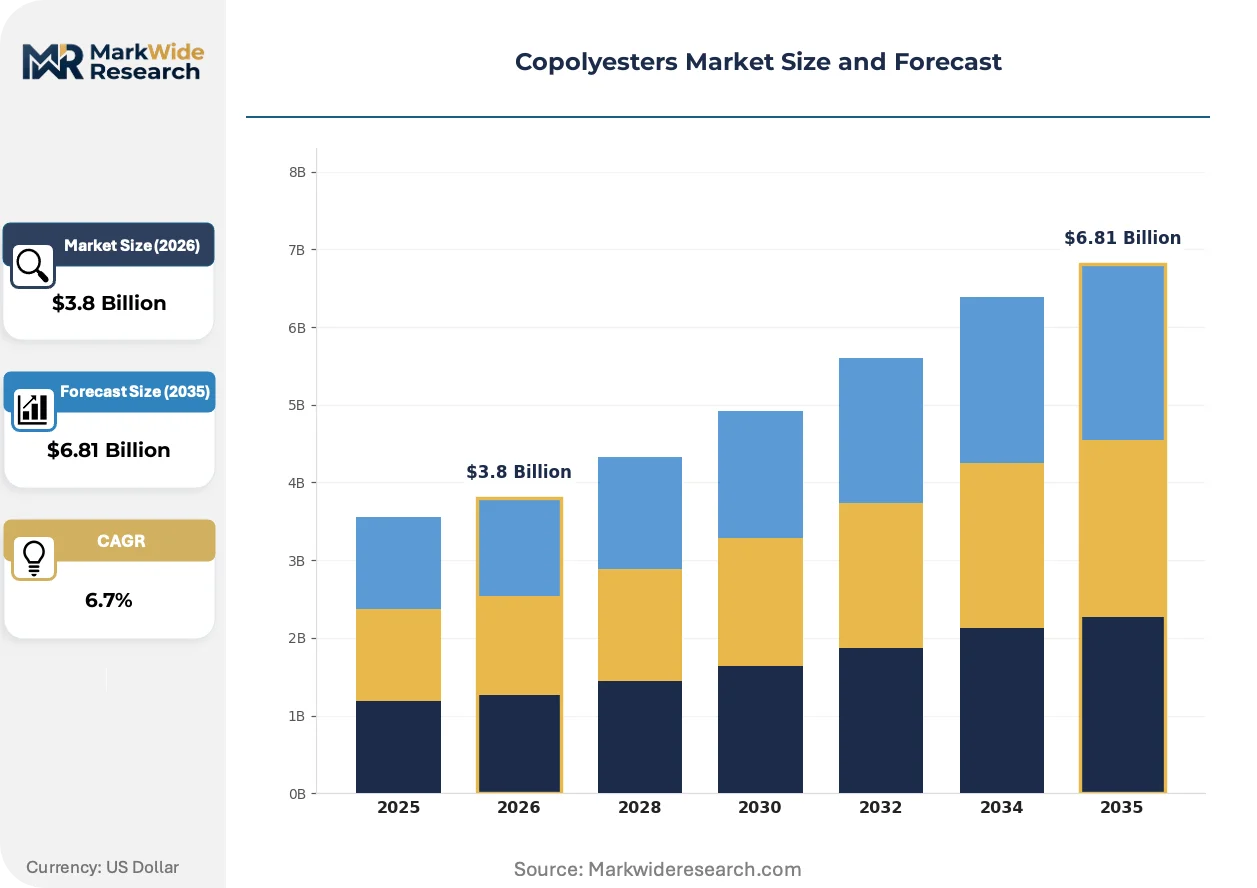
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastic, Biodegradable, Engineering Grade, High-Performance Application: Automotive Interiors, Packaging, Electronics, Textiles End User: Manufacturers, Retailers, OEMs, Distributors Form: Granules, Sheets, Films, Bottles |
| Companies Covered | Indorama Ventures Public Company Limited, DuPont de Nemours, Inc., Eastman Chemical Company, Covestro AG, SABIC, SK Chemicals Co., Ltd., BASF SE, Mitsubishi Chemical Corporation, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copolyesters Market Emerging Trajectories
Formulation science and regulatory compliance are converging to redefine copolyester value propositions, with molecular recycling and bio-based monomer routes displacing conventional petrochemical supply chains.
Enzymatic depolymerization technology is consolidating scattered post-consumer polyester waste streams into certified recycled monomers suitable for food-contact copolyester production. Packaging converters in Germany and the Netherlands adopt these feedstocks to satisfy retailer sustainability scorecards. The technology is consolidating regional recycling infrastructure around centralized molecular purification hubs rather than mechanical regrind networks.
REACH Article 33 disclosure requirements and the EU Green Deal carbon-border adjustment mechanism tighten traceability obligations for copolyester importers and compounders. Downstream automotive and electronics OEMs now mandate cradle-to-gate carbon intensity documentation for engineering-grade specifications. German Tier-1 suppliers invest in blockchain-tracked mass-balance certification to maintain access to premium specification pools.
Cosmetics and personal care brands compress supplier qualification cycles from 24 months to 12 months, prioritizing copolyester converters with pre-validated FDA food-contact and EU cosmetic packaging dossiers. This acceleration favors compounders with in-house regulatory affairs capacity over commodity resin distributors. The shift concentrates procurement authority among multinational packaging groups with centralized sustainability compliance functions.
Copolyesters Market Segmentation
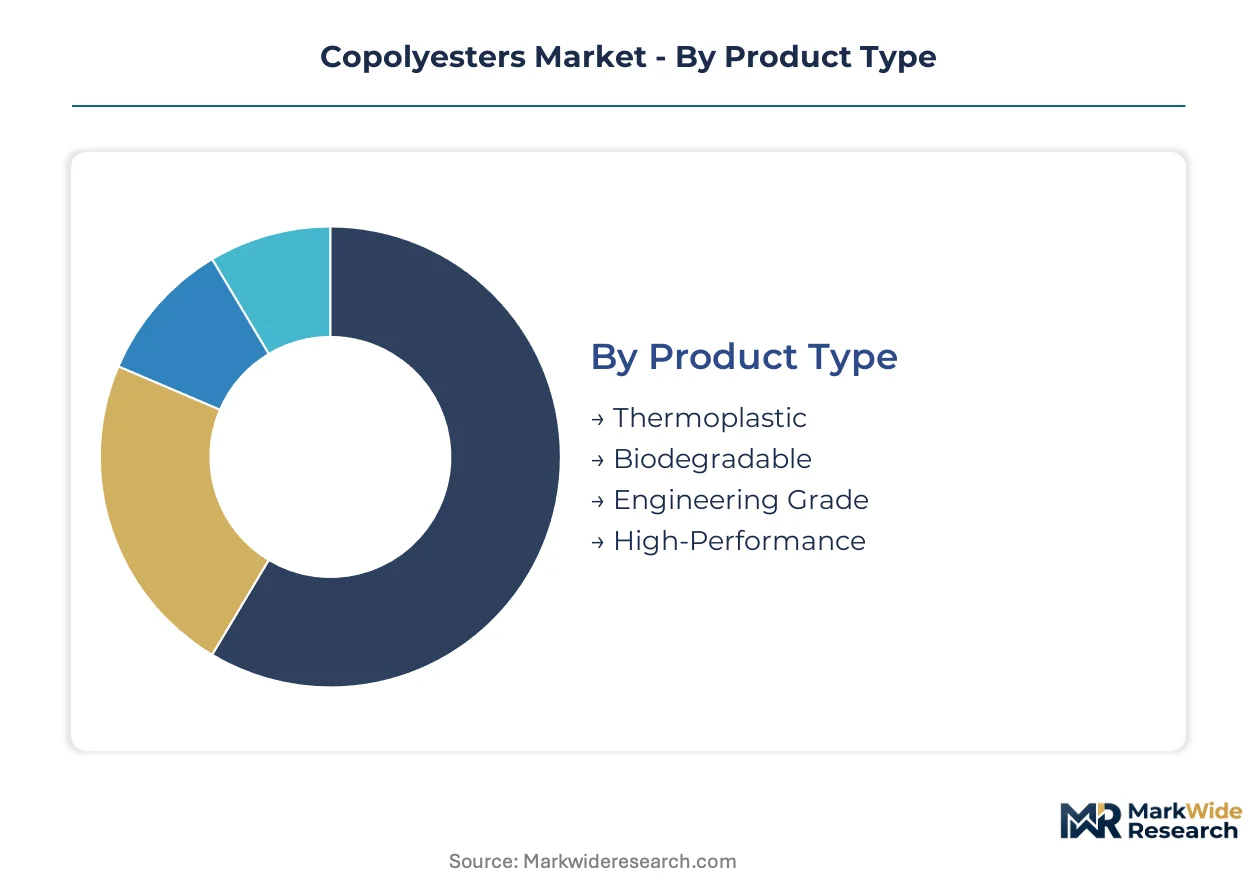
Copolyester procurement patterns diverge sharply across product grades and end-use specifications. Understanding these divides reveals where margin pools concentrate and which formulation investments align with tightening circular-economy mandates.
Product Type:
Buyers differentiate primarily by performance certification requirements and carbon-intensity documentation thresholds.
- Thermoplastic:Amorphous and semi-crystalline grades dominate blow-molded packaging and extruded film applications where clarity and processability must coexist. German packaging converters specify these for cosmetics and food-contact bottles under REACH compliance deadlines.
- Biodegradable:Aliphatic-aromatic copolyesters degrade in industrial composting environments, capturing specification shifts from single-use plastics directives. French retailers and Dutch supermarket chains prioritize these grades for flexible packaging to satisfy Extended Producer Responsibility scorecards.
- Engineering Grade:High-clarity, flame-retardant specifications for automotive interior laminates and electronic housings.
- High-Performance:Gamma-stable, USP Class VI compliant variants penetrating medical device applications.
Thermoplastic leads volumes today; biodegradable is gaining share fastest.
Application:
Specification intensity varies by thermal cycling demands and optical performance requirements.
- Automotive Interiors:German OEMs drive demand for high-clarity laminates and flame-retardant housings where dimensional stability under thermal cycling justifies material premiums over standard grades. REACH carbon-border adjustments tighten cradle-to-gate documentation obligations for Tier-1 suppliers.
- Packaging:Blow-molded bottles and extruded films for cosmetics, food-contact, and personal care applications dominate volume flows. Molecular recycling infrastructure enables certified recycled-content supply for Eastman's cosmetics packaging customers without virgin-equivalent performance degradation.
- Electronics:Durable housings and interior laminates requiring flame-retardant certifications.
- Textiles:Bio-based PETG and PCTG fiber grades penetrating sportswear markets.
Packaging commands the largest volume position; automotive interiors show the steepest margin expansion.
End User:
Procurement authority concentrates among entities with centralized sustainability compliance functions.
- Manufacturers:Compounders and converters with in-house regulatory affairs capacity capture preferential qualification cycles. Cosmetics brands compress supplier validation from 24 months to 12 months, favoring manufacturers with pre-validated FDA food-contact and EU cosmetic packaging dossiers.
- OEMs:Automotive and electronics original equipment manufacturers mandate blockchain-tracked mass-balance certification for engineering-grade specifications. German Tier-1 suppliers invest in traceability infrastructure to maintain access to premium specification pools.
- Retailers:Supermarket chains and personal care brands with sustainability scorecards.
- Distributors:Commodity resin distributors losing share to compounders with regulatory capacity.
Manufacturers lead procurement volumes; OEMs are driving the fastest specification upgrades.
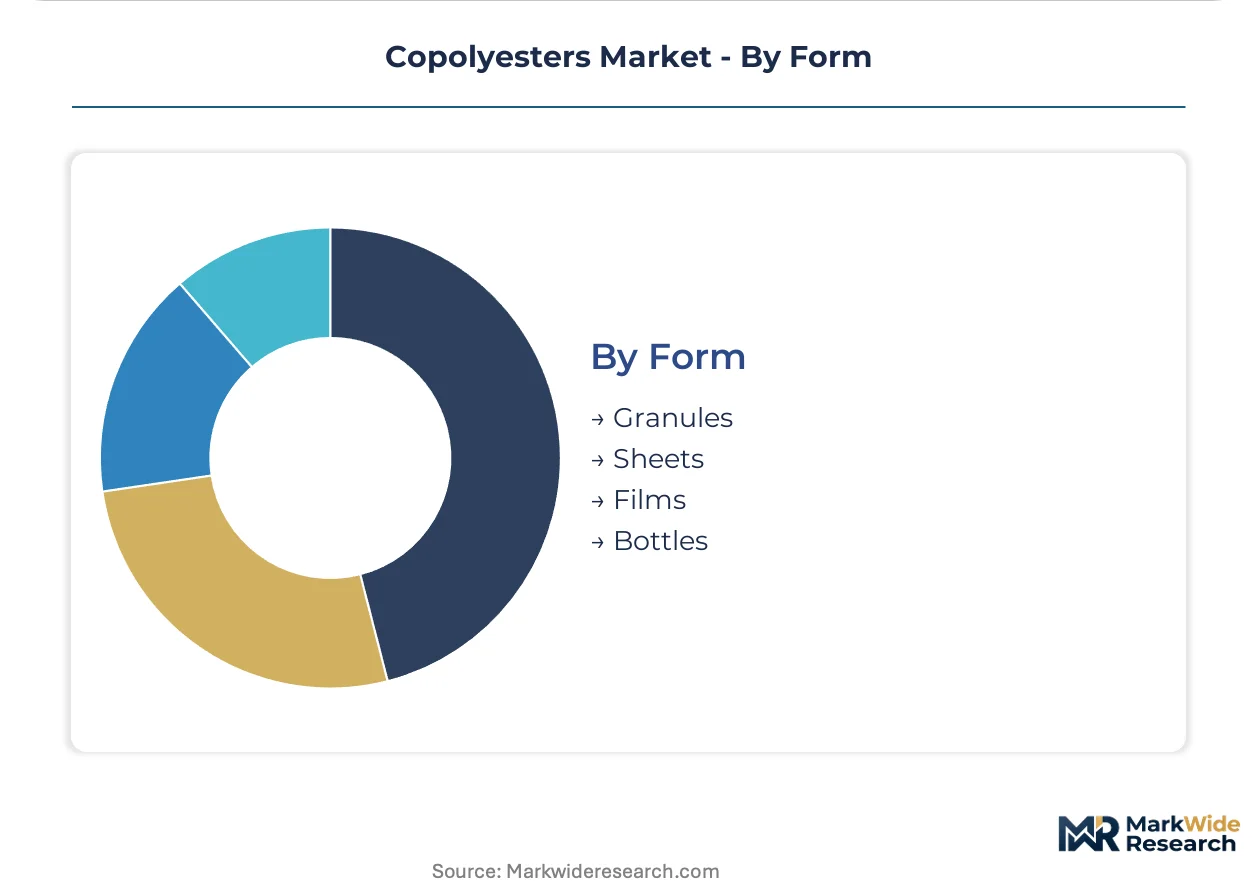
Form:
Processing method determines hygroscopicity handling and equipment retrofit requirements.
- Granules:Standard pellet form for injection molding and extrusion processes. Legacy PET processing lines require screw and dryer modifications to handle copolyester hygroscopicity and shear sensitivity, raising capital barriers for mid-volume converters.
- Films:Extruded sheet and film grades for flexible packaging and laminates.
- Sheets:Thermoforming feedstock for durable goods and medical trays.
- Bottles:Blow-molded containers for beverage and cosmetics applications.
Granules dominate processing volumes; films are climbing the fastest on flexible packaging substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands premium engineering-grade volumes while the United States scales molecular recycling infrastructure. China concentrates bio-based monomer capacity. Japan targets high-performance medical grades. France leads biodegradable packaging adoption.
Germany
Automotive OEMs in Stuttgart and Munich drive specification intensity for flame-retardant laminates and electronic housings. REACH carbon-border adjustments and ECHA registration deadlines tighten cradle-to-gate documentation for Tier-1 suppliers. The Rhine-Ruhr packaging cluster accelerates shifts toward recycled-content grades under Extended Producer Responsibility mandates.
United States
Food-contact packaging converters in the Midwest and Southeast expand certified recycled-content specifications. FDA notification timelines and EPA recycled-content claim guidelines govern market access for molecular recycling platforms. The Gulf Coast petrochemical corridor hosts glycolysis and methanolysis infrastructure serving cosmetics and beverage markets.
China
Domestic packaging demand and bio-propanediol feedstock integration concentrate capacity in the Yangtze River Delta. GB standards and MIIT circular-economy directives shape formulation decisions for export-oriented compounders. Zhejiang and Jiangsu provinces anchor bio-based monomer production serving Asian textile and flexible packaging markets.
Japan
Medical device manufacturers in Osaka and Tokyo specify gamma-stable, USP Class VI compliant grades for diagnostic equipment. PMDA quality management system requirements and METI sustainability guidelines drive qualification cycles for wearable drug delivery systems. The Chubu region concentrates high-performance compounding for electronics applications.
France
Supermarket chains and cosmetics brands in the Paris basin prioritize biodegradable aliphatic-aromatic grades for flexible packaging. Citeo Extended Producer Responsibility schemes create preferential procurement channels with verified end-of-life traceability. The Lyon packaging cluster integrates enzymatic depolymerization feedstocks to satisfy retailer sustainability scorecards.
Copolyesters Market Vendor Landscape
Top-tier vendors anchor molecular recycling and bio-based monomer platforms, while regional compounders compete on formulation agility and regulatory dossier capacity. The vendor base stratifies across integrated petrochemical majors, specialty material innovators, and downstream converters with in-house compounding expertise. Two strategic archetypes dominate: technology licensors with certified recycling infrastructure, and formulation specialists with pre-validated food-contact and medical-grade portfolios. Capacity expansion in bio-based diols and backward integration into purified terephthalic acid represent the primary competitive vectors.
Within the technology-licensor tier, Eastman Chemical Company and SK Chemicals Co., Ltd. exemplify divergent platform strategies. Eastman anchors North American molecular recycling supply for cosmetics and food-contact applications. SK Chemicals occupies a position in Asian bio-based monomer routes that differentiate output from fossil-derived alternatives. Covestro AG represents the European engineering-grade specialist competing on optical performance and flame-retardant certifications for automotive and electronics markets.
| Leading Market Players |
|---|
| Indorama Ventures Public Company Limited |
| DuPont de Nemours, Inc. |
| Eastman Chemical Company |
| Covestro AG |
| SABIC |
| SK Chemicals Co., Ltd. |
| BASF SE |
| Mitsubishi Chemical Corporation |
| Celanese Corporation |
| Others |
Supply Flow & Price Mechanics
Engineering-grade versus commodity-grade bifurcation drives divergent margin structures across copolyester supply chains, with REACH carbon-border documentation and FDA food-contact certification creating tiered procurement thresholds that reshape both pricing power and raw material sourcing patterns. German automotive OEMs absorb 40-60% premiums for flame-retardant laminates while Asian packaging converters compete on spot-priced virgin resin, fragmenting supplier strategies across molecular recycling investments versus undifferentiated volume plays.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for standard thermoplastic grades, compressing margins for commodity compounders while European molecular recycling platforms sustain certified-recycled premiums. Three-tier pricing structure across premium, standard, and economy levels reflects certification intensity: FDA food-contact and EU cosmetic dossiers command top-tier positioning, REACH-compliant recycled-content grades occupy mid-market slots, and undifferentiated virgin resin competes on volume scale. Price differentiation hinges on carbon-intensity documentation and monomer traceability, with cosmetics brands least price-sensitive due to compressed 12-month qualification cycles and rigid packaging converters most exposed to PTA and bio-propanediol cost swings.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for engineering-grade copolyesters, while commodity flows bypass intermediaries through direct mill-to-converter arrangements. Supply concentrates in Germany for automotive laminates, China for bio-based monomer production, and the US Gulf Coast for molecular recycling feedstocks. Raw material dependencies rest on purified terephthalic acid from naphtha crackers, bio-propanediol from agricultural feedstocks, and specialty diols for high-performance grades. Single-source vulnerability in Asian bio-based monomer capacity exposes European compounders to geographic concentration risk. Distribution runs through authorized distributor networks for medical and food-contact grades, with spot-market trading dominant in textile and standard packaging applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in copolyesters hinges on molecular recycling scale economics displacing virgin resin cost curves, while engineering-grade specifications capture value from automotive electrification and medical device outsourcing trends.
For Market Incumbents: Anchor defensible positions through backward integration into PTA and bio-propanediol feedstocks, securing margin control against agricultural commodity volatility. Invest in blockchain-tracked mass-balance certification infrastructure to maintain access to German OEM and French retailer procurement channels as EPR schemes tighten. Prioritize in-house regulatory affairs capacity to compress cosmetics brand qualification cycles from 24 months toward 12-month benchmarks, defending against compounders with pre-validated FDA and EU dossiers. For New Entrants and Emerging Players: Begin with biodegradable aliphatic-aromatic grades for French and Dutch supermarket chains, where Citeo and Der Grüne Punkt schemes create preferential procurement channels with less entrenched incumbent competition. Target medical device housing applications in Japan's Chubu region, where gamma-stable USP Class VI compliance requirements filter out commodity suppliers. Pursue joint development agreements with enzymatic depolymerization technology licensors to shortcut molecular recycling infrastructure buildout. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-volume compounders lack capital to retrofit legacy PET lines for copolyester hygroscopicity handling or sustain 12-18 month FDA notification timelines. Long-term viability favors technology licensors with certified recycling platforms and formulation specialists with pre-validated medical and food-contact portfolios over commodity resin distributors losing procurement authority. Watch for inflection when Extended Producer Responsibility schemes in additional EU member states mandate verified recycled-content thresholds, accelerating preference for mass-balance-certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Propanediol | Captures margin from agricultural feedstock volatility while securing REACH carbon-intensity documentation for EU market access. |
| Molecular Recycling Capacity Expansion | Enables certified recycled-content supply for Eastman-scale cosmetics and food-contact applications without performance degradation. |
| Medical Device Grade Certification | Opens USP Class VI and gamma-stability positioning against polycarbonate in Japanese diagnostic equipment and wearable drug delivery. |
| Blockchain Mass-Balance Tracking | Satisfies German Tier-1 supplier requirements for cradle-to-gate carbon documentation under EU Green Deal border adjustments. |
| Textile Fiber Grade Development | Penetrates sportswear and automotive upholstery markets where bio-based PETG aligns with moisture management and sustainability claims. |
Methodological Framework
Bottom-up packaging and automotive modeling reconciled against top-down molecular recycling capacity tracking forms the analytical core of this study. Primary interviews with plant managers at compounding facilities, procurement leads at German Tier-1 suppliers, distribution channel partners in the Rhine-Ruhr cluster, and technical R&D directors at bio-based monomer producers were validated against secondary sources including ECHA registration databases, FDA food-contact notification filings, EU customs trade data for copolyester resin categories, and SEC 10-K disclosures from listed petrochemical majors. Triangulation between demand-side specification intensity and supply-side certification capacity yields volume and value estimates.
Input-output matrices segment the market across grade tier (thermoplastic, biodegradable, engineering, high-performance), end-use industry (packaging, automotive interiors, electronics, textiles, medical), and regional production hub (Germany, United States, China, Japan, France). CAGRs derive from regression analysis of historical specification shifts against regulatory deadline schedules and announced capacity additions. Key forecast inputs include EPR scheme rollout timelines, FDA notification queue lengths, and enzymatic depolymerization technology deployment rates.
Caveats apply where REACH carbon-border adjustment implementation delays or bio-propanediol feedstock cost spikes could materially shift the outlook for recycled-content grade economics. Forecasts reflect documented assumptions around molecular recycling yield rates and qualification cycle compression. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyethylene (PE) Foam Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Global Liquid Crystal Polymer (LCP) Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
China Geopolymer Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
South America Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Bismaleimide Monomer Market
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Global Microcellular Polyurethane Foam Market