
 Photoacoustic Imaging Market | 2026-2036
Photoacoustic Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Photoacoustic Imaging Market Intelligence
Aftermarket service revenue is narrowing as manufacturers bundle multi-year maintenance contracts into initial system sales. Siemens Healthineers leverages its installed base of ultrasound platforms to cross-sell photoacoustic modules. GE Healthcare anchors its position through deep integration with existing radiology workflows. iThera Medical GmbH specializes in preclinical systems that sustain premium pricing in academic research settings.
Photoacoustic imaging combines pulsed laser excitation with ultrasonic detection to generate high-resolution optical absorption maps of biological tissue, typically operating at near-infrared wavelengths between 680 and 970 nanometers for deep tissue penetration. The technique measures thermoelastic expansion induced by localized heating, enabling functional imaging of hemoglobin concentration and oxygen saturation without ionizing radiation. Imaging systems command the largest revenue share due to capital-intensive hardware requirements and lengthy sales cycles. Software segments exhibit faster expansion as vendors emphasize AI-powered reconstruction algorithms and quantitative biomarker extraction. Cancer detection applications attract disproportionate R&D investment given unmet needs in breast and skin oncology.
The FDA regulates photoacoustic devices under 21 CFR 892 for diagnostic ultrasound modifications, while the EU Medical Device Regulation requires notified body certification for laser-integrated systems. Japan's PMDA maintains distinct approval pathways that favor domestic clinical trial data, creating localization incentives for foreign manufacturers. Stakeholders must monitor evolving reimbursement codes for photoacoustic procedures across CMS, NHS England, and Japan's MHLW to validate commercial assumptions.
Market Dynamics
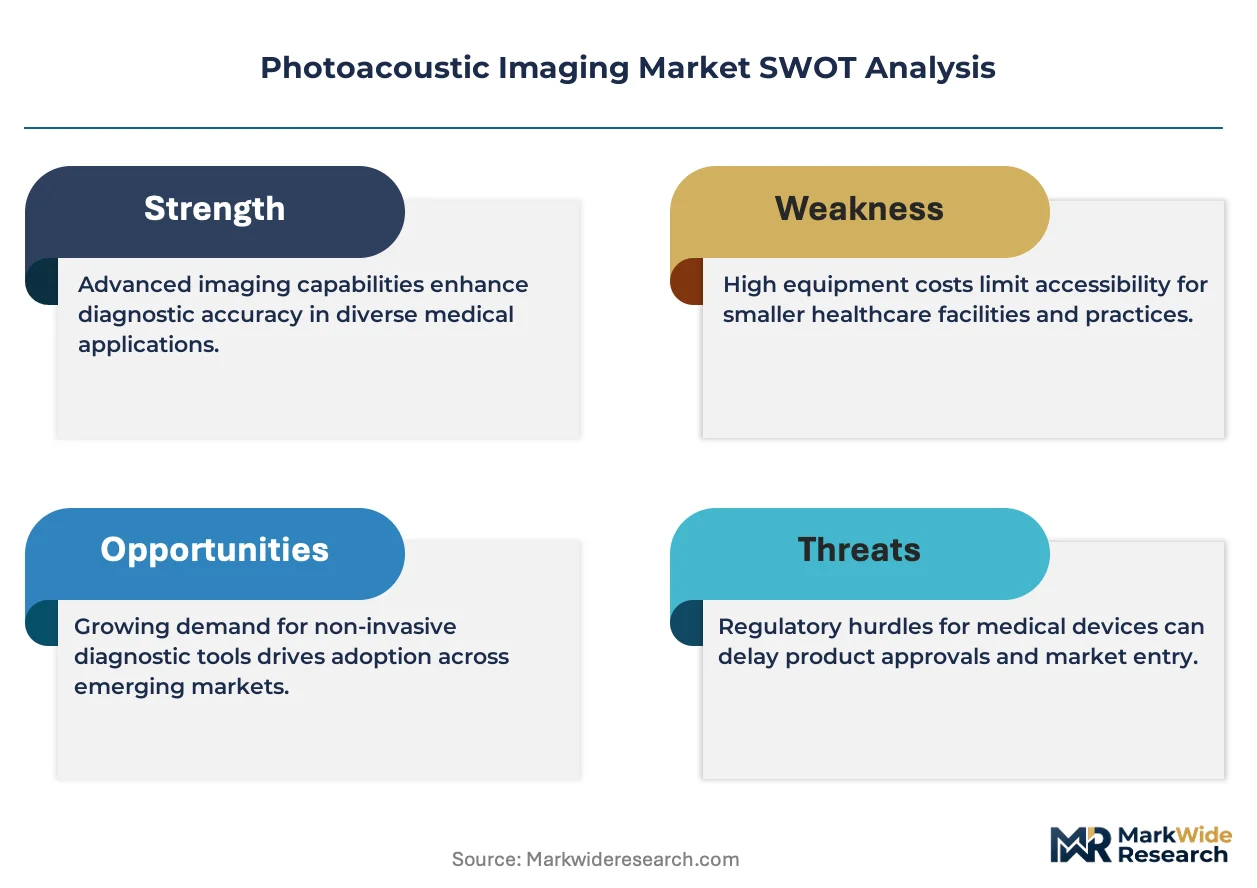
The FDA's breakthrough device designation pathway is compressing commercialization timelines for photoacoustic platforms, while academic medical centers in oncology departments drive disproportionate early adoption for tumor margin assessment applications.
Growth Catalysts
- Breakthrough Device Designation:The FDA pathway accelerates regulatory review for novel photoacoustic systems, reducing time-to-market for manufacturers targeting cancer detection applications.
- Oncology Department Demand:Academic medical centers seek non-invasive alternatives to traditional biopsy methods for intraoperative tumor margin assessment, creating sustained equipment refresh cycles.
- Laser-Ultrasound Convergence:Advances in pulsed laser miniaturization and ultrasonic transducer arrays enable portable system configurations that expand point-of-care deployment scenarios.
Market Restraints
- Capital Equipment Intensity:Photoacoustic imaging systems require substantial upfront investment in laser sources, acoustic detection arrays, and computational reconstruction hardware, limiting procurement to well-capitalized institutions.
- Reimbursement Code Gaps:CMS, NHS England, and Japan's MHLW maintain incomplete procedure coding for photoacoustic diagnostics, forcing providers to absorb costs or pursue experimental billing pathways.
- Optical Window Limitations:Near-infrared penetration depth constraints between 680 and 970 nanometers restrict functional imaging to superficial tissue layers, excluding deep organ applications without invasive probe insertion.
Strategic Opportunities
- Preclinical Research Premium:Academic institutions sustain pricing power for high-resolution small-animal imaging systems, with iThera Medical GmbH and comparable specialists capturing recurring grant-funded procurement cycles.
- AI-Powered Reconstruction:Machine learning algorithms for real-time photoacoustic image reconstruction reduce computational latency, enabling intraoperative guidance applications that command software subscription revenue streams.
- Workflow Integration:Deep embedding with existing radiology information systems and PACS infrastructure creates switching costs that protect installed base positions against modular competitors.
Industry Challenges
- Multidisciplinary Talent Scarcity:System development requires simultaneous expertise in laser physics, acoustic engineering, and clinical translation, with few training programs producing qualified hybrid specialists.
- Dual Certification Complexity:EU Medical Device Regulation mandates notified body review for laser-integrated diagnostic systems, layering CE marking requirements atop 21 CFR 892 ultrasound modifications for US market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photoacoustic Imaging Market |
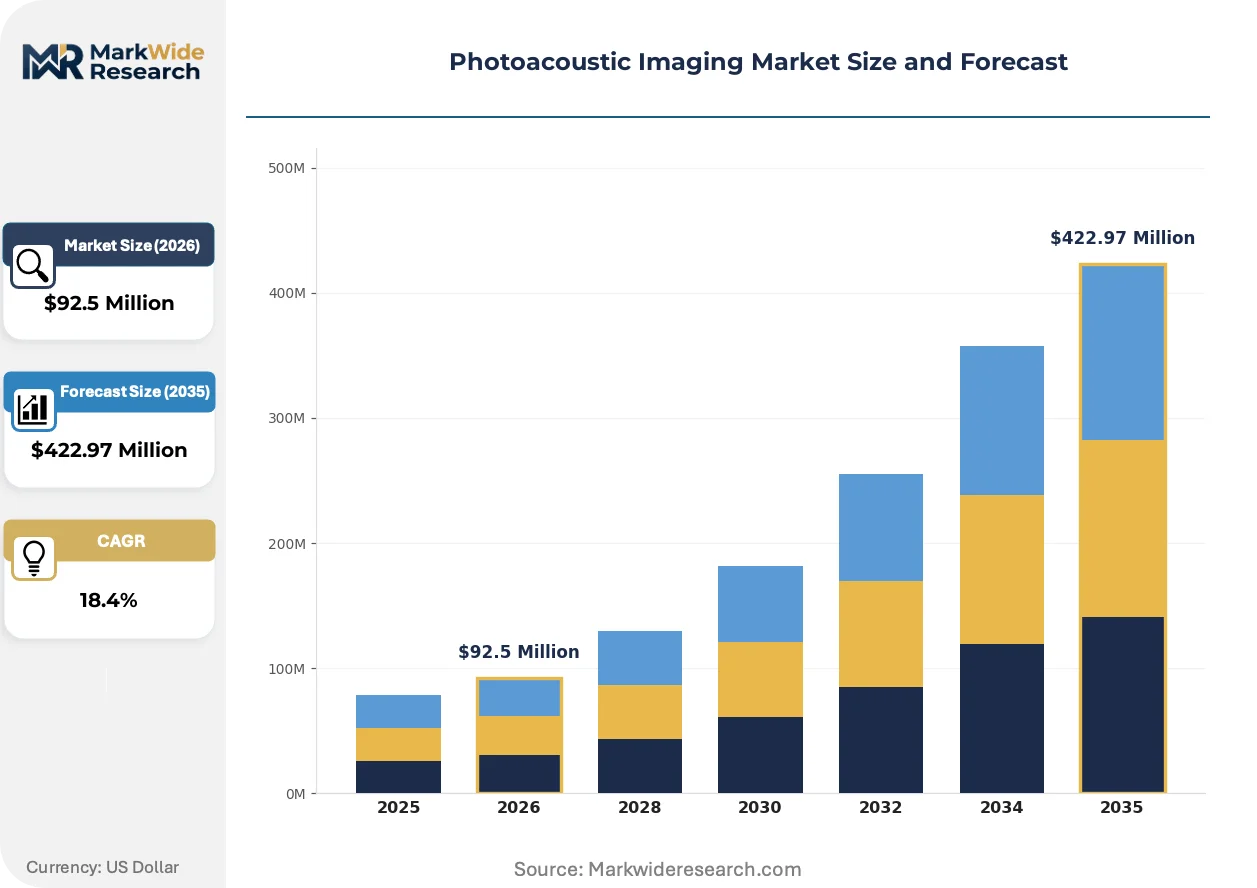
| Market Size in 2026 | $92.5 Million |
| Market Size in 2035 | $422.97 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Imaging Systems, Software, Probes, Accessories End User: Hospitals, Clinics, Research Institutions, Diagnostic Centers Technology: Multimodal Imaging, Ultrasonic Detectors, Laser Systems, Signal Processing Application: Cancer Detection, Cardiovascular Imaging, Therapeutic Monitoring, Tissue Characterization |
| Companies Covered | Siemens Healthineers, GE Healthcare, FUJIFILM Holdings Corporation, iThera Medical GmbH, Seno Medical Instruments Inc., Advantest Corporation, TomoWave Laboratories Inc., Verasonics Inc., illumiSonics Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photoacoustic Imaging Market Strategic Shifts & Innovations
Photoacoustic imaging is experiencing accelerated platform evolution as vendors compete on computational reconstruction speed, regulatory pathway efficiency, and seamless electronic health record integration.
Deep learning architectures are digitizing photoacoustic image formation, replacing iterative reconstruction algorithms with neural network inference that reduces processing time from minutes to seconds. Oncology surgical teams at academic medical centers are adopting these real-time systems for intraoperative guidance. The compression of reconstruction latency is digitizing the competitive basis of system performance, shifting vendor differentiation from hardware specifications to software optimization.
Japan's PMDA maintains distinct clinical trial data requirements that favor domestic validation studies for foreign manufacturers seeking market access. This regulatory architecture creates localization incentives for device companies to establish in-country clinical operations. European and North American vendors are responding by partnering with Japanese academic medical centers for prospective trials.
Service contract bundling is displacing discrete aftermarket revenue streams as manufacturers embed multi-year maintenance agreements into initial capital sales. Siemens Healthineers and GE Healthcare leverage installed ultrasound bases to cross-sell photoacoustic modules through consolidated procurement channels. This consolidation is most visible in the United States and Germany where radiology department purchasing authority concentrates capital acquisition decisions.
Photoacoustic Imaging Market Segmentation
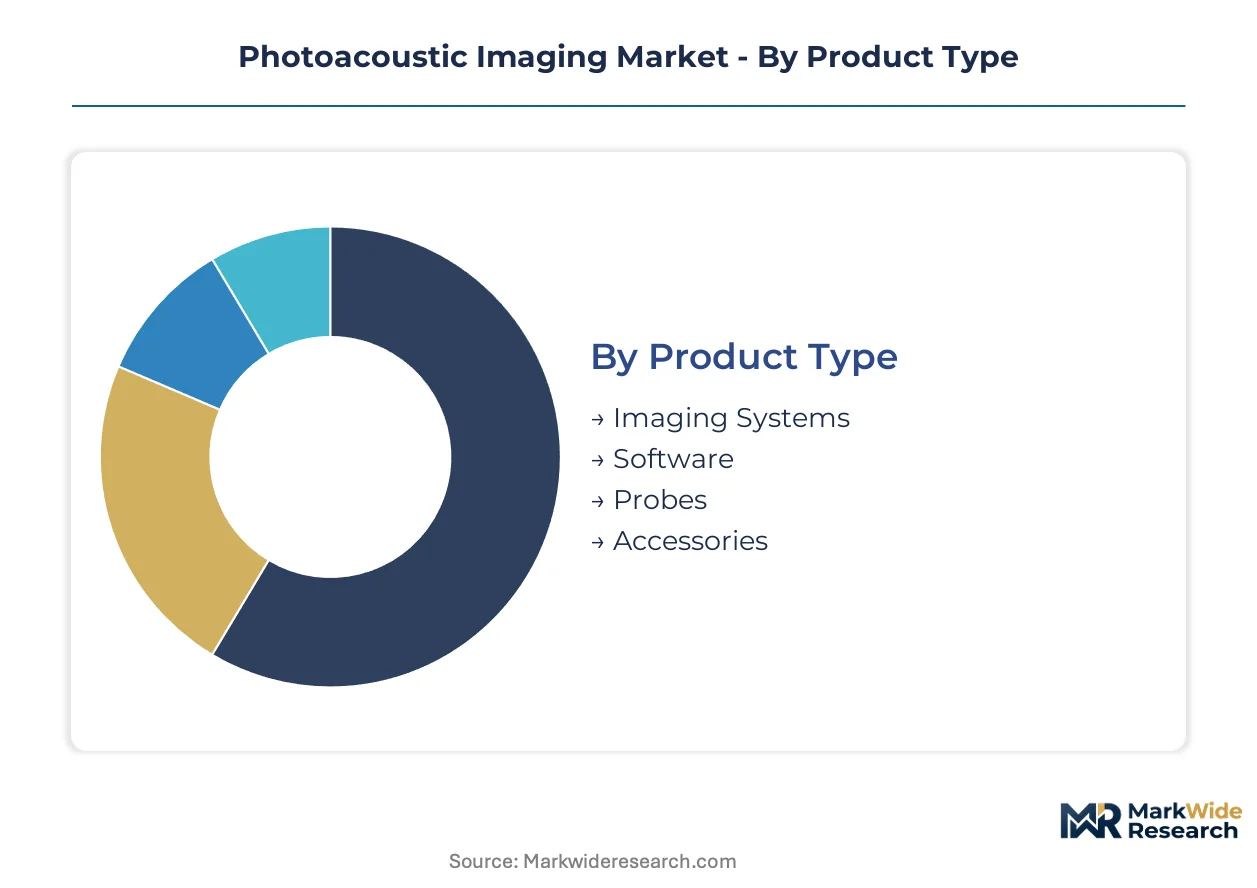
Photoacoustic imaging vendors configure product portfolios around capital intensity gradients and recurring revenue potential. Each segment category demands distinct manufacturing competencies, regulatory pathways, and commercial relationships that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across hardware versus software segments, with imaging systems requiring field engineering support while software layers generate remote update revenue.
- Imaging Systems:Integrated platforms combine tunable laser sources, multi-element ultrasonic arrays, and GPU-accelerated reconstruction workstations. Demand concentrates at academic medical centers in Germany and the United States where capital budgets accommodate seven-figure procurement cycles for intraoperative guidance suites.
- Software:AI-powered reconstruction algorithms and quantitative biomarker extraction tools deploy via subscription licensing. Research institutions in Japan drive fastest adoption as PMDA regulatory frameworks incentivize clinical validation partnerships with algorithm developers.
- Probes:Handheld acoustic detection arrays with fiber-coupled laser delivery for superficial tissue applications.
- Accessories:Consumable coupling gels, calibration phantoms, and disposable laser safety eyewear.
Imaging systems hold the largest share; momentum sits with software.
End User:
Procurement authority patterns diverge between centralized hospital radiology departments and distributed research grant funding cycles.
- Hospitals:Integrated delivery networks in the United States consolidate purchasing decisions through value analysis committees. Siemens Healthineers and GE Healthcare leverage existing ultrasound installed bases to cross-sell photoacoustic modules through consolidated capital equipment contracts.
- Research Institutions:Grant-funded laboratories sustain premium pricing for preclinical systems with sub-millimeter resolution specifications. iThera Medical GmbH dominates this segment through specialized small-animal imaging platforms that command recurring equipment refresh cycles.
- Clinics:Outpatient dermatology and breast imaging centers seeking point-of-care deployment.
- Diagnostic Centers:Independent imaging facilities pursuing differentiated service offerings.
Hospitals anchor volume procurement; research institutions sustain margin premiums.
Technology:
Component integration depth determines system portability and regulatory classification complexity.
- Multimodal Imaging:Hybrid platforms combining photoacoustic tomography with conventional ultrasound or optical coherence tomography. Oncology surgical teams at academic medical centers in Japan and Germany adopt these configurations for real-time tumor margin assessment.
- Laser Systems:Solid-state and fiber laser sources operating at near-infrared wavelengths between 680 and 970 nanometers. FDA breakthrough device designation pathways accelerate commercialization for manufacturers targeting cancer detection applications.
- Ultrasonic Detectors:Piezoelectric transducer arrays and capacitive micromachined sensors.
- Signal Processing:FPGA-based acquisition hardware and iterative reconstruction algorithms.
Multimodal imaging commands premium positioning; laser systems are climbing the fastest.
Application:
Clinical validation requirements and reimbursement pathway maturity create stark adoption velocity differences across use cases.
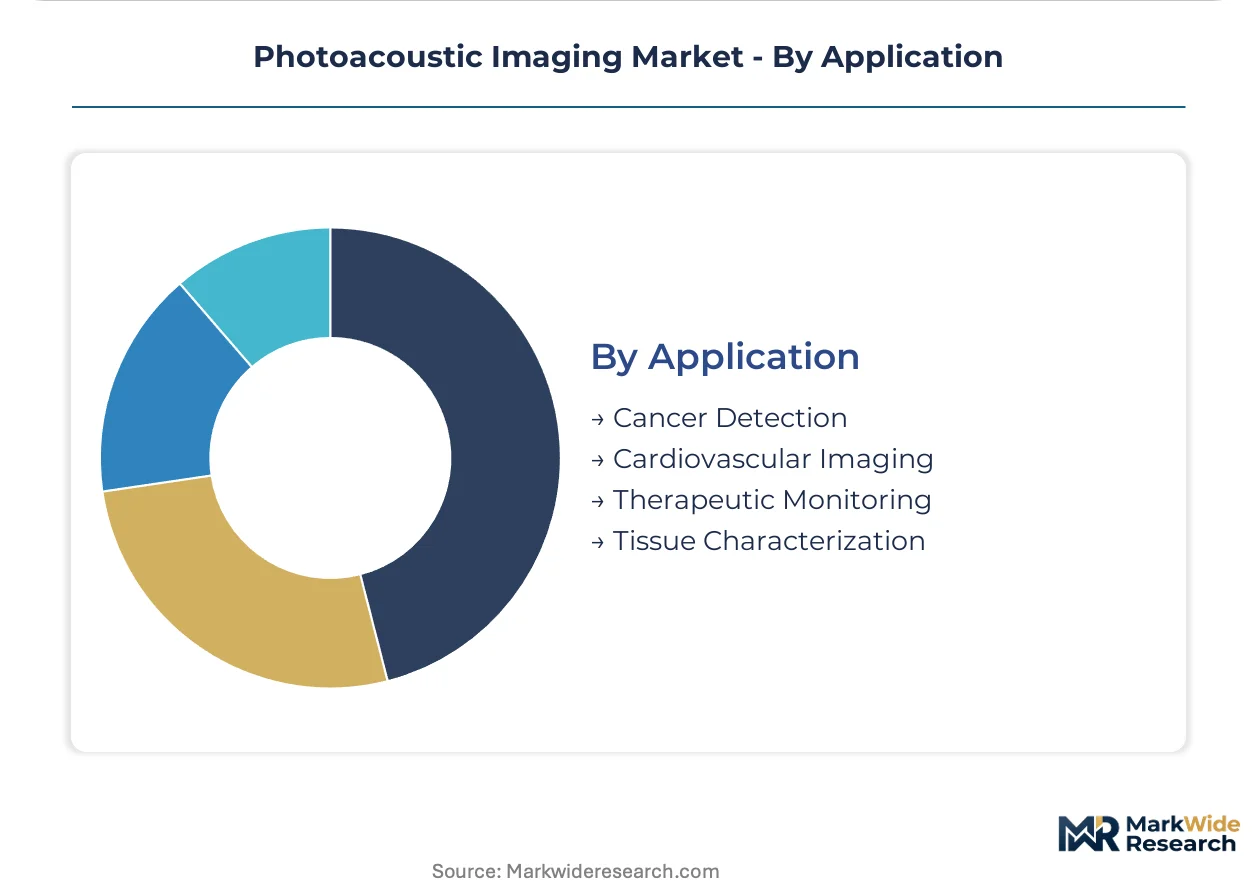
- Cancer Detection:Breast and skin oncology applications attract disproportionate R&D investment given unmet needs for non-invasive tumor margin assessment. Academic medical centers in the United States and Germany drive equipment procurement for intraoperative guidance protocols.
- Therapeutic Monitoring:Real-time visualization of tissue response to photothermal therapy and drug delivery. Research institutions in Japan pursue clinical trials under PMDA supervision to establish efficacy endpoints for regulatory submission.
- Cardiovascular Imaging:Plaque characterization and intravascular applications.
- Tissue Characterization:Preclinical studies of hemoglobin concentration and oxygen saturation mapping.
Cancer detection dominates commercial focus; therapeutic monitoring is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. Academic medical centers in Germany and Japan absorb premium pricing for intraoperative guidance systems, while outpatient clinics in emerging markets remain price-constrained and dependent on grant-funded procurement cycles.
United States
Oncology departments at academic medical centers in Boston and Houston drive capital equipment procurement for tumor margin assessment applications. FDA breakthrough device designation pathways compress regulatory review timelines for manufacturers targeting cancer detection. Siemens Healthineers and GE Healthcare leverage established ultrasound installed bases in the Midwest and Southeast to cross-sell photoacoustic modules through consolidated hospital network contracts.
Germany
Research institutions in Munich and Heidelberg sustain premium pricing for preclinical small-animal imaging systems with sub-millimeter resolution specifications. EU Medical Device Regulation mandates notified body certification for laser-integrated diagnostic systems, layering CE marking requirements atop existing quality frameworks. Bavarian medical technology clusters anchor European distribution for multimodal imaging platforms combining photoacoustic tomography with conventional ultrasound.
Japan
PMDA maintains distinct clinical trial data requirements that favor domestic validation studies for foreign manufacturers seeking market access. Tokyo and Osaka academic medical centers partner with international vendors for prospective trials under Japanese regulatory supervision. METI funding programs support localization incentives for device companies establishing in-country clinical operations and manufacturing partnerships.
United Kingdom
NHS England maintains incomplete procedure coding for photoacoustic diagnostics, forcing providers to absorb costs or pursue experimental billing pathways. London and Cambridge research hospitals concentrate grant-funded procurement for therapeutic monitoring applications. The Medicines and Healthcare products Regulatory Agency aligns with EU MDR standards post-Brexit, preserving certification continuity for laser-integrated systems.
China
NMPA regulatory frameworks for innovative medical devices accelerate review for photoacoustic platforms with domestic clinical trial data. Shanghai and Beijing academic hospitals drive demand for AI-powered reconstruction algorithms and quantitative biomarker extraction tools. MIIT industrial policy supports domestic manufacturing of pulsed laser sources and ultrasonic transducer arrays to reduce import dependence.
Photoacoustic Imaging Market Key Industry Players
Capability concentration sits with specialized preclinical system developers; scale advantage sits with diversified imaging conglomerates with established ultrasound installed bases. The market structures around three tiers: premium-tier integrated platform vendors, mid-tier modular attachment specialists, and grant-dependent preclinical research equipment providers. Strategic archetypes include workflow-embedded incumbents leveraging radiology information system integration, laser-physics specialists commanding academic research premiums, and algorithm-focused software vendors pursuing subscription revenue. Dominant competitive moves center on cross-selling photoacoustic modules through existing capital equipment relationships and bundling multi-year service contracts into initial system sales.
Within the diversified imaging conglomerate tier, Siemens Healthineers and GE Healthcare represent archetypal positions anchored by ultrasound platform installed bases that enable consolidated procurement channel access. iThera Medical GmbH exemplifies the specialized preclinical equipment archetype, occupying a position sustained by grant-funded academic research cycles and premium pricing for small-animal imaging resolution specifications. These three entities collectively illustrate the competitive divergence between scale-driven workflow integration and capability-driven research market specialization.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| FUJIFILM Holdings Corporation |
| iThera Medical GmbH |
| Seno Medical Instruments Inc. |
| Advantest Corporation |
| TomoWave Laboratories Inc. |
| Verasonics Inc. |
| illumiSonics Inc. |
| Others |
Cost & Logistics Intelligence
Laser source manufacturing concentrates in Germany and Japan, anchoring margin capture for tunable solid-state and fiber laser subsystems while downstream system integrators compete on software differentiation and service bundling. This upstream concentration shapes pricing power across the value chain, with acoustic detection arrays and GPU reconstruction hardware representing secondary cost centers.
Pricing Analysis
Multi-year service contracts embedded in initial system sales now generate the dominant share of lifetime customer value, displacing discrete aftermarket parts revenue. Three-tier pricing structure across premium, standard, and economy levels separates research-grade preclinical systems from hospital-deployed intraoperative guidance platforms and modular ultrasound attachments. Cost compression in mid-tier hospital procurement is intensifying because integrated delivery networks consolidate purchasing through value analysis committees. Research institutions exhibit lowest price sensitivity due to grant-funded procurement cycles, while outpatient diagnostic centers face acute budget constraints.
Supply Chain Analysis
Contract manufacturing for ultrasonic transducer arrays rests with specialized EMS providers in South Korea, Taiwan, and Germany, with limited alternative capacity for multi-element piezoelectric fabrication. System assembly draws from tunable laser sources, FPGA-based signal processing boards, and precision optical fiber couplings. Single-source vulnerability runs through qualified laser source suppliers holding FDA master files. Distribution runs through direct field sales for hospital systems and grant-funded academic channels for research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photoacoustic imaging represents a high-growth disruption propelled by FDA breakthrough device designation compressing regulatory timelines for cancer detection platforms. This regulatory inflection accelerates commercialization velocity and reshapes competitive entry economics.
For Market Incumbents: Pre-empt modular competitors by embedding photoacoustic modules into existing ultrasound platform refresh cycles through consolidated capital contracts. Deepen software subscription attach rates for AI-powered reconstruction algorithms to create switching costs. Defend against algorithm-focused entrants by accelerating PACS integration roadmaps and securing radiology information system partnerships. For New Entrants and Emerging Players: Therapeutic monitoring applications in Japan represent the most penetrable entry point, given PMDA's structured clinical trial partnerships and METI localization incentives. Preclinical small-animal imaging for grant-funded European research institutions offers second-mover viability with lower regulatory barriers. Pursue algorithm licensing models with Japanese academic medical centers to establish clinical validation credibility before hardware commercialization. For Investors and Strategic Acquirers: Capital is best deployed toward specialized preclinical system developers with established academic relationships and recurring grant-funded refresh cycles. Long-term viability hinges on regulatory pathway efficiency and software monetization scalability rather than hardware shipment volume alone. Watch FDA breakthrough designation grants to algorithm developers as the signal indicating shift toward software-differentiated competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates review timelines for photoacoustic cancer detection platforms targeting intraoperative guidance. |
| CE Marking Pathway | EU MDR notified body certification enables laser-integrated system commercialization across German hospital networks. |
| Hospital System Partnership | Integrated delivery network contracts consolidate procurement authority for ultrasound-embedded photoacoustic modules. |
| Software Companion Development | AI-powered reconstruction algorithms reduce latency for real-time intraoperative guidance applications. |
| Reimbursement Strategy | CMS and NHS England coding advocacy validates commercial assumptions for outpatient diagnostic deployment. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, PMDA approval databases, and hospital procurement records. Primary interviews engaged biomedical engineers at academic medical centers, hospital purchasing committee members, GPO contracts managers, and laser systems technical directors. Secondary sources included CMS reimbursement code databases, EU MDR notified body certification registries, and grant funding disclosures from NIH and Deutsche Forschungsgemeinschaft. Bottom-up equipment shipment modeling and top-down addressable market sizing were triangulated against capital budget surveys from radiology departments.
Forecast inputs include installed base refresh cycles, regulatory approval velocity by geography, and software subscription attach rate assumptions across the projection horizon. Segmentation dimensions encompass product type, end user procurement authority, technology integration depth, and application clinical validation status. CAGRs were derived from equipment procurement pipeline analysis and grant funding trajectory assessment. Specific inputs include pulsed laser miniaturization cost curves and ultrasonic transducer array manufacturing yield improvements.
Macroeconomic conditions sit as an overlay; deviation in NIH grant funding levels, hospital capital expenditure cycles, or laser component import tariffs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement code adoption velocity. Quarterly review of FDA breakthrough designation grants, PMDA clinical trial partnership announcements, and CMS coding updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Photography Ring Flash Market
Imaging
Global Pathology Imaging Systems Market
Imaging
Mobile Imaging Services Market
Imaging
Hyperspectral Cameras Market
Imaging
Vintage Cameras Market
Imaging
CMOS X-Ray Detectors Market
Imaging
Thermal Camera Market
Imaging
Hyper Spectral Imaging System Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Thermal Imaging Camera Market
Imaging
Japan Digital X-Ray Market
Imaging
Camera Technology Market
Imaging
Hybrid Imaging Systems Market
Imaging
Global Image Processing Systems Market
Imaging
Global Backscatter X-Ray Devices Market
Imaging
Holographic Imaging Market