
 Uncooled Infrared Imaging Market | 2026-2036
Uncooled Infrared Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Uncooled Infrared Imaging Market Analytics
Buyer concentration among defense integrators is hardening as prime contractors consolidate supplier lists for long-term thermal imaging programs. Teledyne FLIR LLC leverages its vertically integrated sensor-to-system pipeline to secure multi-year government contracts. Leonardo DRS anchors its position through captive manufacturing of vanadium oxide microbolometers for military end users. Lynred competes on wafer-scale production economics, supplying detector arrays to European and Asian OEMs.
Uncooled infrared imaging relies on microbolometer focal plane arrays fabricated from vanadium oxide or amorphous silicon thin films, operating at ambient temperature without cryogenic cooling and detecting thermal radiation in the 8-14 μm wavelength band for night vision, industrial thermography, and autonomous sensing. The microbolometer segment dominates unit shipments due to mature MEMS fabrication and falling die costs, while the imaging sensor category captures disproportionate value through ASIC integration and embedded analytics. Military application demand sustains premium pricing for radiation-hardened variants, whereas automotive adoption is expanding fastest among commercial end users driven by pedestrian detection mandates.
The U.S. Department of Defense ITAR regime restricts thermal sensor exports, compelling foreign buyers to source through licensed channels or develop indigenous alternatives. EAR dual-use classifications administered by the U.S. Commerce Department shape cross-border technology flows, while EU CE marking under the Radio Equipment Directive governs product access for civilian thermal cameras sold in Europe. Stakeholders must monitor evolving export control list revisions and onshoring subsidy programs that could abruptly reroute supply relationships.
Market Dynamics
Defense procurement agencies are consolidating supplier relationships around vertically integrated thermal imaging providers, compressing the vendor landscape while elevating long-term contract security as the primary competitive dimension.
Growth Catalysts
- EU AI Act:The EU AI Act mandates on-device processing for biometric identification systems, accelerating demand for edge-capable thermal sensors with embedded ASICs.
- Automotive pedestrian detection:NHTSA-equivalent mandates in multiple jurisdictions are embedding thermal cameras into advanced driver-assistance systems for nighttime pedestrian safety.
- Vanadium oxide microbolometers:MEMS fabrication advances are reducing die costs while improving temperature coefficient performance, expanding addressable applications.
Market Restraints
- ITAR export controls:The U.S. Department of Defense's International Traffic in Arms Regulations restrict thermal sensor exports, fragmenting supply access for non-U.S. buyers.
- Amorphous silicon wafer supply:Concentration of thin-film deposition equipment among Japanese and German toolmakers creates input bottlenecks during demand surges.
- Pixel pitch limitations:Diffraction limits at 8-14 μm wavelengths constrain resolution improvements below 12-micron pitches without cryogenic cooling.
Strategic Opportunities
- India industrial thermography:BIS certification alignment and PLI scheme incentives are opening procurement channels for uncooled sensors in predictive maintenance applications.
- Drone-mounted thermal payloads:Convergence of uncooled microbolometers with gimbal stabilization and AI-enabled object tracking is creating new aerial inspection verticals.
- EU Green Deal subsidies:Building energy audit mandates are accelerating replacement of legacy spot pyrometers with thermal imaging cameras for envelope leakage detection.
Industry Challenges
- Radiation-hardened ASIC design:Military qualification timelines for custom readout integrated circuits extend 18-24 months, compressing product refresh cycles.
- Multi-spectral fusion integration:Combining thermal, visible, and SWIR channels requires specialized optical alignment expertise that remains scarce among system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Uncooled Infrared Imaging Market |
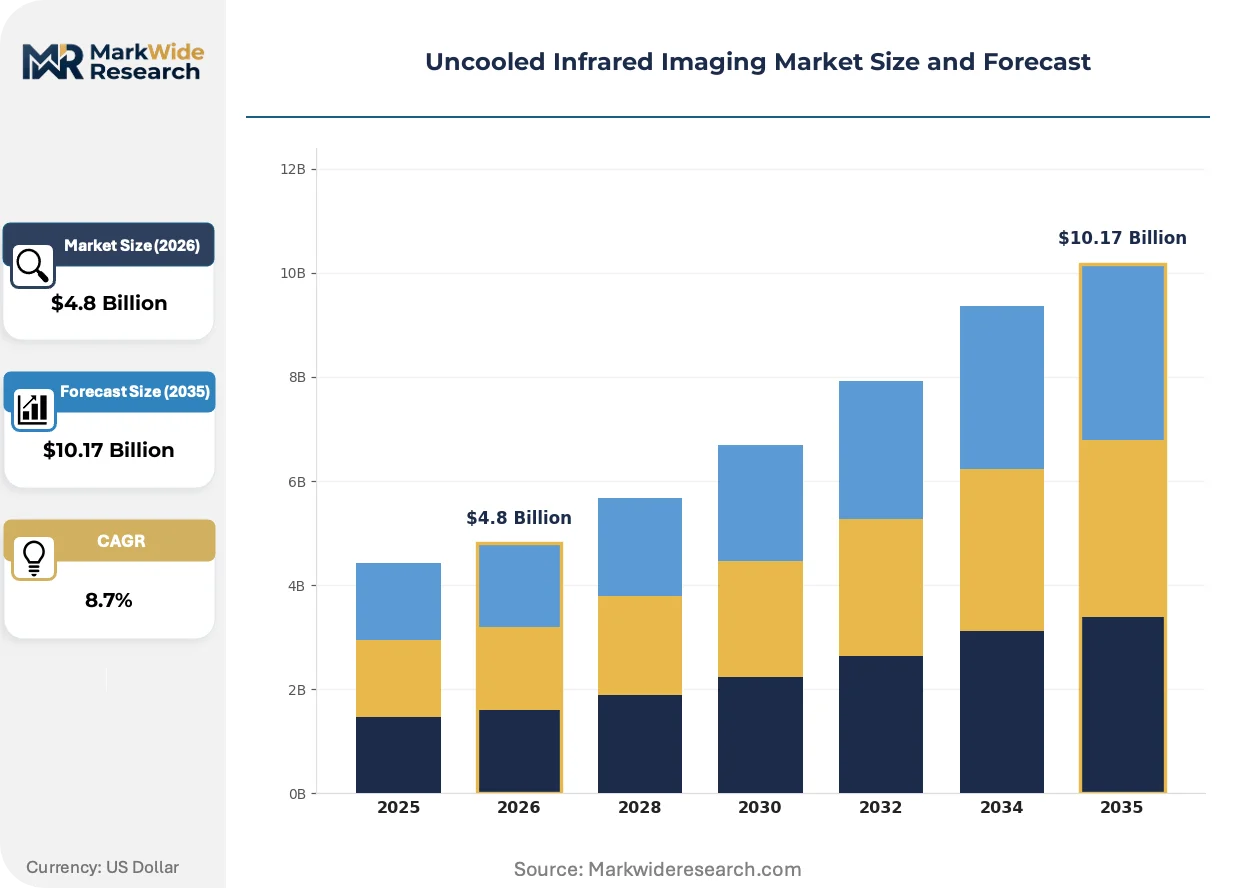
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bolometer, Microbolometer, Thermal Detector, Imaging Sensor Application: Building Inspection, Surveillance, Automotive, Military Industry Vertical: Aerospace, Healthcare, Manufacturing, Retail End User: Government, Commercial, Industrial, Residential |
| Companies Covered | Xenics NV, VIGO System, Teledyne FLIR LLC, Leonardo DRS, Zhejiang ULIRVISION Technology Co Ltd, BAE Systems, Cantronic Systems Inc, L3Harris Technologies, Lynred, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Uncooled Infrared Imaging Market Evolving Landscape
Wafer-scale packaging and heterogeneous integration are compressing form factors while elevating thermal sensitivity, reshaping competitive differentiation from raw detector performance toward system-level analytics capability.
Amorphous silicon microbolometers with pixel pitches below 12 microns are electrifying the automotive night vision segment. Tier 1 suppliers are qualifying these sensors for 2026 model-year pedestrian detection systems. The technology is electrifying cost structures by eliminating thermoelectric stabilizers previously required for temperature drift compensation.
The EU AI Act's prohibition on remote biometric identification in public spaces is redirecting R&D investment toward on-device inference architectures. Manufacturers are embedding neural processing units directly into thermal camera modules to ensure compliance. European OEMs are responding fastest, with French and German integrators leading qualification programs for privacy-preserving edge analytics.
Defense primes are unbundling sensor procurement from system integration, creating direct purchasing relationships with detector foundries previously accessed only through prime contractor tiers. This disintermediation is compressing margins for middle-tier integrators while rewarding wafer-scale producers with captive capacity. The pattern is most visible in the United States, where the Army's IVAS program and Marine Corps' Squad Binocular Night Vision initiatives are driving the shift.
Uncooled Infrared Imaging Market Segmentation
Uncooled infrared imaging segments diverge sharply between standalone thermal cameras and embedded sensor modules. The former command higher unit margins but slower refresh cycles; the latter integrate into larger systems with volume scaling but compressed pricing. Understanding this integration-depth split reveals where component suppliers retain leverage versus where system integrators capture value.
Product Type:
Standalone thermal cameras require complete signal chains and housing, while embedded detectors ship as bare die or packaged arrays for integration into larger systems.
- Microbolometer:Vanadium oxide or amorphous silicon thin-film arrays fabricated via MEMS processes detect 8-14 μm radiation without cryogenic cooling. Automotive pedestrian detection mandates in Germany and pedestrian safety regulations administered by NHTSA are concentrating demand among Tier 1 suppliers qualifying 12-micron pitch designs for 2026 model-year integration.
- Imaging Sensor:ASIC-integrated focal plane arrays with embedded readout circuits and neural processing units enable on-device inference for EU AI Act compliance. French and German OEMs are fastest to qualify these privacy-preserving edge analytics modules for biometric identification systems in public infrastructure.
- Bolometer:Discrete thermal resistive elements without integrated readout electronics serve laboratory and calibration equipment manufacturers requiring configurable signal chains.
- Thermal Detector:Pyroelectric and thermopile alternatives address cost-sensitive motion detection and presence sensing in building automation systems.
Microbolometer arrays lead volumes today; imaging sensors with embedded ASICs are gaining share fastest.
Application:
Cost tier separates military-qualified systems from commercial variants, with automotive emerging as a volume bridge between premium defense pricing and commoditized industrial segments.
- Military:Radiation-hardened microbolometers with custom ROIC designs sustain 18-24 month qualification timelines and premium pricing. U.S. Army IVAS and Marine Corps Squad Binocular Night Vision programs are consolidating procurement around vertically integrated suppliers with captive wafer fabrication in Texas and Arizona defense corridors.
- Automotive:Amorphous silicon microbolometers below 12-micron pitch eliminate thermoelectric stabilizers, cutting cost structures for nighttime pedestrian detection. Japanese and German Tier 1 suppliers are driving fastest adoption among commercial end users.
- Surveillance:Fixed and pan-tilt thermal cameras for perimeter security and critical infrastructure protection compete on detection range and analytics integration.
- Building Inspection:Handheld thermography for envelope leakage detection and energy audit compliance accelerates under EU Green Deal subsidy programs.
Military applications sustain highest margins; automotive qualification programs are climbing the fastest.
Industry Vertical:
Customer type determines specification stringency, with aerospace and healthcare demanding traceable calibration chains absent in manufacturing and retail deployments.
- Manufacturing:Predictive maintenance thermography for electrical panels, rotating equipment, and process vessels represents the largest installed base. India's PLI scheme incentives and BIS certification alignment are opening procurement channels for uncooled sensors in industrial facilities.
- Aerospace:UAV-mounted thermal payloads require gimbal stabilization and AI-enabled object tracking for aerial inspection verticals. Drone integrators in France and Germany are fastest to qualify compact uncooled modules.
- Healthcare:Fever screening and medical thermography applications demand FDA or equivalent regulatory clearance with documented temperature measurement accuracy.
- Retail:People counting and occupancy analytics represent emerging demand for privacy-preserving thermal sensing without biometric identification.
Manufacturing leads vertical volumes today; aerospace drone integration is expanding most quickly.
End User:
Maturity separates government procurement with multi-year program commitments from commercial buyers with shorter replacement cycles and price sensitivity.
- Government:Defense and security agencies consolidate supplier relationships around long-term thermal imaging programs with ITAR-controlled technology flows. U.S. procurement concentrates in Texas and Arizona corridors with restricted export access for foreign buyers.
- Industrial:Energy, utilities, and process manufacturers deploy thermal cameras for condition monitoring and safety compliance with faster refresh cycles than government programs.
- Commercial:Security integrators and building automation providers source through distribution with shorter lead times and standardized specifications.
- Residential:DIY thermography and smart home integration represent nascent demand with highest price elasticity.
Government end users anchor revenue stability; industrial buyers are scaling fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense electronics engineers and MEMS fabrication specialists concentrate in Texas and Arizona corridors, anchoring U.S. production capacity for uncooled microbolometers while European wafer-scale foundries compete on process economics.
United States
The Army's IVAS program and Marine Corps Squad Binocular Night Vision initiatives drive procurement consolidation around vertically integrated suppliers. ITAR restrictions administered by the U.S. Department of State fragment export access for foreign buyers. Defense corridors in Texas and Arizona host captive wafer fabrication for radiation-hardened microbolometers.
Germany
Automotive Tier 1 suppliers qualify 12-micron pitch amorphous silicon designs for 2026 model-year pedestrian detection systems. KBA vehicle safety regulations align with EU Green Deal building energy audit mandates. Stuttgart and Munich industrial clusters concentrate thermal camera module integration for both automotive and industrial thermography.
France
Drone integrators qualify compact uncooled modules for aerial inspection verticals combining gimbal stabilization with AI-enabled object tracking. CNIL privacy guidelines and EU AI Act biometric prohibitions redirect R&D toward on-device inference architectures. Paris and Grenoble technology corridors lead qualification programs for edge-analytics thermal sensors.
Japan
Thin-film deposition equipment concentration among Japanese toolmakers creates input bottlenecks during demand surges for amorphous silicon wafer supply. METI industrial technology roadmaps support MEMS fabrication advances. Tokyo-Osaka manufacturing belts anchor microbolometer die production for Asian OEMs.
India
BIS certification alignment and PLI scheme incentives open procurement channels for uncooled sensors in predictive maintenance applications across electrical utilities and process manufacturing. CEA energy efficiency mandates accelerate industrial thermography adoption. Gujarat and Maharashtra industrial corridors concentrate thermal camera distribution networks.
Uncooled Infrared Imaging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a consolidating vendor landscape where long-term contract security has displaced raw detector performance as the primary competitive dimension. Three archetypes dominate: vertically integrated sensor-to-system providers with captive wafer fabrication, wafer-scale detector foundries supplying OEM channels, and defense primes unbundling procurement to establish direct foundry relationships. M&A activity concentrates on MEMS fabrication assets while strategic partnerships proliferate around multi-spectral fusion integration.
Within the vertically integrated tier, Teledyne FLIR LLC and Leonardo DRS exemplify providers controlling sensor-to-system pipelines through in-house production of vanadium oxide microbolometers. Lynred occupies a position among European wafer-scale specialists competing on die economics for detector array supply. Zhejiang ULIRVISION Technology Co Ltd represents Chinese fabricators addressing cost-sensitive industrial thermography segments through packaged module exports.
| Leading Market Players |
|---|
| Xenics NV |
| VIGO System |
| Teledyne FLIR LLC |
| Leonardo DRS |
| Zhejiang ULIRVISION Technology Co Ltd |
| BAE Systems |
| Cantronic Systems Inc |
| L3Harris Technologies |
| Lynred |
| Others |
Value Network & Pricing Analysis
Captive wafer fabrication in Texas and Arizona defense corridors anchors supply positioning for radiation-hardened microbolometers while simultaneously securing pricing power through ITAR-controlled access restrictions. This integration pattern insulates domestic suppliers from foreign competition but exposes non-U.S. buyers to fragmented supply channels and elevated procurement costs.
Pricing Analysis
Capacity additions in Japan and Germany are reshaping price floors for amorphous silicon microbolometers destined for automotive pedestrian detection systems. Three-tier pricing structure across ITAR-restricted military, automotive-qualified commercial, and uncertified industrial tiers separates buyers by qualification burden and volume commitment. Pricing pressure stems from wafer-scale foundries competing on die economics for embedded sensor modules. Industrial thermography buyers exhibit highest price sensitivity, while defense integrators accept premiums for radiation-hardened ROIC designs with 18-24 month qualification timelines.
Supply Chain Analysis
Military qualification gating through ITAR and EAR dual-use classifications fragments supply access and creates tiered distribution structures based on end-user citizenship and end-use certification. Manufacturing concentrates in the United States, Japan, and Germany, with thin-film deposition equipment for amorphous silicon wafers drawing from Japanese and German toolmakers. Vanadium oxide precursor chemicals and MEMS fabrication equipment represent critical input dependencies. Single-source vulnerability in deposition tool supply creates bottlenecks during demand surges. Distribution runs through defense primes for military end users, Tier 1 automotive suppliers for vehicle integration, and industrial distributors for commercial thermography applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where ITAR restrictions in the United States create premium pricing corridors that European and Asian competitors can undercut through uncontrolled technology flows, provided they bypass U.S. content thresholds.
For Market Incumbents: Acquire MEMS fabrication assets in ITAR-exempt jurisdictions to maintain defense revenue while building parallel commercial capacity. Consolidate supplier relationships around long-term thermal imaging programs before defense primes complete disintermediation toward direct foundry purchasing. Counter the threat of European wafer-scale competitors by accelerating qualification timelines for embedded ASIC designs with on-device inference capability. For New Entrants and Emerging Players: The EU AI Act in Europe opens a window for edge-analytics thermal camera modules that process biometric data without cloud transmission. Target building inspection applications under EU Green Deal subsidy programs where certification requirements remain less stringent than automotive or military tiers. Pursue white-label partnerships with French and German drone integrators seeking compact uncooled modules for aerial inspection verticals. For Investors and Strategic Acquirers: Consolidation pressure builds where defense primes unbundle sensor procurement from system integration, elevating wafer-scale foundries with captive capacity above middle-tier integrators. Five-to-ten year viability favors vertically integrated sensor-to-system providers with ITAR licensing and in-house ROIC design capability. Watch for Army IVAS program contract awards as inflection indicators for supplier ranking stability.| Strategic Initiative | Industry Significance |
|---|---|
| Wafer-Scale MEMS Capacity Expansion | Captures die cost reductions from 12-micron pitch amorphous silicon migration for automotive qualification. |
| On-Device ASIC Integration | Enables EU AI Act compliance for biometric identification systems without cloud processing architectures. |
| ITAR Licensing Investment | Secures defense procurement access for radiation-hardened microbolometer supply to Army IVAS programs. |
| Multi-Spectral Fusion Partnership | Combines thermal, visible, and SWIR channels for advanced driver-assistance system Tier 1 qualification. |
| Drone Payload Module Development | Addresses aerial inspection demand from French and German integrators requiring gimbal-stabilized thermal imaging. |
Research Methodology
Coverage spans the United States, Germany, France, Japan, and India, with primary inputs from each regional cluster combining defense procurement officers, MEMS fabrication engineers, Tier 1 automotive supplier procurement leads, and thermal camera system integrators. Secondary validation draws from ITAR-controlled technology export filings, EAR dual-use classification registers, EU AI Act implementation guidance, and customs records for microbolometer die shipments. Bottom-up unit shipment estimates from detector foundries triangulate against top-down defense budget allocation analysis for thermal imaging programs.
Rate-of-change decomposition separates volume growth from value capture across the projection horizon, modeling microbolometer die shipments, ASIC-integrated imaging sensor modules, and complete thermal camera systems as distinct revenue streams. Segmentation dimensions include pixel pitch tier, end-use qualification level, and regional regulatory cluster. CAGRs derive from slope-intercept modeling of historical procurement patterns adjusted for EU AI Act compliance deadlines and NHTSA-equivalent pedestrian detection mandate timelines. Forecast inputs incorporate foundry capacity expansion announcements and defense program budget authorization trajectories.
Revisions become necessary when export control list revisions, onshoring subsidy program expansions, or foundry equipment delivery delays materialize differently than baseline assumptions. Forecasts reflect documented assumptions about ITAR restriction continuity, automotive qualification timeline adherence, and wafer-scale yield improvement curves. A model refresh is warranted upon material change in Army IVAS program scope or EU AI Act enforcement intensity for biometric identification systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Asia Pacific Smartphone Camera Module Market
Imaging
Photo Kiosk Market
Imaging
Underwater Camera Market
Imaging
Microscope Digital Cameras Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Global Trail Camera Market
Imaging
Near-Infrared Fluorescence Imaging System Market
Imaging
Global Ingaas Camera Market
Imaging
Industrial Machine Vision Market
Imaging
Japan Digital X-Ray Market
Imaging
Smart Camera Market
Imaging
Photoacoustic Microscope Market
Imaging
Digital Camera Market
Imaging
Biophotonics Market
Imaging
Semiconductor CD-SEM Systems Market
Imaging
APAC Image Sensors Market