
 Global Image Processing Systems Market | 2026-2036
Global Image Processing Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Image Processing Systems Market Intelligence
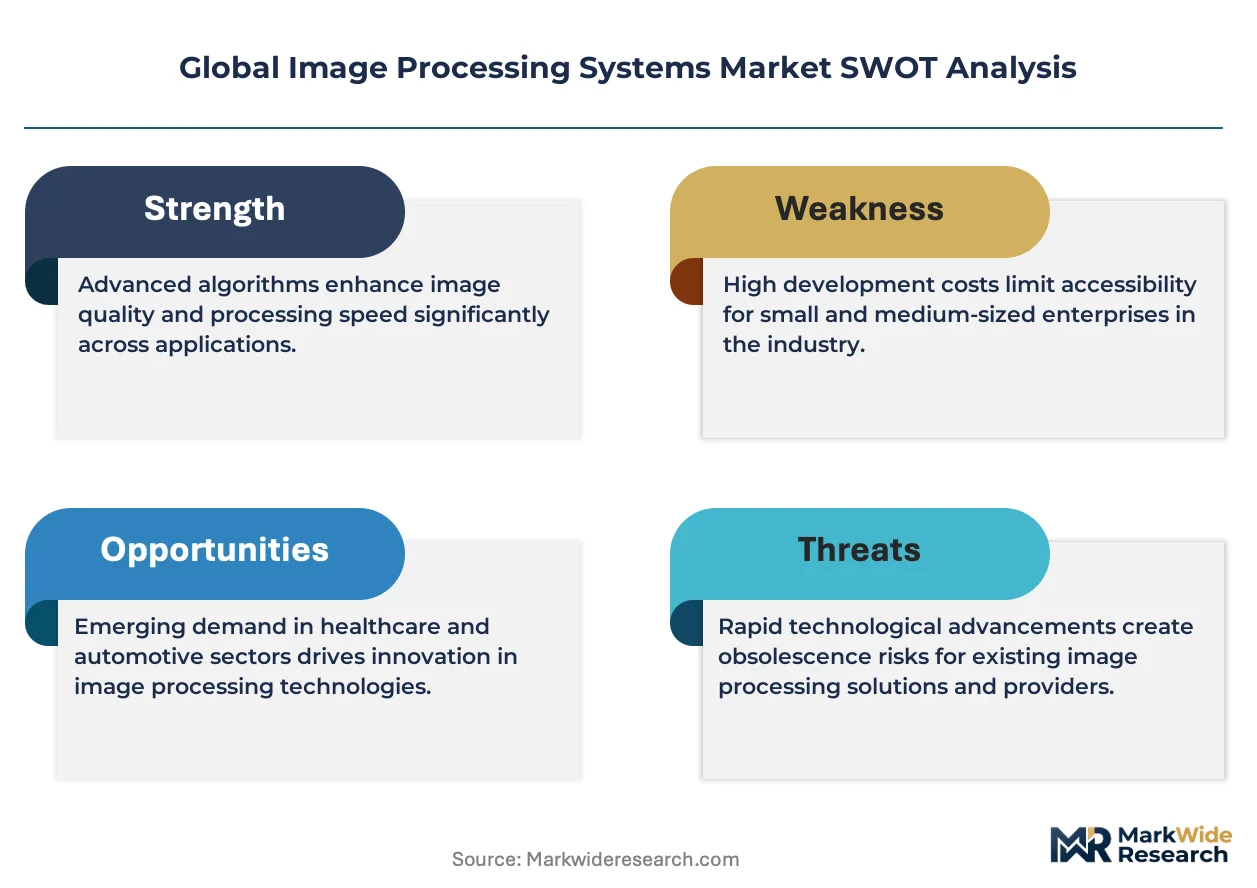
Germany's expanded manufacturing capacity for industrial automation is tilting the European competitive landscape for vision systems. Cognex Corporation leverages its deep software expertise in factory automation applications. Keyence Corporation specializes in high-precision sensors and integrated vision systems for complex inspection tasks. Basler AG competes on the strength of its extensive camera portfolio and modular hardware components.
Image processing systems are integrated setups that capture, analyze, and interpret visual information from the environment. These systems often utilize high-resolution CMOS sensors and specialized algorithms to perform tasks beyond human capability. Within applications, quality inspection in manufacturing plants remains the dominant revenue source, while medical imaging represents a high-margin niche. The technology segment shows a clear shift from traditional machine vision algorithms toward neural networks, which are better suited for complex pattern recognition.
Regulatory frameworks such as the FDA's requirements for medical devices in the United States and the EU's CE marking under the Medical Device Regulation (MDR) impose stringent validation standards. In China, GB standards for industrial equipment influence system design and interoperability. Stakeholders must now decide whether to develop specialized, compliant systems for high-value regulated markets or pursue volume in less-regulated industrial sectors.
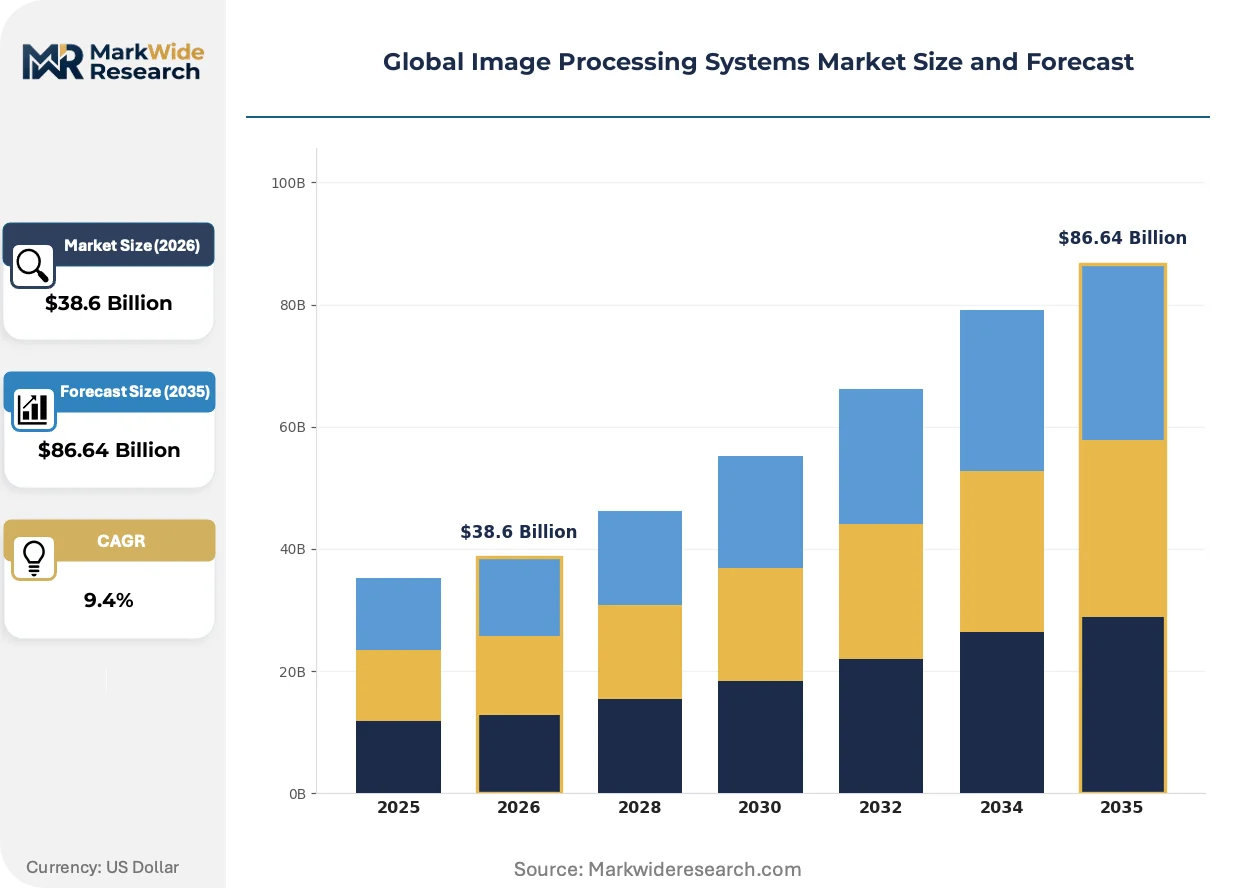
Market Dynamics
The convergence of neural network algorithms with edge computing hardware defines the market's current trajectory. This combination enables on-device processing, shifting value from generic camera hardware to specialized software capable of handling complex, real-time inspection tasks in manufacturing and logistics.
Growth Catalysts
- Industrial Automation Initiatives:China's national initiatives to upgrade manufacturing infrastructure, alongside Germany's focus on Industry 4.0, create sustained demand for automated quality inspection systems to improve productivity and reduce defects.
- Proliferation of Edge AI:The integration of AI accelerators into system-on-chip designs enables faster, lower-latency image analysis directly on the factory floor, expanding applications in high-speed sorting and robotic guidance.
- Medical Imaging Advancements:Growing requirements for high-precision diagnostics in pathology and radiology drive adoption of specialized image processing systems for cellular analysis, representing a high-margin segment.
Market Restraints
- High Implementation Costs:The significant initial capital outlay for high-resolution cameras, specialized lighting, and integration services presents a barrier for small and medium-sized enterprises, particularly in price-sensitive industrial sectors.
- Data and Algorithm Complexity:Developing and training robust neural networks for specific inspection tasks requires vast, high-quality labeled datasets and specialized machine learning expertise, which remains a bottleneck for custom applications.
- Stringent Validation Hurdles:Navigating regulatory frameworks like the FDA's requirements in the U.S. and the EU's MDR for medical imaging systems involves lengthy and costly validation processes, slowing market entry.
Strategic Opportunities
- Agricultural Technology (AgriTech):Application of image processing for crop monitoring, weed detection, and automated harvesting presents an underpenetrated market, especially for drone-based and robotic systems that can improve yield and reduce chemical use.
- Hyperspectral and 3D Imaging:Combining traditional 2D imaging with hyperspectral or 3D data provides richer information for sorting materials in recycling or detecting subsurface defects in manufacturing, creating new value propositions.
- Southeast Asian Manufacturing Hubs:Targeting emerging manufacturing economies like Vietnam and Thailand with scalable, cost-effective vision systems for electronics and automotive assembly offers significant volume growth potential.
Industry Challenges
- Shortage of Integration Expertise:A scarcity of engineers skilled in both machine vision hardware and deep learning software development complicates system deployment and customization, leading to longer project timelines and higher service costs.
- Interoperability with Legacy Systems:Integrating modern image processing systems with existing factory automation infrastructure, such as older PLCs and MES software, creates significant technical and compatibility hurdles for system integrators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Image Processing Systems Market |
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $86.64 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hardware, Software, Embedded Systems, FPGA Boards, ASICs Technology: Machine Vision, Digital Signal Processing, Neural Networks, Edge Computing, Cloud Computing Application: Quality Inspection, Traffic Management, Facial Recognition, Medical Imaging, Agricultural Monitoring End User Industry: Manufacturing Plants, Transport Authorities, Security Firms, Diagnostic Centers, Farming Enterprises |
| Companies Covered | Basler AG, Cognex Corporation, Intel Corporation, CARL ZEISS Industrielle Messtechnik, Datalogic S.p.A, GÖPEL electronic GmbH, DELTA Electronics, Keyence Corporation, NVIDIA Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Image Processing Systems Market Strategic Shifts & Innovations
The market's evolution is defined by a decisive shift toward software-centric value and algorithmic performance. Innovations are now centered on improving analytical capabilities and meeting increasingly stringent, data-driven regulatory requirements for validation and traceability across industries.
Deep learning, particularly convolutional neural networks (CNNs), provides advanced pattern recognition for image analysis. Manufacturers in automotive and electronics are rapidly adopting these algorithms for complex surface defect detection. As a result, the basis of competition is migrating from raw camera sensor specifications to the sophistication and adaptability of the underlying AI software model.
New regulations like the European Union's AI Act introduce risk-based classifications and transparency requirements for artificial intelligence systems. This regulation forces developers of vision systems, especially those used in critical infrastructure or medical diagnostics, to document data provenance and algorithmic decision-making. The medical imaging segment is most affected, now needing to build auditability and explainability features directly into their platforms to achieve compliance.
End-users are increasingly purchasing image processing capabilities through subscription-based Software-as-a-Service (SaaS) models. This model disrupts the traditional one-time capital expenditure on hardware, replacing it with recurring revenue streams that include continuous software updates and support. This transition is most visible in the logistics and warehousing sector, where providers offer "inspection-as-a-service" for package sorting and tracking.
Global Image Processing Systems Market Segmentation
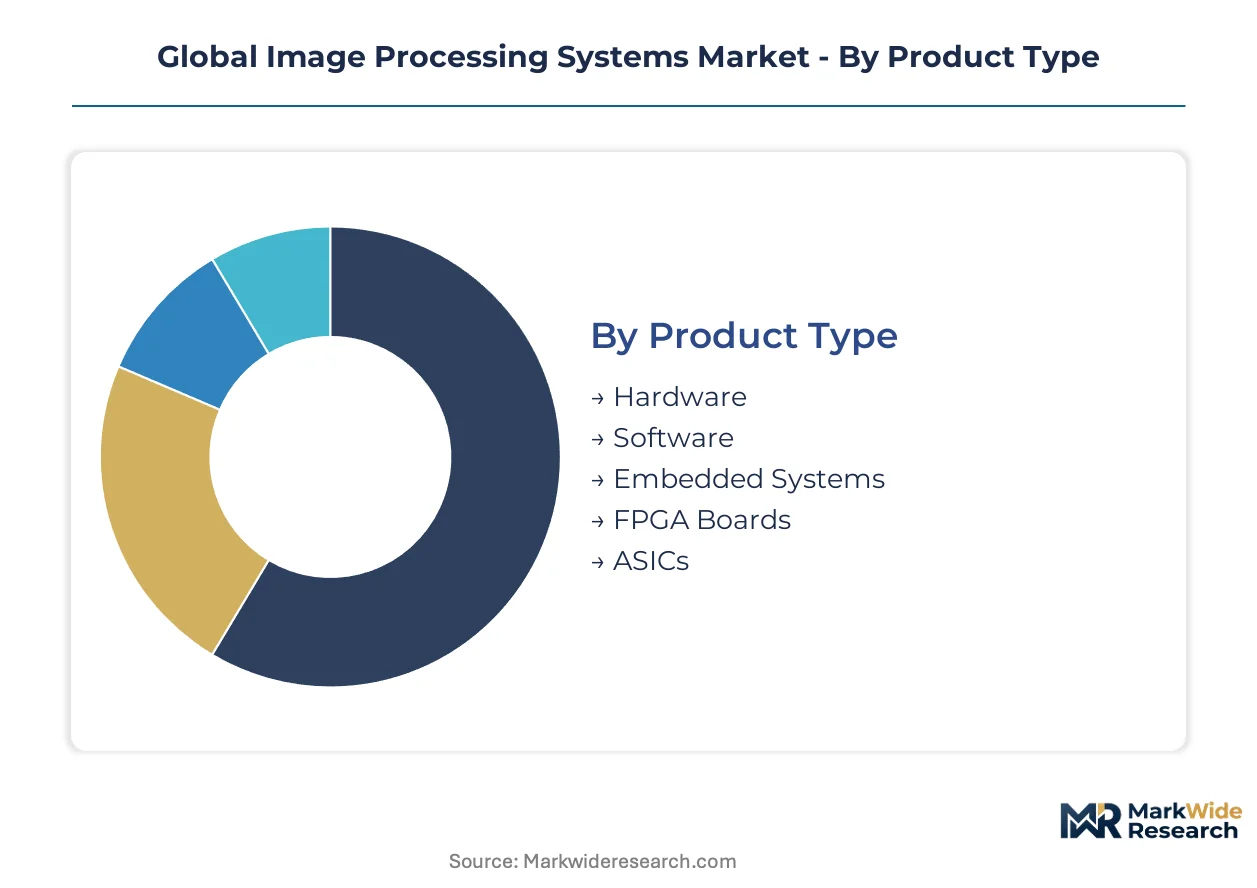
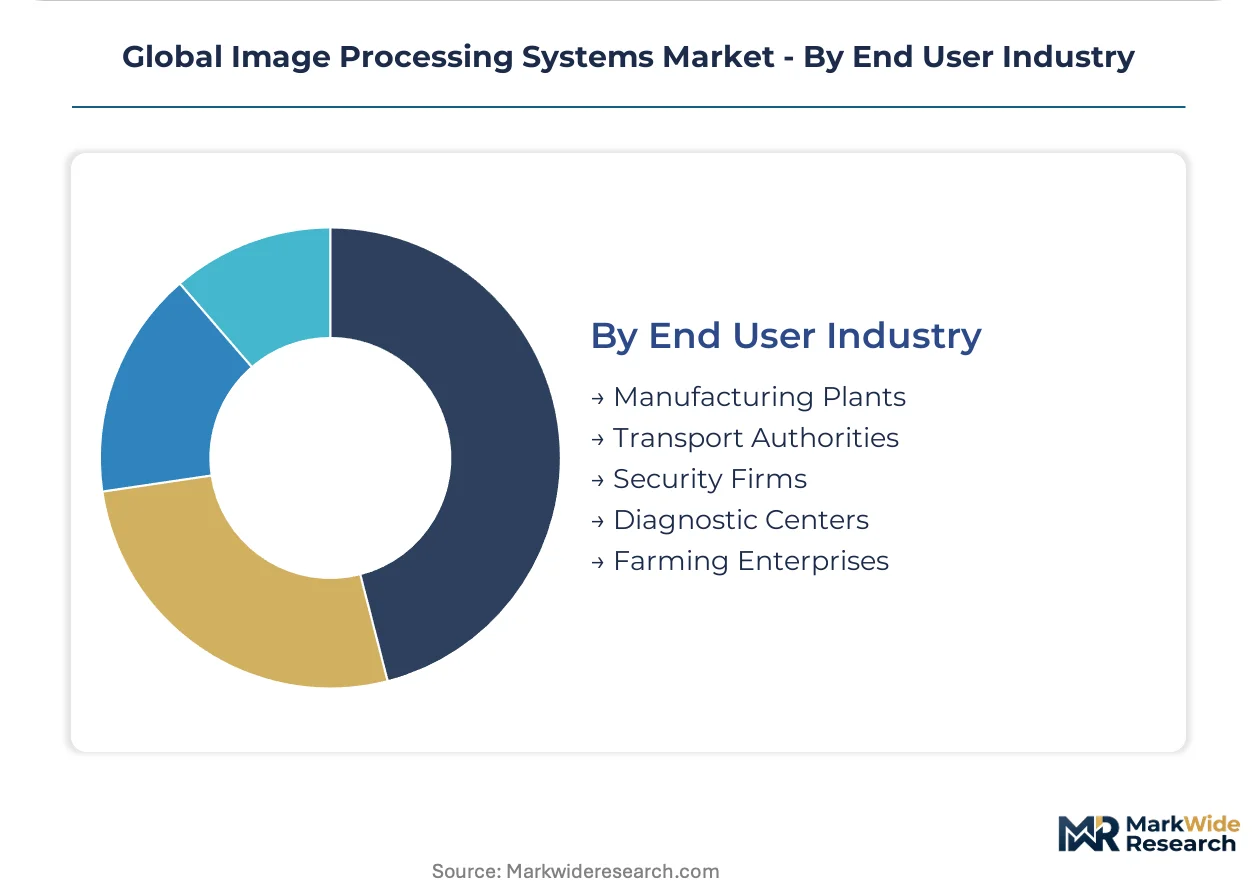
The Global Image Processing Systems Market is segmented across various dimensions, reflecting specialized industry requirements. This analysis clarifies where technological advancements and market investments are concentrating, highlighting distinct value propositions driving adoption in critical sectors.
Product Type:
Image processing systems are defined by their fundamental components, each supporting operational demands from data capture to algorithmic execution. Hardware and software interplay defines system capabilities.
- Hardware:These systems encompass cameras, lenses, lighting, and frame grabbers, forming the physical backbone for image acquisition. Demand for high-resolution CMOS sensors concentrates in manufacturing plants for quality inspection.
- Software:This segment includes image processing libraries, development environments, and application-specific algorithms, providing the intelligence layer for analysis. Demand concentrates in factory automation, leveraging deep software expertise.
- Embedded Systems:Integrated computing solutions combine processors, memory, and I/O for compact, dedicated image processing.
- FPGA Boards:Field-Programmable Gate Arrays offer reconfigurable hardware logic for custom, high-speed acceleration.
- ASICs:Application-Specific Integrated Circuits provide highly optimized, fixed-function processing for volume applications requiring efficiency.
The dominant share belongs to Hardware, while Software is closing the gap fastest as algorithmic performance becomes a primary differentiator.
Technology:
The technological foundations dictate analytical power and real-time performance across applications. Advancements in computational methods are expanding system capabilities significantly.
- Neural Networks:These deep learning algorithms provide advanced pattern recognition for complex image analysis, particularly for surface defect detection in automotive. Adoption accelerates due to superior performance.
- Edge Computing:This technology enables on-device processing and analysis, reducing latency for real-time applications like high-speed sorting. AI accelerators drive its integration on the factory floor.
- Machine Vision:Traditional machine vision relies on rule-based algorithms for measurement, gauging, and object detection in industrial environments.
- Digital Signal Processing:DSP techniques are fundamental for filtering, enhancement, and compression of visual data for analysis.
- Cloud Computing:Cloud platforms provide scalable storage and processing power for large datasets and complex AI model training.
Neural Networks and Edge Computing collectively lead the technological evolution, driving new possibilities for real-time, intelligent image analysis.
Application:
Image processing systems find utility across diverse applications, each presenting distinct challenges and requiring specialized analytical capabilities. These address critical needs from quality control to advanced diagnostics.
- Quality Inspection:This application involves automated defect detection, assembly verification, and component measurement in manufacturing. It remains the dominant revenue source, driven by industrial automation initiatives.
- Medical Imaging:This high-margin niche utilizes image processing for diagnostics, cellular analysis, and surgical guidance in healthcare. Growing requirements for high-precision diagnostics drive adoption.
- Traffic Management:Systems monitor vehicle flow, detect incidents, and enforce traffic laws using visual data.
- Facial Recognition:This application identifies or verifies individuals from digital images, primarily used in security and access control.
- Agricultural Monitoring:Image processing aids in crop health assessment, weed detection, and automated harvesting via robotic systems.
Quality Inspection maintains its leading position, while Medical Imaging shows significant expansion due to specialized requirements and high-value outcomes.
End User Industry:
Adoption of image processing systems varies significantly across end-user industries, reflecting their specific operational needs and regulatory environments. Each sector leverages systems to enhance productivity.
- Manufacturing Plants:These facilities integrate image processing for automated quality inspection, process control, and robotic guidance on production lines. China's national initiatives create sustained demand.
- Diagnostic Centers:Medical diagnostic centers deploy image processing systems for analyzing X-rays, MRIs, and microscopic images to aid disease detection. FDA requirements heavily influence system design.
- Transport Authorities:These entities utilize image processing for traffic monitoring, incident detection, and automated toll collection.
- Security Firms:Security companies deploy image processing for surveillance, access control, and threat detection.
- Farming Enterprises:Agricultural businesses use image processing in AgriTech for precision farming, crop health monitoring, and automated harvesting.
Manufacturing Plants represent the largest consumer base, with Diagnostic Centers demonstrating accelerating adoption due to advancements in medical technology.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global consumption of image processing systems varies significantly by region. China's demand concentrates on industrial automation and infrastructure upgrades, contrasting with the United States' emphasis on high-precision medical imaging applications. European adoption focuses on advanced manufacturing and regulatory compliance for specialized vision systems.
China
China's industrial automation initiatives drive significant demand for image processing systems, particularly in automated quality inspection. The country's GB standards for industrial equipment influence system design, ensuring interoperability across manufacturing lines. Production hubs like the Yangtze River Delta actively integrate these systems for advanced electronics and automotive assembly.
Germany
German manufacturing capacity for industrial automation fuels substantial demand for advanced vision systems, emphasizing precision and efficiency. The EU's CE marking under the Medical Device Regulation (MDR) imposes stringent validation standards for medical imaging components. Industrial clusters in Baden-Württemberg lead the integration of sophisticated image processing for automotive and machinery production.
United States
American demand for image processing systems spans both quality inspection in manufacturing and high-margin medical imaging. The FDA's stringent requirements for medical devices dictate system design and validation, ensuring diagnostic accuracy. The Boston-Cambridge life sciences hub actively develops specialized systems for pathology and radiology applications.
Japan
Japanese industries require high-precision sensors and integrated vision systems for complex inspection tasks, especially in electronics and automotive. JIS standards for industrial equipment guide the development of robust and reliable image processing solutions. The Tokyo-Yokohama industrial region focuses on advanced robotics and automated quality control leveraging these technologies.
Vietnam
Emerging manufacturing economies like Vietnam present significant volume growth potential for cost-effective vision systems, particularly in electronics assembly. Local industrial policies encourage foreign direct investment in high-tech manufacturing, boosting automation adoption. Industrial zones around Ho Chi Minh City are rapidly deploying image processing for quality control in export-oriented production.
Global Image Processing Systems Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another, creating a diverse competitive landscape for image processing systems. The market features a blend of specialized vision system providers and larger industrial automation conglomerates. Strategic archetypes include software-centric innovators, hardware component specialists, and integrated solution providers. Companies pursue strategic partnerships to expand their technological reach and diversify their product portfolios.
Specialized vision system providers such as Basler AG, a German AG, anchor the hardware segment with extensive camera portfolios and modular components, serving as foundational elements for diverse image acquisition needs. Cognex Corporation, a US-based entity, exemplifies software-centric innovation, leveraging deep expertise in factory automation applications and advanced pattern recognition algorithms. Keyence Corporation, a Japanese entity, occupies a position focused on high-precision sensors and integrated vision systems, catering to intricate inspection tasks that demand superior accuracy and reliability across various industrial settings.
| Leading Market Players |
|---|
| Basler AG |
| Cognex Corporation |
| Intel Corporation |
| CARL ZEISS Industrielle Messtechnik |
| Datalogic S.p.A |
| GÖPEL electronic GmbH |
| DELTA Electronics |
| Keyence Corporation |
| NVIDIA Corporation |
Cost & Logistics Intelligence
High-resolution CMOS sensor manufacturing, concentrated in East Asia, directly influences the cost structure and margin potential for image processing system integrators. This upstream concentration shapes the competitive landscape for hardware components, impacting downstream system pricing.
Pricing Analysis
Project-based contracts often characterize custom image processing system deployments, while subscription models gain traction for "inspection-as-a-service" offerings. Price differentiation stems from the customization level of algorithms and the certification requirements for regulated markets like medical imaging. Pricing pressure stems from the commoditization of basic hardware components in less-regulated industrial sectors. Small and medium-sized enterprises typically exhibit the highest price sensitivity for initial capital outlay.
Supply Chain Analysis
Extended payment terms often characterize procurement relationships between system integrators and specialized component suppliers. Geographic supply concentrates in Japan for high-precision sensors, China for electronics manufacturing, and Germany for industrial automation components. Key dependencies include high-resolution CMOS sensors, specialized AI accelerators, and robust optical components. Single-source vulnerability for advanced AI chips represents a structural supply chain risk. Distribution runs through direct sales channels for enterprise clients and specialized system integrators for complex industrial projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a significant service-attach opportunity, with recurring software updates and maintenance contracts expanding faster than initial hardware sales.
For Market Incumbents: Harden core software expertise in neural network development and regulatory compliance. This strategy defends against commoditization of generic camera hardware and mitigates risks from evolving AI regulations like the EU AI Act. Invest in advanced R&D for explainable AI features to meet stringent validation standards in high-value segments.
For New Entrants and Emerging Players: Southeast Asian manufacturing hubs represent a geographic underpenetration for cost-effective vision systems. Target these regions with scalable, subscription-based "inspection-as-a-service" models, focusing on electronics and automotive assembly. Develop specialized software solutions for niche applications like AgriTech, leveraging drone-based and robotic systems.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialized software firms possessing robust intellectual property in deep learning algorithms. Long-term viability hinges on companies able to navigate complex regulatory frameworks and provide verifiable AI system performance. Acquire niche providers with strong expertise in medical imaging diagnostics or edge AI integration. The signal to watch is the adoption rate of explainable AI features in critical infrastructure applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Develop Explainable AI Platforms | This initiative enables compliance with emerging regulations like the EU AI Act for critical applications. |
| Form Strategic Partnerships with Edge AI Hardware Manufacturers | These collaborations accelerate on-device processing capabilities, reducing latency for real-time applications. |
| Expand "Inspection-as-a-Service" Offerings | This move converts one-time capital expenditures into predictable recurring revenue streams for end-users. |
| Acquire Specialized Software Developers in Medical Imaging | This strategy strengthens high-margin diagnostic capabilities and deepens regulatory expertise for specialized systems. |
| Target Underpenetrated Manufacturing Hubs in Southeast Asia | This expansion captures significant volume growth potential in electronics and automotive assembly sectors. |
Research Approach
Initial hypotheses were tested against primary input from R&D directors, plant managers, regulatory compliance officers, and system integrators, then refined through iterative analysis. This approach combined in-depth primary interviews with rigorous secondary validation from industry association reports, patent databases, government industrial policy documents, and academic research. Bottom-up and top-down triangulation ensured data consistency and comprehensive market sizing.
Demand-supply balance formed the core analytical framework across the projection horizon. The study modeled segmentation dimensions including product type, technology, application, end-user industry, and regional regulatory frameworks. Compound annual growth rates were derived from historical data analysis and future growth drivers. Key forecast inputs included industrial automation investment trends and AI hardware adoption rates.
Practitioners should monitor the pace of AI regulatory development and shifts in global trade policies for early signals. Forecasts reflect assumptions documented through this process. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Holographic Imaging Market
Imaging
Global in Ceiling Camera Market
Imaging
IP Camera Market
Imaging
Digital Microscope Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Acoustic Microscopy Market
Imaging
Digital Image Processing Market
Imaging
Stacked CMOS Image Sensor Market
Imaging
X-Ray Photoelectron Spectroscopy Market
Imaging
Global Ingaas Camera Market
Imaging
Wearable IP Camera Market
Imaging
Uncooled Infrared Imaging Market
Imaging
Global Microscopy Market
Imaging
TDI Camera Market
Imaging
Thermal Imaging Systems Market
Imaging
Automotive 3D Imaging Market