
 Multimodal Imaging Market | 2026-2036
Multimodal Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Multimodal Imaging Market Intelligence
Modular system architecture is recalibrating buyer choice across the multimodal imaging landscape. Siemens Healthineers leverages integrated platform designs that combine PET-CT and MRI-PET workflows within unified software environments. GE Healthcare anchors its position through deep vertical integration into detector manufacturing and radiopharmaceutical supply chains. Canon Medical Systems differentiates via high-field MRI compatibility layered with advanced CT reconstruction algorithms.
Multimodal imaging fuses two or more imaging modalities into synchronized acquisition systems, typically achieving sub-millimeter spatial registration through shared patient tables and hardware clocks that time-stamp data streams to within nanoseconds; its primary purpose is to overlay functional metabolic data onto high-resolution anatomical maps for precise lesion localization. PET-CT retains the largest installed base and generates the steadiest service revenue streams, while MRI-PET captures the fastest expansion as neuro-oncology protocols demand simultaneous soft-tissue contrast and metabolic tracer visualization. Integrated platforms command premium pricing relative to standalone systems due to software harmonization requirements and specialized service contracts.
FDA 510(k) premarket notification and EU MDR conformity assessment govern device clearance timelines, with the latter extending certification cycles through expanded clinical evidence requirements. ISO 13485 quality management systems and IEC 60601-1-3rd edition electrical safety standards form baseline procurement filters for hospital capital committees. Stakeholders must monitor evolving radiopharmaceutical tracer availability and reimbursement coding convergence between anatomical and functional imaging procedures.
Market Dynamics
Modular detector arrays and shared software environments are compressing upgrade cycles as hospitals seek to extend PET-CT platforms into MRI-PET configurations without full system replacement.
Growth Catalysts
- Oncology Protocol Expansion:Academic medical centers in the United States, Germany, and Japan are standardizing simultaneous anatomical-metabolic imaging for tumor staging and treatment response monitoring.
- EU MDR Harmonization:Convergence of conformity assessment procedures across European member states is reducing duplicate certification burdens for multimodal system manufacturers.
- Silicon Photomultiplier Transition:Solid-state detector technology is replacing photomultiplier tubes, enabling faster coincidence timing and improved signal-to-noise ratios in integrated PET-MRI configurations.
Market Restraints
- Radiopharmaceutical Supply Concentration:Cyclotron production of fluorodeoxyglucose and gallium-based tracers clusters at regional hub facilities, creating distribution bottlenecks for rural hospital networks.
- Facility Infrastructure Requirements:MRI-PET installations demand reinforced flooring, cryogen venting systems, and magnetic shielding that retrofit poorly into older radiology suites.
- Reimbursement Coding Fragmentation:Separate billing codes for PET and CT components in certain jurisdictions complicate revenue cycle management for integrated procedure claims.
Strategic Opportunities
- Neurodegenerative Imaging Protocols:Amyloid and tau tracer visualization for Alzheimer's assessment is opening dedicated neurology PET-MRI service lines at memory disorder centers.
- India Diagnostic Infrastructure:Greenfield hospital construction under the country's PLI scheme for medical devices is creating first-mover advantages for turnkey multimodal installation contracts.
- Artificial Intelligence Reconstruction:Deep learning algorithms for low-dose PET image enhancement are integrating with vendor-agnostic PACS architectures, enabling software-only upgrades.
Industry Challenges
- Cross-Modal Physics Expertise:Service engineers must simultaneously troubleshoot positron detection electronics and superconducting magnet cryogenics, extending training timelines.
- Legacy System Interoperability:DICOM conformance variations between installed PET-CT fleets and new MRI-PET platforms complicate unified radiology workflow orchestration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multimodal Imaging Market |
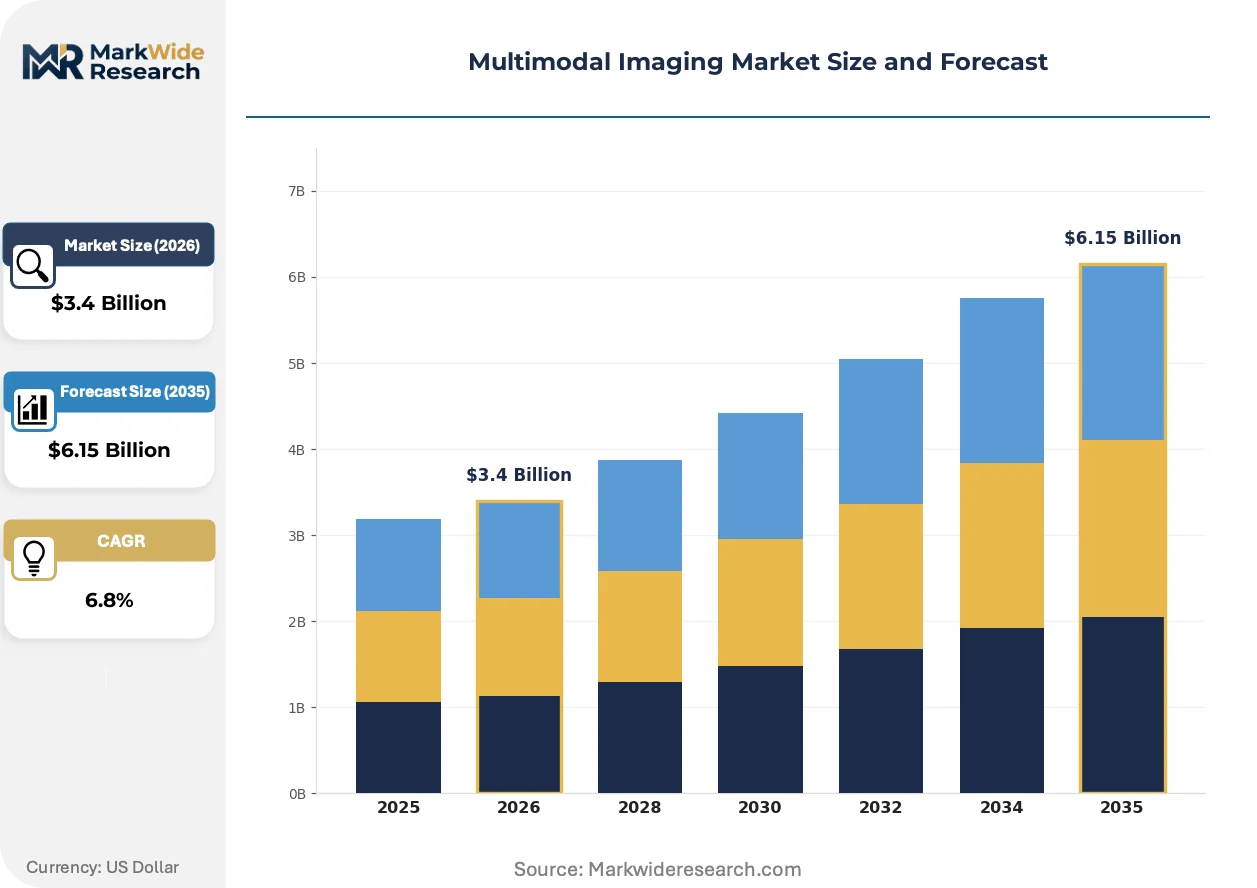
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $6.15 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: MRI-PET, CT-SPECT, Ultrasound-Optical, MRI-Ultrasound, PET-CT Application: Oncology Diagnosis, Cardiovascular Imaging, Neurological Assessment, Musculoskeletal Imaging, Gastrointestinal Evaluation End User: Diagnostic Centers, Research Laboratories, Cancer Institutes, Animal Clinics, Dental Practices Deployment: Standalone Systems, Integrated Platforms, Portable Units, Cloud-Based Solutions, Hybrid Installations |
| Companies Covered | Canon Medical Systems Corporation, Neusoft Medical Systems Co., Ltd., GE Healthcare, Fujifilm Holdings Corporation, Mediso Ltd., Koninklijke Philips N.V., United Imaging Healthcare Co., Ltd., Topcon Corporation, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multimodal Imaging Market Strategic Shifts & Innovations
Detector material advances and regulatory pathway convergence are compressing product development timelines while expanding the addressable hospital base for premium integrated systems.
Silicon photomultiplier arrays are integrating lutetium-based scintillator crystals to achieve sub-300 picosecond coincidence timing resolution. Siemens Healthineers and GE Healthcare are field-testing these detector stacks in next-generation PET-MRI gantries for cardiac viability imaging. The technology is integrating time-of-flight performance improvements with reduced magnetic field susceptibility, enabling simultaneous acquisition without interference artifacts.
EU MDR Article 10 clinical evaluation requirements are extending technical documentation timelines for Class IIb imaging devices. Manufacturers must now submit post-market surveillance plans and periodic safety update reports that demonstrate sustained clinical benefit. European notified bodies are prioritizing multimodal system audits, forcing vendors to reallocate regulatory affairs resources from FDA 510(k) preparation.
Hospital capital committees are unbundling service contracts from equipment procurement, negotiating multi-vendor maintenance agreements through third-party clinical engineering firms. Radiology departments in the United States are leading this shift, driven by pressure to reduce per-scan operational expenditures. Independent service organizations are capturing preventive maintenance volumes previously held by original equipment manufacturers.
Multimodal Imaging Market Segmentation
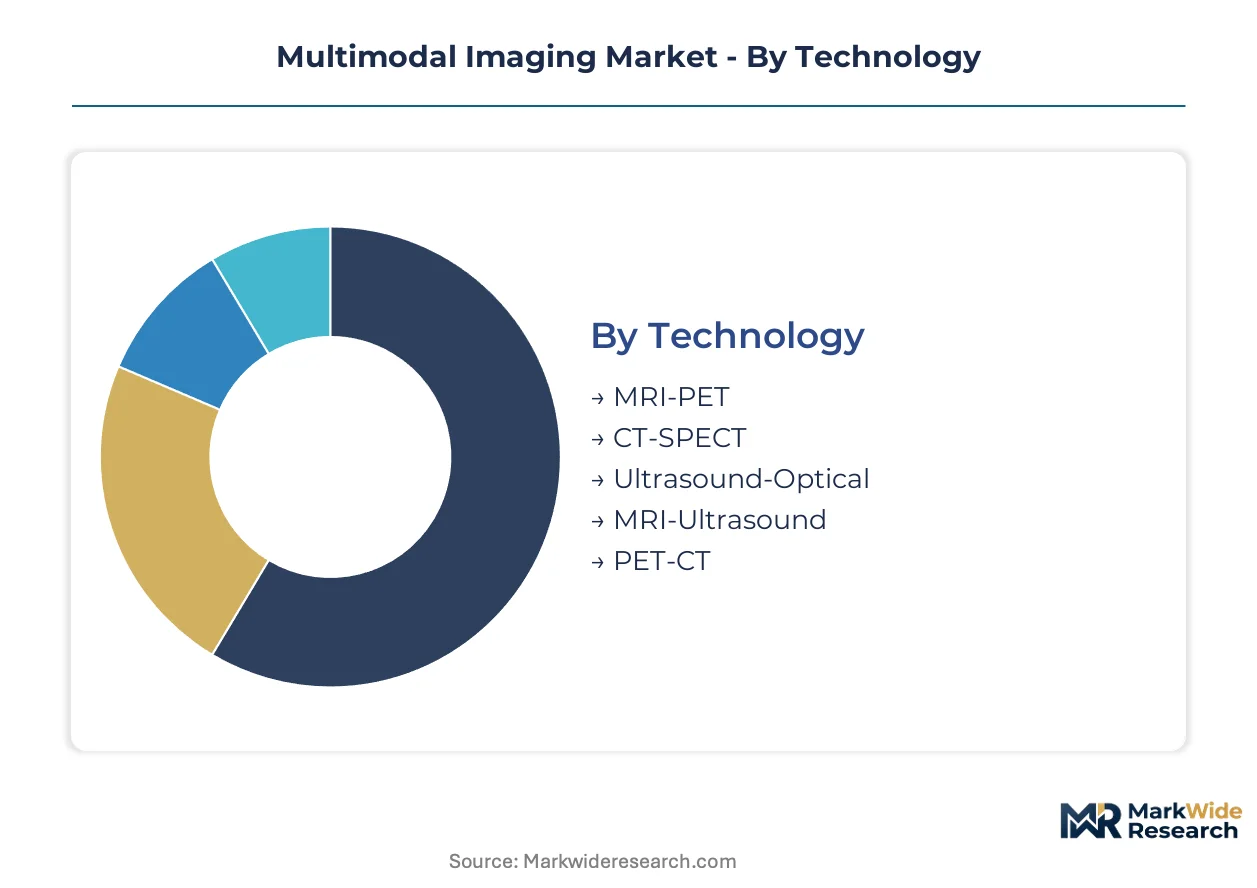
Multimodal imaging segmentation reveals distinct procurement patterns across integration depths. Standalone systems dominate installed base economics while integrated platforms capture new capital allocations. Understanding these technology-application-end user intersections determines vendor go-to-market priorities and service contract structuring.
Technology:
Integration depth separates established hybrid modalities from emerging fusion architectures in current procurement cycles.
- PET-CT:Lutetium oxyorthosilicate crystal arrays paired with time-of-flight electronics achieve sub-400 picosecond coincidence timing. United States academic medical centers anchor replacement demand as Medicare reimbursement codes stabilize for oncologic staging protocols.
- MRI-PET:Simultaneous acquisition through avalanche photodiode or silicon photomultiplier detectors operating inside high-field magnetic environments enables true functional-anatomical registration. Germany's university hospitals drive fastest adoption as EU MDR certification pathways mature for superconducting hybrid gantries.
- CT-SPECT:Dual-detector gamma camera integration with helical CT supports myocardial perfusion quantification.
- MRI-Ultrasound:Real-time electromagnetic tracking of transducer position enables fused interventional guidance.
- Ultrasound-Optical:Photoacoustic layers add hemoglobin oxygen saturation mapping to conventional B-mode imaging.
PET-CT leads volumes today; MRI-PET is gaining share fastest.
Application:
Clinical utility depth determines pricing power and service contract duration across diagnostic specialties.
- Oncology Diagnosis:Tumor staging, treatment response monitoring, and radiotherapy planning leverage combined metabolic and anatomical data. Japan's National Cancer Center network standardizes FDG-PET-CT for lymphoma protocols, with reimbursement codes covering 90% of insured populations.
- Neurological Assessment:Amyloid and tau tracer imaging for Alzheimer's disease progression tracking demands simultaneous MRI soft-tissue contrast. United States memory disorder centers in Boston and San Francisco anchor specialized PET-MRI service line development.
- Cardiovascular Imaging:Myocardial viability and perfusion assessment combines coronary CT angiography with metabolic tracer distribution.
- Musculoskeletal Imaging:MRI-ultrasound fusion guides tendon and ligament interventions with real-time needle tracking.
- Gastrointestinal Evaluation:PET-CT localizes occult primary tumors in metastatic presentations of unknown origin.
Oncology Diagnosis commands premium pricing; Neurological Assessment shows steepest expansion trajectory.
End User:
Capital intensity and technical staffing requirements stratify addressable customer base by integration complexity tolerance.
- Cancer Institutes:Dedicated oncology centers maintain full-time nuclear medicine physicists and radiopharmacists for tracer production oversight. United States NCI-designated comprehensive cancer centers in Houston and New York operate highest PET-MRI scan volumes per machine.
- Diagnostic Centers:Multi-site imaging networks achieve utilization efficiency through centralized scheduling and shared technologist pools. Germany's outpatient radiology chains negotiate fleet-wide service agreements covering mixed PET-CT and MRI-PET installed bases.
- Research Laboratories:Preclinical imaging suites demand sub-millimeter resolution for small-animal pharmacology studies.
- Animal Clinics:Veterinary oncology practices adopt refurbished human systems for companion animal cancer staging.
- Dental Practices:Cone-beam CT integration with optical scanning supports implant planning workflows.
Diagnostic Centers dominate unit shipments; Cancer Institutes drive revenue per installation.
Deployment:
Infrastructure commitment level and upgrade flexibility define procurement choice architecture.
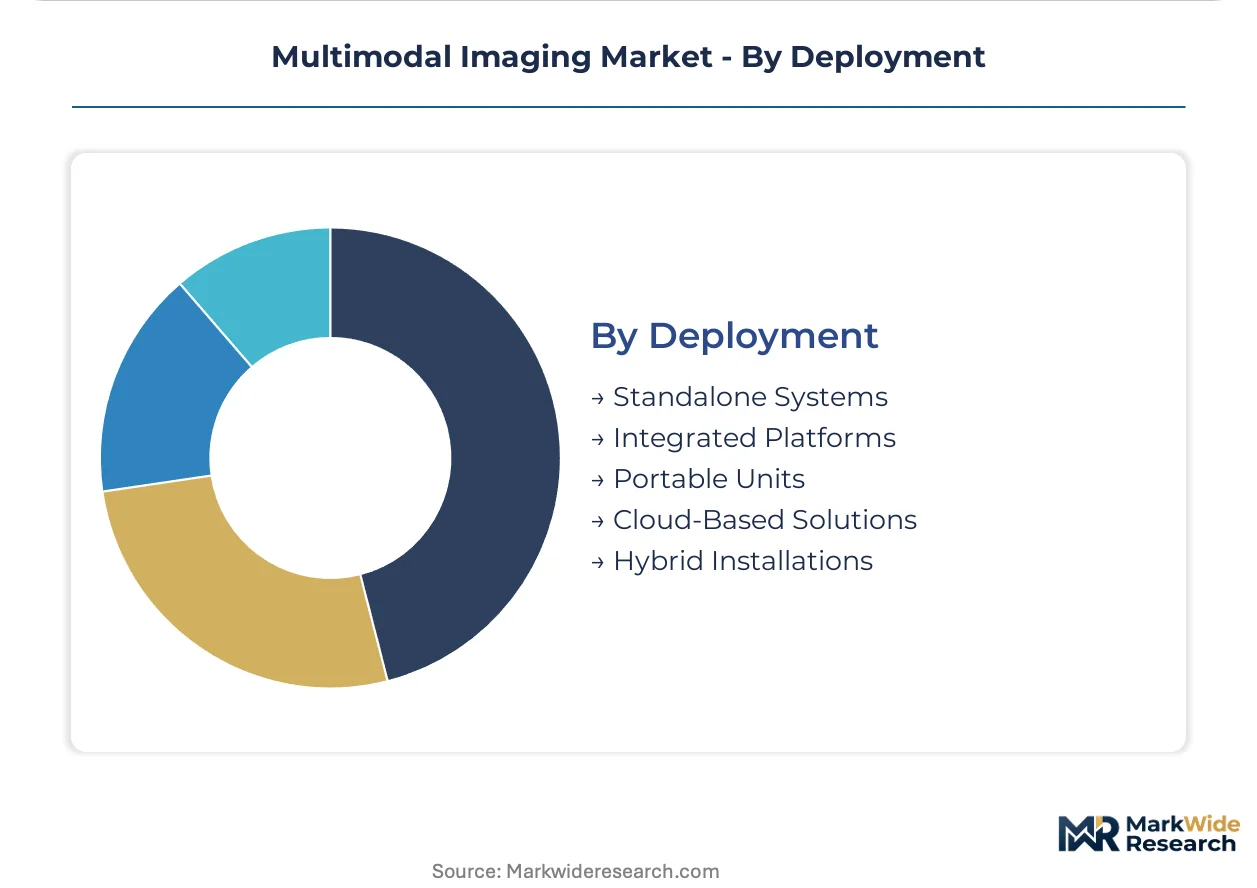
- Integrated Platforms:Single-vendor hardware and software environments minimize registration errors through shared patient tables and unified reconstruction pipelines. Japan's hospital construction boom under 2024 medical infrastructure grants favors turnkey integrated installations with 10-year service bundling.
- Standalone Systems:Separately housed modalities connected through software fusion allow phased capital deployment and vendor diversification. Rural United States hospitals preserve upgrade optionality through standalone PET and CT units with third-party fusion workstations.
- Hybrid Installations:Retrofitted detector arrays extend existing MRI or CT platforms into multimodal configurations.
- Portable Units:Mobile PET-CT and SPECT-CT trailers serve markets below fixed-installation population thresholds.
- Cloud-Based Solutions:Remote reconstruction and AI-enhanced image processing reduce on-premise computational requirements.
Integrated Platforms anchor new capital expenditure; Hybrid Installations expand fastest among budget-constrained providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Multimodal imaging technology first achieved commercial scale through PET-CT installations at university hospitals in the United States and Germany during the early 2000s. These early deployments established the clinical protocols and regulatory templates that subsequently diffused to Japan, China, and India.
United States
NCI-designated comprehensive cancer centers in Houston and New York operate the highest PET-MRI scan volumes per machine globally. FDA 510(k) premarket notification pathways govern device clearance timelines, with recent emphasis on software-as-medical-device components. Academic medical centers in Boston anchor specialized neurology service lines for amyloid tracer imaging.
Germany
University hospitals in Munich and Heidelberg drive fastest MRI-PET adoption as EU MDR certification pathways mature for superconducting hybrid gantries. The country's national medical device regulator enforces expanded clinical evidence requirements under Article 10 technical documentation rules. Outpatient radiology chains negotiate fleet-wide service agreements covering mixed installed bases.
Japan
The National Cancer Center network standardizes FDG-PET-CT for lymphoma protocols with reimbursement codes covering insured populations. METI medical infrastructure grants under 2024 hospital construction programs favor turnkey integrated installations. Tokyo metropolitan hospitals lead service line development for cardiovascular PET-MRI applications.
China
Domestic manufacturers capture share in provincial hospital procurement through NMPA Class III device registrations. The Yangtze River Delta cluster around Shanghai concentrates installed base growth for oncology staging applications. Local production of lutetium-based scintillator crystals reduces import dependency for detector array assembly.
India
Greenfield hospital construction under the PLI scheme for medical devices creates first-mover advantages for turnkey multimodal installation contracts. CDSCO medical device rules govern import licensing for PET-CT and MRI-PET systems. Diagnostic networks in Maharashtra and Karnataka achieve utilization efficiency through centralized scheduling and shared technologist pools.
Multimodal Imaging Market Key Industry Players
Premium-margin players sit above commodity-margin players across detector technology and software integration depth. The vendor base organizes into three tiers: integrated platform specialists commanding service contract premiums, component subsystem suppliers capturing detector and reconstruction module sales, and regional assembly houses fulfilling price-sensitive procurement. Strategic moves concentrate on silicon photomultiplier technology transitions and multi-vendor PACS interoperability certifications.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare occupy positions exemplifying integrated platform architecture, while Canon Medical Systems represents high-field MRI compatibility specialization. United Imaging Healthcare Co., Ltd. anchors the domestic Chinese supply base. Koninklijke Philips N.V. sits within the premium-tier imaging equipment segment alongside Fujifilm Holdings Corporation, which exemplifies diversification from traditional photographic materials into diagnostic systems.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Neusoft Medical Systems Co., Ltd. |
| GE Healthcare |
| Fujifilm Holdings Corporation |
| Mediso Ltd. |
| Koninklijke Philips N.V. |
| United Imaging Healthcare Co., Ltd. |
| Topcon Corporation |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Silicon photomultiplier detector transitions are simultaneously compressing manufacturing costs and concentrating production expertise among Japanese and German component specialists. This technology shift reconfigures procurement economics as hospitals negotiate system upgrades around detector replacement cycles rather than full gantry replacement.
Pricing Analysis
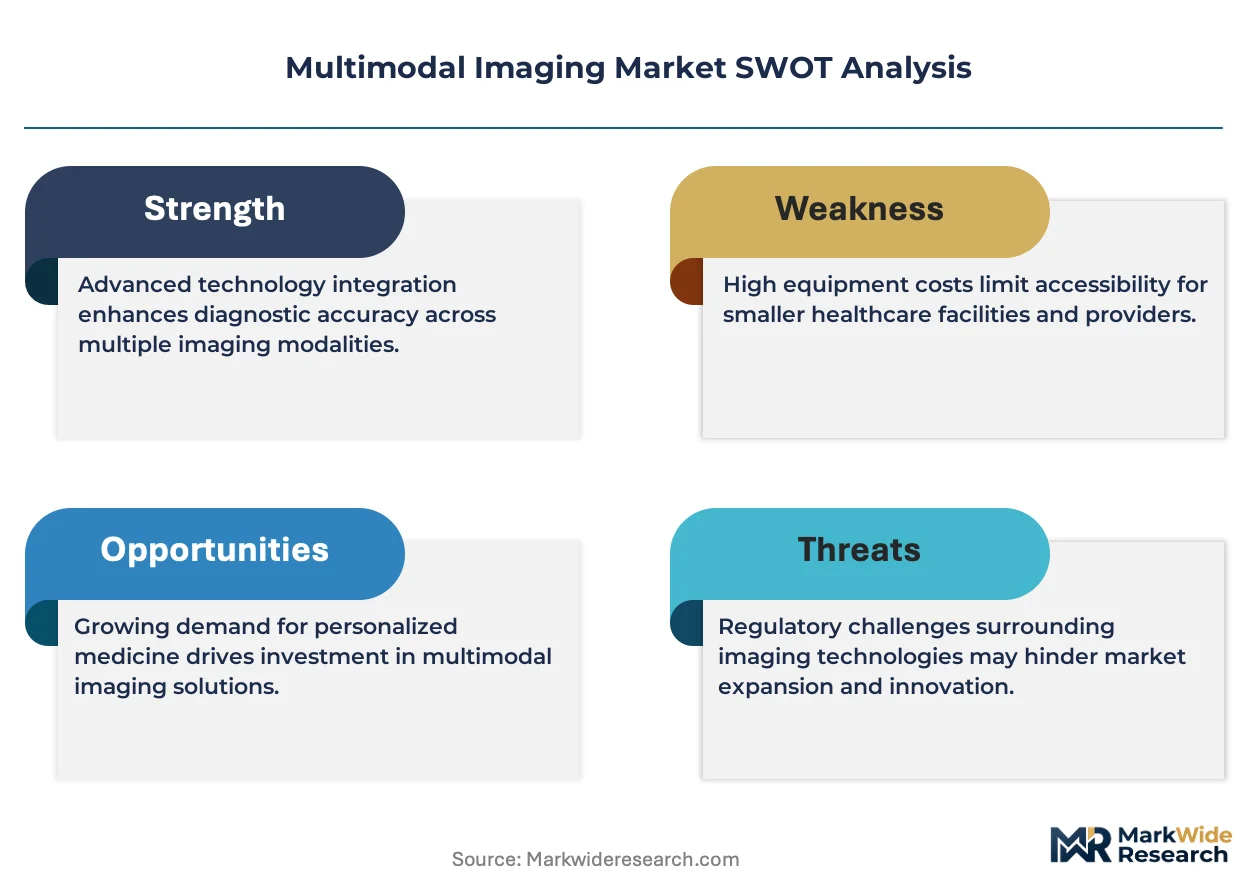
Three-tier pricing structure across premium, standard, and economy levels separates integrated platform vendors from modular subsystem suppliers and refurbished equipment dealers. Price differentiation hinges on FDA 510(k) clearance tier and bundled service contract duration, with premium tiers commanding extended warranty and radiopharmacist training inclusion. Cost compression in economy tiers is intensifying because independent service organizations capture preventive maintenance volumes previously held by original equipment manufacturers. Diagnostic centers exhibit highest price sensitivity due to per-scan operational expenditure pressures, while NCI-designated cancer centers prioritize performance specifications over acquisition cost.
Supply Chain Analysis
Specialized cryogenics engineers and nuclear medicine physicists concentrate in Germany, Japan, and the United States, creating workforce bottlenecks for superconducting magnet assembly and PET detector calibration. Manufacturing draws from lutetium-based scintillator crystal production in China, silicon photomultiplier fabrication in Japan, and superconducting wire supply from European specialists. Single-source vulnerability in fluorodeoxyglucose cyclotron production clusters at regional hub facilities. Distribution runs through original equipment manufacturer direct sales for integrated platforms and third-party clinical engineering firms for service contract unbundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU MDR Article 10 clinical evaluation requirements and FDA 510(k) software-as-medical-device emphasis simultaneously extend certification timelines and deepen competitive moats for cleared systems.
For Market Incumbents: Anticipate service contract unbundling by hospital capital committees through multi-vendor maintenance negotiations with third-party clinical engineering firms. Defensive positioning requires backward integration into silicon photomultiplier detector manufacturing to preserve margin structure against component suppliers. Priority investment in radiopharmaceutical tracer production partnerships addresses supply concentration vulnerability threatening installed base utilization rates. For New Entrants and Emerging Players: Rural United States hospitals represent the most penetrable buyer archetype as standalone PET and CT unit procurement preserves upgrade optionality against integrated platform premiums. White-space opportunity centers on AI-enhanced image reconstruction software integrating with vendor-agnostic PACS architectures, enabling software-only revenue capture without hardware certification burdens. Go-to-market execution through independent service organization partnerships bypasses incumbent direct sales infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among component subsystem suppliers capturing detector and reconstruction module sales outside integrated platform bundling. Long-term viability over the projection horizon favors silicon photomultiplier technology specialists with magnetic field compatibility expertise. Inflection signal to monitor: EU MDR notified body audit prioritization forcing vendor reallocation of regulatory affairs resources from FDA preparation.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photomultiplier Technology Transition | Solid-state detector replacement of photomultiplier tubes enables sub-300 picosecond coincidence timing in PET-MRI configurations. |
| EU MDR Certification Pathway Investment | Article 10 clinical evaluation requirements extend technical documentation timelines for Class IIb imaging devices. |
| Hospital System Partnership Development | Academic medical centers in Boston and Houston anchor specialized neurology and oncology service line standardization. |
| Software Companion Development | Deep learning algorithms for low-dose PET image enhancement integrate with vendor-agnostic PACS architectures. |
| Reimbursement Strategy Alignment | Medicare coding convergence between anatomical and functional imaging procedures stabilizes revenue cycle management. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with hospital purchasing committee members, biomedical engineers, nuclear medicine physicists, and GPO contracts managers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement coding records, and hospital procurement transaction logs. Bottom-up installed base modeling and top-down market sizing triangulated volume estimates.
Segment-weighting approaches distributed value across technology integration depth, clinical application specialty, and end-user capital intensity tiers throughout the forecast period. CAGRs derived from replacement cycle analysis, greenfield installation pipelines, and upgrade conversion rates. Industry-specific inputs incorporated silicon photomultiplier adoption curves and radiopharmaceutical tracer reimbursement stability.
Underlying measurement precision varies by segment; integrated platform revenue carries tighter precision than refurbished equipment resale due to manufacturer disclosure practices. Forecasts reflect assumptions around EU MDR certification pathway maturation and Medicare coding stabilization. Material deviation in silicon photomultiplier yield rates or cyclotron production consolidation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Automotive Imaging Market
Imaging
Asia-Pacific Hyperspectral Imaging Systems Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Medical X-Ray Detectors Market
Imaging
Thermal Imaging Camera Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
Automotive Compact Camera Module Market
Imaging
Europe Machine Vision Systems Market
Imaging
Wearable IP Camera Market
Imaging
Europe CT Market
Imaging
Handheld Backscatter X-Ray Devices Market
Imaging
SDI Camera Market
Imaging
Wide Field Imaging Devices Market
Imaging
Europe Hyperspectral Imaging Market
Imaging
Global Broadcast Cameras Market
Imaging
Hyperspectral Cameras Market