
 Japan Digital X-Ray Market | 2026-2036
Japan Digital X-Ray Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Digital X-Ray Market Foresight
Flat-panel detector resolution tiers above 100 micrometer pixel pitch is bifurcating procurement patterns across Japan's hospital procurement consortia. Canon Medical Systems Corporation leverages in-house semiconductor fabrication to sustain premium detector supply chains. Fujifilm Holdings anchors mid-tier hospital contracts through domestic service density. Siemens Healthineers competes on AI-integrated workflow software bundled with hardware leases.
Japan digital X-ray denotes radiographic imaging systems employing solid-state detectors—typically amorphous selenium or cesium iodide scintillator layers on thin-film transistor arrays—to convert X-ray photons directly into digital signals without analog film intermediates, achieving spatial resolution exceeding 3.5 line pairs per millimeter for skeletal and soft-tissue diagnosis. Portable X-Ray systems lead volume shipments as aging rural clinics prioritize bedside and emergency department flexibility over fixed-room installations. Direct Radiography technology captures the fastest expansion trajectory, displacing Computed Radiography cassette-based workflows in large hospital networks where throughput per technologist drives operational returns. Orthopedics applications concentrate margin pools due to weight-bearing extremity protocols requiring specialized detector geometries.
PMDA medical device quality management system ordinances and JIS Z 4751 radiation safety standards shape product registration timelines and detector calibration requirements for manufacturers seeking Japanese market access. METI industrial policy incentives for domestic production of critical healthcare components influence supplier localization decisions among multinational device firms. Stakeholders must monitor PMDA's evolving software-as-a-medical-device guidance for AI-enabled image reconstruction algorithms, as this classification pathway will determine competitive entry costs for algorithm-native vendors versus incumbent hardware-integrated platforms.
Market Dynamics
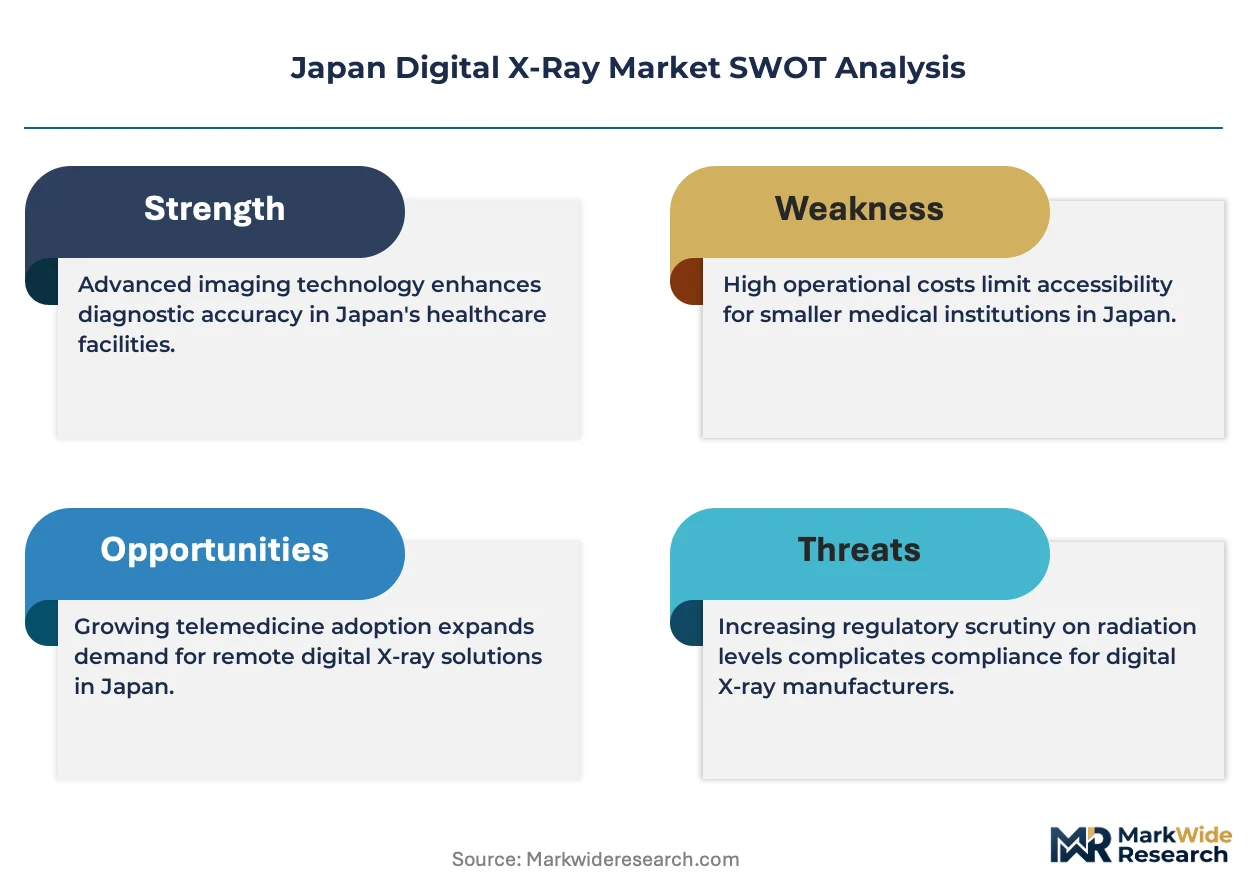
Japan's hospital procurement consortia are consolidating purchasing power around flat-panel detector resolution tiers, compressing vendor margins while elevating technical specifications as the primary competitive battleground.
Growth Catalysts
- Direct Radiography technology:Large hospital networks in Tokyo and Osaka are replacing Computed Radiography cassette workflows to maximize technologist throughput per shift.
- METI industrial policy incentives:Domestic production subsidies for critical healthcare components are accelerating localization decisions among multinational device suppliers.
- Rural clinic bedside imaging demand:Portable X-Ray systems are capturing volume leadership as aging prefectural facilities prioritize emergency department flexibility over fixed-room capital expenditure.
Market Restraints
- Amorphous selenium supply concentration:Detector substrate fabrication depends on a narrow base of semiconductor foundries, exposing procurement timelines to wafer allocation constraints.
- PMDA software-as-medical-device classification friction:Evolving guidance for AI-enabled image reconstruction creates registration uncertainty for algorithm-native vendors without hardware integration.
- Computed Radiography residual installed base:Cassette-based systems in smaller prefectural clinics delay full-network standardization and fragment service contract economics.
Strategic Opportunities
- AI-integrated workflow convergence:Bundled hardware-software leases are opening margin pools beyond equipment sales in metropolitan hospital networks.
- Orthopedic weight-bearing protocols:Specialized detector geometries for extremity imaging command premium pricing in sports medicine and trauma centers.
- PMDA accelerated approval pathways:Streamlined quality management system ordinances for domestically manufactured components reduce time-to-revenue for localized production investments.
Industry Challenges
- Detector calibration technician scarcity:JIS Z 4751 radiation safety compliance requires specialized training that outpaces workforce pipeline development in rural prefectures.
- Legacy film-based system integration:Hybrid workflows during transition periods create imaging protocol inconsistencies and double maintenance burdens.
- AI algorithm validation timelines:PMDA clinical evidence requirements for software-as-medical-device submissions extend development cycles for image reconstruction innovations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Digital X-Ray Market |
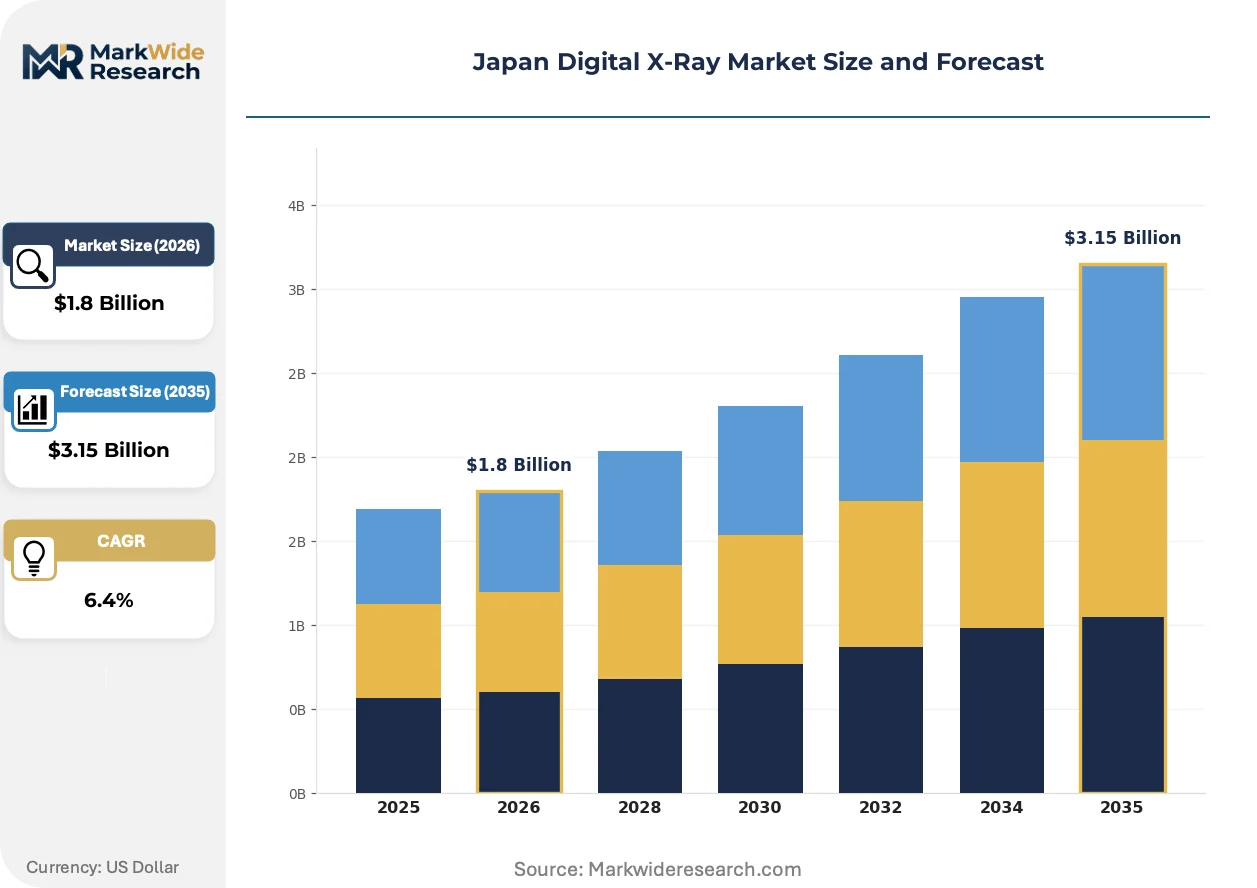
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
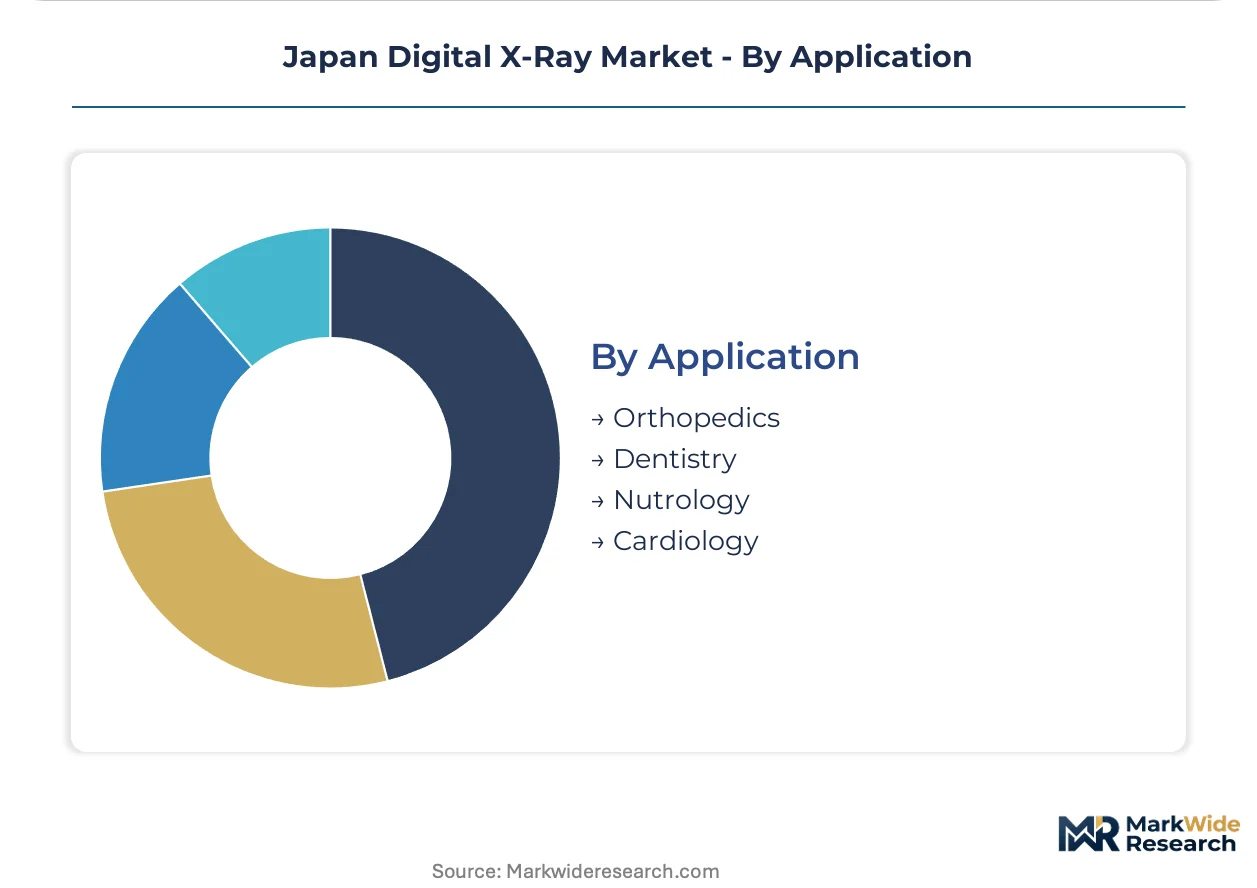
| Segmentation | Product Type: Portable X-Ray, Stationary X-Ray, Flat Panel Detectors, CR Systems End User: Hospitals, Diagnostic Centers, Research Laboratories, Outpatient Facilities Technology: Computed Radiography, Direct Radiography, Image Processing Software, Hybrid Systems Application: Orthopedics, Dentistry, Nutrology, Cardiology |
| Companies Covered | Canon Medical Systems Corporation, Siemens Healthineers, Fujifilm Holdings, Hamamatsu Photonics, Hitachi, Konica Minolta, GE Healthcare, Carestream Health, Shimadzu Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Digital X-Ray Market Shifts & Advancements
Artificial intelligence reconstruction algorithms and portable form factors are compressing traditional equipment replacement cycles while elevating software capabilities to parity with hardware specifications in procurement evaluations.
Cesium iodide scintillator layers on thin-film transistor arrays are decomposing the historical fixed-room installation model. Rural clinics in Hokkaido and Kyushu are adopting mobile units at twice the pace of metropolitan hospitals. This technology is decomposing capital allocation patterns by shifting investment toward bedside flexibility rather than dedicated radiography suites.
METI domestic production incentives are reshaping supplier facility location decisions. Manufacturers seeking Japanese market access must balance PMDA quality management system ordinances against tariff exposure on imported detector substrates. Osaka's diagnostic imaging cluster is capturing the majority of localization investments due to existing semiconductor fabrication infrastructure.
Service contract unbundling is fragmenting vendor revenue streams. Large hospital procurement consortia are separating hardware leases from maintenance agreements and software subscriptions. Tokyo's metropolitan hospital network is pioneering this trifurcated model, pressuring incumbents to defend recurring revenue through calibration expertise rather than captive equipment lock-in.
Japan Digital X-Ray Market Segmentation

Procurement consortia across Japan's hospital networks are fragmenting demand along resolution-performance tiers and care setting requirements. Understanding where margin pools concentrate within each dimension enables vendors to align R&D roadmaps with actual purchasing authority structures.
Product Type:
Flat-panel detector resolution specifications above 100 micrometer pixel pitch command premium pricing in metropolitan hospital procurement cycles.
- Portable X-Ray:Mobile units with cesium iodide scintillator layers on thin-film transistor arrays enable bedside imaging in aging rural prefectural clinics. Hokkaido and Kyushu facilities prioritize emergency department flexibility over fixed-room capital expenditure, driving volume leadership in this category.
- Stationary X-Ray:Fixed-room installations with amorphous selenium direct-conversion detectors achieve spatial resolution exceeding 3.5 line pairs per millimeter for skeletal diagnosis. Tokyo's metropolitan hospital network and Osaka's diagnostic imaging cluster concentrate demand here, though replacement cycles are lengthening as software capabilities substitute for hardware refresh.
- Flat Panel Detectors:Solid-state detector modules serve as upgrade components for existing radiography infrastructure.
- CR Systems:Cassette-based computed radiography workflows persist in smaller prefectural clinics, delaying full-network standardization.
The dominant share belongs to Portable X-Ray, while Stationary X-Ray is closing the gap fastest through AI-integrated workflow bundles.
End User:
Purchasing authority concentrates in hospital procurement consortia that aggregate radiography fleet decisions across multi-site networks.
- Hospitals:Large hospital networks in Tokyo and Osaka are replacing aging film-based systems with direct radiography technology to maximize technologist throughput per shift. METI domestic production incentives accelerate localization decisions among suppliers targeting these high-volume accounts.
- Diagnostic Centers:Specialized imaging facilities in Japan's urban corridors handle outsourced radiography referrals from smaller clinics. These centers prioritize detector calibration reliability and JIS Z 4751 radiation safety compliance to maintain accreditation for insurance reimbursement.
- Research Laboratories:Academic medical centers drive early adoption of AI-enabled image reconstruction algorithms.
- Outpatient Facilities:Ambulatory care sites favor portable units for point-of-service diagnostics.
Hospitals retain the largest procurement volume, though Diagnostic Centers are expanding their share through consolidation of rural clinic referrals.
Technology:
PMDA software-as-medical-device classification pathways are redistributing competitive advantage between hardware-integrated and algorithm-native vendors.
- Direct Radiography:Amorphous selenium or cesium iodide scintillator layers on thin-film transistor arrays convert X-ray photons directly into digital signals without analog intermediates. Large hospital networks are displacing cassette-based workflows to capture operational returns from higher technologist throughput.
- Computed Radiography:Photostimulable phosphor plate systems persist in budget-constrained prefectural facilities where capital replacement cycles lag metropolitan standards.
- Image Processing Software:AI-enabled reconstruction algorithms face evolving PMDA guidance that extends validation timelines for standalone submissions.
- Hybrid Systems:Transitional architectures bridge legacy cassette workflows with digital detector interfaces.
Direct Radiography holds the installed base majority, while Image Processing Software is climbing the fastest as procurement evaluations elevate software capabilities to parity with hardware specifications.
Application:
Specialized detector geometries for weight-bearing protocols create defensible margin pools in trauma and sports medicine settings.
- Orthopedics:Weight-bearing extremity protocols require customized detector geometries that command premium pricing in sports medicine centers and trauma facilities. These specialized configurations resist commoditization pressure from standard radiography procurement consortia.
- Dentistry:Intraoral and panoramic digital systems serve Japan's aging demographic with high-frequency dental imaging needs.
- Nutrology:Gastrointestinal fluoroscopy applications demand real-time digital acquisition capabilities.
- Cardiology:Cardiac catheterization suites integrate digital angiography with hemodynamic monitoring systems.
Orthopedics captures the highest margin concentration, while Dentistry is gaining share fastest through point-of-care installation in dental clinic chains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detector substrate fabrication concentrates in a narrow corridor of semiconductor foundries, exposing procurement timelines to wafer allocation constraints while METI incentives accelerate facility localization decisions.
Kanto/Tokyo
Tokyo's metropolitan hospital network drives premium-tier procurement for fixed-room installations with direct-conversion detectors. PMDA quality management system ordinances streamline certification timelines for domestically manufactured components. The Kanto corridor anchors the largest concentration of radiography fleet replacement contracts.
Kansai/Osaka
Osaka's diagnostic imaging cluster captures localization investments from multinational suppliers seeking proximity to existing semiconductor fabrication infrastructure. METI industrial policy incentives for domestic production of critical healthcare components influence facility siting decisions. The region concentrates mid-tier hospital contracts through service density advantages.
Chubu/Nagoya
Nagoya's manufacturing base supports component supply chains for portable X-ray system assembly. JIS Z 4751 radiation safety standards shape detector calibration requirements for equipment serving central Japan's aging rural clinics. The region bridges metropolitan demand with prefectural distribution networks.
Kyushu
Kyushu's aging prefectural facilities prioritize bedside imaging flexibility over fixed-room capital expenditure, driving portable system adoption at twice the metropolitan pace. PMDA device approval pathways accommodate emergency department deployment requirements. Fukuoka's medical device logistics hub facilitates rural service coverage.
Hokkaido
Hokkaido's dispersed rural clinic network depends on mobile radiography units with cesium iodide scintillator layers for point-of-service diagnostics. Detector calibration technician scarcity under JIS Z 4751 compliance requirements complicates maintenance coverage across remote prefectures. Sapporo's regional hospital network coordinates fleet procurement for satellite facilities.
Japan Digital X-Ray Market Competitive Landscape
Concentration sits with diversified medical imaging conglomerates and specialized detector fabricators. Three archetypes define competitive positioning: integrated hardware-software platforms, component-specialist suppliers, and multinational imaging system vendors. M&A activity targets AI-enabled workflow capabilities, while capacity expansion focuses on domestic detector substrate production.
Among Japan-based diversified manufacturers, Canon Medical Systems Corporation, Fujifilm Holdings, and Shimadzu Corporation exemplify the integrated platform archetype. These companies occupy positions spanning semiconductor fabrication through hospital service contracts. Siemens Healthineers and GE Healthcare represent multinational vendors competing through bundled hardware-software lease structures. Konica Minolta and Carestream Health sit within the mid-tier specialist segment.
| Leading Market Players |
|---|
| Canon Medical Systems Corporation |
| Siemens Healthineers |
| Fujifilm Holdings |
| Hamamatsu Photonics |
| Hitachi |
| Konica Minolta |
| GE Healthcare |
| Carestream Health |
| Shimadzu Corporation |
| Others |
Supply & Pricing Matrix
Hardware-software lease bundles lock in multi-year service revenue streams for Japan's hospital procurement consortia while capping upfront capital exposure. This contract structure secures detector substrate allocation priority from semiconductor foundries and stabilizes calibration technician deployment across metropolitan and rural prefectures alike.
Pricing Analysis
PMDA software-as-medical-device guidance dictates the pricing tier structure across Japan's digital X-ray procurement landscape. Three-tier pricing structure across premium, standard, and economy levels separates AI-integrated workflow bundles from standalone hardware and legacy Computed Radiography systems. Cost compression in the mid-tier is intensifying because Fujifilm Holdings and Canon Medical Systems Corporation are competing on domestic service density rather than detector specifications alone. Prefectural clinics in Hokkaido and Kyushu exhibit the highest price sensitivity due to constrained capital budgets, while Tokyo's metropolitan hospital network prioritizes throughput optimization over unit economics.
Supply Chain Analysis
Japan and South Korea anchor amorphous selenium wafer fabrication and cesium iodide scintillator crystal growth for detector substrate production. Supply draws from specialized semiconductor foundries in Osaka's diagnostic imaging cluster and thin-film transistor array manufacturers in the Kanto corridor. Single-source vulnerability concentrates in amorphous selenium deposition equipment, where two Japanese suppliers control global capacity. Distribution runs through hospital procurement consortia that aggregate fleet decisions across multi-site networks, compressing vendor margins while securing volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's digital X-ray market rewards vendors who capture recurring revenue through calibration expertise and AI software subscriptions, layers expanding faster than hardware replacement cycles. Service contract unbundling in Tokyo's metropolitan hospital network signals where margin pools are migrating.
For Market Incumbents: Compound defensive positioning by deepening captive production of amorphous selenium detector substrates under METI domestic production incentives, and accelerate PMDA quality management system certification for AI-enabled image reconstruction algorithms to preempt algorithm-native entrants. Threat substitution from standalone software vendors without hardware integration demands faster regulatory lock-in. For New Entrants and Emerging Players: PMDA accelerated approval pathways for domestically manufactured components offer the fastest route to procurement eligibility. Target portable X-Ray deployments in Kyushu and Hokkaido prefectural clinics where bedside imaging demand outpaces incumbent service coverage. Go-to-market through regional hospital network fleet procurement coordination rather than direct clinic sales. For Investors and Strategic Acquirers: Component-specialist detector fabricators with JIS Z 4751 calibration technician networks represent the most defensible acquisition profile. Long-term viability hinges on software-as-medical-device revenue streams displacing hardware lease economics. Signal to monitor: PMDA guidance finalization for AI algorithm classification timelines, which will determine capital requirements for competitive entry.| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Quality Management System Certification | Accelerates device approval timelines for domestic detector substrate production under METI incentives. |
| AI-Integrated Workflow Development | Bundles image reconstruction algorithms with hardware leases to capture recurring software subscription revenue. |
| Portable System Manufacturing Scale-Up | Addresses Hokkaido and Kyushu rural clinic demand for bedside imaging flexibility over fixed-room capital. |
| Calibration Technician Training Pipeline | Resolves JIS Z 4751 compliance scarcity that fragments service contract economics in remote prefectures. |
| Orthopedic Detector Geometry Specialization | Commands premium pricing in sports medicine centers through weight-bearing extremity protocol customization. |
Research Methodology
Cross-validation between hospital procurement committee interviews and PMDA device registration databases anchors the qualitative findings in this study. Primary fieldwork engaged radiology department heads, biomedical engineers, GPO contracts managers, and METI industrial policy officials across Tokyo, Osaka, and Fukuoka. Secondary sources incorporated hospital procurement databases, JIS Z 4751 compliance records, and METI domestic production incentive filings. Bottom-up shipment estimates triangulated against top-down healthcare capital expenditure surveys.
Sensitivity analysis around detector substrate allocation constraints and PMDA software classification timelines shapes the forecast framework. Segmentation dimensions span product type, end user, technology, and application, with orthopedics and portable systems modeled as distinct growth vectors. CAGRs derive from replacement cycle analysis of aging Computed Radiography installed bases and technologist throughput optimization targets. Forecast inputs include semiconductor foundry capacity expansion under METI incentives and rural clinic bedside imaging adoption curves.
Decision-makers should treat outputs as directional under assumptions of stable PMDA regulatory trajectories and continued METI domestic production support; material deviation in AI software classification timelines or amorphous selenium supply disruptions would warrant model refresh. Recalibration cycles align with material shifts in hospital procurement consortia consolidation patterns and detector resolution tier migration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Uncooled Infrared Camera Market
Imaging
Micro-Magnetic Resonance Imaging Market
Imaging
Silent Scan Technology Market
Imaging
Hyperspectral Cameras Market
Imaging
Ingaas Image Sensor Market
Imaging
Camera Lens Market
Imaging
Handheld Retinal Scanners Market
Imaging
Global Digital Binoculars Market
Imaging
Cooled IR Camera Market
Imaging
Global Trail Camera Market
Imaging
IR and Thermal Imaging Systems Market
Imaging
Europe Thermal Imaging Systems Market
Imaging
Global Microscopy Market
Imaging
Global Digital Photo Frame Market
Imaging
Global Ingaas Camera Market
Imaging
APAC Thermal Imaging Systems Market