
 Mobile Imaging Services Market | 2026-2036
Mobile Imaging Services Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Imaging Services Market Intelligence
Lighter-weight composite materials replacing traditional steel and aluminum in vehicle chassis construction is broadening the operational range and accessibility of mobile imaging fleets. Alliance HealthCare Services leverages its extensive network to provide contracted services to hospitals across the United States. TridentCare specializes in delivering diagnostic services to post-acute and long-term care facilities. Meanwhile, RAYUS Radiology differentiates its service offerings through a focus on advanced modalities like mobile MRI and PET/CT scans, catering to specialized clinical needs.
Mobile imaging services involve the provision of diagnostic procedures such as X-ray, MRI, CT, and ultrasound outside of fixed hospital environments. These services utilize specialized vehicles equipped with medical-grade imaging systems, often featuring high-frequency generators for portable X-ray units to ensure diagnostic quality. The primary purpose is to deliver convenient and timely diagnostic care to patients in alternate settings. Ultrasound and X-ray services constitute the largest volume segment due to their versatility and lower operational costs. The home care and diagnostic centers end-user categories represent the fastest-growing areas of deployment.
Regulatory frameworks are critical in defining operational standards and ensuring patient safety in this market. In the United States, equipment must receive clearance from the FDA, while technicians require state-level licensing. In Europe, mobile systems must adhere to CE marking requirements under the Medical Device Regulation (MDR). Approvals from bodies like Japan's PMDA are necessary for market entry in other key geographies. Providers must decide whether to specialize in a single high-demand modality or build a diversified portfolio to serve a wider range of clinical needs.
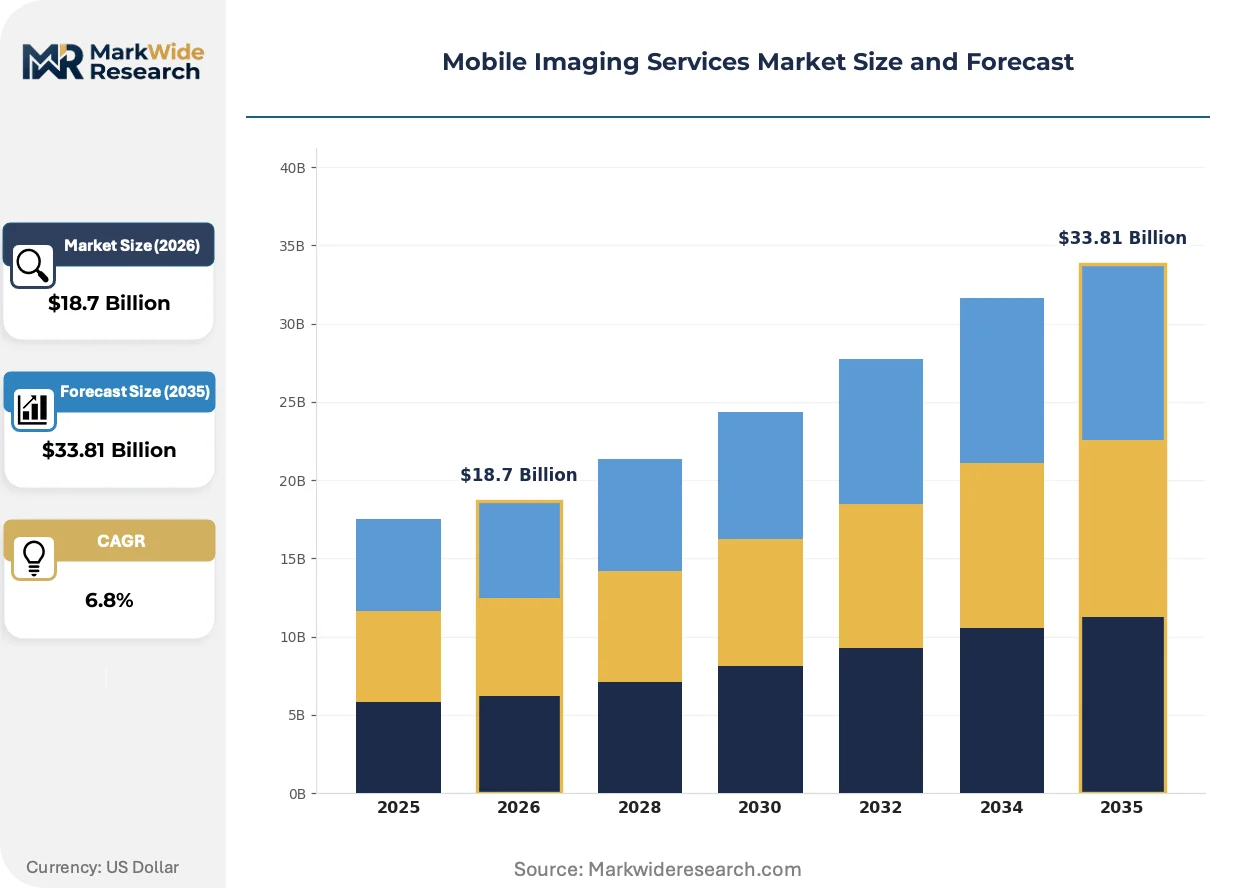
Market Dynamics
The primary structural force is the decentralization of healthcare delivery, shifting diagnostic procedures from centralized hospitals to alternate sites. This movement is driven by efforts to manage chronic diseases more effectively in lower-cost settings like home care and long-term care facilities, increasing demand for on-site imaging.
Growth Catalysts
- Aging Demographics:Countries with rapidly aging populations, notably Japan, exhibit high demand for accessible diagnostics, supporting mobile service expansion to serve elderly patients with mobility limitations.
- Regulatory Streamlining:Expedited clearance pathways from bodies like the US FDA for portable imaging equipment reduce time-to-market, encouraging innovation and adoption by service providers.
- Material Science Advances:The use of lightweight composite materials in vehicle construction, replacing steel, increases fuel efficiency and allows mobile units to access locations with stricter weight or size limits.
Market Restraints
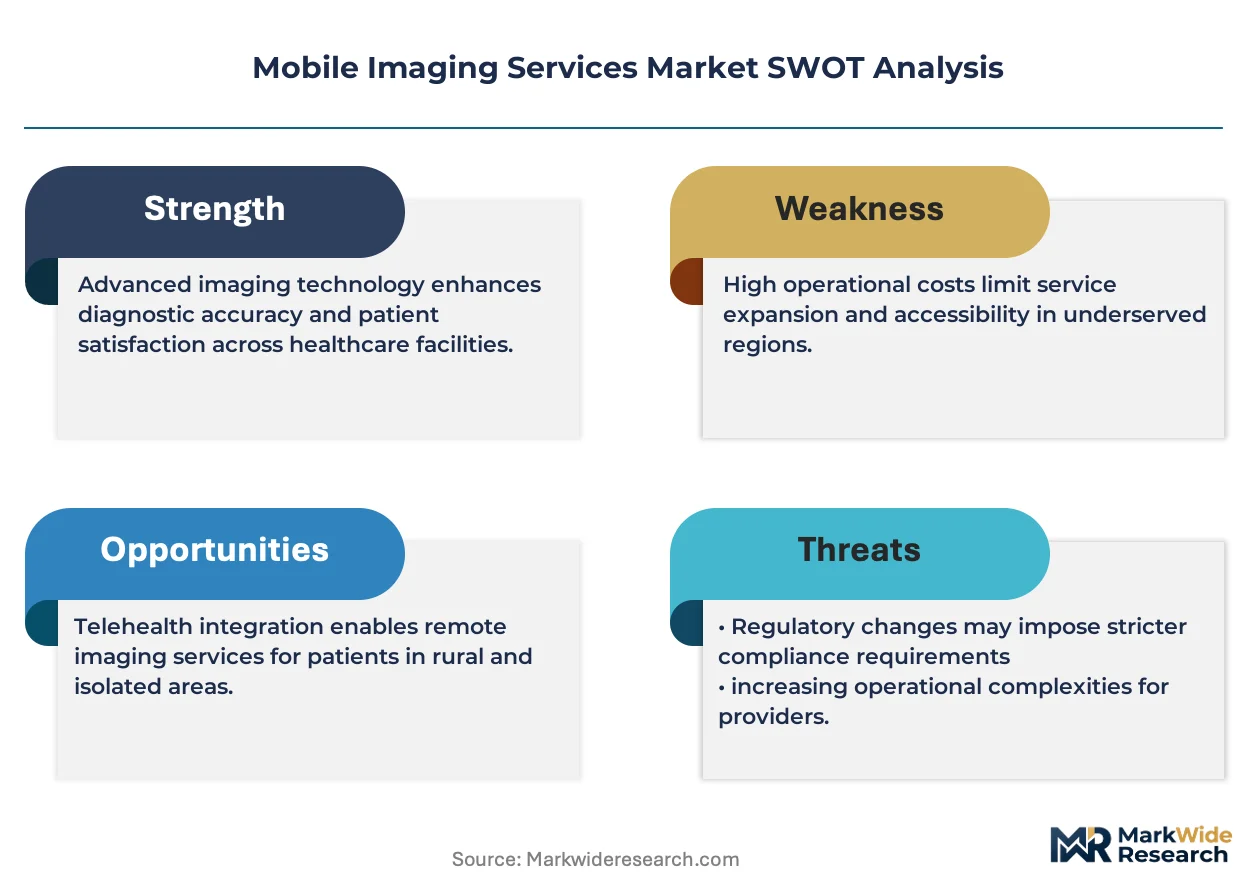
- High Capital Costs:The initial investment for advanced mobile units, particularly those with MRI or PET/CT systems, presents a significant financial barrier for new entrants and smaller operators.
- Licensing Fragmentation:In the United States, technician licensing requirements vary by state, creating administrative complexity and limiting the flexible deployment of staff across state lines.
- Technical Limitations:Mobile MRI units require stable power sources and controlled environments for magnetic field shielding, restricting their use in certain remote or underdeveloped locations.
Strategic Opportunities
- Teleradiology Integration:Combining mobile fleets with teleradiology platforms allows for immediate, expert interpretation of scans from remote specialists, enhancing diagnostic value and report turnaround times.
- Expansion in Underserved Markets:Targeting rural regions and developing nations with limited fixed hospital infrastructure represents a significant growth vector for basic modalities like X-ray and ultrasound.
- AI-Powered Triage:Integrating artificial intelligence software for on-site, preliminary image analysis helps prioritize critical cases and optimize radiologist workflow, creating a new service tier.
Industry Challenges
- Specialized Talent Scarcity:A shortage of radiologic technologists and drivers certified and willing to work within the demanding travel schedules of mobile fleet operations constrains service capacity.
- Data System Interoperability:Ensuring secure and seamless integration of imaging data from mobile units with diverse hospital Picture Archiving and Communication Systems (PACS) remains a persistent technical hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Imaging Services Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: X-Ray, Ultrasound, MRI, CT Scan Technology: Digital Imaging, Analog Imaging, 3D Imaging, Portable Imaging End User: Hospitals, Clinics, Home Care, Diagnostic Centers Deployment: On-Demand, Subscription, Pay-Per-Use, Hybrid |
| Companies Covered | Akumin Inc., DMS Health, Cobalt Health, Front Range Mobile Imaging, TridentCare, Accurate Imaging Diagnostics, RAYUS Radiology, Shared Medical Services, Alliance HealthCare Services, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Imaging Services Market Strategic Shifts & Innovations
The integration of digital technologies and new service models is transforming mobile imaging into an integral component of the patient care continuum. This evolution is driven by a focus on efficiency and accessibility in decentralized healthcare settings.
Portable, high-frequency X-ray generators provide diagnostic-quality imaging in a compact form factor. Home care agencies and long-term care facilities are the primary adopters, valuing the ability to perform exams at the bedside. This technology is modularizing diagnostic capabilities, unbundling them from large vehicles and allowing for more flexible deployment scenarios.
Europe's Medical Device Regulation (MDR) elevates the requirements for clinical evidence and post-market surveillance for all medical equipment. This directly impacts mobile imaging systems, especially those incorporating software for analysis. Providers and manufacturers in the EU must now invest more heavily in compliance and ongoing data collection to maintain CE marking.
A significant shift is occurring from simple fee-for-scan transactions toward value-based contracting. This model disrupts traditional procurement by tying payments for mobile imaging services to patient outcomes, report turnaround times, and overall cost savings. This trend is most advanced in the United States, where insurers and large health systems are its primary advocates.
Mobile Imaging Services Market Segmentation
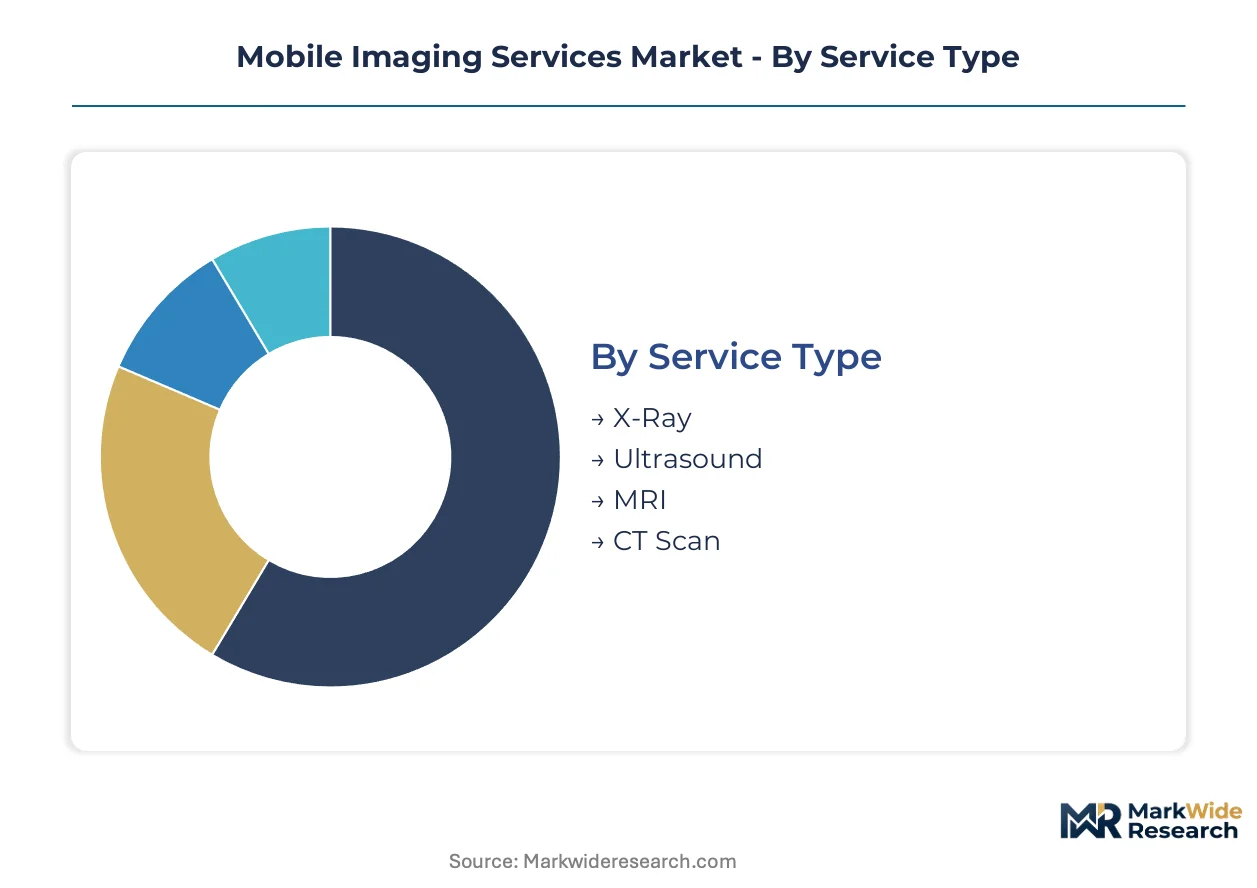
The Mobile Imaging Services Market is distinctly segmented to reflect the varied operational models, technological capabilities, and end-user requirements that shape its delivery. Understanding these segments is critical for providers to tailor service offerings and for healthcare systems to optimize diagnostic accessibility and efficiency across diverse patient populations.
Service Type:
The market segments by the diagnostic capabilities and operational characteristics of each imaging service type.
- X-Ray:These units utilize high-frequency generators for portable diagnostic imaging, crucial for musculoskeletal assessments and chest examinations. Demand concentrates in home care and long-term care facilities, providing essential diagnostics for elderly patients with mobility limitations.
- Ultrasound:This non-invasive modality provides real-time imaging of soft tissues and organs, frequently used for cardiac, abdominal, and vascular studies. Home care settings and point-of-care diagnostic centers drive demand due to its portability, safety, and immediate results.
- MRI:Mobile MRI units offer advanced soft tissue imaging for detailed neurological and orthopedic diagnoses.
- CT Scan:Mobile CT systems provide detailed cross-sectional images, essential for trauma assessment and complex disease diagnosis.
X-Ray leads on scale; Ultrasound leads on momentum.
Technology:
The market segments by the functional benefits and application scope of the underlying imaging technologies.
- Portable Imaging:This technology emphasizes compact design and ease of transport, enabling diagnostic services in diverse, non-traditional healthcare environments. Demand is high in rural regions and home care, where accessibility is a primary concern for basic diagnostic needs.
- Digital Imaging:Digital systems offer superior image quality, efficient data transfer, and seamless integration with Picture Archiving and Communication Systems (PACS). This technology is fundamental across all mobile imaging settings, enhancing diagnostic accuracy and workflow efficiency.
- 3D Imaging:This advanced technology provides multi-planar reconstructions, offering enhanced visualization for complex anatomical structures.
- Analog Imaging:Traditional analog systems, while cost-effective for initial setup, offer lower image resolution and slower processing compared to digital alternatives.
Digital Imaging dominates in adoption; Portable Imaging is gaining adoption fastest.
End User:
End-user segments reflect distinct settings of care and patient populations served by mobile imaging.
- Home Care:This segment serves patients in their residences, often managing chronic conditions or recovering from acute episodes, providing convenient bedside diagnostics. Demand is driven by aging populations and the decentralization of healthcare delivery, particularly in countries like Japan.
- Diagnostic Centers:These facilities leverage mobile imaging to expand service capacity, offer specialized modalities, and improve patient throughput. Demand is concentrated in urban and suburban areas requiring timely and accessible diagnostic procedures.
- Hospitals:Mobile units supplement fixed hospital imaging departments, providing overflow capacity or specialized services for specific patient populations.
- Clinics:Smaller clinics utilize mobile imaging for on-site diagnostic capabilities, enhancing patient convenience and reducing referral times.
Home Care is expanding most quickly; Diagnostic Centers demonstrate significant expansion.
Deployment:
Deployment models define the contractual and operational structures through which mobile imaging services are delivered.
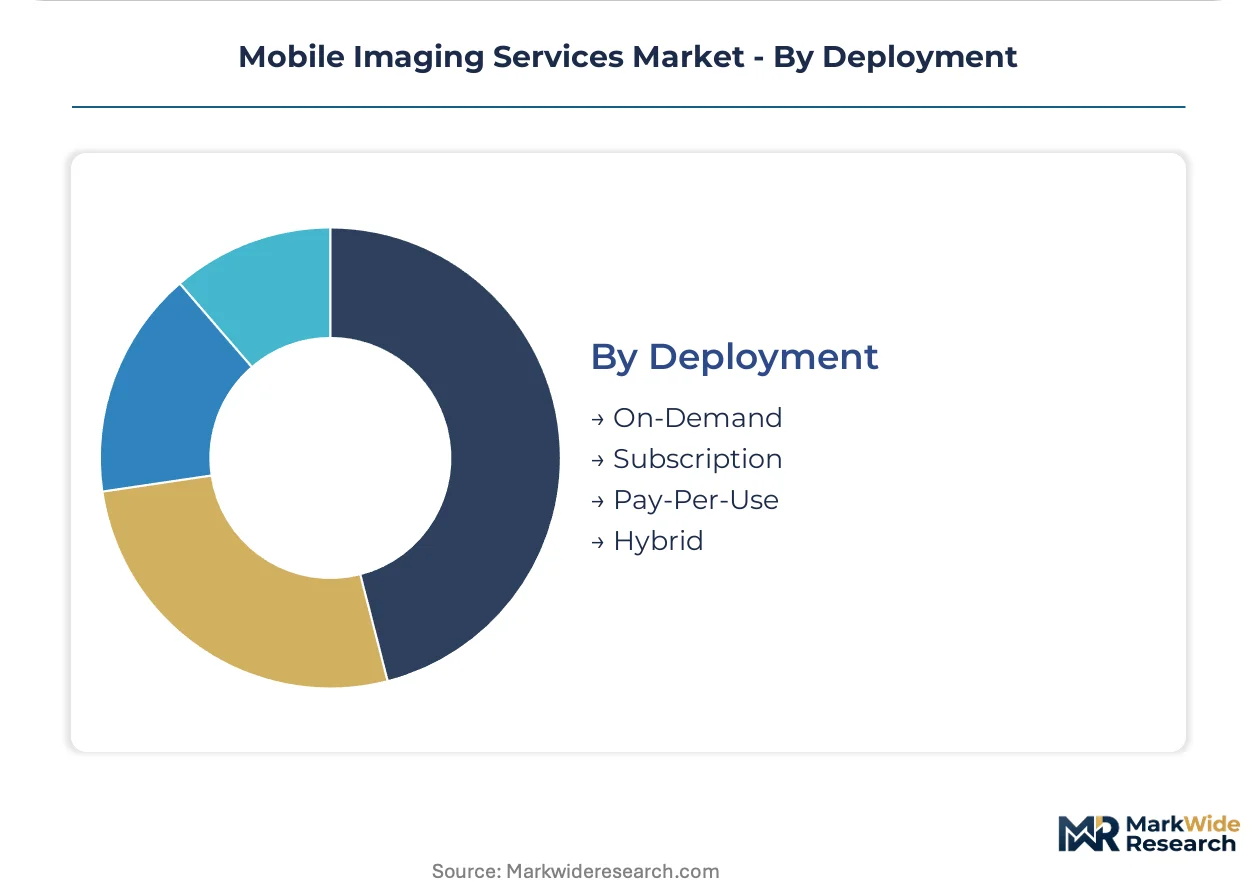
- On-Demand:This model provides services for immediate or ad-hoc diagnostic needs, offering flexibility for facilities without standing contracts. Demand arises from urgent care scenarios or unexpected equipment downtime in fixed facilities.
- Subscription:Facilities enter into long-term agreements for consistent access to mobile imaging services, ensuring predictable scheduling and cost management. This model is favored by long-term care facilities and large health systems for stable coverage.
- Pay-Per-Use:This transactional model charges clients for each individual imaging procedure performed.
- Hybrid:Hybrid models combine elements of subscription and pay-per-use, offering customized service agreements tailored to specific client requirements.
On-Demand deployment remains prevalent; Subscription models are gaining traction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's rapidly aging population anchors a significant portion of global demand for mobile imaging services, particularly within home care settings. This demographic shift drives the decentralization of diagnostic procedures, moving them closer to patients with mobility limitations. Regulatory bodies across different nations play a critical role in standardizing equipment and service delivery, ensuring patient safety and diagnostic quality.
Japan
Aging demographics and a strong emphasis on home-based care fuel the demand for accessible mobile diagnostic solutions in Japan. The Pharmaceuticals and Medical Devices Agency (PMDA) ensures stringent approval processes for all medical imaging equipment entering the market. Major metropolitan areas like Tokyo and Osaka are primary hubs for mobile imaging service providers expanding their fleets to serve elderly patients.
United States
The United States market experiences high demand for mobile imaging services, driven by chronic disease management and the expansion of home care services. US FDA clearance is mandatory for portable imaging equipment, alongside varied state-level licensing requirements for technicians. Urban centers such as New York, Los Angeles, and Chicago demonstrate significant deployment of mobile units by large healthcare networks.
Germany
Germany's healthcare system focuses on decentralization, increasing the need for mobile imaging services in post-acute and long-term care facilities. Mobile systems must adhere to CE marking requirements under the Medical Device Regulation (MDR) for market entry. Regions like Bavaria and North Rhine-Westphalia are seeing increased adoption of advanced mobile modalities, supporting specialized clinical needs.
India
Expanding healthcare access to underserved populations and developing rural regions drives demand for mobile X-ray and ultrasound services across India. Regulatory bodies, including the Bureau of Indian Standards (BIS), set quality and safety benchmarks for medical equipment. Major cities like Delhi-NCR and Mumbai are witnessing the growth of mobile diagnostic centers to improve patient throughput.
China
China's vast patient base and ongoing healthcare infrastructure development create substantial opportunities for mobile imaging, especially for basic diagnostic procedures. The National Medical Products Administration (NMPA) oversees the approval and regulation of medical devices, including mobile imaging systems. The Yangtze River Delta and Pearl River Delta regions represent key areas for mobile imaging innovation and service deployment.
Mobile Imaging Services Market Key Industry Players
Portfolio diversification dominates the current landscape, as providers strategically expand their service offerings to capture varied market segments. The market structure exhibits fragmentation, with numerous regional players alongside a few larger entities operating extensive networks. Strategic archetypes include large-scale network providers, specialized post-acute care providers, and advanced modality specialists. Geographic expansion and technology integration, particularly teleradiology and AI, represent significant competitive moves.
Specialists in post-acute and long-term care services, such as TridentCare, exemplify focused operational models catering to specific patient populations. Alliance HealthCare Services and Shared Medical Services occupy positions as large-scale network providers, leveraging extensive infrastructures to offer contracted services to hospitals. RAYUS Radiology, meanwhile, anchors the advanced modality segment, differentiating its offerings through specialized mobile MRI and PET/CT scans.
| Leading Market Players |
|---|
| Akumin Inc. |
| DMS Health |
| Cobalt Health |
| Front Range Mobile Imaging |
| TridentCare |
| Accurate Imaging Diagnostics |
| RAYUS Radiology |
| Shared Medical Services |
| Alliance HealthCare Services |
| Others |
Cost & Logistics Intelligence
Outsourced service provision anchors the supply position for mobile imaging, enabling flexible fleet deployment while influencing pricing power through specialized equipment and operational scale. This model permits providers to adapt to fluctuating demand and cost structures.
Pricing Analysis
Fuel and maintenance costs for specialized vehicles directly influence service pricing, with providers often passing these fluctuations to clients through adjusted contract rates. Value-based contracting is gaining traction, tying payments to patient outcomes and efficiency metrics, particularly in the United States. Geographic delivery costs and the advanced modality (e.g., mobile MRI vs. X-ray) drive significant price differentiation. Pricing softness in basic modalities like X-ray reflects increased competition, making home care agencies highly price-sensitive.
Supply Chain Analysis
Single-source vulnerability sits with specialized medical imaging equipment manufacturers for high-end mobile units like MRI and PET/CT systems. Key components and advanced systems draw from manufacturing hubs in Germany, Japan, and the United States, creating concentrated supply points. Regulatory restrictions on medical device import and export, particularly CE marking and FDA clearance, pose a structural risk to supply. Distribution runs through specialized logistics providers capable of handling sensitive medical equipment and managing complex installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Mobile Imaging Services Market functions as a stable compounder, driven by the persistent decentralization of healthcare delivery. This foundational shift ensures sustained demand for accessible diagnostic solutions across diverse care settings.
For Market Incumbents: Hedge against rising operational costs by optimizing fleet routing and investing in fuel-efficient composite material vehicles. Consolidate regional operations to achieve economies of scale and standardize service protocols. Pursue strategic partnerships with large hospital networks to secure long-term contracts, countering the threat of fragmented technician licensing. Invest in advanced teleradiology platforms to enhance diagnostic value.
For New Entrants and Emerging Players: Home care agencies offer a direct channel for new entrants to target underserved populations requiring basic X-ray and ultrasound services. Focus on rural regions and developing nations with limited fixed hospital infrastructure. Basic modalities in home care settings represent the most penetrable segment for initial market entry. Offer flexible pay-per-use models tailored to smaller clinics and remote facilities.
For Investors and Strategic Acquirers: Roll-up economics work for regional service providers because market fragmentation allows for efficient consolidation of operational footprints. The market demonstrates long-term viability, driven by aging demographics and the persistent shift towards decentralized care. Target specialized post-acute care providers to gain advanced modality capabilities. Watch for increased regulatory harmonization across states or regions as an inflection indicator for accelerated growth.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Teleradiology Integration | Enables remote interpretation of scans by specialists, enhancing diagnostic value and report turnaround times for providers. |
| Invest in Lightweight Composite Fleets | Broadens operational range and accessibility for mobile units, improving fuel efficiency for service providers. |
| Develop AI-Powered Image Triage | Prioritizes critical cases and optimizes radiologist workflow, creating a new service tier for diagnostic centers. |
| Pursue CE Marking for EU Entry | Ensures compliance with Medical Device Regulation, facilitating market entry for manufacturers in Europe. |
| Specialize in Mobile PET/CT Modalities | Differentiates service offerings for advanced clinical needs, attracting specialized patient populations and hospital contracts. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with robust secondary validation. Primary interviews included radiologic technologists, hospital procurement managers, and home care agency directors. Secondary data sources involved FDA clearance records, PMDA approvals, and industry reports on healthcare expenditure, facilitating bottom-up and top-down triangulation to ensure data accuracy.
Segment-weighting models were applied to project market evolution across the analysis window. Segmentation dimensions modeled included service type, technology, end-user category, and deployment model. Compound Annual Growth Rates were derived from historical trends and projected future demand, incorporating aging population statistics as a key input.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to technological breakthroughs and evolving healthcare policies. Forecasts reflect current market assumptions, yet global economic or regulatory shifts could alter trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Imaging
Global Pathology Imaging Systems Market
Imaging
Infrared Imaging Software Market
Imaging
Global Thermal Imager Market
Imaging
Global Image Signal Processor Market
Imaging
Pan-Tilt-Zoom (PTZ) Camera Market
Imaging
Light Field Market
Imaging
Concrete Rebar Corrosion and Delamination Imaging Systems Market
Imaging
Holotomographic Imaging Market
Imaging
Hyperspectral Imaging Camera Market
Imaging
X Ray Tubes Market
Imaging
Embedded Smart Cameras Market
Imaging
Latin America Surveillance Analog Camera Market
Imaging
Thermal Imaging Riflescope for Hunting Market
Imaging
North America Digital Camera Market
Imaging
Pocket Video Camera Market
Imaging
Global Label-Free Array Systems Market