
 Europe Pharmaceutical Glass Packaging Market | 2026-2036
Europe Pharmaceutical Glass Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Pharmaceutical Glass Packaging Market Insights
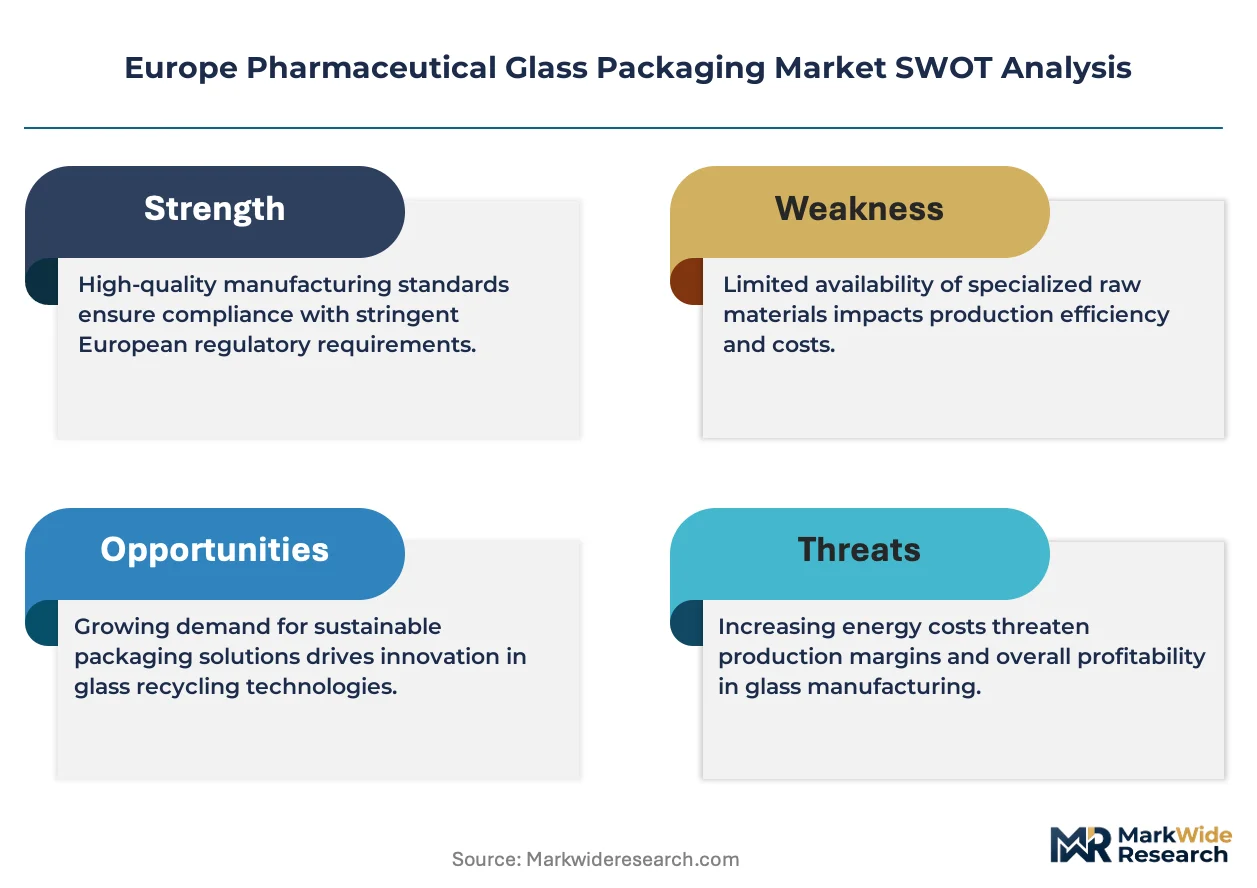
The divergence between premium and commodity tiers is shifting as biologic drug manufacturers demand Type I borosilicate vials with sub-ppm alkali release profiles while generic oral-solid producers accept Type III soda-lime bottles at substantially lower unit economics. Schott AG leverages its German melting furnace network to sustain captive supply of pharmaceutical tubing for high-value injectables. Gerresheimer AG anchors its position through vertical control over converting operations across multiple European manufacturing sites. SGD Pharma competes by specializing in molded glass bottles for oral liquid formulations where barrier specifications remain less stringent.
Pharmaceutical glass packaging denotes container systems fabricated from borosilicate or soda-lime compositions, engineered to meet pharmacopeial chemical durability standards including hydrolytic resistance and thermal shock tolerance, primarily serving to maintain drug sterility, prevent oxygen ingress, and eliminate ionic migration over shelf-life durations. Vials occupy the dominant revenue position within product type segments due to their indispensability for parenteral biologics requiring hermetic closure with elastomeric stoppers. Type I Glass commands premium pricing and fastest growth within material categories because its low boron oxide formulation minimizes delamination risk for protein-based therapies. Ampoules retain mature demand profiles in Eastern European markets where small-volume generic injectables still rely on single-use break-seal formats.
EMA stability guidelines, EU MDR traceability mandates, and REACH chemical authorization protocols collectively elevate compliance burdens for packaging converters while creating barriers against non-European suppliers lacking notified body certifications. The F-Gas Regulation indirectly shapes demand by restricting fluorinated greenhouse gas use in glass melting operations, pushing manufacturers toward electric furnace retrofits or oxy-fuel combustion alternatives. Stakeholders must monitor how EMA's evolving extractables testing thresholds will bifurcate supplier qualification timelines between premium borosilicate and commodity soda-lime categories.
Market Dynamics
EMA's tightening extractables and leachables thresholds are forcing biologic drug manufacturers to requalify their entire vial supply chains around Type I borosilicate specifications, compressing qualification timelines and concentrating procurement decisions among converters with captive melting capacity.
Growth Catalysts
- EMA Stability Guidelines:The agency's sub-ppm alkali release thresholds for protein-based therapies are compelling biologics manufacturers to upgrade from Type III soda-lime to Type I borosilicate vials, creating sustained demand pull for premium glass tubing.
- F-Gas Regulation:Restrictions on fluorinated greenhouse gases in glass melting operations are accelerating electric furnace retrofits across German and French manufacturing clusters, positioning early movers with lower-carbon production credentials.
- Biologics Pipeline Expansion:Monoclonal antibody and cell therapy developers in Germany, Switzerland, and the Netherlands are locking in multi-year supply contracts for hermetic vial systems with demonstrated delamination resistance.
Market Restraints
- Energy Cost Volatility:Natural gas and electricity price swings across Germany and Italy directly compress margins for converters operating energy-intensive melting furnaces, forcing pass-through pricing that erodes competitiveness against Asian imports.
- Raw Material Concentration:High-purity boron oxide and sand supply chains concentrate among a handful of Turkish and Nordic suppliers, exposing European fabricators to geopolitical disruption and input cost spikes.
- Substitute Materials:Cyclic olefin polymers and barrier-coated plastics are capturing share in oral-solid and ophthalmic segments where oxygen ingress requirements remain less stringent than parenteral standards.
Strategic Opportunities
- Eastern European Manufacturing:Poland and Czech Republic offer underutilized industrial gas infrastructure and skilled glassworker labor pools for converters seeking to diversify production footprint beyond high-cost German sites.
- EU MDR Traceability Mandates:The regulation's unique device identification requirements create first-mover advantage for packaging converters integrating serialization and aggregation capabilities directly into vial and ampoule production lines.
- Pre-filled Syringe Convergence:Combination product developers seeking integrated drug-device formats present white space for glass converters partnering with elastomer and plunger manufacturers on ready-to-fill systems.
Industry Challenges
- Specialized Glassworker Shortage:Melter operator and forming technician expertise is concentrating among aging workforces in Thuringia and Bavaria, constraining capacity expansion timelines for new furnace installations.
- Qualification Timeline Compression:EMA's evolving extractables testing protocols are extending supplier validation cycles from 18 to 36 months for biologics applications, freezing out mid-tier converters lacking dedicated regulatory affairs functions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Pharmaceutical Glass Packaging Market |
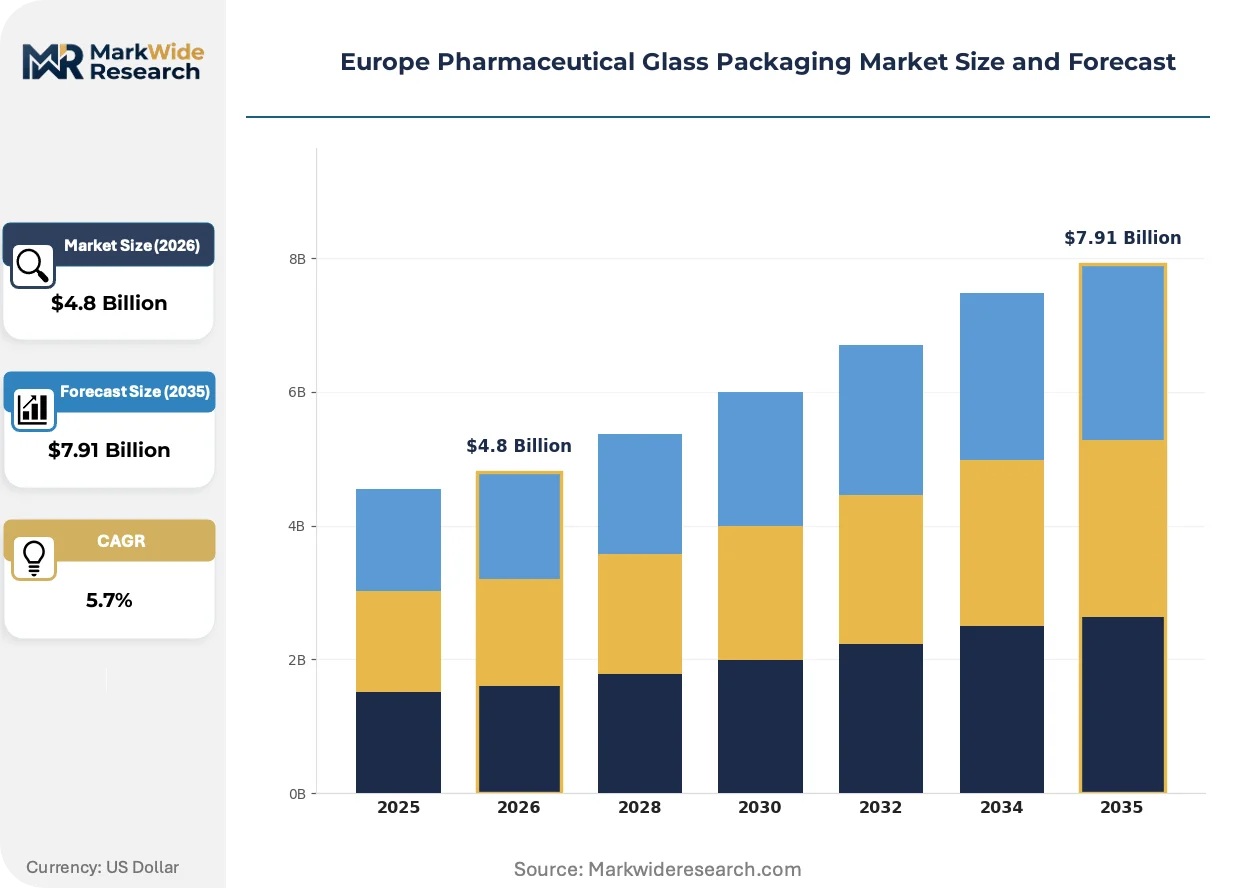
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vials, Ampoules, Syringes, Bottles Material: Type I Glass, Type II Glass, Type III Glass, Borosilicate End User: Pharmaceutical Companies, Biotech Firms, Contract Manufacturers, Research Laboratories Closure Type: Screw Caps, Stoppers, Crimp Caps, Dropper Caps |
| Companies Covered | Schott AG, Gerresheimer AG, Stevanato Group, SGD Pharma, Bormioli Pharma, Nipro Corporation, Ardagh Group, Stölzle-Oberglas GmbH, Beatson Clark, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Pharmaceutical Glass Packaging Market Trends and Innovations
Glass melting and forming technologies are undergoing fundamental transformation as energy transition imperatives collide with pharmacopeial precision requirements, reshaping capital deployment patterns across European manufacturing networks.
Oxy-fuel combustion systems with electric boosting are electrifying the melting process in German furnace networks, replacing conventional air-gas firing to cut direct emissions while maintaining thermal uniformity for borosilicate tubing production. Schott AG and Gerresheimer AG are retrofitting legacy sites in Mainz and Mitterteich, targeting compliance with EU Green Deal carbon benchmarks without sacrificing hydrolytic resistance specifications. This electrification is compressing the competitive set to converters with balance sheet capacity for nine-figure capex programs.
REACH chemical authorization protocols are tightening scrutiny on cobalt-based colorants and surface treatment chemistries used in amber glass production, forcing reformulation of Type III bottles for photosensitive oral liquids. SGD Pharma and smaller French converters are accelerating migration to iron-based colorant systems, absorbing R&D costs that commodity soda-lime competitors cannot shoulder. Oral liquid formulations with moderate light protection requirements are most affected, with several German generic firms now requiring full material disclosure from packaging suppliers.
Biologics procurement teams are consolidating vendor panels around converters offering integrated quality agreements spanning tubing, converting, and surface treatment operations. Large-molecule developers in Switzerland and the Netherlands are displacing multi-source strategies with sole-source partnerships anchored by dedicated furnace capacity and real-time extractables data sharing. This concentration is most visible among CDMOs serving Phase III biologics pipelines, where supply security now outweighs unit cost optimization in sourcing criteria.
Europe Pharmaceutical Glass Packaging Market Segmentation
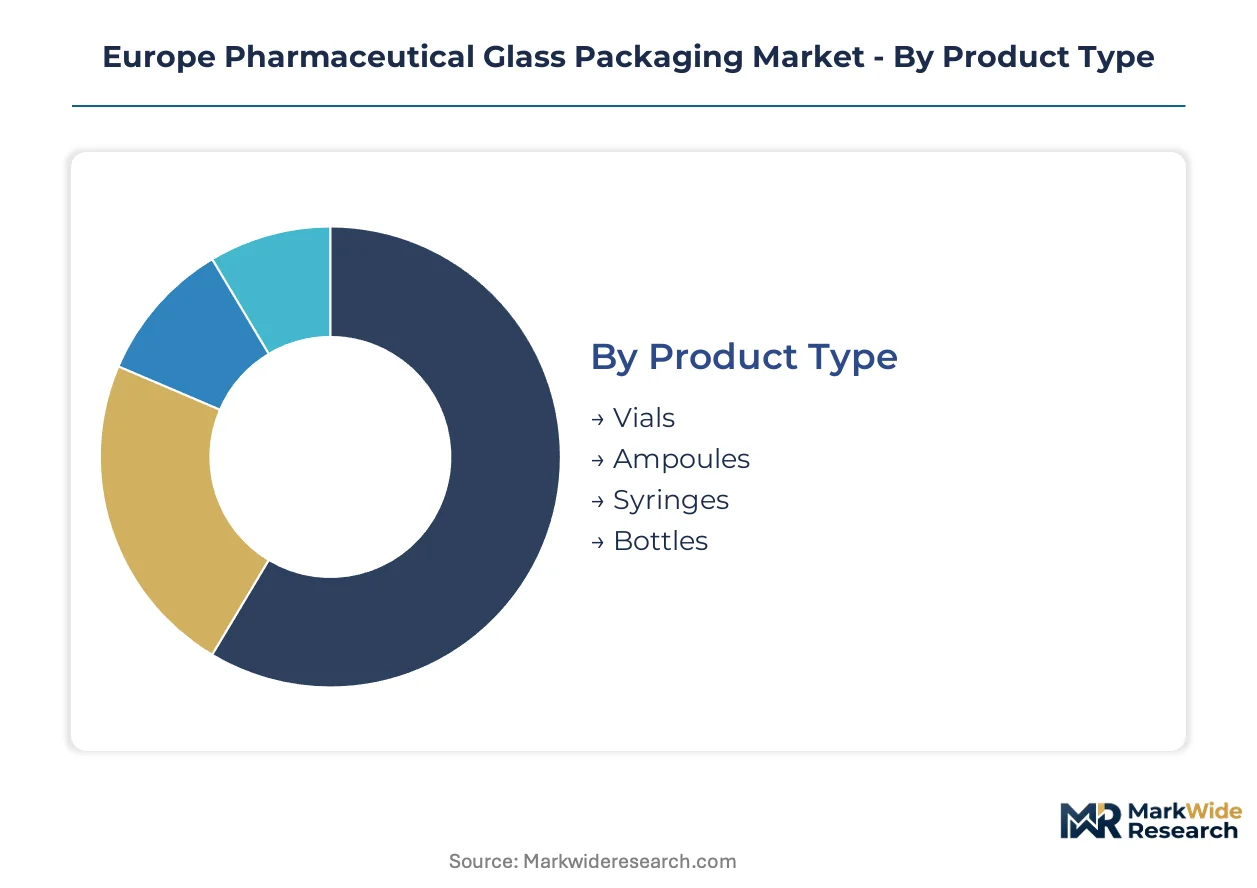
Pharmaceutical glass packaging procurement in Europe bifurcates sharply between biologics manufacturers demanding pharmacopeial-grade Type I borosilicate systems and generic producers optimizing for unit cost. Understanding segment-level trade-offs enables converters to align furnace investments with qualification timelines and margin profiles.
Product Type:
End-use application dictates closure complexity, barrier requirements, and sterilization protocols across European manufacturing sites.
- Vials:Hermetic cylindrical containers engineered for parenteral administration with elastomeric stopper interfaces. Demand concentrates among German and Swiss biologics developers requiring delamination-resistant formats for monoclonal antibody storage, with EMA extractables thresholds forcing specification upgrades.
- Syringes:Pre-sterilized barrel-and-plunger systems designed for ready-to-administer injectables. Dutch and Belgian CDMOs are locking in multi-year supply contracts for integrated glass-elastomer combination products, displacing traditional vial-and-needle workflows.
- Ampoules:Single-dose break-seal containers for small-volume generics. Eastern European markets retain mature demand profiles where cost-sensitive injectables still rely on this format.
- Bottles:Wide-mouth containers for oral liquid and solid formulations. French and Italian generic houses specify Type III soda-lime variants where hydrolytic resistance requirements remain less stringent than parenteral standards.
Vials lead on scale; syringes lead on momentum.
Material:
Chemical durability grades separate premium biologics applications from commodity oral-solid packaging across European pharmacopeial compliance frameworks.
- Type I Glass:Low boron oxide borosilicate composition delivering sub-ppm alkali release profiles. German tubing manufacturers are capturing dedicated furnace contracts from Phase III biologics developers, with EMA stability guidelines compressing qualification timelines around this specification.
- Type III Glass:Soda-lime composition with moderate hydrolytic resistance for non-parenteral applications. Polish and Czech converters serve oral liquid generic producers where barrier specifications tolerate higher ionic migration thresholds.
- Type II Glass:Surface-treated soda-lime offering intermediate durability for sensitive non-injectables. Limited penetration in Europe as buyers prefer clear grade differentiation between Type I and Type III tiers.
- Borosilicate:Broad category encompassing both pharmaceutical-grade tubing and technical glassware. REACH chemical authorization protocols are tightening scrutiny on cobalt-based colorants used in amber variants, forcing reformulation investments.
Type III glass dominates volume throughput; Type I glass commands margin expansion.
End User:
Procurement sophistication varies sharply between large-cap biologics developers and fragmented generic manufacturers.
- Pharmaceutical Companies:Integrated drug developers with captive quality assurance functions. Swiss and German majors are consolidating vendor panels around converters offering real-time extractables data sharing and dedicated furnace capacity.
- Biotech Firms:Venture-backed developers of monoclonal antibodies and cell therapies. Netherlands-based startups are prioritizing supply security over unit cost optimization, locking in sole-source partnerships with Mainz and Mitterteich fabricators.
- Contract Manufacturers:CDMOs serving multiple sponsor pipelines. Eastern European facilities are expanding glass packaging procurement as biotech clients demand localized supply chains for EU MDR traceability compliance.
- Research Laboratories:Academic and clinical trial material suppliers. Smaller volume requirements limit bargaining power, with procurement flowing through distributor channels rather than direct converter relationships.
Pharmaceutical companies anchor procurement volume; biotech firms drive specification escalation.
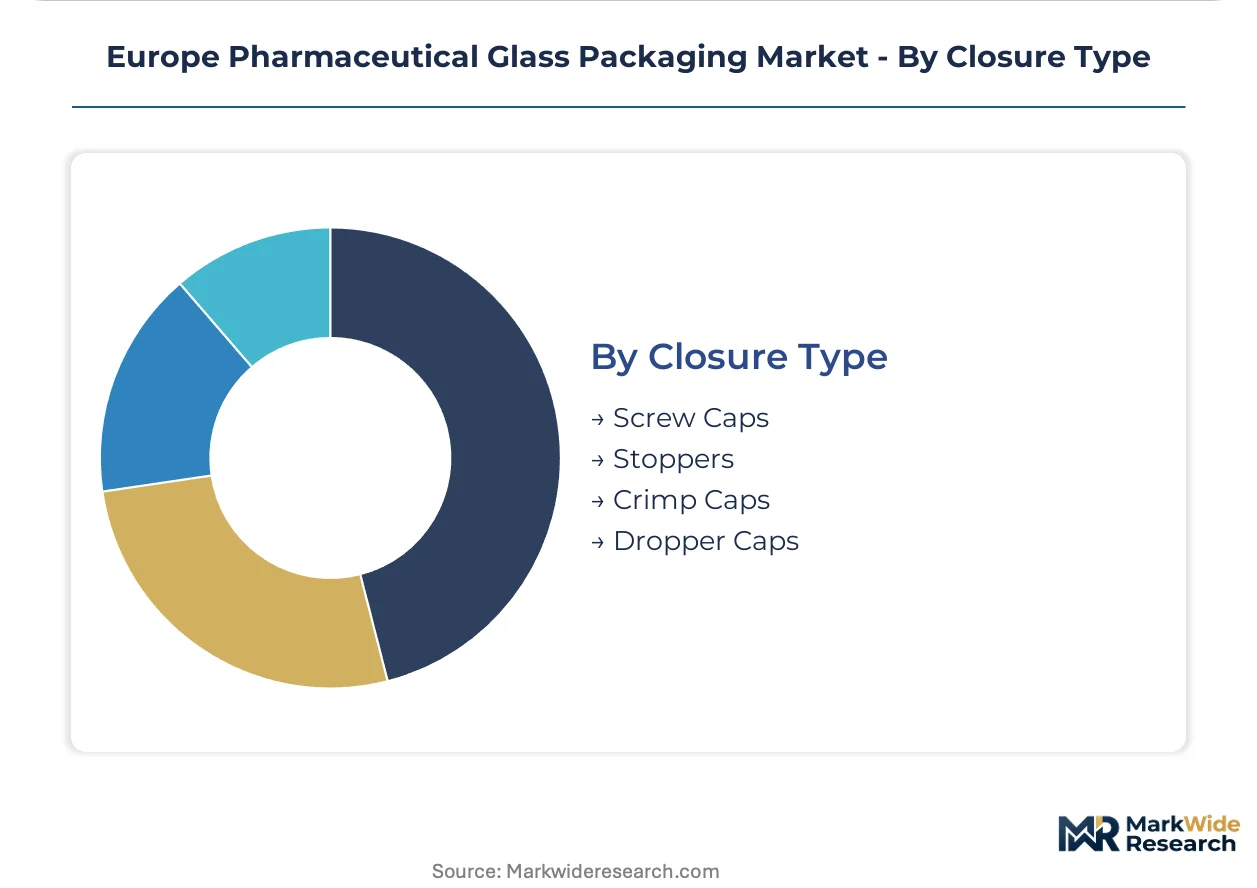
Closure Type:
Sealing mechanism selection determines barrier integrity, user handling, and regulatory classification as device or packaging.
- Stoppers:Elastomeric inserts for hermetic vial sealing. German rubber compounders are partnering with glass converters on integrated quality agreements spanning both substrate and closure extractables testing.
- Crimp Caps:Aluminum seals applied over stoppers for tamper evidence. Biologics applications require precise crimp force control to maintain container closure integrity through freeze-thaw cycles.
- Screw Caps:Threaded closures for multi-dose bottles. French oral liquid specialists specify child-resistant variants with iron-based colorants replacing REACH-scrutinized cobalt systems.
- Dropper Caps:Integrated bulb-and-tip assemblies for ophthalmic and nasal applications. Italian converters specialize in molded glass compatibility with silicone bulb formulations.
Stoppers dominate biologics applications; screw caps retain oral-solid volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled glassworker concentrations in Thuringia and Bavaria anchor European pharmaceutical glass fabrication, with specialized melter operators and forming technicians concentrating in legacy industrial clusters around Mainz and Mitterteich.
Germany
Biologics developers in Munich and Heidelberg are locking in multi-year vial supply contracts as EMA extractables thresholds tighten. The F-Gas Regulation is accelerating electric furnace retrofits across Rhineland-Palatinate melting sites. Mainz-based tubing manufacturers are capturing dedicated capacity agreements from Phase III monoclonal antibody sponsors seeking supply security.
Switzerland
Basel-area pharmaceutical majors are consolidating vendor panels around converters offering real-time quality data sharing. Swissmedic pharmacovigilance requirements exceed baseline EMA standards for container closure integrity. Lucerne and St. Gallen fabrication clusters are expanding borosilicate tubing output for cell therapy packaging applications.
France
Paris-region generic houses are reformulating amber glass colorant systems away from REACH-scrutinized cobalt toward iron-based alternatives. ANSM stability guidelines for oral liquids are tightening material disclosure requirements from packaging suppliers. Normandy and Picardy molded glass sites are specializing in Type III bottles for photosensitive formulations.
Netherlands
Leiden and Utrecht biotech startups are prioritizing supply security over unit cost in vial procurement decisions. EU MDR traceability mandates are driving demand for serialization-ready packaging from Dutch CDMOs. Eindhoven-area converters are integrating aggregation capabilities directly into vial production lines for combination product developers.
Poland
Warsaw and Krakow contract manufacturers are expanding glass packaging procurement as Western European biotech clients demand localized supply chains. Lower Saxony-based fabricators are shifting secondary converting operations to Polish sites to manage energy cost differentials. Silesian industrial zones offer underutilized gas infrastructure for furnace operators diversifying beyond German production footprints.
Europe Pharmaceutical Glass Packaging Market Competitive Landscape
Top-tier vendors anchor premium borosilicate supply, while mid-scale converters compete on molded glass volume and regional oral-solid contracts. The market structure concentrates around German and Swiss fabricators with captive melting capacity, with second-tier players specializing in Type III soda-lime formats for cost-sensitive applications. Two strategic archetypes dominate: integrated tubing-to-vial operators with furnace networks, and molded bottle specialists serving generic liquid formulations. Competitive moves center on electric furnace retrofits for carbon credentialing and sole-source partnerships with biologics developers seeking dedicated capacity.
Among German-based fabricators, Schott AG and Gerresheimer AG exemplify the integrated archetype with upstream control over pharmaceutical tubing production, while SGD Pharma occupies a position within the molded glass specialization tier serving oral liquid applications. These three entities represent the competitive spectrum from premium parenteral systems to commodity pharmaceutical bottles, with each anchoring distinct qualification timelines and margin profiles across European procurement panels.
| Leading Market Players |
|---|
| Schott AG |
| Gerresheimer AG |
| Stevanato Group |
| SGD Pharma |
| Bormioli Pharma |
| Nipro Corporation |
| Ardagh Group |
| Stölzle-Oberglas GmbH |
| Beatson Clark |
| Others |
Pricing and Supply Chain Analysis
High-purity boron oxide feedstock flows from Turkish and Nordic suppliers through German melting furnace networks, concentrating pricing power among converters with captive tubing production while forcing commodity soda-lime competitors toward thinner margins. EMA extractables thresholds bifurcate procurement panels, enabling premium-tier converters to command sustained premiums for Type I borosilicate qualification data.
Pricing Analysis
Bundled quality agreements spanning tubing, converting, and real-time extractables data sharing command substantial premiums over unbundled transactional sourcing. Three-tier pricing structure across premium, standard, and economy levels separates dedicated-furnace biologics contracts from spot-market oral-solid bottles. Price differentiation hinges on pharmacopeial certification grade and volume-scale commitments. Cost compression in Type III soda-lime tiers intensifies because energy pass-through pricing erodes competitiveness against Eastern European imports. Generic oral-solid producers exhibit highest price sensitivity, while Phase III biologics developers prioritize supply security.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical glass remain minimal given single-use sterility requirements, though defective batch returns to German and French melting sites enable cullet recycling into non-pharmaceutical technical glass. Supply concentrates in Germany, France, and Switzerland for premium borosilicate tubing, with Poland and Czech Republic capturing secondary converting operations. Raw material dependencies rest on Turkish boron oxide, Nordic high-purity sand, and Ukrainian soda ash. Single-source vulnerability concentrates among a handful of boron oxide suppliers. Distribution runs through direct converter relationships for biologics and distributor channels for generic oral-solid procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe pharmaceutical glass packaging operates as a regulatory compounder, where EMA's tightening extractables thresholds continuously revalue qualification timelines and furnace capacity. EU MDR traceability mandates compound compliance burdens while creating defensive moats for early movers.
For Market Incumbents: Anchor defensive positioning through captive melting capacity expansion in Rhineland-Palatinate and Bavaria, locking in sole-source partnerships with Swiss and Dutch biologics developers. Cyclic olefin polymers threaten parenteral share in ophthalmic segments; counter through integrated glass-elastomer combination product development with Dutch CDMOs. Backward integration into boron oxide offtake agreements mitigates raw material concentration risk. For New Entrants and Emerging Players: The premium-economy price-point gap in Type II surface-treated soda-lime presents white-space opportunity for mid-tier oral liquid applications where barrier requirements exceed Type III tolerance. Target Polish and Czech contract manufacturing clusters seeking localized supply chains for EU MDR compliance. Partner with Eastern European industrial gas infrastructure operators to undercut German energy cost structures. For Investors and Strategic Acquirers: Consolidation pressure builds where aging glassworker expertise concentrates in Thuringia and Bavaria, constraining capacity expansion timelines for independent converters. Five-to-ten-year viability favors integrated tubing-to-vial operators with electric furnace retrofit completion and dedicated biologics capacity. Monitor EMA extractables protocol evolution as inflection indicator for qualification timeline compression favoring incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Electric Furnace Retrofit | Rhineland-Palatinate sites achieve F-Gas compliance while maintaining borosilicate thermal uniformity. |
| Integrated Quality Agreement | Real-time extractables data sharing secures sole-source partnerships with Swiss biologics developers. |
| Eastern European Footprint Expansion | Polish and Czech sites leverage underutilized gas infrastructure to manage energy cost differentials. |
| Iron-Based Colorant Migration | REACH-compliant amber glass reformulation captures French generic oral liquid contracts. |
| Serialization Integration | Dutch converters embed aggregation capabilities for EU MDR traceability compliance. |
Research Methodology
Coverage spans Western and Eastern European pharmaceutical manufacturing clusters, with primary inputs from each regional regulatory environment. Melting furnace operators, biologics procurement directors, CDMO quality assurance leads, and EMA regulatory affairs specialists contributed structured interviews. Secondary validation drew from EMA stability guideline publications, EU MDR implementation documents, F-Gas Regulation compliance disclosures, and REACH chemical authorization protocols. Bottom-up tubing capacity assessments and top-down pharmaceutical packaging expenditure estimates underwent cross-triangulation.
Granularity-level modeling distinguished Type I borosilicate from Type III soda-lime at the material tier, vial from syringe from ampoule at the product format level, and biologics developer from generic manufacturer from contract manufacturer at the end-user archetype. Dosage form, administration route, and regional regulatory cluster dimensions informed segment-level projections. CAGRs were derived from production capacity expansion schedules, pipeline progression data, and procurement contract visibility across the projection horizon. Energy transition capex programs and glassworker demographic trajectories supplied industry-specific forecast inputs.
Caveats apply where EMA extractables protocol revisions or REACH chemical authorization expansions could materially shift the outlook for supplier qualification timelines and furnace investment returns. Forecasts reflect assumptions about biologics pipeline progression, energy cost stabilization, and boron oxide supply continuity. Practitioners should monitor F-Gas Regulation enforcement intensity and Eastern European industrial gas infrastructure utilization for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
China Pharmaceutical Packaging Market
Pharmaceutical Packaging
Pharmaceutical Labeling Market
Pharmaceutical Packaging
Europe Pharmaceutical Blister Packaging Market
Pharmaceutical Packaging
Serum Bottles Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Global Temperature Controlled Packaging Solutions for Pharmaceuticals Market
Pharmaceutical Packaging
Pharma Trays Market
Pharmaceutical Packaging
US Clinical Trial Packaging Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Laboratory Consumables Primary Packaging Market
Pharmaceutical Packaging
Pharmaceutical Vial Fillers Market
Pharmaceutical Packaging
Pharmaceutical Packaging Equipment Market
Pharmaceutical Packaging
China Pharmaceutical Contract Packaging Market
Pharmaceutical Packaging
Vaccine Packaging Market
Pharmaceutical Packaging
Tablets and Capsules Packaging Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market