
 Flexible Pouch Market | 2026-2036
Flexible Pouch Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Pouch Market Foresight
Multi-source procurement for barrier films is realigning how brand owners manage supply risk across converter networks. Amcor PLC leverages its global film extrusion footprint to secure resin access across three continents. Mondi Group anchors its competitive stance through integrated kraft paper and extrusion coating operations in Europe. Sealed Air Corporation differentiates via proprietary vacuum and modified-atmosphere pouch systems for protein applications.
Flexible pouches are multi-layer laminated containers, typically combining polyethylene, polyamide, or ethylene vinyl alcohol in thicknesses ranging from 80 to 200 microns, formed through flat-bed or roll-fed sealing processes to provide oxygen and moisture barriers for perishable contents. Laminates dominate material value due to their tailored barrier performance, while biodegradable films represent the fastest-expanding category as converters respond to extended producer responsibility frameworks. Zipper closures command premium positioning in pet products and snack packaging, whereas heat seal formats occupy volume leadership in commodity liquid and powder applications.
EU REACH and the Packaging and Packaging Waste Regulation constrain adhesive and ink chemistries, while FDA compliance requirements govern migration limits for U.S.-destined food-contact laminates. ECHA substance-of-very-high-concern listings are forcing reformulation of certain phthalate-based plasticizers previously common in spout assemblies. Stakeholders must monitor evolving mono-material recyclability certifications and state-level extended producer responsibility laws to anticipate which barrier technologies will retain market access.
Market Dynamics
Mono-material recyclability mandates from the EU Packaging and Packaging Waste Regulation are forcing converters to re-engineer multi-layer laminates, collapsing established barrier film supply relationships and accelerating capital redeployment toward polyethylene-compatible lines.
Growth Catalysts
- Retort-ready mono-materials:Polyethylene-based high-barrier films are displacing polyamide laminates in shelf-stable pet food and ready-to-eat meals as converters chase Design for Recycling certification.
- Extended Producer Responsibility frameworks:France's AGEC law and Italy's CONAI fee restructuring penalize non-recyclable packaging, directing brand owner procurement toward certified mono-material suppliers.
- Spout integration for liquid concentrates:Fitness beverages and liquid coffee concentrates are adopting fitmented pouches to replace rigid bottles, driving zipper and spout assembly demand.
Market Restraints
- Ethylene vinyl alcohol resin concentration:Four Asian petrochemical groups control over seventy percent of EVOH supply, exposing European converters to freight volatility and currency mismatch.
- Retort compatibility barriers:Mono-material polyethylene structures fail at 121°C sterilization temperatures required for low-acid foods, preserving multi-layer laminate dominance in shelf-stable protein.
- Mechanical recycling contamination limits:Germany's DKR and Spain's Ecoembes sorting facilities reject pouches with aluminum oxide coatings, stranding inventory from brands lacking chemical recycling partnerships.
Strategic Opportunities
- Pharmaceutical compliance expansion:Child-resistant zipper certification for cannabis edibles and pediatric OTC liquids is expanding pouch adoption beyond food into regulated drug delivery.
- Digital watermarking integration:AIM-Digimarc and GS1 standards enable sortation-line recognition of mono-material structures, unlocking deposit-return scheme eligibility in Scandinavian markets.
- Paper-fiber hybrid structures:Extrusion-coated kraft pouches with thin polymer barriers are penetrating dry goods and confectionery, capturing fiber-based packaging subsidies in the Netherlands and Belgium.
Industry Challenges
- Barrier film coextrusion expertise scarcity:Mono-material lines require precise layer distribution control that legacy laminate technicians lack, extending commissioning timelines and defect rates at converted facilities.
- Migration testing backlog:EU 10/2011 compliance documentation for new adhesive and ink chemistries faces eighteen-month queues at commercial laboratories, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Pouch Market |
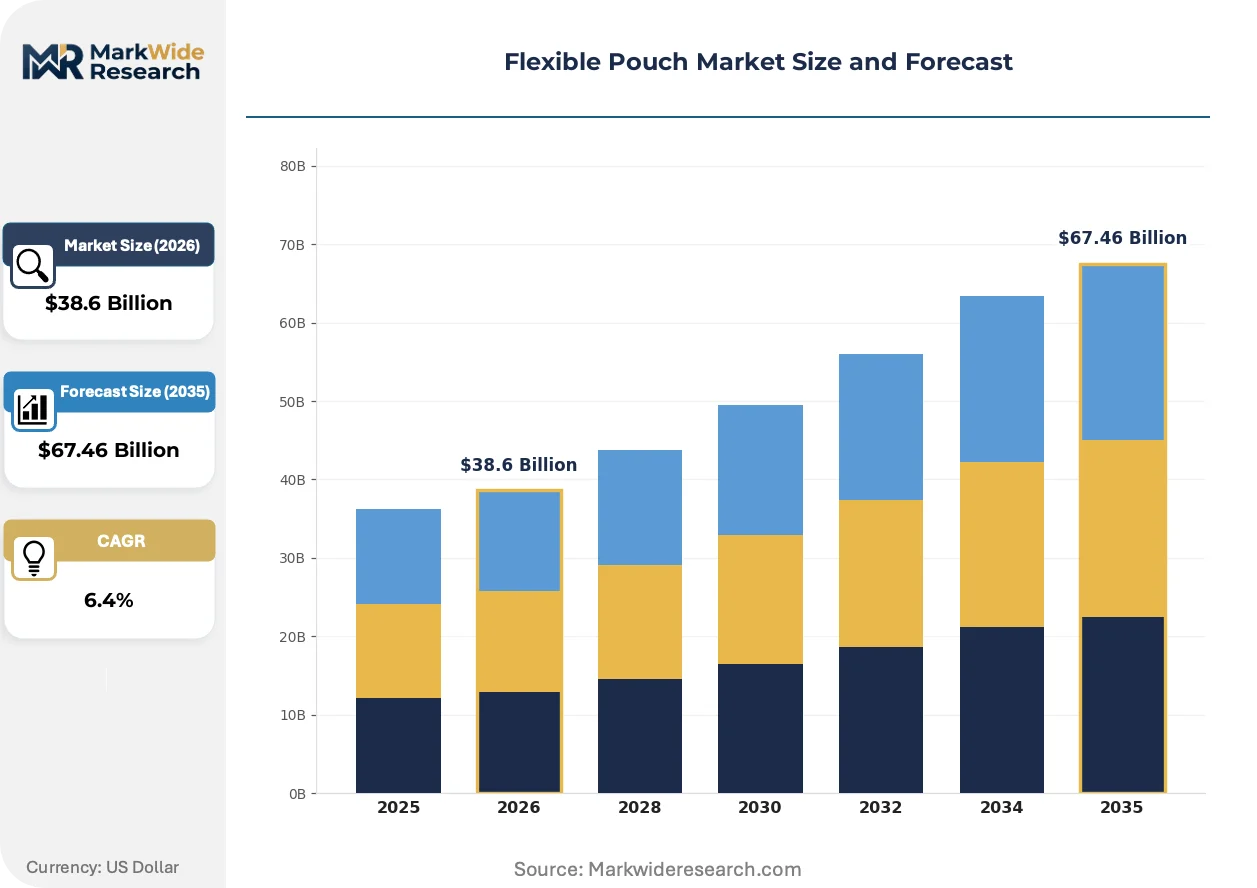
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $67.46 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Aluminum Foil, Paper, Laminates, Biodegradable Films Closure Type: Zipper, Spout, Heat Seal, Adhesive Tape, Tear Notch End Use Industry: Food & Beverage, Personal Care, Pet Products, Household Chemicals, Agriculture Application: Snack Packaging, Liquid Packaging, Powder Packaging, Pharmaceutical Packaging, Cosmetic Containers |
| Companies Covered | Amcor PLC, Mondi Group, Sealed Air Corporation, Sonoco Products Company, Berry Global Inc., Huhtamaki Oyj, ProAmpac, Constantia Flexibles, Smurfit Kappa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Pouch Market Shifts & Advancements
Digital printing and artificial intelligence are compressing design-to-shelf cycles while regulatory pressure on recyclability is collapsing traditional material hierarchies, forcing simultaneous innovation across substrate, conversion, and sortation infrastructure.
Digital inkjet printing is expanding into short-run flexible pouch production, enabling brand owners to test regional flavor variants without plate costs. Pet food and craft snack producers in Poland and the Czech Republic are adopting this for seasonal SKUs. The technology is expanding into territory previously dominated by rotogravure, compressing minimum economic order quantities and fragmenting converter customer bases.
REACH substance-of-very-high-concern listings are forcing immediate adhesive reformulation across European converter networks. ECHA's 2023 phthalate restrictions have disrupted spout assembly supply chains, compelling procurement teams to qualify citrate-based plasticizer alternatives. Protein and dairy applications face the steepest compliance timelines given existing migration testing commitments.
Direct-to-retailer procurement consolidation is compressing distributor margins in flexible packaging. German and French supermarket chains are establishing private-label pouch specifications and auditing converter compliance directly, bypassing traditional trade intermediaries. This pattern is most visible in discount grocery and organic private label segments where traceability requirements exceed standard distributor capabilities.
Flexible Pouch Market Segmentation
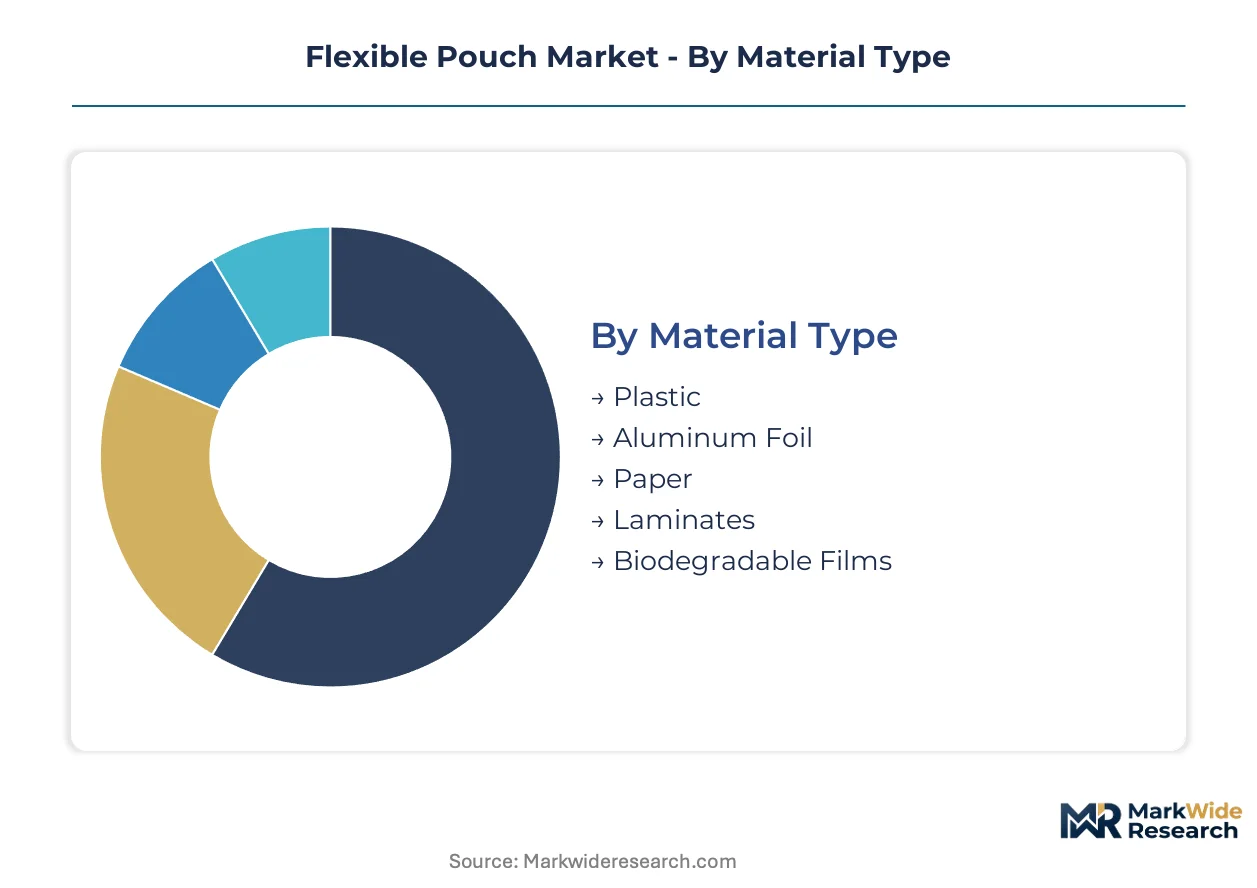
Flexible pouch segmentation reveals how material and closure choices cascade through compliance obligations, conversion economics, and sortation infrastructure. Each dimension carries distinct capital intensity and regulatory exposure that shapes procurement strategy.
Material Type:
Resin supply concentration and recycling certification requirements are fragmenting converter capabilities across substrate categories.
- Plastic:Polyethylene and polypropylene structures dominate volume through mono-material compatibility with existing mechanical recycling streams. German and Italian converters are prioritizing these for EPR compliance.
- Aluminum Foil:Multi-layer laminates incorporating aluminum oxide deliver superior oxygen barrier for retort applications. Spain's Ecoembes and Germany's DKR sorting facilities reject these structures, limiting market access without chemical recycling partnerships.
- Paper:Extrusion-coated kraft grades capture fiber-based packaging subsidies in the Netherlands and Belgium. These structures suit dry goods with moderate barrier requirements.
- Laminates:Polyamide-ethylene vinyl alcohol combinations retain dominance in shelf-stable protein where 121°C sterilization is mandatory. Four Asian petrochemical groups control over seventy percent of EVOH resin supply.
- Biodegradable Films:Polylactic acid and polyhydroxyalkanoate formulations are climbing the fastest as converters respond to extended producer responsibility frameworks and composting infrastructure investments.
Laminates absorb the bulk of installed capacity; biodegradable films are expanding most quickly.
Closure Type:
Application requirements and premium positioning drive divergence in assembly complexity and unit economics.
- Zipper:Child-resistant certification variants are penetrating cannabis edibles and pediatric OTC pharmaceuticals. These closures command premium positioning in pet products and snack packaging segments.
- Spout:Fitmented pouches for liquid coffee concentrates and fitness beverages displace rigid bottles. ECHA phthalate restrictions have forced reformulation of spout assembly plasticizers toward citrate-based alternatives.
- Heat Seal:Flat-seal formats occupy volume leadership in commodity liquid and powder applications where reclosability is non-essential.
- Adhesive Tape:Pressure-sensitive closures serve single-serve portions and sample sachets with minimal equipment investment.
- Tear Notch:Laser-scored opening features reduce material cost in dry goods and confectionery where controlled dispensing is unnecessary.
Heat seal closures capture the highest throughput volumes; spout integration is gaining share fastest in liquid concentrate applications.
End Use Industry:
Regulatory migration limits and shelf-life requirements stratify demand across compliance-intensive sectors.
- Food & Beverage:Retort-ready mono-materials are displacing polyamide laminates in ready-to-eat meals as converters chase Design for Recycling certification.
- Personal Care:Stand-up pouches for shampoos and conditioners leverage digital printing for regional variant testing without plate costs.
- Pet Products:Shelf-stable wet food drives demand for high-barrier structures with zipper reclosability. Polish and Czech producers are adopting digital inkjet for seasonal SKU fragmentation.
- Household Chemicals:Concentrated liquid detergents and disinfectants require chemical-resistant films with child-resistant closure compatibility.
- Agriculture:Fertilizer and seed treatment packaging prioritizes moisture barriers and UV stability over recyclability certification.
Food and beverage commands the largest share of converter capacity; pet products are climbing fastest on premiumization and humanization trends.
Application:
Fill-line compatibility and barrier performance requirements determine material selection and margin structure.
- Snack Packaging:Digital inkjet adoption is compressing minimum order quantities for regional flavor variants. Seasonal production in Central Europe favors short-run flexibility.
- Liquid Packaging:Fitmented pouches for concentrates face EU 10/2011 migration testing backlogs of eighteen months for new adhesive chemistries.
- Powder Packaging:Anti-static films and precise seal integrity prevent leakage in protein powders and baking mixes.
- Pharmaceutical Packaging:Unit-dose and compliance-prompting formats expand pouch adoption beyond food into regulated drug delivery with serialization requirements.
- Cosmetic Containers:Premium skincare pouches leverage metallized films and soft-touch laminates for shelf differentiation.
Snack packaging holds the broadest converter footprint; pharmaceutical applications are expanding most quickly on compliance-driven specification tightening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ethylene vinyl alcohol resin production clusters in Japan and South Korea supply barrier film converters worldwide. Converter investments track regulatory enforcement intensity across national extended producer responsibility schemes.
Germany
DKR sorting facilities reject aluminum oxide-coated pouches, stranding inventory without chemical recycling partnerships. The country's national packaging regulator enforces strict mechanical recycling contamination limits under extended producer responsibility frameworks. Converters in North Rhine-Westphalia are redeploying capital toward polyethylene-compatible mono-material lines.
France
AGEC law penalties for non-recyclable packaging direct brand procurement toward certified mono-material suppliers. The national environmental agency enforces extended producer responsibility fee restructuring that favors Design for Recycling certification. Industrial clusters around Lyon and Paris are qualifying retort-ready polyethylene structures for shelf-stable pet food applications.
Italy
CONAI fee restructuring accelerates converter migration from multi-layer laminates to certified mono-material structures. The national packaging consortium mandates recyclability documentation for market access. Converters in Emilia-Romagna are commissioning high-barrier polyethylene lines to capture EPR-compliant procurement from pan-European food brands.
United States
FDA migration limits govern food-contact laminate specifications for export-bound production. The national food and drug regulator enforces compliance documentation queues that delay new adhesive chemistry launches. Flexible packaging converters in Wisconsin and Illinois are expanding retort capacity for shelf-stable protein applications.
China
Dual carbon goals and provincial extended producer responsibility pilots reshape converter investment priorities. The national environmental regulator is tightening standards for plastic waste reduction in packaging applications. Manufacturing clusters in Jiangsu and Zhejiang provinces are scaling biodegradable film extrusion for export markets facing composting infrastructure mandates.
Flexible Pouch Market Competitive Landscape
Global majors compete with regional champions across film extrusion and conversion technology tiers. The market structure consolidates around integrated resin-to-pouch operators and specialized barrier film innovators. Three archetypes dominate: multinational converters with captive resin supply, regional specialists in mono-material certification, and equipment-integrated packaging system providers. Capacity expansion and strategic technology licensing represent the dominant competitive moves as converters race to qualify retort-ready recyclable structures.
Within the integrated multinational tier, Amcor PLC and Mondi Group exemplify geographic diversification strategies that secure resin access across multiple continents. Sealed Air Corporation occupies a position among system-integrated specialists, anchoring competitive differentiation through proprietary barrier technologies. These three entities represent distinct archetypes—global extrusion footprint, integrated paper-polymer operations, and equipment-integrated pouch systems—that structure procurement options for brand owners navigating recyclability mandates.
| Leading Market Players |
|---|
| Amcor PLC |
| Mondi Group |
| Sealed Air Corporation |
| Sonoco Products Company |
| Berry Global Inc. |
| Huhtamaki Oyj |
| ProAmpac |
| Constantia Flexibles |
| Smurfit Kappa |
| Others |
Supply & Pricing Matrix
EU Packaging and Packaging Waste Regulation recyclability mandates gate qualified supply access and premium-tier pricing for mono-material certified pouches, collapsing multi-layer laminate margins while rewarding Design for Recycling investment with procurement preference from pan-European brand owners.
Pricing Analysis
Migration testing documentation and EPR compliance certification are bundled into quoted unit costs rather than unbundled as separate line items. Three-tier pricing structure across premium, standard, and economy levels separates Design for Recycling certified mono-materials from uncertified laminates and commodity heat-seal formats. Cost compression in uncertified multi-layer structures is intensifying because Germany's DKR and Spain's Ecoembes rejection of aluminum oxide coatings strands inventory. Private-label discount grocery buyers exhibit highest price sensitivity; pharmaceutical and premium pet food brand owners demonstrate lowest sensitivity due to compliance-driven specification rigidity.
Supply Chain Analysis
Ethylene vinyl alcohol resin supply rests on Japanese and South Korean petrochemical producers, with four Asian groups controlling over seventy percent of global capacity. Polyethylene and polypropylene feedstocks draw from German and Italian polymer complexes, while extrusion coating equipment sources from Swiss and German engineering specialists. Single-source vulnerability in EVOH creates exposure to freight volatility and currency mismatch for European converters. Distribution runs through converter-direct relationships with pan-European food brands, bypassing traditional trade intermediaries as supermarket chains establish private-label specifications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU extended producer responsibility fee restructuring forces capital-constrained converters without mono-material certification capabilities toward exit.
For Market Incumbents: Extend high-barrier polyethylene extrusion capacity in France and Italy to capture AGEC and CONAI-compliant procurement from shelf-stable pet food and ready-to-eat meal brands. Acquire regional specialists holding Design for Recycling certification to compress competitor access to qualified supply. Prioritize retort-ready mono-material R&D to displace polyamide-EVOH laminates before 121°C sterilization compatibility gaps close. For New Entrants and Emerging Players: France's AGEC law opens a window for certified mono-material specialists to penetrate private-label discount grocery chains establishing direct converter auditing relationships. Target dry goods and confectionery segments in the Netherlands and Belgium where extrusion-coated kraft structures capture fiber-based packaging subsidies. Lead with digital inkjet printing capabilities to serve Polish and Czech seasonal SKU fragmentation demand with short-run flexibility. For Investors and Strategic Acquirers: Eighteen-month EU 10/2011 migration testing queues for new adhesive chemistries is the leading indicator that compliant formulation IP will command scarcity premiums. Focus acquisition screening on mid-cap converters with validated mono-material lines and existing commercial laboratory relationships. Watch for chemical recycling partnership announcements as signals of stranded inventory recovery capability.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Line Commissioning | Captures EPR-compliant procurement from German and French supermarket private-label programs. |
| Design for Recycling Certification | Unlocks AGEC and CONAI fee advantages for shelf-stable food pouch suppliers. |
| Digital Inkjet Printing Adoption | Enables Polish and Czech pet food producers to fragment SKUs without plate costs. |
| Chemical Recycling Partnership | Recovers stranded aluminum oxide-coated inventory rejected by Germany's DKR sorting facilities. |
| Retort-Ready Barrier Development | Addresses 121°C sterilization gap blocking polyethylene displacement of polyamide laminates. |
Research Methodology
Multi-period observation of converter capital deployment patterns and EPR fee restructuring impacts anchored the trend analysis, supplemented by interviews with extrusion line operators, brand owner procurement directors, commercial laboratory compliance managers, and supermarket private-label specification auditors. Secondary validation drew from EU Packaging and Packaging Waste Regulation implementation documents, ECHA substance-of-very-high-concern listings, national packaging consortium fee schedules, and customs data on EVOH resin trade flows. Bottom-up capacity modeling and top-down demand segmentation were triangulated to ground projections.
Input-output matrices mapped resin supply concentration against converter certification status across material type, closure complexity, end-use regulatory intensity, and geographic enforcement variation. Modeled dimensions spanned substrate category, sterilization requirement tier, and national EPR framework maturity. CAGRs were derived from segment-level volume build-ups validated against aggregate demand elasticity estimates. Forecast inputs included mono-material line commissioning timelines and commercial laboratory testing queue durations.
Caveats apply where EVOH supply disruption, accelerated ECHA substance restrictions, or chemical recycling infrastructure delays could materially shift the outlook. Forecasts embed assumptions regarding regulatory enforcement consistency and sortation facility technology adoption. A small set of named triggers—EVOH price spikes, migration testing backlog extensions, and DKR rejection threshold changes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pouch
Benelux Pouch Packaging Market
Pouch
Retort Pouch Packaging Market
Pouch
Colombia Pouch Packaging Market
Pouch
Ziplock Products Market
Pouch
Canada Pouch Packaging Market
Pouch
OPP Pouches Market
Pouch
Nigeria Pouch Packaging Market
Pouch
Clear Pouches Market
Pouch
Spouted Pouches Market
Pouch
MAP Flow Wrappers Market
Pouch
Mexico Pouch Packaging Market
Pouch
Doyen Style Pouches Market
Pouch
Middle East and Africa Pouch Packaging Market
Pouch
United States Pouch Packaging Market
Pouch
2 Seal Pouches Market
Pouch
Morocco Pouch Packaging Market