
 Pharmacy Repackaging Systems Market | 2026-2036
Pharmacy Repackaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmacy Repackaging Systems Market Outlook
ISO 15378 certification for primary packaging materials is unwinding competitive access across the pharmacy repackaging systems landscape, filtering out suppliers lacking validated quality management systems. Omnicell Inc. leverages its installed base of automated dispensing cabinets to extend into adjacent repackaging workflows. ARxIUM anchors its position through in-house production of robotic vial-filling and pouch-packaging modules. Yuyama Co. Ltd. competes on compact footprint designs tailored to Asian hospital pharmacy layouts.
Pharmacy repackaging systems comprise electromechanical equipment that sorts, counts, packages, and labels oral solid and liquid medications into patient-specific or unit-dose formats, typically operating at throughputs of 60 to 400 doses per minute depending on automation tier. Their primary purpose is to replace manual medication preparation in institutional settings, reducing cross-contamination risk and enabling barcode-verified traceability from stock bottle to patient bedside. Automated systems dominate capital expenditure budgets due to labor substitution economics and error-rate reduction, while software integration represents the fastest-growing technology dimension as health systems demand interoperability with electronic health records. Compliance packaging applications command premium pricing relative to standard prescription repackaging because of the additional adherence-monitoring features and child-resistant requirements.
The US FDA enforces current Good Manufacturing Practice standards for repackaging operations, while the EU MDR imposes traceability obligations on devices incorporated into packaging lines. HIPAA in the United States and GDPR in Europe constrain how patient-specific data flows through connected repackaging software, creating compliance costs that favor established vendors with dedicated regulatory affairs functions. Stakeholders must weigh the pace of robotics cost decline against the stickiness of incumbent manual-system relationships when allocating R&D and sales resources.
Market Dynamics
Health system consolidation across the United States is concentrating purchasing power into fewer centralized pharmacy operations, forcing equipment vendors to reconfigure service models around multi-site enterprise contracts rather than single-facility transactions.
Growth Catalysts
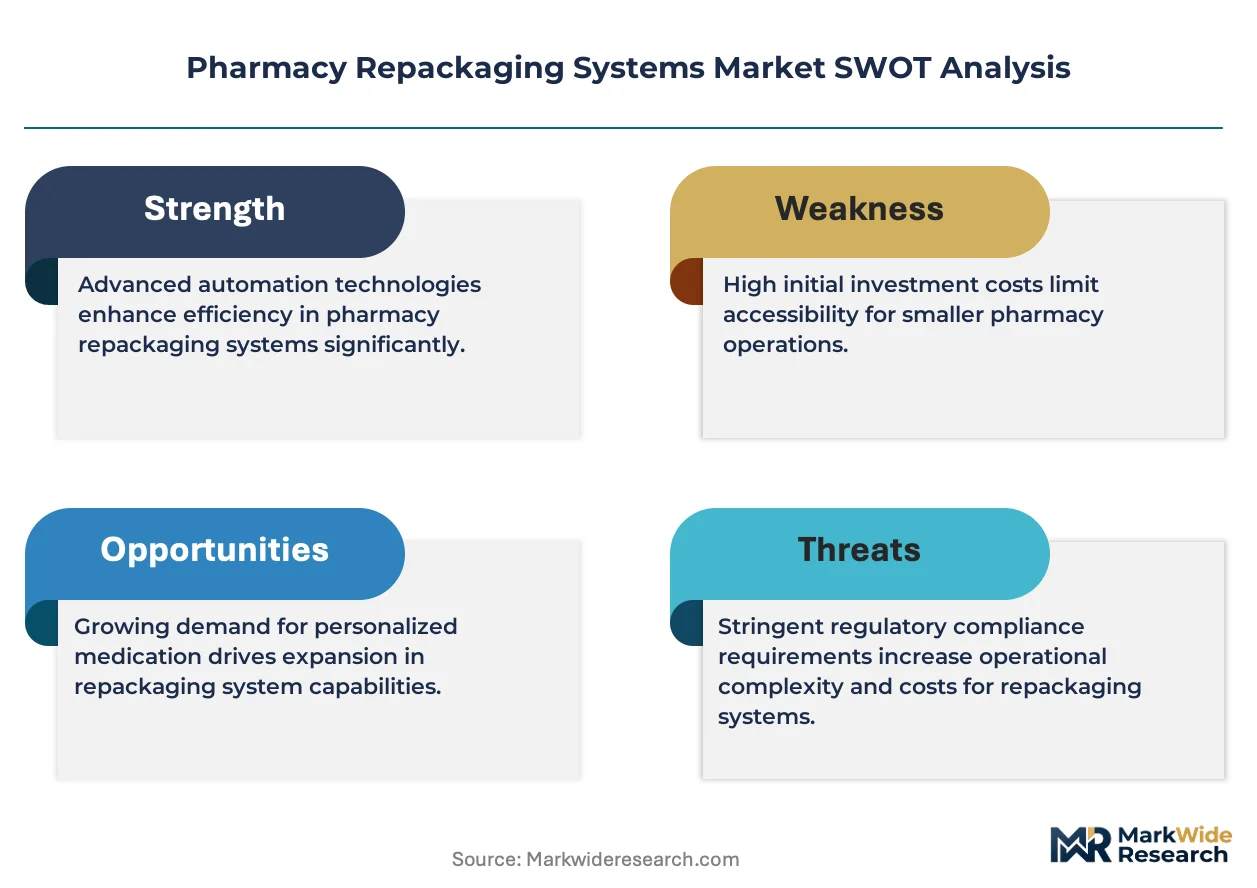
- FDA unit-dose packaging mandates:Institutional settings must comply with barcode-verified medication administration requirements, compelling hospitals to automate repackaging workflows.
- Robotics cost decline:Falling sensor and actuator prices enable mid-sized hospital pharmacies to justify capital expenditure on automated counting and packaging lines previously reserved for academic medical centers.
- Labor substitution economics:Pharmacy technician wage inflation in the United States and Western Europe accelerates payback calculations for electromechanical systems operating at 200-plus doses per minute.
Market Restraints
- Stainless steel and electronic component volatility:Input cost swings for pharmaceutical-grade alloys and precision motors compress margin visibility for equipment manufacturers.
- ISO 15378 certification barriers:Primary packaging material suppliers lacking validated quality management systems face exclusion from institutional procurement shortlists.
- Manual repackaging stickiness:Long-standing relationships between hospital pharmacies and compound pharmacies create switching friction despite automation advantages.
Strategic Opportunities
- Compliance packaging expansion:Adherence-monitoring features and child-resistant specifications command premium pricing in retail pharmacy and long-term care segments.
- Software interoperability convergence:Electronic health record integration and barcode traceability systems create recurring revenue streams beyond hardware sales.
- Asian hospital pharmacy layouts:Compact footprint designs address space constraints in Japan, South Korea, and Singapore facilities where square footage carries extreme opportunity cost.
Industry Challenges
- Pharmacy informatics specialist scarcity:Health systems struggle to hire personnel capable of bridging clinical workflow knowledge with electromechanical system configuration.
- Legacy automated dispensing cabinet integration:Repackaging lines must communicate with incumbent medication storage infrastructure without disrupting established verification protocols.
- EU MDR traceability compliance timelines:Device manufacturers face compressed certification windows for packaging line components classified as medical devices under European regulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmacy Repackaging Systems Market |
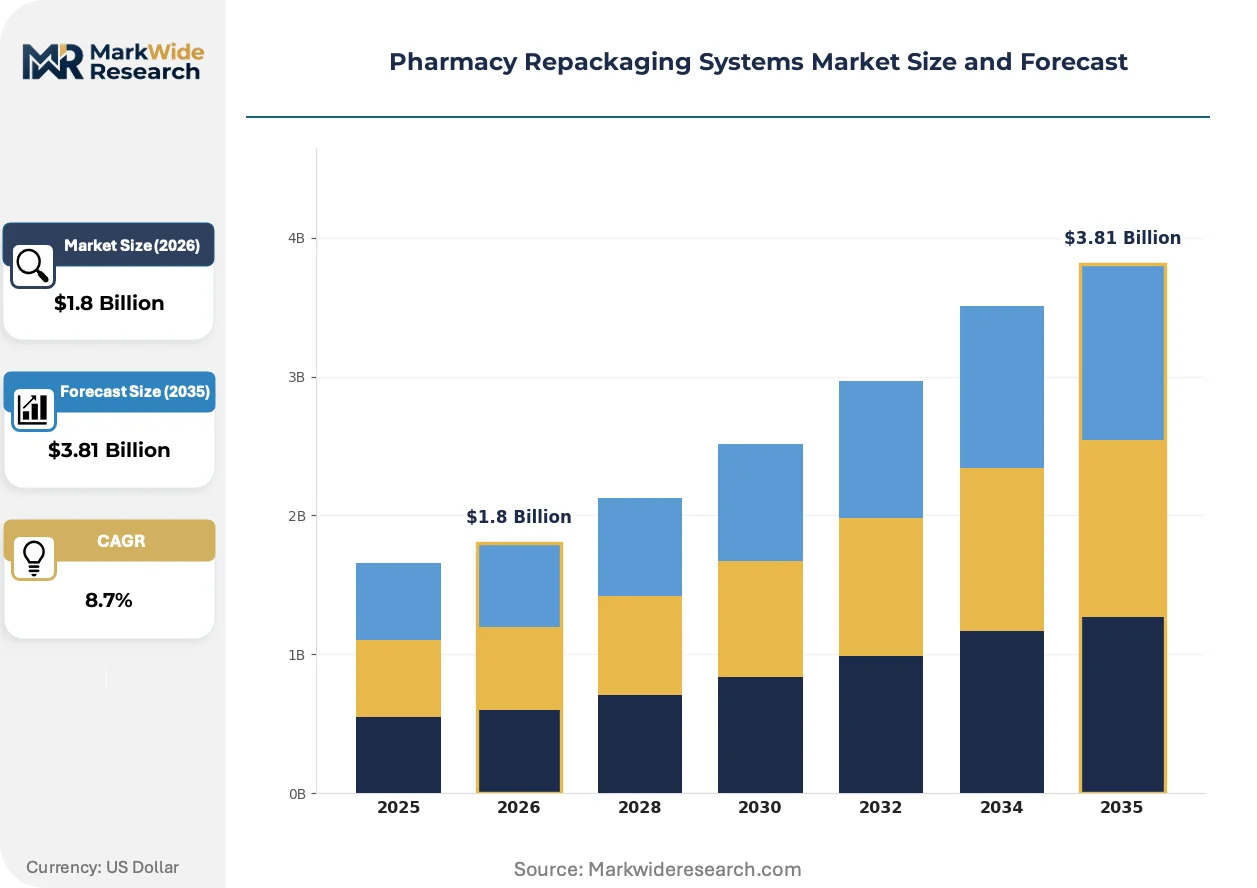
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Systems, Manual Systems, Semi-Automated Systems, Labeling Machines End User: Hospitals, Pharmacies, Long-Term Care Facilities, Home Healthcare Technology: Robotics, Barcode Scanning, RFID Technology, Software Integration Application: Prescription Repackaging, Unit Dose Packaging, Compliance Packaging, Hazardous Drug Handling |
| Companies Covered | Swisslog Holding Ltd., TCGRx, Omnicell Inc., Yuyama Co. Ltd., ARxIUM, McKesson Corporation, Parata Systems, Kirby Lester, Becton Dickinson And Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmacy Repackaging Systems Market Strategic Shifts
Electromechanical packaging equipment is converging with cloud-native software architectures, enabling real-time production monitoring and predictive maintenance that reshapes how hospital pharmacies justify capital investments.
Robotic pouch-packaging modules are miniaturizing. These systems consolidate counting, packaging, and labeling into single-footprint units designed for satellite pharmacy locations. Community hospital networks in the United States Midwest are deploying these compact lines at one-third the floor space of traditional configurations. Equipment footprint compression is miniaturizing the minimum viable pharmacy layout, allowing health systems to redistribute medication preparation closer to patient care areas.
EU MDR traceability obligations are tightening documentation requirements for devices incorporated into packaging lines. Manufacturers must now maintain unique device identification across robotic components and software modules. European hospital pharmacies face extended procurement cycles as vendors recertify existing product portfolios, with German and French health systems experiencing the most pronounced approval delays.
Consolidated purchasing by multi-hospital systems is compressing vendor sales cycles and expanding request-for-proposal scope. Single contracts now cover enterprise-wide standardization across dozens of facilities. United States health system aggregators in Texas and Florida are demanding unified equipment platforms with centralized software licensing, displacing the historical pattern of site-by-site procurement autonomy.
Pharmacy Repackaging Systems Market Segmentation
Pharmacy repackaging systems fragment across four distinct dimensions that reshape competitive positioning. Product type and technology tiers determine capital intensity and payback periods, while end-user concentration and application specifications dictate feature bundling and service attach rates.
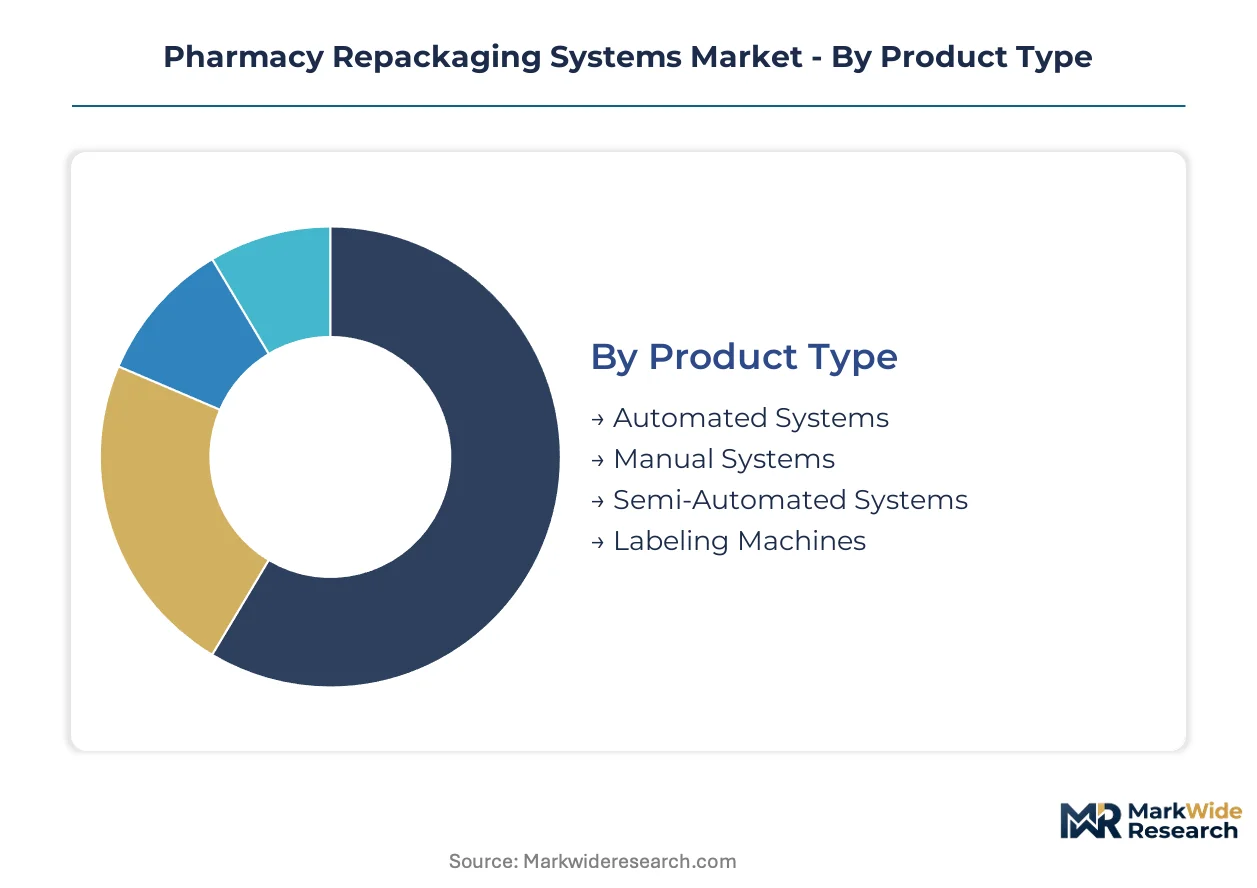
Product Type:
Manual systems face the most acute substitution pressure as labor economics and error-rate accountability erode their historical installed base.
- Automated Systems:Electromechanical lines integrate counting, packaging, and barcode verification at throughputs exceeding 200 doses per minute. Hospital pharmacies in the United States concentrate procurement here as health system consolidation centralizes medication preparation into fewer high-volume facilities.
- Manual Systems:Benchtop equipment requiring pharmacy technician operation for counting and pouch-sealing persists in small community hospitals and resource-constrained international markets. Regulatory tolerance for manual repackaging is narrowing under FDA unit-dose mandates and EU MDR traceability requirements.
- Semi-Automated Systems:Hybrid configurations automate counting while retaining manual verification steps.
- Labeling Machines:Standalone barcode and patient-specific label applicators serve retrofit installations and satellite pharmacy expansions.
Automated Systems retain volume leadership; Semi-Automated Systems hold the steepest expansion curve as mid-sized facilities bridge cost and capability gaps.
End User:
Customer type stratification follows care delivery centralization, with acute care settings commanding premium specifications.
- Hospitals:Inpatient pharmacies drive demand for high-throughput lines with EHR interoperability and robotic pouch-packaging modules. German and French health systems are extending procurement cycles as vendors recertify portfolios under EU MDR timelines.
- Pharmacies:Retail and outpatient settings prioritize compact footprint designs and compliance packaging capabilities for medication adherence programs.
- Long-Term Care Facilities:Skilled nursing and assisted living operations seek simplified interfaces for non-specialist staff.
- Home Healthcare:Patient-directed medication management creates demand for portable, low-volume repackaging solutions.
Hospitals dominate absolute equipment value; Home Healthcare is climbing the fastest as post-acute care decentralization accelerates.
Technology:
Software and sensing layers are displacing pure electromechanical differentiation as health systems prioritize data integration over hardware throughput alone.
- Robotics:Articulated arms and Cartesian gantries handle vial-filling, pouch-sealing, and sortation with precision motor control. Japanese hospital pharmacies favor compact robotic modules from domestic suppliers optimized for constrained floor plans.
- Barcode Scanning:Linear and 2D imagers enable medication verification from stock bottle to patient bedside. FDA barcode-verified medication administration requirements make this capability non-negotiable in United States institutional procurement.
- RFID Technology:Item-level tagging supports inventory tracking and automated replenishment.
- Software Integration:Cloud-native architectures connect repackaging lines to electronic health records and enterprise resource planning systems.
Barcode Scanning retains universal deployment; Software Integration is gaining share fastest as recurring revenue models displace pure hardware transactions.
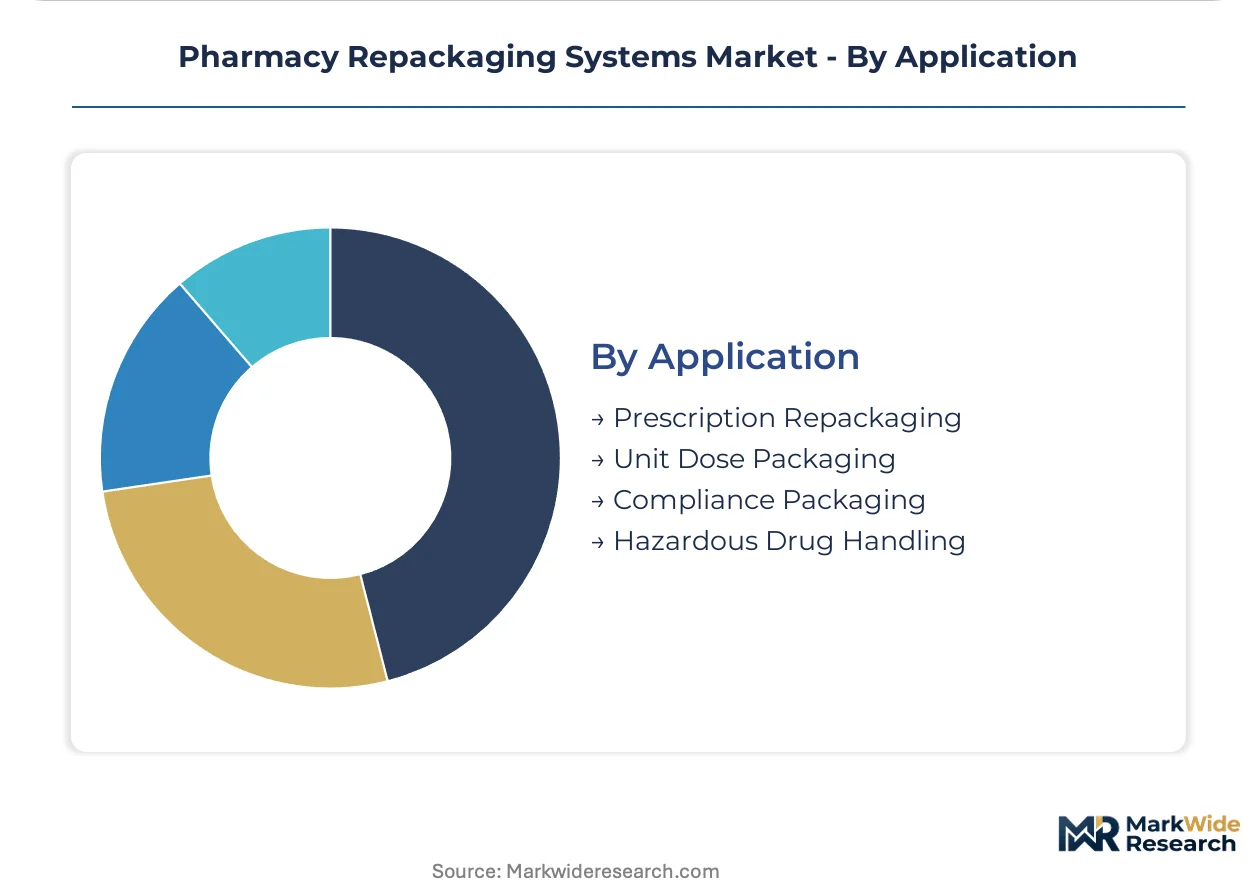
Application:
Regulatory complexity and liability exposure create tiered pricing power across use cases.
- Prescription Repackaging:Standard oral solid and liquid medication preparation for outpatient dispensing. Community hospital networks in the United States Midwest deploy compact lines at reduced floor space to redistribute preparation closer to patient care areas.
- Unit Dose Packaging:Patient-specific or time-specific single-unit formats for inpatient administration. HIPAA constraints on patient data flows through connected software favor established vendors with dedicated compliance infrastructure.
- Compliance Packaging:Adherence-monitoring formats with child-resistant specifications and calendarized blister designs.
- Hazardous Drug Handling:Containment engineering for cytotoxic and antineoplastic agents requiring negative pressure and closed-system transfer devices.
Prescription Repackaging holds installed base dominance; Compliance Packaging commands the steepest margin expansion as retail pharmacies monetize adherence services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital pharmacy buyers concentrate procurement authority into fewer centralized operations, with multi-site health system contracts displacing single-facility transactions across major markets.
United States
Health system consolidation in Texas and Florida drives enterprise-wide equipment standardization across dozens of facilities. FDA unit-dose packaging mandates for institutional settings compel barcode-verified medication administration compliance. The Midwest community hospital networks deploy compact robotic pouch-packaging modules at reduced floor space to redistribute preparation closer to patient care areas.
Germany
Academic medical centers anchor demand for high-throughput lines with EHR interoperability and robotic vial-filling modules. EU MDR traceability obligations compress certification windows for packaging line components classified as medical devices. The Rhine-Ruhr industrial corridor experiences pronounced procurement cycle extensions as vendors recertify existing product portfolios.
Japan
Domestic hospital pharmacies favor compact robotic modules optimized for constrained floor plans in aging urban facilities. METI industrial standards shape equipment specifications for pharmaceutical-grade automation. The Kanto region around Tokyo concentrates deployment of miniaturized pouch-packaging systems designed for satellite pharmacy locations.
United Kingdom
NHS trust consolidation centralizes medication preparation into fewer high-volume pharmacy operations. GDPR constraints on patient-specific data flows through connected software favor established vendors with dedicated compliance infrastructure. The Greater London health economy leads adoption of cloud-native software architectures enabling real-time production monitoring.
South Korea
Hospital pharmacy automation accelerates as health system digitization programs expand beyond Seoul. MFDS medical device regulations impose documentation requirements on robotic components integrated into packaging lines. The Busan-Ulsan manufacturing belt supplies precision motors and sensor arrays to regional equipment integrators.
Pharmacy Repackaging Systems Market Competitive Environment
Player mix skews toward diversified automation conglomerates with adjacent healthcare portfolios, creating tiered competition between full-line integrators and specialized pharmacy equipment fabricators. Market structure concentrates around vendors with validated quality management systems for ISO 15378 certification compliance. Three archetypes dominate: integrated medication management platform providers, standalone repackaging equipment specialists, and healthcare distribution conglomerates with captive automation divisions. Competitive moves center on strategic partnerships for software interoperability and geographic expansion through multi-hospital system enterprise contracts.
Among North American platform providers, Omnicell Inc. and ARxIUM exemplify the integrated-systems archetype, leveraging installed bases of automated dispensing infrastructure to extend into adjacent repackaging workflows. Japanese specialist Yuyama Co. Ltd. occupies a position within the compact-footprint tier, addressing space-constrained Asian hospital pharmacy layouts. Swisslog Holding Ltd. represents the European automation conglomerate model, drawing on broader logistics and robotics competencies to serve institutional pharmacy markets.
| Leading Market Players |
|---|
| Swisslog Holding Ltd. |
| TCGRx |
| Omnicell Inc. |
| Yuyama Co. Ltd. |
| ARxIUM |
| McKesson Corporation |
| Parata Systems |
| Kirby Lester |
| Becton Dickinson And Company |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day lead times for pharmaceutical-grade stainless steel and precision servo motors concentrate pricing power with Japanese and German component suppliers, forcing equipment manufacturers to absorb volatility or pass through via indexation clauses in multi-year hospital contracts.
Pricing Analysis
Cost-plus contracts with stainless steel and rare-earth magnet indexation dominate capital equipment transactions, though software subscriptions now anchor recurring revenue streams. Price differentiation hinges on ISO 15378 certification tier and EHR interoperability depth, with uncertified vendors facing exclusion from institutional shortlists. Cost compression in mid-tier automated systems is intensifying because robotics component costs are declining faster than system pricing, squeezing integrator margins. Community hospital networks exhibit highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize throughput specifications over unit economics.
Supply Chain Analysis
Strategic stockpiling of precision motors and sensor arrays has displaced just-in-time preferences as lead-time volatility from East Asian suppliers disrupts production schedules. Manufacturing concentration in Japan, Germany, and the United States feeds the global installed base, with the Busan-Ulsan corridor supplying critical electromechanical subassemblies. Supply chain risk centers on single-source dependency for pharmaceutical-grade alloys subject to export licensing delays. Distribution runs through regional equipment integrators and direct enterprise contracts with consolidated health systems, bypassing traditional medical device distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across automation tiers creates entry niches as mid-sized hospital pharmacies bridge manual workflows and full robotic lines, demanding configurable semi-automated platforms.
For Market Incumbents: Secure ISO 15378 certification lock-in by embedding quality management audits into enterprise service contracts, insulating against emerging Asian suppliers lacking validated documentation. Expand captive production of robotic pouch-packaging modules to defend margin position against component cost volatility from Japanese motor suppliers. For New Entrants and Emerging Players: Differentiate on compact footprint designs targeting satellite pharmacy deployments in United States community hospital networks, where space constraints and capital limitations exclude full-line vendors. Penetrate the long-term care segment through simplified interfaces and adherence-monitoring bundling, leveraging lower regulatory barriers than acute care settings. For Investors and Strategic Acquirers: Carve-out targets emerge from healthcare distribution conglomerates with captive automation divisions seeking portfolio rationalization, particularly European players facing EU MDR recertification cost burdens. Monitor FDA enforcement patterns on unit-dose barcode verification as an inflection signal; accelerated citation rates would compress sales cycles for compliant vendors and strand non-compliant installed bases.| Strategic Initiative | Industry Significance |
|---|---|
| Software Interoperability Partnership | EHR integration with Epic and Cerner platforms secures hospital procurement preference. |
| EU MDR Recertification Acceleration | Expedited CE marking for robotic components prevents German and French procurement delays. |
| Compact Footprint Product Line | Miniaturized pouch-packaging modules penetrate Asian hospital pharmacy space constraints. |
| ISO 15378 Certification Investment | Validated quality management systems unlock institutional procurement shortlists. |
| Enterprise Service Contract Expansion | Multi-site health system agreements in Texas and Florida displace site-by-site sales. |
Study Parameters
Operator-level perspectives from hospital pharmacy directors, biomedical equipment technicians, GPO contracts managers, and regulatory affairs specialists anchored the qualitative base, cross-referenced with FDA 483 inspection observations, EU MDR notified body guidance documents, and health system capital expenditure disclosures. Bottom-up equipment shipment tallies triangulated against top-down health system automation budget allocations.
Sensitivity analysis tested forecast robustness across robotics cost decline trajectories and health system consolidation scenarios over the projection horizon. Segmentation modeling spanned automation tier, end-user facility type, technology layer, and application specification, with CAGRs derived from equipment replacement cycle analysis and penetration rate assumptions for software-enabled recurring revenue streams. Input assumptions incorporated pharmacy technician wage inflation elasticities and FDA enforcement intensity indices.
Decision-makers should treat outputs as directional under stable regulatory enforcement and consolidated purchasing trajectories; material deviation would warrant model refresh. Revision becomes warranted when EU MDR certification delays or health system merger activity crosses thresholds that disrupt historical procurement patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Pharmaceutical Packaging Market
Pharmaceutical Packaging
Asia-Pacific Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Glass Packaging Market
Pharmaceutical Packaging
Injectable Drug Packaging Market
Pharmaceutical Packaging
Vial Box Market
Pharmaceutical Packaging
Reefer Container for Pharmaceutical Market
Pharmaceutical Packaging
Pharmaceutical Unit Dose Packaging Market
Pharmaceutical Packaging
Vaccine Shippers Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Materials Market
Pharmaceutical Packaging
Europe Glass Prefilled Syringes and Glass Vials Packaging Equipment Market
Pharmaceutical Packaging
Global Parenteral Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Packaging Market
Pharmaceutical Packaging
Middle East and Africa Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Europe Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Pharmaceuticals Pouch Market