
 Vaccine Packaging Market | 2026-2036
Vaccine Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Vaccine Packaging Market Outlook
Biologics manufacturing is pivoting toward single-use, ready-to-fill formats that cut compounding risk and cold-chain footprint. Gerresheimer leverages borosilicate glass expertise to dominate high-value mRNA and viral vector containment. Schott sustains technology leadership through strengthened glass innovations that reduce breakage in ultra-cold distribution. Stevanato Group anchors its position with integrated containment and delivery systems spanning vials, syringes, and auto-injector platforms.
Vaccine packaging comprises sterile containers, closures, and delivery systems engineered to maintain potency, prevent contamination, and enable precise dosing across temperature-controlled supply chains. Glass vials remain the structural default for parenteral vaccines, though polymer alternatives are gaining traction where impact resistance and design flexibility matter. Pre-filled syringes command premium positioning by eliminating fill-step contamination risk and enabling point-of-care efficiency. Secondary packaging carries growing margin weight as track-and-trace mandates and patient-centric design reshape carton and labeling specifications.
The FDA, EMA, and WHO collectively set the regulatory perimeter through container closure integrity, sterility assurance, and distribution stability requirements that dictate material selection and validation burden. India's CDSCO and China's NMPA are tightening local labeling and serialization rules, forcing multinationals to run parallel packaging configurations. Stakeholders must monitor how polymer-to-glass substitution economics evolve against tightening extractables standards and shifting temperature-profile demands from next-generation platforms.
Market Dynamics
Biologics pipelines are tilting toward temperature-sensitive modalities that force packaging formats to accommodate ultra-cold distribution without compromising container closure integrity. This structural pivot is compressing development timelines and amplifying material qualification burdens across the supply base.
Growth Catalysts
- mRNA Platform Expansion:Viral vector and nucleic acid therapies require specialized containment that resists thermal stress across cryogenic transport lanes. Contract manufacturers are scaling dedicated filling lines to capture this demand.
- CDSCO Serialization Mandates:India's tightened track-and-trace rules for export-bound vaccines are accelerating investment in integrated labeling and aggregation systems at domestic packaging sites.
- Pre-filled Syringe Conversion:Health systems are prioritizing ready-to-administer formats that reduce dosing errors and cold-chain footprint in mass immunization campaigns.
Market Restraints
- Borosilicate Glass Supply Concentration:Three European and Asian suppliers control premium tubing supply for Type I glass vials, creating vulnerability during demand surges or geopolitical friction.
- Extractables Testing Burden:FDA's updated container closure guidance extends validation timelines and requires toxicological assessment of novel polymer formulations.
- Cycloolefin Polymer Cost Structure:COP resin prices track petrochemical feedstock volatility, compressing margins for mid-tier syringe manufacturers competing against established glass alternatives.
Strategic Opportunities
- Indonesia Domestic Manufacturing:Southeast Asia's largest vaccine market is localizing fill-finish capacity under government incentive schemes, creating demand for regional packaging suppliers.
- Dual-Chamber Cartridge Convergence:Lyophilized drug and diluent integration in single containers addresses stability challenges for complex biologics requiring reconstitution at point of care.
- WHO Prequalification Pathway:Accelerated regulatory recognition for packaging components used in UN procurement programs opens volume contracts for qualified suppliers.
Industry Challenges
- Container Closure Integrity Validation:Demonstrating seal performance across temperature excursions demands specialized equipment and expertise that smaller converters struggle to acquire.
- Legacy Glass-to-Polymer Line Conversion:Retooling established aseptic filling infrastructure for polymer syringes or vials requires capital outlay and process revalidation that extends time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vaccine Packaging Market |
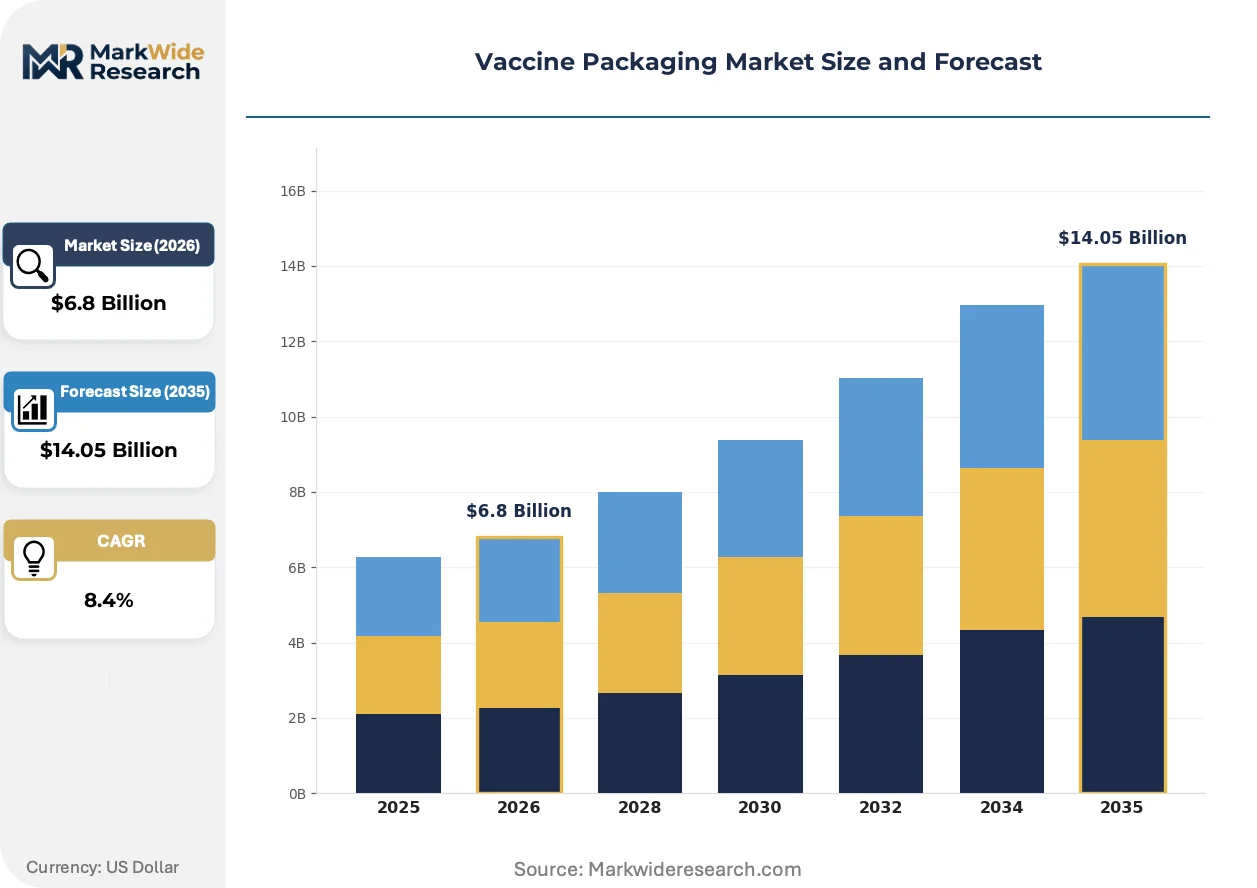
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ampoules, Vials, Pre-filled Syringes, Cartridges Material: Glass, Plastic, Aluminum, Ethylene Vinyl Acetate Packaging Type: Primary Packaging, Secondary Packaging, Tertiary Packaging, Blister Packs Distribution Channel: Pharmacies, Hospitals, Online Retailers, Clinics |
| Companies Covered | Gerresheimer, Schott, Stevanato Group, West Pharmaceutical Services, Amcor, Aptar Group, Nipro, Corning, SGD Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vaccine Packaging Market Strategic Shifts
Packaging innovation is converging on modular systems that integrate primary containment, delivery mechanism, and digital traceability in single product architectures. This integration is compressing the traditional supplier tier structure and elevating contract development organizations that can coordinate across material, device, and data layers.
Cycloolefin polymer is expanding into viral vector and mRNA applications where glass breakage risk and protein adsorption create unacceptable loss rates. Gene therapy developers are specifying COP vials and syringes for clinical and commercial supply. This shift is expanding into high-value biologics that previously defaulted to borosilicate glass, compressing the addressable market for traditional Type I tubing suppliers.
EMA's updated guidelines on extractables and leachables for plastic primary packaging materials are forcing polymer converters to expand toxicological data packages. The industrial consequence is extended development timelines and elevated qualification costs for novel materials. Small-molecule vaccine applications in Europe are most affected, with sponsors delaying polymer adoption until supplier data packages mature.
Health system procurement is consolidating around integrated suppliers capable of delivering validated containment, device, and serialization as bundled contracts. This behavior is displacing component-level sourcing that previously allowed mix-and-match flexibility. The shift is most visible in United States hospital network purchasing, where pharmacy directors prioritize reduced vendor management overhead over unit cost optimization.
Vaccine Packaging Market Segmentation
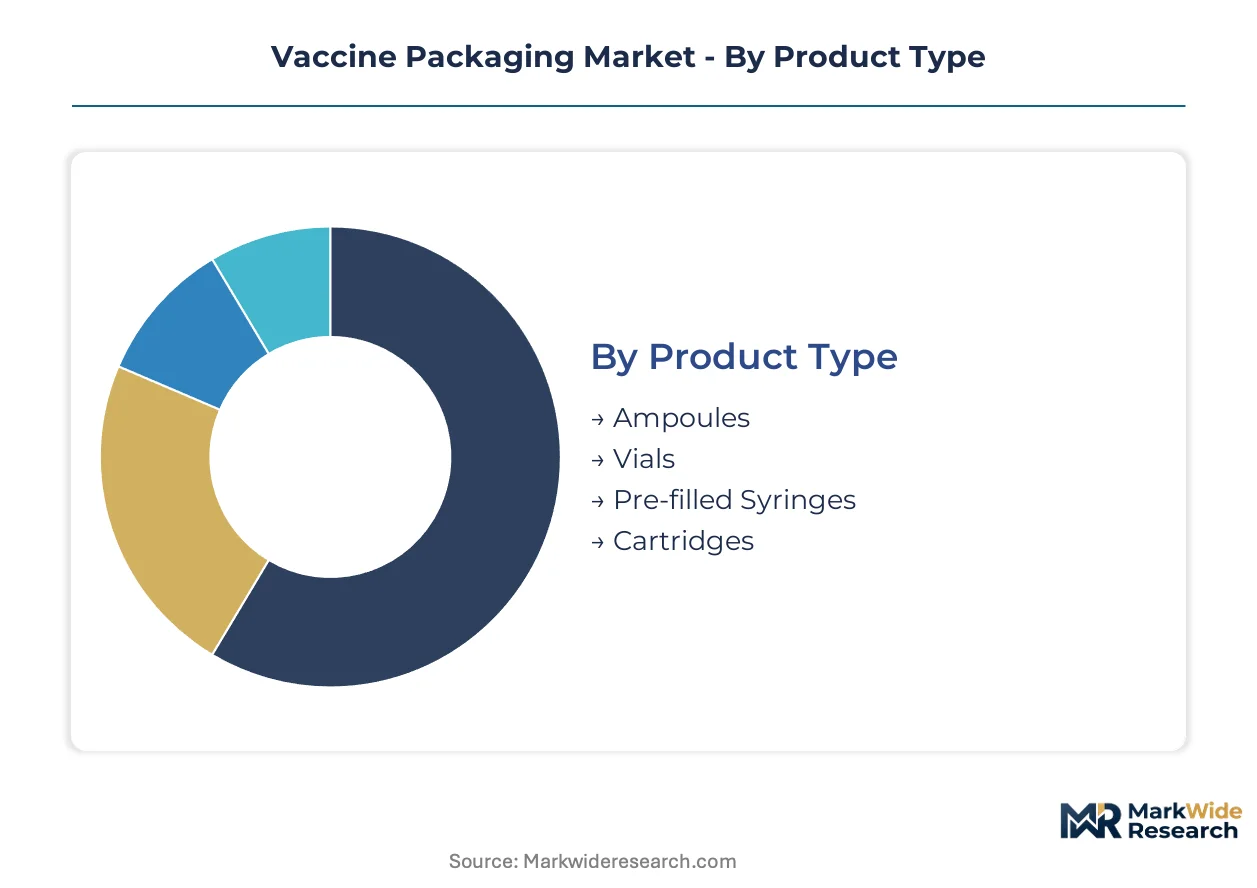
Packaging format selection dictates cold-chain performance, regulatory pathway, and total cost of ownership across vaccine development and commercialization. Material and design specifications must align with thermal stability requirements, extractables profiles, and point-of-care delivery workflows. Each segmentation axis carries distinct qualification burdens and margin structures that reshape supplier competitive position.
Product Type:
Technology leadership concentrates in formats that minimize contamination risk and enable precise dosing in mass immunization settings.
- Vials:Borosilicate glass vials remain the containment default for parenteral vaccines, with Type I tubing specified for alkaline-sensitive biologics. India's domestic manufacturers are scaling vial conversion capacity to meet export commitments under CDSCO serialization mandates.
- Pre-filled Syringes:Ready-to-administer formats eliminate compounding steps and reduce cold-chain footprint through optimized volume design. Health systems in the United States and Western Europe are prioritizing these formats for pharmacy efficiency and dosing accuracy.
- Ampoules:Single-dose glass containers serve cost-sensitive vaccine categories where breakage rates are manageable and cold-chain infrastructure is limited.
- Cartridges:Dual-chamber designs integrate lyophilized drug and diluent for complex biologics requiring reconstitution at point of care.
Vials lead on scale; pre-filled syringes lead on momentum.
Material:
Cost tier and performance specifications segment the supply base across temperature resilience and extractables compliance.
- Glass:Type I borosilicate tubing dominates high-value mRNA and viral vector applications where inertness and thermal shock resistance are non-negotiable. Supply concentrates among European and Asian tubing manufacturers, creating vulnerability during demand surges.
- Plastic:Cycloolefin polymer is expanding into cryogenic distribution lanes where glass breakage and protein adsorption create unacceptable loss rates. EMA extractables guidelines are extending qualification timelines for novel polymer formulations.
- Aluminum:Multi-dose vial seals and crimp closures provide tamper-evidence and container closure integrity across glass primary packaging formats.
- Ethylene Vinyl Acetate:Flexible components serve specialized closure and seal applications where compression set and low-temperature performance are critical.
Glass commands premium positioning; plastic is gaining share fastest.
Packaging Type:
Margin distribution follows the hierarchy from sterile containment through traceable distribution infrastructure.
- Primary Packaging:Direct drug-contact containers and closures carry the highest qualification burden and regulatory scrutiny. FDA container closure integrity requirements and WHO prequalification pathways dictate material selection and validation scope.
- Secondary Packaging:Cartons, labels, and inserts are absorbing investment as track-and-trace mandates reshape serialization and aggregation requirements. India's CDSCO rules for export-bound vaccines are accelerating integrated labeling system deployment.
- Tertiary Packaging:Shippers and thermal containers enable ultra-cold distribution for mRNA platforms, with reusable systems gaining traction for sustainability compliance.
- Blister Packs:Oral vaccine formulations and ancillary delivery components utilize barrier films for moisture and oxygen protection.
Primary packaging leads on margin; secondary packaging leads on regulatory-driven investment.
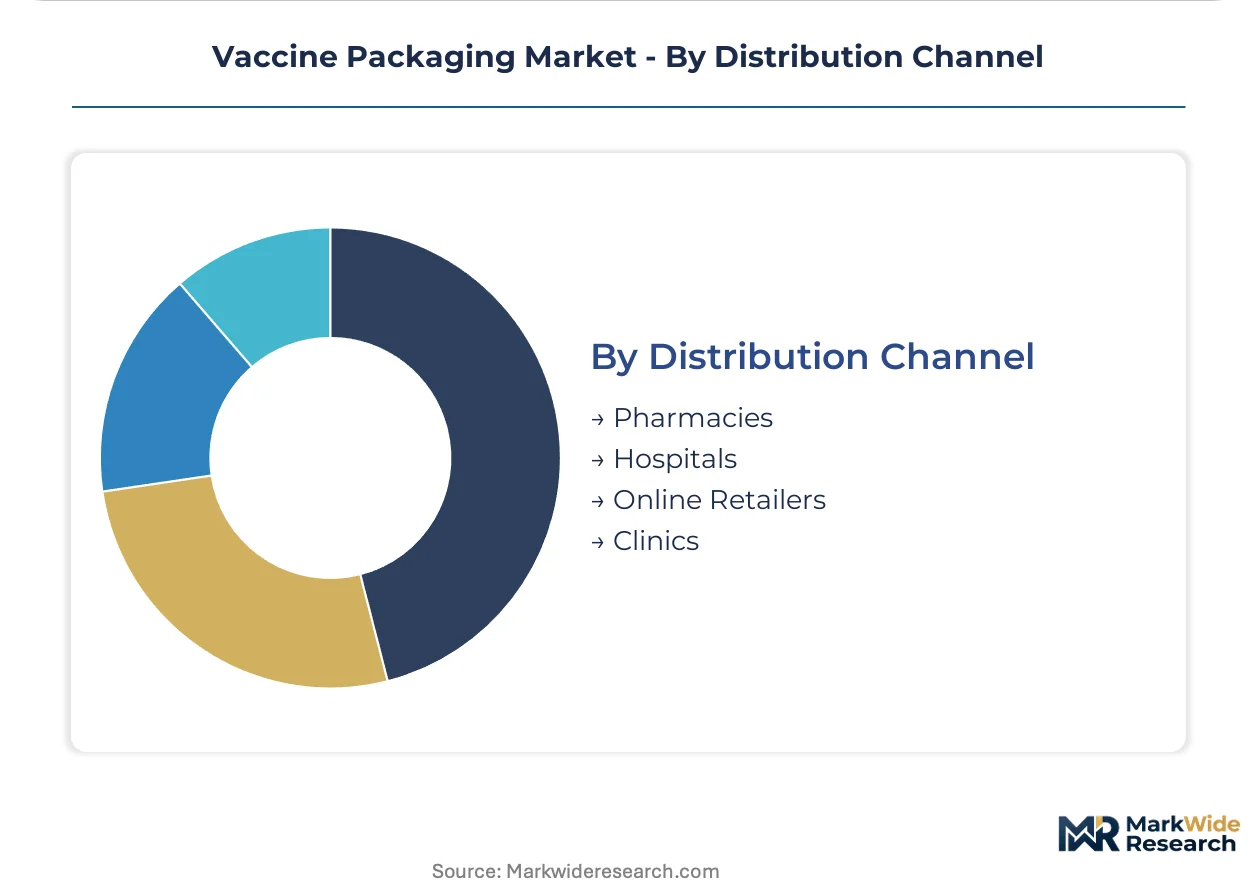
Distribution Channel:
Customer type and procurement concentration determine format specifications and supplier relationship structures.
- Hospitals:Integrated health networks are consolidating procurement around bundled contracts spanning containment, device, and serialization. United States pharmacy directors prioritize reduced vendor management overhead over unit cost optimization.
- Clinics:Point-of-care settings drive demand for pre-filled formats that minimize preparation time and training requirements.
- Pharmacies:Retail channels emphasize patient-centric design and adherence packaging for adult and pediatric vaccine schedules.
- Online Retailers:Direct-to-patient distribution channels are emerging for travel vaccines and booster programs, requiring specialized cold-chain last-mile solutions.
Hospitals lead on contract value; clinics lead on format innovation pull.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping vaccine packaging production geography as manufacturers migrate toward jurisdictions offering streamlined qualification pathways and lower cost-of-compliance structures. Cost differentials in extractables testing and serialization infrastructure are accelerating facility investment in South and Southeast Asia.
United States
FDA container closure integrity guidance and serialized track-and-trace mandates drive packaging specification complexity. The 2023 DSCSA stabilization deadline forced wholesale distributors to upgrade aggregation systems. Greater Boston's biotech cluster concentrates demand for cryogenic-ready containment formats serving mRNA developers.
Germany
EMA extractables protocols and MDR device regulations elevate qualification burdens for polymer converters. REACH chemical compliance extends material documentation requirements across glass and plastic supply chains. Bavaria's precision glass tubing corridor anchors European supply for Type I borosilicate vials.
India
CDSCO serialization mandates for export-bound vaccines and PLI scheme incentives for domestic manufacturing accelerate packaging infrastructure buildout. DGFT traceability rules compress implementation timelines for integrated labeling systems. Hyderabad and Pune clusters are scaling fill-finish capacity for COVAX and bilateral supply commitments.
China
NMPA tightened labeling standards and dual carbon goals reshape material selection and energy-intensive glass production economics. GB standards alignment with ICH Q3D drives elemental impurity testing expansion. Yangtze River Delta pharmaceutical manufacturing zones are localizing polymer syringe conversion capacity.
Indonesia
Domestic vaccine manufacturing incentives under national health sovereignty programs create demand for regional packaging suppliers. Ministry of Health localization requirements favor in-country fill-finish partnerships. Jakarta-Bandung corridor is emerging as a Southeast Asian packaging hub serving ASEAN distribution networks.
Vaccine Packaging Market Competitive Environment
Capacity expansion dominates the current landscape as incumbent suppliers race to install cold-chain-ready production lines before biologics pipeline maturation peaks. Market structure concentrates around three European tubing specialists controlling premium borosilicate supply, with mid-tier polymer converters filling specialty niches. Strategic archetypes separate into integrated containment-device suppliers, pure-play primary packaging specialists, and diversified materials conglomerates. M&A activity and geographic licensing partnerships represent the dominant competitive vectors as participants seek local regulatory expertise.
Among European integrated suppliers, Gerresheimer AG and Schott AG exemplify archetypes anchored in glass technology leadership, while Stevanato Group occupies a position spanning containment and delivery system integration. These three entities represent the structural core around which competitive dynamics orbit, with each anchoring distinct approaches to material science and regulatory qualification depth.
| Leading Market Players |
|---|
| Gerresheimer |
| Schott |
| Stevanato Group |
| West Pharmaceutical Services |
| Amcor |
| Aptar Group |
| Nipro |
| Corning |
| SGD Pharma |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap glass converters in Germany and Italy maintain pricing discipline through generational ownership structures that resist short-term margin compression. Their patient capital buffers allow sustained investment in borosilicate tubing capacity without quarterly earnings pressure, insulating premium vial pricing from volatile polymer feedstock cycles that buffet cycloolefin resin suppliers.
Pricing Analysis
Distributor margins on pre-filled syringes compress under health system bundled procurement contracts that eliminate middle-tier markups. Three-tier pricing structure across premium, standard, and economy levels separates FDA-validated containment from CE-marked equivalents and unqualified Asian imports. Cost compression in economy-grade glass vials intensifies because Indian domestic manufacturers scale conversion capacity under PLI scheme subsidies. Hospital networks exhibit lowest price sensitivity for cryogenic-ready formats, while government tenders in Southeast Asia drive ruthless unit-cost optimization.
Supply Chain Analysis
Workforce availability in Bavaria's precision glass corridor and Gujarat's pharmaceutical manufacturing zones anchors global Type I borosilicate tubing output. Supply concentrates among German, Italian, and Indian producers who draw from quartz sand deposits in Brazil and Madagascar. Single-source vulnerability concentrates in specialty cobalt-blue tubing for light-sensitive biologics, where Schott maintains effective monopoly. Distribution runs through cold-chain logistics providers with validated thermal packaging credentials for mRNA platform distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vaccine packaging market compounds steadily as biologics pipelines mature and regulatory qualification burdens deepen moats around incumbent suppliers.
For Market Incumbents: Anchor technology leadership through backward integration into borosilicate tubing production, capturing margin that currently flows to European specialists. Expand capacity in Hyderabad and Pune to serve CDSCO-mandated serialization requirements for export-bound vaccines. Polymer substitution in viral vector applications threatens glass-dominant positioning; accelerate COP vial development to retain shelf space in gene therapy supply chains. For New Entrants and Emerging Players: Cycloolefin polymer conversion expertise offers entry into mRNA and viral vector containment where glass breakage rates create unacceptable loss. Indonesia's domestic manufacturing incentives under national health sovereignty programs represent the most penetrable geography, with Ministry of Health localization requirements favoring in-country fill-finish partnerships. Pursue WHO prequalification pathway to unlock UN procurement volume contracts as credibility anchor. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier polymer converters with underdeveloped toxicological data packages that EMA extractables guidelines have sidelined. Long-term viability hinges on regulatory qualification depth rather than unit cost position, favoring targets with validated containment-device-serialization integration capabilities. Monitor FDA container closure guidance revisions as inflection indicator for accelerated polymer adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Borosilicate Tubing | Captures margin from German and Italian tubing specialists while securing supply during demand surges. |
| CDSCO Serialization Compliance Investment | Unlocks Indian export-bound vaccine contracts under DGFT traceability mandates for COVAX supply. |
| Cycloolefin Polymer Vial Development | Addresses protein adsorption and breakage risks in cryogenic mRNA distribution lanes. |
| Dual-Chamber Cartridge Platform Launch | Integrates lyophilized drug and diluent for complex biologics requiring point-of-care reconstitution. |
| WHO Prequalification Pathway Completion | Accelerates regulatory recognition for UN procurement programs and bilateral supply commitments. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with biologics manufacturing executives, regulatory affairs specialists at FDA and EMA, hospital pharmacy procurement directors, and cold-chain logistics operators with secondary validation against FDA container closure guidance documents, EMA extractables protocols, CDSCO serialization circulars, and WHO prequalification pathway specifications. Bottom-up demand modeling from vaccine pipeline analysis triangulated against top-down market sizing from packaging supplier capacity disclosures.
Historical reference periods anchored volume and value projections across the modeling period, with segmentation dimensions spanning packaging format, material type, and regional regulatory cluster. CAGRs derived from growth rate reconciliation across segment-level demand forecasts and supply-side capacity expansion announcements incorporated biologics pipeline maturation timelines and temperature-profile requirements from next-generation platforms.
The model holds under stable regulatory qualification burdens and continued biologics pipeline expansion; deviation in polymer extractables standards or geopolitical friction in borosilicate tubing trade flows would shift growth trajectories. Practitioners should monitor EMA extractables guideline enforcement patterns and CDSCO implementation timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Packaging
Clinical Trial Packaging Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Bottles Market
Pharmaceutical Packaging
Nasal Spray Packaging Market
Pharmaceutical Packaging
Pharmacy Repackaging Systems Market
Pharmaceutical Packaging
India Pharmaceutical Packaging Market
Pharmaceutical Packaging
Global Pharmaceutical Processing Seals Market
Pharmaceutical Packaging
North America Pharmaceutical Plastic Packaging Market
Pharmaceutical Packaging
Injection Bottles Market
Pharmaceutical Packaging
Global Ampoules Packaging Market
Pharmaceutical Packaging
Pharmaceutical Plastic Pots Market
Pharmaceutical Packaging
Middle East and Africa Ampoules Packaging Market
Pharmaceutical Packaging
Tablet Bottle Market
Pharmaceutical Packaging
Recycled Prescription Bag Market
Pharmaceutical Packaging
Pharmaceutical Secondary Packaging Market
Pharmaceutical Packaging
Global Vaccine Storage and Packaging Market
Pharmaceutical Packaging
Pharmaceutical Tubes Market