
 Immunosuppressants Market | 2026-2036
Immunosuppressants Market Size, Share, and Industry Trends Forecast 2026-2036
Immunosuppressants Market Outlook
The FDA Risk Evaluation and Mitigation Strategy for mTOR inhibitors is realigning cost-of-entry calculus for new entrants. Pfizer leverages its manufacturing scale to sustain supply chain reliability across calcineurin inhibitor portfolios. Novartis anchors its position through deep specialization in transplant rejection protocols. Bristol-Myers Squibb differentiates via extended R&D intensity in next-generation antiproliferative compounds.
Immunosuppressants comprise pharmacologic agents that attenuate immune response through cytokine inhibition, lymphocyte depletion, or metabolic pathway disruption, typically requiring cold-chain storage at 2-8°C and sterile parenteral formulation. These agents serve primarily to prevent graft rejection in transplant recipients and to modulate pathologic autoimmunity in disorders such as lupus and rheumatoid arthritis. Calcineurin inhibitors occupy the largest revenue pool due to decades of clinical validation in organ transplantation, while mTOR inhibitors represent the fastest-expanding category as nephrology programs seek alternatives with reduced nephrotoxic profiles. Autoimmune disorder applications command premium pricing relative to inflammatory disease segments, reflecting longer treatment durations and biologic combination protocols.
The FDA, EMA, and China's NMPA collectively enforce pharmacovigilance mandates that lengthen approval timelines but elevate safety benchmarks for chronic immunosuppression regimens. REACH compliance in Europe and GB standards in China impose additional purity and impurity-testing requirements on active pharmaceutical ingredient suppliers. Stakeholders must monitor evolving REMS modifications and biosimilar interchangeability designations that will reshape competitive dynamics without reference to specific calendar milestones.
Market Dynamics
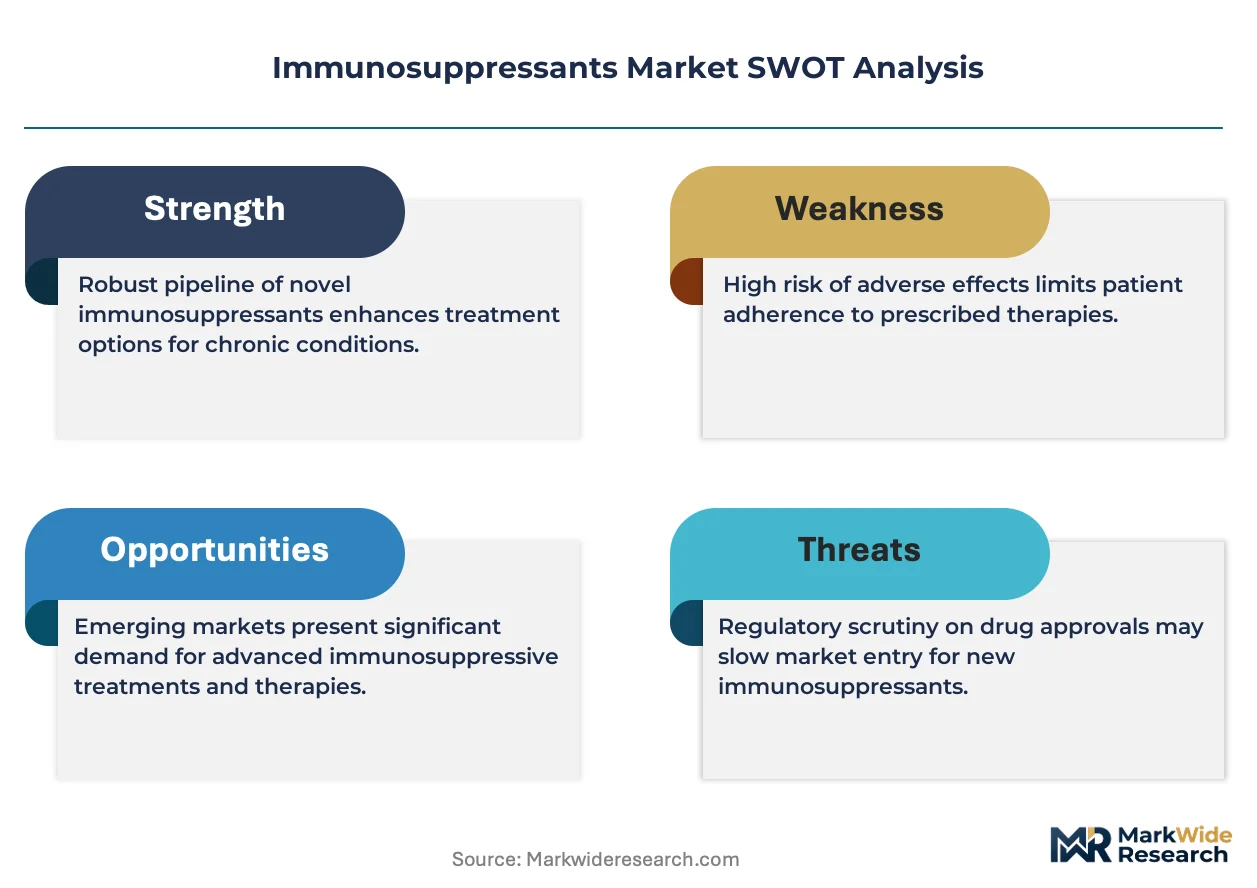
The FDA's Risk Evaluation and Mitigation Strategy for mTOR inhibitors is forcing manufacturers to absorb elevated compliance costs while transplant centers consolidate procurement around calcineurin inhibitor portfolios with established safety profiles.
Growth Catalysts
- REMS Compliance Infrastructure:The FDA's mTOR inhibitor Risk Evaluation and Mitigation Strategy creates competitive moats for incumbents with existing pharmacovigilance systems. Tertiary transplant centers in the United States prioritize suppliers with validated REMS documentation.
- Nephrology Protocol Migration:Solid organ transplant programs in Germany are accelerating adoption of mTOR inhibitors with reduced nephrotoxicity profiles. Clinical validation in renal-sparing regimens expands addressable patient pools beyond traditional calcineurin inhibitor candidates.
- Cold-Chain Logistics Maturation:Sterile parenteral formulation requirements at 2-8°C storage are driving investment in temperature-controlled distribution networks across China's tier-one hospital clusters. Supply chain reliability becomes a selection criterion for biologic immunosuppressant tenders.
Market Restraints
- Active Pharmaceutical Input Concentration:Calcineurin inhibitor API synthesis depends on fermentation-derived intermediates concentrated among contract manufacturers in India and China. Geopolitical friction or export license delays disrupt formulation continuity for European and North American finished-dose producers.
- EMA Pharmacovigilance Burden:The European Medicines Agency's post-authorization safety study mandates for chronic immunosuppression regimens extend approval timelines by 18-24 months. Development costs for novel mechanisms escalate beyond mid-cap R&D budgets.
- Biosimilar Substitution Pressure:Interchangeability designations for reference biologics in autoimmune indications compress pricing power for originator molecules. Rheumatology and dermatology segments face accelerating generic erosion in mature markets.
Strategic Opportunities
- India Transplant Infrastructure Buildout:The country's national organ allocation network expansion creates demand for affordable calcineurin inhibitor regimens. Local manufacturing partnerships with CDSCO-registered facilities circumvent import tariff structures.
- Biomarker-Guided Dosing:Therapeutic drug monitoring integration with pharmacogenomic profiling enables personalized immunosuppression in high-risk transplant recipients. Nephrology and hepatology programs in Japan's academic medical centers pilot algorithm-driven taper protocols.
- Subcutaneous Formulation Development:Self-administration routes for maintenance immunosuppression reduce infusion center burden. Home-care channels in post-acute settings capture margin previously allocated to hospital outpatient departments.
Industry Challenges
- Specialized Compound Pharmacist Scarcity:Sterile parenteral compounding for patient-specific immunosuppressant doses requires USP <797>-certified technicians. Workforce pipeline constraints limit expansion of hospital-based transplant pharmacy services.
- Legacy Electronic Health Record Integration:Therapeutic drug monitoring data from point-of-care analyzers must interface with Epic and Cerner systems for clinical decision support. Custom API development timelines delay protocol standardization across multi-site transplant networks.
- Multi-Site Trial Coordination Complexity:International registration studies for novel immunosuppressant mechanisms require harmonized endpoints across FDA, EMA, and NMPA jurisdictions. Investigator site qualification delays compress patent-protected commercialization windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Immunosuppressants Market |
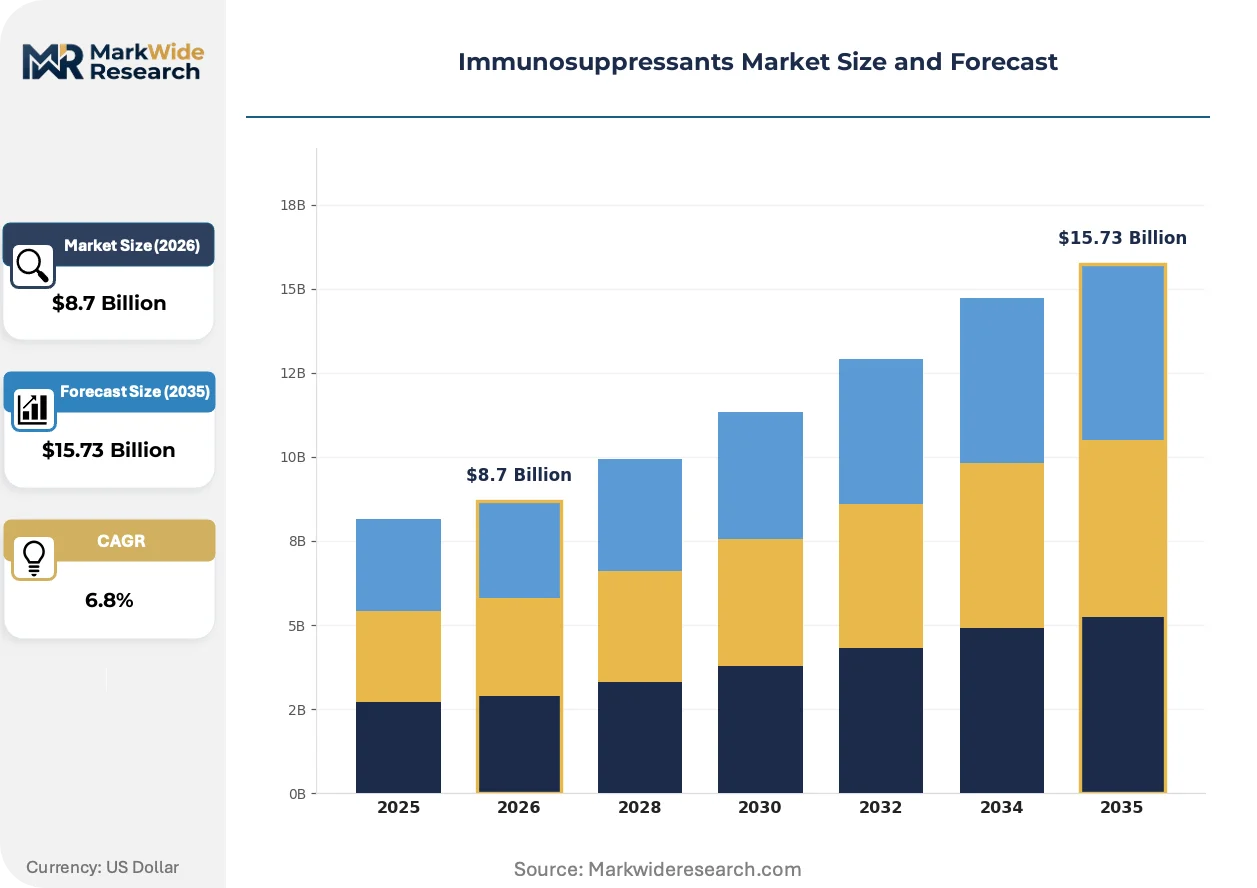
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corticosteroids, Calcineurin Inhibitors, mTOR Inhibitors, Antiproliferative Agents Application: Organ Transplantation, Autoimmune Disorders, Inflammatory Diseases, Cancer Therapy End User: Hospitals, Specialty Clinics, Outpatient Care Centers, Homecare Settings Delivery Mode: Oral, Injectable, Intravenous, Sublingual |
| Companies Covered | Pfizer, Sanofi, Novartis, GlaxoSmithKline, AbbVie, Roche, Bristol-Myers Squibb, Veloxis Pharmaceuticals, Astellas Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Immunosuppressants Market Strategic Shifts
Automation of manufacturing quality assurance and real-time release testing is compressing batch cycle times for sterile immunosuppressant formulations. These shifts intersect with evolving regulatory data integrity requirements and procurement centralization among integrated delivery networks.
Continuous manufacturing technology for small-molecule immunosuppressants is automating in-process control sampling that previously required manual chromatographic verification. Pfizer and Novartis production facilities in Ireland and Switzerland deploy PAT-enabled flow chemistry for calcineurin inhibitor API synthesis. Batch release timelines compress from 21 days to 72 hours, enabling just-in-time inventory models for transplant center pharmacies.
REACH compliance in Europe is mandating impurity profiling thresholds below 0.10% for genotoxic impurities in chronic-use immunosuppressants. Active pharmaceutical ingredient suppliers to the EMA-regulated market must retrofit analytical laboratories with high-resolution mass spectrometry infrastructure. Contract manufacturers serving European formulation clients absorb capital expenditure loads or exit the supplier base, concentrating qualified sources among tier-one chemistry providers.
Consolidated procurement by US integrated delivery networks is compressing supplier rosters for maintenance immunosuppression regimens. Transplant centers within Ascension and CommonSpirit Health systems centralize formulary decisions at regional pharmacy committees. Preferred vendor agreements with calcineurin inhibitor manufacturers displace fragmented hospital-level contracting, extracting volume-based rebates in exchange for exclusive or primary positioning.
Immunosuppressants Market Segmentation
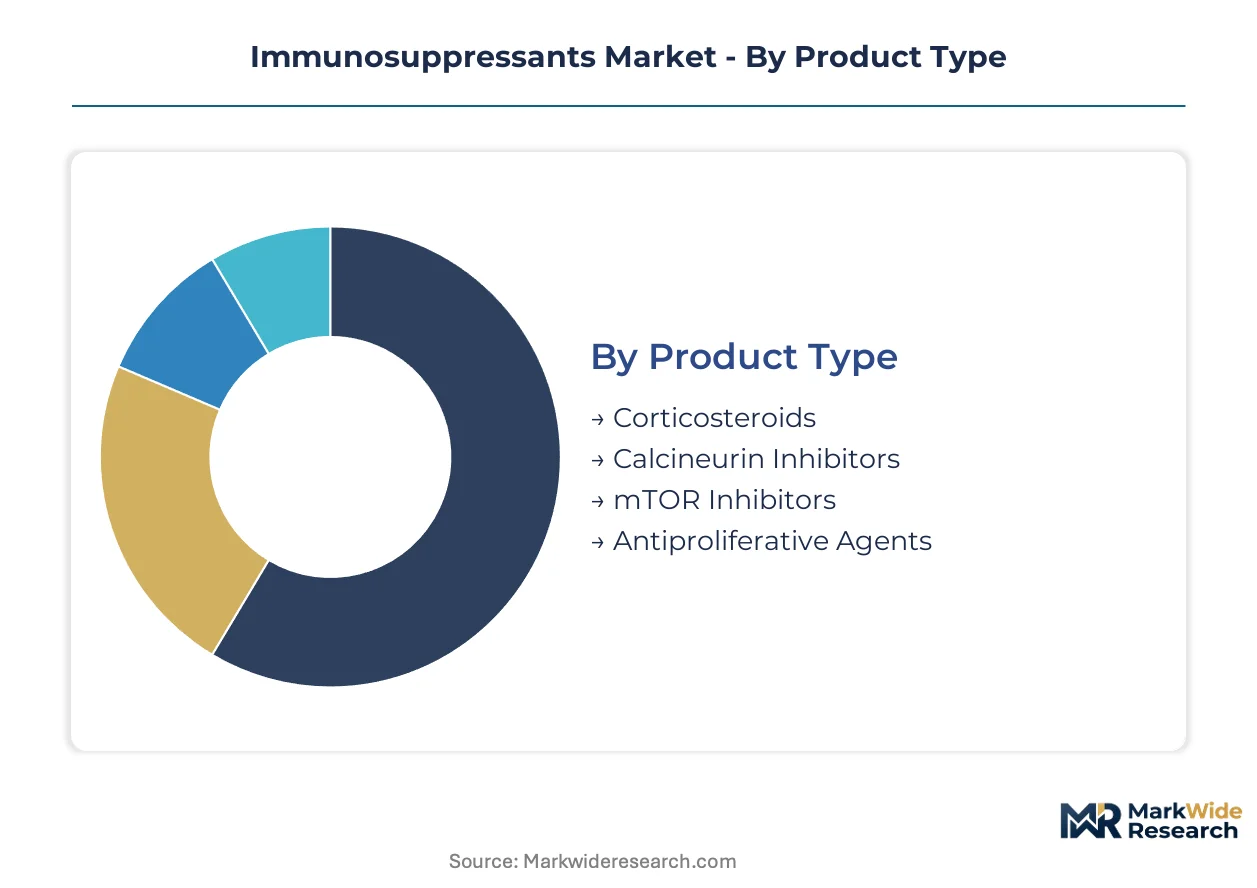
Immunosuppressant procurement patterns diverge sharply between high-acuity transplant centers requiring sterile parenteral formulations and chronic autoimmune patients managed through oral maintenance protocols. Understanding these segment boundaries clarifies where formulation investment, cold-chain infrastructure, and regulatory compliance resources concentrate.
Product Type:
Volume leadership rests with calcineurin inhibitors, while premium positioning and fastest expansion attach to mTOR inhibitors as nephrology programs seek renal-sparing alternatives.
- Calcineurin Inhibitors:Cyclosporine and tacrolimus formulations dominate solid organ transplantation through decades of graft survival validation. Tertiary transplant centers in the United States, Germany, and China standardize procurement around these agents despite nephrotoxicity trade-offs.
- mTOR Inhibitors:Sirolimus and everolimus attenuate immune response through mammalian target of rapamycin pathway blockade with reduced kidney toxicity profiles. German nephrology programs and US academic medical centers are accelerating adoption in renal-sparing regimens for high-risk recipients.
- Corticosteroids:Methylprednisolone and prednisone serve as induction and maintenance backbone across transplant and autoimmune protocols.
- Antiproliferative Agents:Mycophenolate mofetil and azathioprine interrupt lymphocyte proliferation through purine synthesis inhibition.
Mature deployment sits with calcineurin inhibitors. Newer deployment is concentrated in mTOR inhibitors.
Application:
Revenue concentration favors organ transplantation due to lifelong immunosuppression requirements, though autoimmune disorder applications command superior pricing per patient-year through biologic combination protocols.
- Organ Transplantation:Kidney, liver, heart, and lung transplant programs require multi-agent regimens combining calcineurin inhibitors, antiproliferatives, and corticosteroids. Procurement centralization within US integrated delivery networks and Chinese tier-one hospital clusters drives volume contracting.
- Autoimmune Disorders:Systemic lupus erythematosus, rheumatoid arthritis, and multiple sclerosis indications demand chronic immunomodulation with therapeutic drug monitoring. Rheumatology and dermatology segments in Germany and Japan face accelerating biosimilar substitution pressure.
- Inflammatory Diseases:Inflammatory bowel disease and psoriasis protocols employ immunosuppressants as steroid-sparing agents.
- Cancer Therapy:Graft-versus-host disease prophylaxis in allogeneic stem cell transplantation uses calcineurin-based regimens.
Longest treatment duration attaches to organ transplantation. Steepest expansion trajectory is emerging in autoimmune disorders.
End User:
Procurement authority concentrates in hospital pharmacy committees for acute induction phases, while maintenance therapy shifts toward outpatient and home channels seeking cost containment.
- Hospitals:Tertiary transplant centers with UNOS certification or equivalent national accreditation control high-value formulary decisions. Cold-chain infrastructure for sterile parenteral formulations and USP <797> compounding capabilities limit service expansion.
- Homecare Settings:Subcutaneous formulation development and patient self-administration programs reduce infusion center burden. Post-acute channels in the United States capture margin previously allocated to hospital outpatient departments.
- Specialty Clinics:Nephrology and hepatology-focused practices manage therapeutic drug monitoring for maintenance patients.
- Outpatient Care Centers:Ambulatory infusion sites handle intravenous induction dosing for transplant recipients.
Acute-phase revenue concentrates in hospitals. Channel expansion is gaining share fastest in homecare settings.
Delivery Mode:
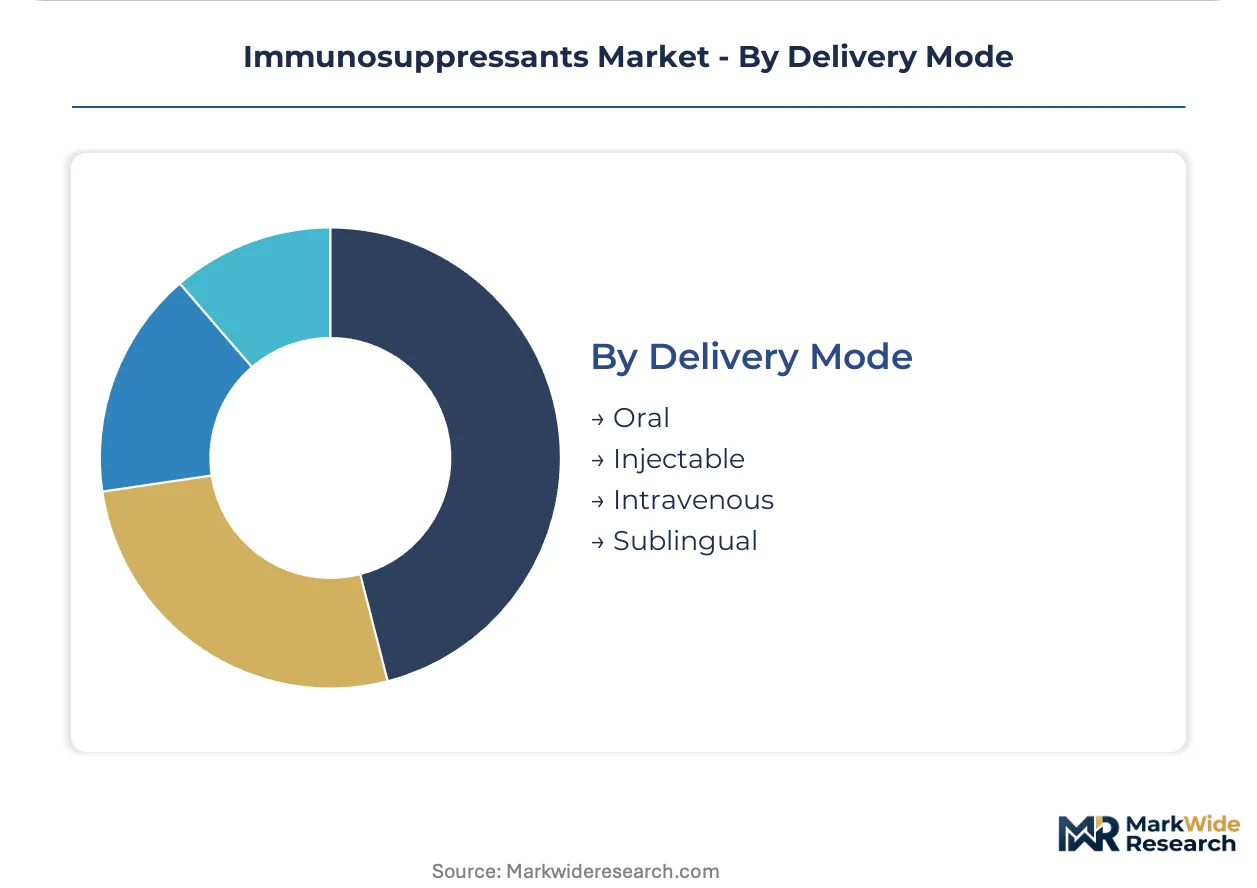
Patient compliance and cold-chain economics create divergent investment priorities between oral maintenance platforms and sterile injectable infrastructure.
- Injectable:Subcutaneous and intramuscular routes enable therapeutic drug monitoring with precise bioavailability. German and Japanese transplant networks prioritize depot formulations for adherence optimization in high-risk populations.
- Oral:Capsule and tablet formulations dominate chronic maintenance phases across calcineurin inhibitor and antiproliferative portfolios. Chinese and Indian markets drive demand for affordable solid-dose generics.
- Intravenous:Hospital-based infusion remains standard for induction and acute rejection rescue therapy.
- Sublingual:Limited adoption for tacrolimus formulations in patients with gastrointestinal absorption impairment.
Volume leadership resides with oral delivery. Innovation investment is concentrating in injectable platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement authority for immunosuppressants concentrates in tertiary transplant centers across the United States, China, and Germany, with each market governed by distinct regulatory frameworks and cold-chain infrastructure maturity.
United States
UNOS-certified transplant centers in Houston, Pittsburgh, and Los Angeles drive calcineurin inhibitor procurement through integrated delivery network formularies. FDA REMS documentation requirements for mTOR inhibitors elevate compliance costs for new entrants. The Southeast hospital cluster around Emory and Duke anchors volume contracting for sterile parenteral formulations.
Germany
Nephrology programs in Berlin, Munich, and Heidelberg accelerate mTOR inhibitor adoption for renal-sparing regimens. EMA post-authorization safety study mandates extend development timelines but reinforce safety benchmarks for chronic immunosuppression. The Baden-Württemberg pharmaceutical corridor concentrates API synthesis and finished-dose manufacturing for European distribution.
China
Tier-one hospital clusters in Beijing, Shanghai, and Guangzhou standardize procurement around calcineurin inhibitors for kidney and liver transplant programs. NMPA pharmacovigilance mandates align with international standards while GB purity requirements impose additional testing burdens on suppliers. The Yangtze River Delta biopharma hub scales cold-chain distribution networks for temperature-sensitive biologics.
India
Expansion of the national organ allocation network creates demand for affordable calcineurin inhibitor regimens in Delhi, Mumbai, and Chennai. CDSCO registration requirements for imported APIs protect domestic formulation manufacturers. The Hyderabad-Visakhapatnam corridor develops contract manufacturing capabilities for fermentation-derived immunosuppressant intermediates.
Japan
Academic medical centers in Tokyo, Osaka, and Nagoya pilot biomarker-guided dosing protocols for high-risk transplant recipients. PMDA therapeutic drug monitoring guidelines enable personalized immunosuppression taper algorithms. The Kanto region concentrates specialty pharmacy services for maintenance therapy management.
Immunosuppressants Market Competitive Environment
North American producers anchor one tier with established REMS infrastructure and integrated delivery network relationships; European specialists hold differentiated positions through nephrology protocol specialization and EMA regulatory expertise. The vendor base stratifies across three tiers: multinational pharmaceutical conglomerates with calcineurin inhibitor portfolios, mid-cap biotech firms developing next-generation mTOR pathways, and regional generic manufacturers serving price-sensitive markets. Consolidation pressures intensify as procurement centralization extracts volume-based rebates. Strategic moves concentrate on manufacturing automation investments and subcutaneous formulation development for home-care channels.
Within the multinational tier, Pfizer and Novartis occupy positions defined by manufacturing scale and transplant rejection protocol depth. Bristol-Myers Squibb represents the R&D-intensive archetype pursuing antiproliferative compound innovation. Among mid-cap specialists, Veloxis Pharmaceuticals exemplifies focused portfolio strategy around immunosuppressant delivery technologies. Astellas Pharma anchors the Asia-Pacific regional presence through transplant center relationships in Japan and emerging market expansion.
| Leading Market Players |
|---|
| Pfizer |
| Sanofi |
| Novartis |
| GlaxoSmithKline |
| AbbVie |
| Roche |
| Bristol-Myers Squibb |
| Veloxis Pharmaceuticals |
| Astellas Pharma |
| Others |
Value Chain & Pricing Dynamics
REACH compliance in Europe gates qualified supply for chronic-use immunosuppressants, concentrating premium-tier pricing access among API suppliers with high-resolution mass spectrometry infrastructure and certified impurity profiling below 0.10% thresholds.
Pricing Analysis
Lead-time-driven pricing stratifies across contract tiers, with tertiary transplant centers in the United States and Germany paying premiums for validated REMS documentation and 72-hour batch release timelines while spot procurement through fragmented hospital pharmacies absorbs cost penalties. Price differentiation hinges on FDA REMS certification status and cold-chain logistics reliability, with integrated delivery networks extracting volume rebates through exclusive formulary positioning. Cost compression in oral maintenance generics intensifies as Indian and Chinese manufacturers scale fermentation-derived calcineurin inhibitor output. Autoimmune disorder applications show least price sensitivity due to biologic combination protocol stickiness.
Supply Chain Analysis
Fermentation-derived intermediate supply rests on contract manufacturers concentrated in India and China, with the Hyderabad-Visakhapatnam corridor and Yangtze River Delta biopharma hub anchoring calcineurin inhibitor API synthesis. Critical inputs span fermentation substrates, sterile parenteral formulation excipients, and temperature-controlled packaging materials. Single-source vulnerability in fermentation capacity exposes European and North American finished-dose producers to export license delays and geopolitical friction. Distribution runs through integrated delivery network central warehouses for US transplant centers, with tier-one hospital clusters in Beijing and Shanghai maintaining direct API supplier relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation capacity scarcity for calcineurin inhibitor intermediates props pricing power among incumbent API suppliers, constraining supply elasticity across transplant center procurement cycles.
For Market Incumbents: Acquire USP <797>-certified compounding facilities and cold-chain distribution assets to lock in tertiary transplant center relationships. Consolidate formulation manufacturing in Ireland and Switzerland to exploit PAT-enabled continuous processing advantages. Defend against biosimilar erosion in autoimmune indications through biomarker-guided dosing protocol development and therapeutic drug monitoring integration. For New Entrants and Emerging Players: Direct-to-homecare digital channels enable subcutaneous formulation penetration in post-acute maintenance segments underserved by hospital outpatient departments. Target India's national organ allocation network expansion with CDSCO-registered local manufacturing partnerships circumventing import tariff structures. Pursue nephrology protocol migration in German academic medical centers as the most penetrable mTOR inhibitor adoption corridor. For Investors and Strategic Acquirers: FDA REMS modification announcements for mTOR inhibitors are the leading indicator that compliance infrastructure valuations will spike among incumbent suppliers with validated pharmacovigilance systems. Long-term viability favors vertically integrated players controlling fermentation-derived API synthesis through captive supply arrangements. Monitor EMA post-authorization safety study mandate timelines as the signal for novel mechanism development cost escalations.| Strategic Initiative | Industry Significance |
|---|---|
| REMS Compliance Infrastructure Investment | FDA-mandated pharmacovigilance systems create competitive moats for transplant rejection protocol suppliers. |
| Continuous Manufacturing Technology Deployment | PAT-enabled flow chemistry in Irish and Swiss facilities compresses calcineurin inhibitor batch release from 21 days to 72 hours. |
| Subcutaneous Formulation Development | Self-administration routes capture margin from hospital outpatient departments into homecare channels. |
| Biomarker-Guided Dosing Integration | Pharmacogenomic profiling algorithms enable personalized immunosuppression in Tokyo and Osaka academic medical centers. |
| India Manufacturing Partnership Structuring | CDSCO-registered local production circumvents import tariffs for Delhi and Mumbai transplant program expansion. |
Study Parameters
FDA filings, EMA post-authorization safety study databases, and ClinicalTrials.gov registration records formed the secondary backbone for this analysis, cross-referenced with primary interviews involving transplant pharmacy directors, nephrology protocol specialists, CDSCO regulatory affairs leads, and integrated delivery network formulary managers. Bottom-up and top-down triangulation validated calcineurin inhibitor and mTOR inhibitor volume estimates against customs data for fermentation-derived API trade flows and hospital procurement database extracts from US UNOS-certified centers.
Bottom-up modeling anchored patient pool projections across the analysis window, segmented by organ transplantation indication, autoimmune disorder application, delivery mode, and regional regulatory cluster. Top-down reconciliation applied pharmaceutical industry spending patterns and immunosuppressant therapeutic category growth rates. CAGRs derived from log-linear trend fitting across historical volume trajectories, with forecast inputs incorporating NMPA pharmacovigilance mandate implementation timelines and REACH impurity threshold enforcement intensity.
The model holds under stable regulatory enforcement of REMS and REACH compliance standards; deviation in FDA biosimilar interchangeability designation timelines or EMA post-authorization study mandate scope would shift competitive positioning and pricing power assumptions. Forecasts reflect documented assumptions regarding cold-chain infrastructure buildout rates in China's tier-one hospital clusters and fermentation capacity expansion in India's pharmaceutical corridor. A small set of named triggers warrants ongoing watch: CDSCO API export policy modifications, USP <797> compounding workforce pipeline constraints, and integrated delivery network procurement centralization velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Global Penicillin Drug Market
Pharmaceutical Ingredients
Anti-Allergic Agent Ingredients Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Fosfomycin Trometamol Powder Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Global Cephalosporin Drugs Market
Pharmaceutical Ingredients
Asia-Pacific Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceutical Ingredients
Global Dexamethasone Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Global Chlorpheniramine Maleate Market
Pharmaceutical Ingredients
Pharma Grade Sodium Bicarbonate Market
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market