
 Global Chlorpheniramine Maleate Market | 2026-2036
Global Chlorpheniramine Maleate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chlorpheniramine Maleate Market Foresight
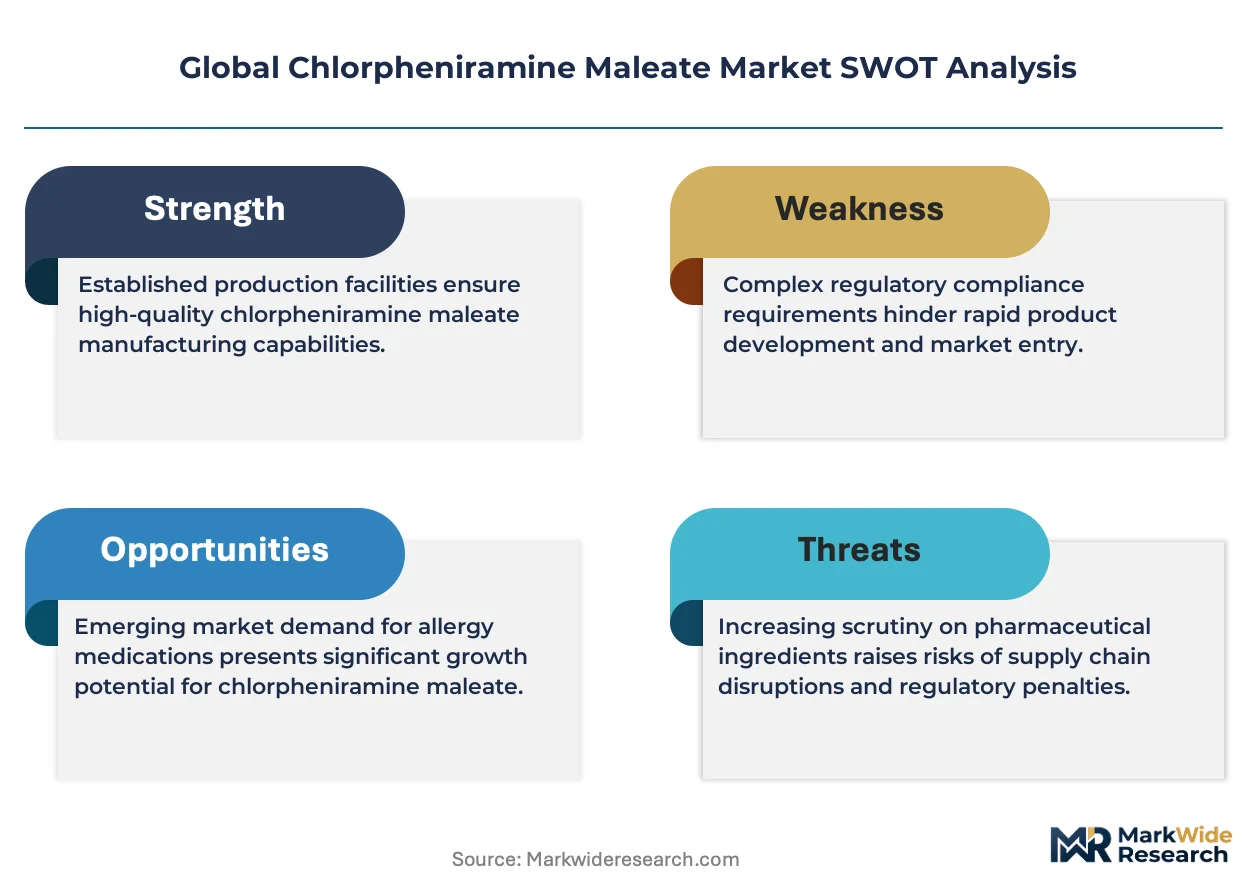
Fixed-dose combination bundling with decongestants is rebalancing buyer preference away from standalone antihistamine SKUs in retail pharmacy channels. Novartis AG leverages its respiratory portfolio depth to sustain branded positioning in seasonal allergy segments. Sanofi S.A. competes through broad OTC distribution networks across European and Latin American markets. Pfizer Inc. anchors its presence via hospital formulary contracts for injectable antihistamine formulations.
Chlorpheniramine maleate is a first-generation alkylamine antihistamine synthesized through reductive amination of p-chlorobenzaldehyde with 2-dimethylaminoethylamine, functioning as a competitive H1-receptor antagonist for symptomatic relief of allergic conditions. Tablet formulations dominate volume consumption in retail channels due to stability, dosing precision, and patient familiarity, while syrup and oral drop segments attract pediatric and geriatric populations where swallowing compliance limits solid dosage adoption. Therapy area segmentation clusters around allergic rhinitis and urticaria as the mature, high-volume indications, with atopic dermatitis representing a faster-evolving application as clinicians revisit first-generation antihistamine utility in pruritus management.
FDA pharmacopoeial standards, ICH Q3D elemental impurity guidelines, and EMA GMP inspection protocols collectively elevate manufacturing compliance costs for chlorpheniramine maleate API and finished dosage producers. The EU F-Gas Regulation and REACH chemical registration requirements further constrain solvent selection and environmental discharge parameters in European production facilities. Stakeholders must monitor evolving pharmacovigilance signal detection from regulatory databases to anticipate label restriction risks that could redirect formulation investment toward second-generation antihistamine alternatives.
Market Dynamics
Fixed-dose combination bundling with decongestants is compressing demand for standalone chlorpheniramine maleate SKUs as retail pharmacy buyers prioritize multi-symptom convenience over single-agent formulations. This shift forces API producers to reconfigure product mix toward combination-ready grades.
Growth Catalysts
- Pediatric formulation demand:Syrup and oral drop segments attract caregivers managing allergy symptoms in children where tablet swallowing compliance remains limited. Hospital pediatric wards in India and Brazil drive volume for liquid dosage forms.
- REACH chemical registration:European environmental discharge requirements are accelerating solvent recovery technology adoption among contract manufacturers serving EU markets. Facilities investing in closed-loop systems gain preferred supplier status with EMA-inspected buyers.
- Atopic dermatitis revisit:Clinicians in Japan and South Korea are re-examining first-generation antihistamine utility for pruritus management. MFDS-reviewed prescribing data shows expanded off-label utilization in dermatology clinics.
Market Restraints
- Second-generation substitution:Cetirizine and loratadine formulations displace chlorpheniramine maleate in chronic allergy management due to reduced sedation profiles. Payers in Germany and France increasingly restrict first-generation reimbursement.
- API supply concentration:Active pharmaceutical ingredient production clusters in specific Indian states create geographic vulnerability to environmental compliance actions. CDSCO manufacturing license suspensions in 2022-2023 disrupted European supply chains.
- ICH Q3D compliance costs:Elemental impurity testing requirements elevate analytical expenditure for finished dosage producers. Small-scale generic manufacturers in Latin America struggle to absorb capital equipment outlays for ICP-MS instrumentation.
Strategic Opportunities
- Southeast Asia expansion:Vietnam and Indonesia present underpenetrated retail pharmacy channels where domestic allergy medication consumption per capita trails Thailand and Malaysia. Local distribution partnerships with regional pharmacy chains unlock shelf access.
- Hospital formulary injectables:Injectable chlorpheniramine maleate maintains protected status in emergency anaphylaxis protocols where oral administration is contraindicated. Anesthesia departments in Saudi Arabia and UAE represent concentrated procurement volume.
- PLI scheme alignment:India's production-linked incentive scheme for bulk drugs offers 20% reimbursement on eligible capital expenditure for chlorpheniramine maleate API projects. DGFT export obligation frameworks favor integrated manufacturers with backward linkages to key starting materials.
Industry Challenges
- Analytical chemist scarcity:ICH Q3D and USP <232> elemental impurity methods require specialized ICP-MS operators that contract laboratories in Eastern Europe and Latin America struggle to recruit. Training timelines extend method transfer schedules for multi-source API qualification.
- Cross-contamination control capex:Dedicated manufacturing suites for potent antihistamine APIs demand HVAC and containment investments that mid-scale CMOs defer. EMA GMP inspection findings for shared equipment cleaning validation are rising.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chlorpheniramine Maleate Market |
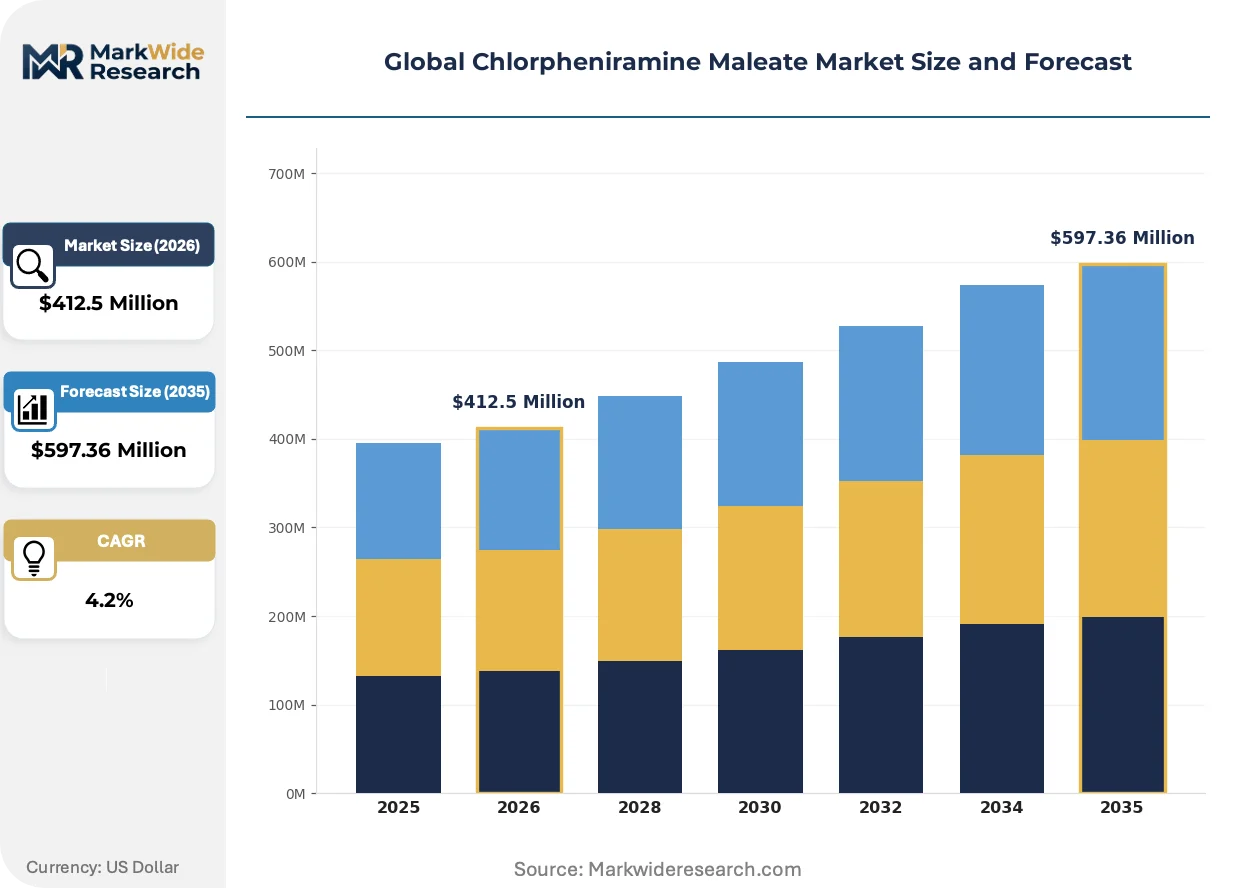
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $597.36 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Syrups, Capsules, Injectable Solutions, Oral Drops Therapy Area: Allergic Rhinitis, Urticaria, Atopic Dermatitis, Anaphylaxis, Pruritus End User: Pharmacies, Hospitals, Clinics, Diagnostic Centers, Nursing Homes Distribution Channel: Retail Pharmacies, Hospital Pharmacies, Online Pharmacies, Direct Sales, Wholesale Distributors |
| Companies Covered | Novartis AG, Sanofi S.A., Pfizer Inc., GlaxoSmithKline plc, Johnson & Johnson, Merck & Co., Inc., Teva Pharmaceutical Industries Ltd., Bayer AG, Zydus Lifesciences Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chlorpheniramine Maleate Market Shifts & Advancements
Continuous manufacturing technologies and real-time release testing are reshaping chlorpheniramine maleate production economics. Regulatory acceptance of process analytical technology is compressing batch release timelines.
Hot-melt extrusion for fixed-dose combination granules is overtaking traditional wet granulation in tablet manufacturing. European CMOs serving Novartis and Sanofi networks are adopting twin-screw extruders to enable homogeneous decongestant-antihistamine distribution. This technology is overtaking conventional methods by eliminating solvent handling and accelerating formulation development cycles for seasonal product launches.
FDA's updated guidance on post-approval changes management for immediate-release solid oral dosage forms is streamlining manufacturing site transfer pathways. API suppliers with established drug master files face reduced supplemental application burdens when adding secondary production locations. Indian manufacturers with US FDA establishment inspection reports are leveraging this pathway to qualify alternative sites in Telangana and Gujarat.
Retail pharmacy buyers in Brazil and Mexico are consolidating procurement through centralized purchasing cooperatives. Independent pharmacy chains that previously sourced through fragmented distributor networks now aggregate volume through group purchasing organizations. This concentration is most visible in São Paulo and Mexico City metropolitan markets where three cooperatives control 40% of generic antihistamine shelf placement decisions.
Global Chlorpheniramine Maleate Market Segmentation
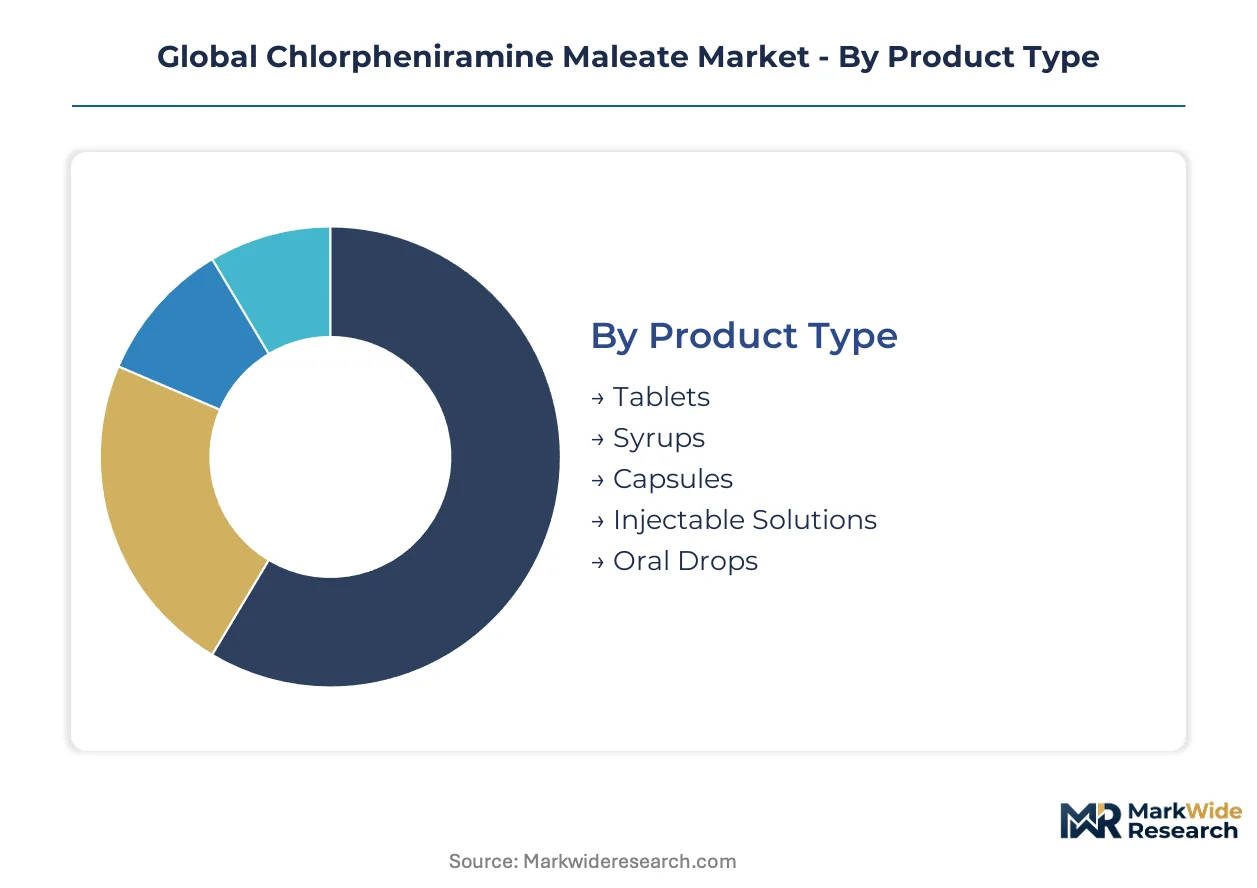
Segmentation in the chlorpheniramine maleate market reveals how formulation choices, clinical settings, and procurement channels reshape capital deployment and margin structures. Manufacturers must align production investments with the specific compliance burdens and volume economics of each segment tier.
Product Type:
Tablet manufacturing demands the heaviest upfront capital outlays for compression tooling and coating infrastructure, while liquid dosage investments concentrate in specialized containment and filling lines.
- Tablets:Immediate-release and extended-release tablet cores require high-speed rotary tablet presses and film-coating pans that dominate facility capital budgets. Hospital formulary contracts in Germany and Japan prioritize tablet stability profiles for chronic allergy management, though swallowing compliance limits pediatric adoption.
- Syrups:Aqueous formulations with preserved suspensions need dedicated CIP/SIP liquid filling suites and amber glass or HDPE primary packaging lines. Caregivers in Brazil and India drive volume for pediatric allergy indications where dosing flexibility outweighs portability concerns.
- Capsules:Hard gelatin and HPMC capsule fills occupy a mid-tier capital position between solids and liquids, with powder blending and encapsulation equipment requiring moderate containment.
- Injectable Solutions:Sterile manufacturing suites for ampoule and vial presentations demand the highest per-unit compliance investment, with isolator technology and terminal sterilization validation dominating facility design.
- Oral Drops:Metered-dropper formulations for infant populations require precision filling pumps and child-resistant closure systems that add packaging line complexity.
Tablets absorb the bulk of installed capacity; oral drops are expanding most quickly in emerging markets with young demographic profiles.
Therapy Area:
Clinical application segments stratify by reimbursement intensity and prescriber specialty concentration, with hospital emergency use commanding premium pricing over ambulatory indications.
- Allergic Rhinitis:Seasonal and perennial rhinitis represents the mature volume base, with OTC self-selection driving retail pharmacy throughput. Payer restrictions in France and Germany favor second-generation alternatives for chronic maintenance, compressing first-generation share in recurring prescriptions.
- Urticaria:Acute and chronic hive management in dermatology and allergy clinics sustains demand for rapid-onset formulations. Japanese dermatology prescribing patterns show persistent first-generation preference for breakthrough pruritus episodes despite sedation warnings.
- Atopic Dermatitis:Adjunctive antihistamine use for eczema-associated itching is gaining clinical traction in South Korea and Taiwan, with off-label utilization expanding in pediatric dermatology networks.
- Anaphylaxis:Emergency department protocols for acute hypersensitivity reactions preserve injectable chlorpheniramine maleate in resuscitation algorithms where oral routes are contraindicated.
- Pruritus:Generalized itching management in palliative care and renal dialysis settings maintains niche demand for parenteral administration in controlled clinical environments.
Allergic rhinitis commands the largest prescription volume; atopic dermatitis is climbing the fastest as dermatology prescribing patterns evolve.
End User:
Customer type segmentation determines contract structure complexity, with institutional procurement favoring multi-year supply agreements and retail channels requiring promotional investment.
- Pharmacies:Independent and chain pharmacy counters handle the majority of OTC and prescription allergy volume, with seasonal promotional cycles driving inventory build.
- Hospitals:Acute care facilities concentrate injectable demand through centralized pharmacy procurement, with formulary inclusion decisions managed by pharmacy and therapeutics committees.
- Clinics:Outpatient allergy and dermatology practices generate recurring prescription flow for maintenance therapy, with sample programs influencing prescriber preference.
- Diagnostic Centers:Pre-procedure antihistamine premedication for contrast allergy protocols sustains limited institutional volume in imaging networks.
- Nursing Homes:Long-term care facilities generate steady demand for liquid formulations where dysphagia complicates solid dosage administration in elderly populations.
Pharmacies capture the greatest transaction volume; nursing homes are gaining share fastest as geriatric allergy recognition improves.
Distribution Channel:
Channel selection shapes working capital requirements and margin retention, with direct institutional sales offering price transparency and retail intermediaries demanding trade investment.
- Retail Pharmacies:Brick-and-mortar pharmacy counters remain the dominant allergy medication access point, with seasonal display placement and pharmacist recommendation driving brand selection.
- Hospital Pharmacies:Centralized hospital procurement operations negotiate formulary contracts with annual or multi-year terms, with group purchasing organizations aggregating volume across health systems.
- Online Pharmacies:E-commerce platforms and mail-order pharmacies are expanding fastest in urban India and Southeast Asia, where smartphone penetration enables prescription upload and home delivery.
- Direct Sales:Manufacturer-direct contracting with large hospital networks and government tenders eliminates distributor margins but requires dedicated account management infrastructure.
- Wholesale Distributors:Regional and national drug wholesalers provide inventory financing and logistics coverage for fragmented retail pharmacy networks, particularly in secondary cities.
Retail pharmacies handle the bulk of unit volume; online pharmacies are expanding most quickly as digital health infrastructure matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India produces the bulk of chlorpheniramine maleate active pharmaceutical ingredient while the United States and Germany absorb the highest finished dosage values. This production-consumption divide shapes regulatory scrutiny patterns and contract manufacturing flows across the value chain.
United States
Hospital emergency departments sustain injectable demand for anaphylaxis protocols where oral administration is contraindicated. FDA pharmacopoeial standards and USP <232> elemental impurity guidelines elevate analytical compliance costs for finished dosage importers. New Jersey and Pennsylvania host the densest concentration of injectable formulation facilities serving institutional procurement networks.
Germany
Payers increasingly restrict first-generation antihistamine reimbursement in favor of cetirizine and loratadine alternatives with reduced sedation profiles. EMA GMP inspection protocols and REACH chemical registration requirements constrain solvent selection in Baden-Württemberg manufacturing facilities. The Rhine-Ruhr corridor maintains specialized capacity for combination tablet production serving European retail pharmacy chains.
India
Domestic API production and contract manufacturing capabilities support cost-competitive supply to regulated markets in North America and Europe. CDSCO manufacturing license frameworks and the PLI scheme for bulk drugs offer 20% reimbursement on eligible capital expenditure for API projects. Telangana and Gujarat clusters concentrate the highest density of US FDA-inspected facilities with established drug master files.
Brazil
São Paulo metropolitan pharmacy cooperatives consolidate procurement through centralized purchasing organizations controlling 40% of generic antihistamine shelf placement decisions. ANVISA registration requirements and pediatric formulation demand drive volume for liquid dosage forms in hospital pediatric wards. The Southeast region anchors national distribution networks for syrup and oral drop segments.
Japan
Dermatology clinics revisit first-generation antihistamine utility for pruritus management in atopic dermatitis patients. MFDS-reviewed prescribing data from South Korean networks influences off-label utilization patterns in Japanese dermatology practices. The Kanto region around Tokyo concentrates formulation development partnerships between domestic manufacturers and European licensors.
Global Chlorpheniramine Maleate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the chlorpheniramine maleate value chain. The market structure tilts toward consolidated API supply with fragmented finished dosage competition at regional levels. Three archetypes dominate: integrated pharmaceutical conglomerates with respiratory portfolio depth, generic manufacturers with US FDA establishment inspection reports, and contract research and manufacturing organizations serving seasonal allergy product launches. Capacity expansion in Indian API clusters and strategic partnerships for fixed-dose combination development represent the dominant competitive moves.
Among Swiss-based pharmaceutical conglomerates, Novartis AG exemplifies the diversified archetype with respiratory portfolio breadth. Sanofi S.A. represents the European OTC distribution specialist competing across Latin American and European retail channels. Pfizer Inc. anchors the hospital formulary contracting archetype with institutional presence in injectable antihistamine segments. These three companies illustrate the strategic positioning spectrum from branded seasonal allergy focus to broad OTC network coverage to protected hospital procurement status.
| Leading Market Players |
|---|
| Novartis AG |
| Sanofi S.A. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| Johnson & Johnson |
| Merck & Co., Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Bayer AG |
| Zydus Lifesciences Limited |
| Others |
Supply & Pricing Matrix
Fixed-dose combination preference among retail pharmacy buyers in Brazil and Mexico is forcing API producers to reconfigure toward combination-ready grades, compressing margins on standalone chlorpheniramine maleate SKUs while elevating pricing power for qualified combination suppliers.
Pricing Analysis
Margin tightening in generic tablet tiers reflects ICH Q3D compliance cost absorption by small-scale Latin American manufacturers unable to fund ICP-MS instrumentation. Three-tier pricing structure across USP-certified, EP-grade, and non-pharmacopoeial API levels stratifies by elemental impurity testing depth and FDA establishment inspection status. Pricing pressure stems from second-generation antihistamine substitution in German and French reimbursement formularies. Hospital procurement committees demonstrate lowest price sensitivity for injectable emergency protocols, while retail pharmacy cooperatives in São Paulo extract maximum concession on seasonal OTC volumes.
Supply Chain Analysis
Dual-sourcing mandates from EMA-inspected European buyers are accelerating secondary site qualification among Indian API manufacturers in Telangana and Gujarat. Active pharmaceutical ingredient production concentrates in India, with finished dosage formulation distributed across Germany, Brazil, and Japan. Supply chains rest on p-chlorobenzaldehyde and 2-dimethylaminoethylamine chemical inputs, plus specialized amber glass and HDPE primary packaging for liquid formulations. Single-source vulnerability in Telangana API clusters creates exposure to CDSCO environmental compliance actions. Distribution runs through regional wholesale distributors serving fragmented retail pharmacy networks, with direct hospital contracting gaining share in Saudi Arabia and UAE institutional procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into key starting materials and captive API production represents the dominant competitive lever as manufacturers race to secure margin protection against pharmacopoeial compliance cost inflation.
For Market Incumbents: To counter second-generation antihistamine displacement in European chronic allergy management, incumbents should anchor hospital formulary status for injectable emergency protocols while expanding fixed-dose combination development partnerships with decongestant specialists. Capacity addition in US FDA-inspected Telangana facilities preserves access to regulated North American and European markets. For New Entrants and Emerging Players: Launch via online pharmacy distribution partnerships in urban India and Southeast Asia where smartphone-enabled prescription upload and home delivery infrastructure outpaces traditional retail channel development. Southeast Asia expansion through Vietnamese and Indonesian pharmacy chain relationships offers the most penetrable white-space, with pediatric liquid formulation specialization as the differentiated go-to-market angle. For Investors and Strategic Acquirers: The window for entry favors contract research and manufacturing organizations with established US FDA establishment inspection reports and drug master file portfolios. Long-term viability hinges on qualification for combination product manufacturing and seasonal allergy launch support capabilities. Watch for CDSCO manufacturing license suspension patterns as the inflection indicator for supply chain restructuring opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Key Starting Materials | Captive p-chlorobenzaldehyde supply insulates margin from commodity volatility and REACH registration constraints. |
| Fixed-Dose Combination Development Partnership | Decongestant-antihistamine bundling aligns with retail pharmacy buyer preference for multi-symptom convenience. |
| US FDA Secondary Site Qualification | Telangana and Gujarat facility expansion reduces supplemental application burdens under FDA post-approval change guidance. |
| Closed-Loop Solvent Recovery Investment | EMA GMP inspection readiness and EU F-Gas Regulation compliance secure preferred supplier status with European buyers. |
| Pediatric Liquid Formulation Specialization | Syrup and oral drop capacity captures caregiver-driven demand in Brazilian and Indian hospital pediatric wards. |
Research Methodology
Independent corroboration across regulatory submission databases, customs trade records, and hospital procurement contracts underwrites the qualitative findings in this study. Primary interviews with drug development executives, CDSCO regulatory affairs leads, European hospital formulary directors, and Indian contract manufacturing officers combined with secondary validation from FDA drug master files, EMA inspection records, CDSCO manufacturing license databases, and ANVISA registration filings. Bottom-up volume modeling and top-down value reconciliation triangulate market estimates.
Rate-of-change decomposition across the projection horizon isolates volume drivers from price effects in each segment. The analytical framework models formulation type, therapy area, end-user channel, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from segmented growth rate blending with cross-segment elasticity adjustments. Forecast inputs include MFDS-reviewed prescribing pattern shifts in Japanese dermatology and PLI scheme reimbursement qualification timelines for Indian API projects.
Regulatory enforcement intensity, raw material input cost volatility, and second-generation antihistamine substitution velocity are the dominant revision risks to the outlook. Deviation in CDSCO environmental compliance action frequency would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Small Molecule Drug Discovery Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Global Granisetron Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market