
 Pharma Grade Sodium Bicarbonate Market | 2026-2036
Pharma Grade Sodium Bicarbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Pharma Grade Sodium Bicarbonate Market Outlook
USP-NF grade specification is rotating toward higher-purity injectable standards as chronic disease protocols multiply. Solvay SA leverages its integrated soda ash-to-bicarbonate chain to sustain cost discipline across European supply. Tata Chemicals anchors South Asian production with dedicated pharmaceutical lines serving CDSCO-registered facilities. Dr. Paul Lohmann GmbH KG differentiates through custom particle-size engineering for effervescent tablet makers.
Pharma grade sodium bicarbonate is sodium hydrogen carbonate meeting pharmacopeial purity thresholds, typically manufactured via carbonation of sodium carbonate solution followed by crystallization, washing, and drying to achieve residual impurity levels below USP-NF and EP monograph limits. The material functions primarily as an active pharmaceutical ingredient in antacid preparations, as a buffering agent in parenteral solutions, and as a pH adjuster in hemodialysis concentrates. Injectable delivery mode commands premium positioning due to sterility and endotoxin control burdens, while oral formulations retain volume leadership across pharmacy and hospital channels. Drug formulation applications are deepening as biologic stability requirements drive excipient sophistication.
FDA enforces Current Good Manufacturing Practice for finished pharmaceuticals under 21 CFR Parts 210-211, directly governing batch release and validation protocols for US-bound material. EMA's revised Annex 1 on sterile manufacturing elevates environmental monitoring expectations for European injectable-grade production. India's CDSCO aligns with ICH Q7 guidelines through its active pharmaceutical ingredient inspection framework, tightening access for non-compliant foreign suppliers. Stakeholders must weigh regulatory divergence against scale economics when siting new pharmaceutical-grade capacity.
Market Dynamics
Injectable-grade sterility mandates are compressing batch yields and forcing capital redeployment toward closed-system carbonation and crystallization infrastructure. FDA endotoxin thresholds and EMA Annex 1 environmental monitoring requirements now govern capacity economics more than feedstock soda ash pricing.
Growth Catalysts
- EMA Annex 1 sterile manufacturing revisions:European injectable-grade producers face elevated environmental monitoring burdens that favor integrated manufacturers with captive analytical capabilities.
- Hemodialysis concentrate demand:Chronic kidney disease protocols in Germany and Japan are expanding parenteral bicarbonate consumption per patient treatment cycle.
- Carbonation process intensification:Continuous crystallization technologies are improving batch consistency for USP-NF compliance, reducing rework rates in high-purity lines.
Market Restraints
- Soda ash feedstock volatility:Synthetic soda ash production energy intensity ties pharmaceutical-grade bicarbonate margins to natural gas pricing in the US Gulf Coast and German chemical clusters.
- Chinese supply concentration:Shandong and Jiangsu provinces host disproportionate pharmaceutical-grade crystallization capacity, creating single-geography exposure for European and Indian formulators.
- Trona-based natural soda ash substitution:Wyoming-mined natural soda ash offers cost advantage but carries trace heavy metal variability that complicates USP-NF compliance.
Strategic Opportunities
- Indian CDSCO registration acceleration:Foreign suppliers completing active pharmaceutical ingredient inspections under ICH Q7 guidelines unlock access to domestic injectable manufacturers in Hyderabad and Ahmedabad.
- Effervescent tablet particle engineering:Custom granulometry specifications for direct-compression formulations command premium positioning in OTC pharmacy channels.
- Saudi Arabia and UAE hospital infrastructure:Greenfield dialysis center construction under national health transformation programs is absorbing import volumes previously routed through European distributors.
Industry Challenges
- Endotoxin testing capacity bottlenecks:Limulus amebocyte lysate assay throughput constraints are extending batch release timelines for sterile-grade material destined for parenteral applications.
- Legacy batch record digitization:Paper-based manufacturing execution systems in mid-scale European facilities are impeding real-time FDA 21 CFR Part 11 compliance audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharma Grade Sodium Bicarbonate Market |
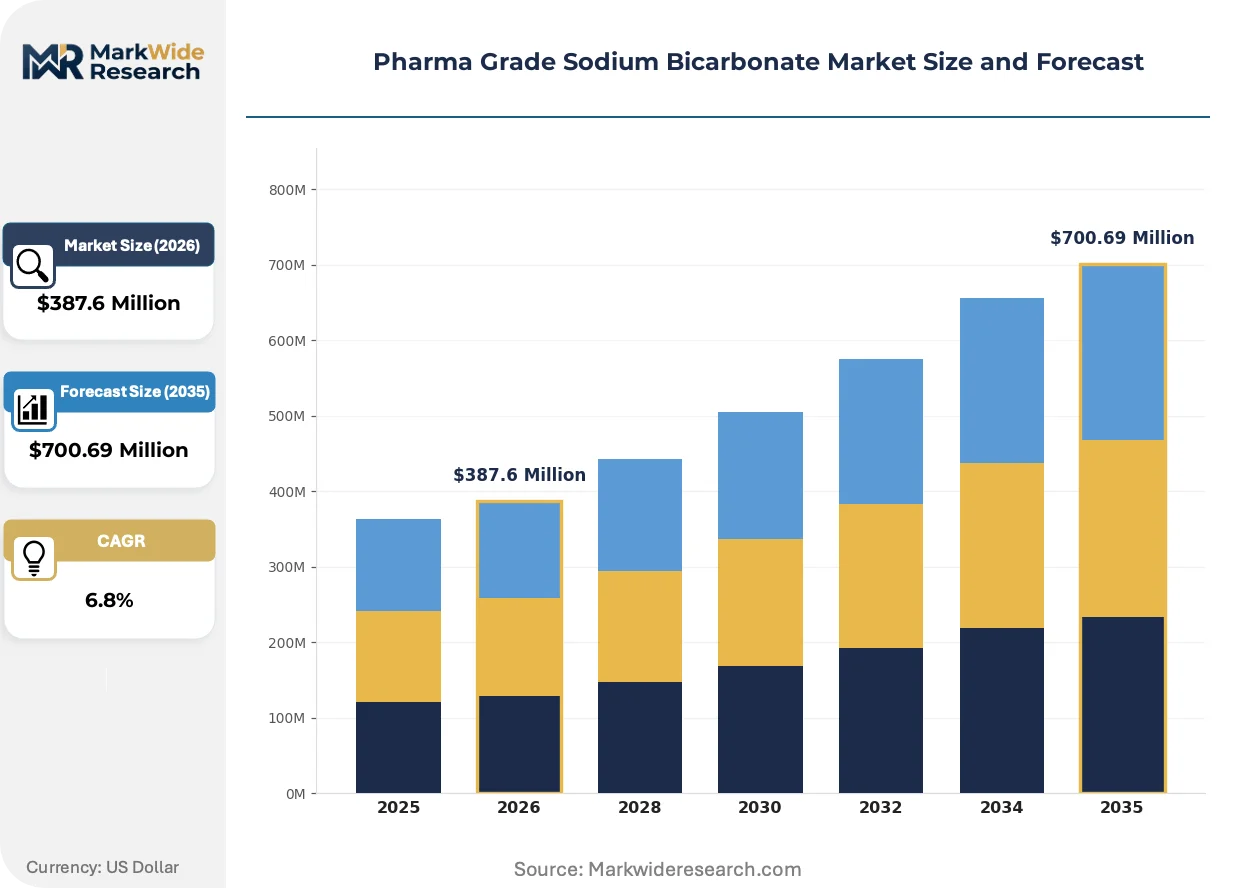
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Food Grade, Technical Grade, Pharmaceutical Grade, Industrial Grade Application: Antacid, Drug Formulation, pH Regulation, Nutritional Supplement Delivery Mode: Oral, Injectable, Topical, Inhalation End User: Pharmacies, Hospitals, Research Laboratories, Home Care |
| Companies Covered | Dr. Paul Lohmann GmbH KG, CIECH S.A., Solvay SA, Jost Chemical Co., Natural Soda LLC, Tata Chemicals, GHCL Limited, Tronox Alkali Corporation, Novacarb (Novacap Group), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharma Grade Sodium Bicarbonate Market Strategic Shifts
Process analytical technology integration is displacing offline quality control, while regulatory divergence between FDA and EMA is fragmenting validation protocols. These shifts are compressing the competitive set toward integrated chemical-pharmaceutical hybrids.
Continuous manufacturing using process analytical technology is supplanting batch crystallization in high-volume injectable-grade lines. Solvay and Tata Chemicals are retrofitting European and Indian facilities with inline particle-size and conductivity sensors. This technology is supplanting manual sampling protocols and enabling real-time release testing that halves batch cycle times.
EMA's revised Annex 1 on sterile manufacturing elevates environmental monitoring to continuous viable particle detection. European producers must install isolator-based carbonation units or risk exclusion from hemodialysis concentrate supply contracts. German and Swiss facilities are responding with barrier technology investments that add 15-20 percent to capital intensity per ton of output.
Hospital procurement consolidation is compressing supplier rosters to three approved vendors per geography. Pharmacy chains in the US and Germany are replacing distributor intermediaries with direct manufacturer contracts tied to annual volume commitments. This pattern is most visible in the US 340B program hospital networks and German hospital procurement cooperatives.
Pharma Grade Sodium Bicarbonate Market Segmentation
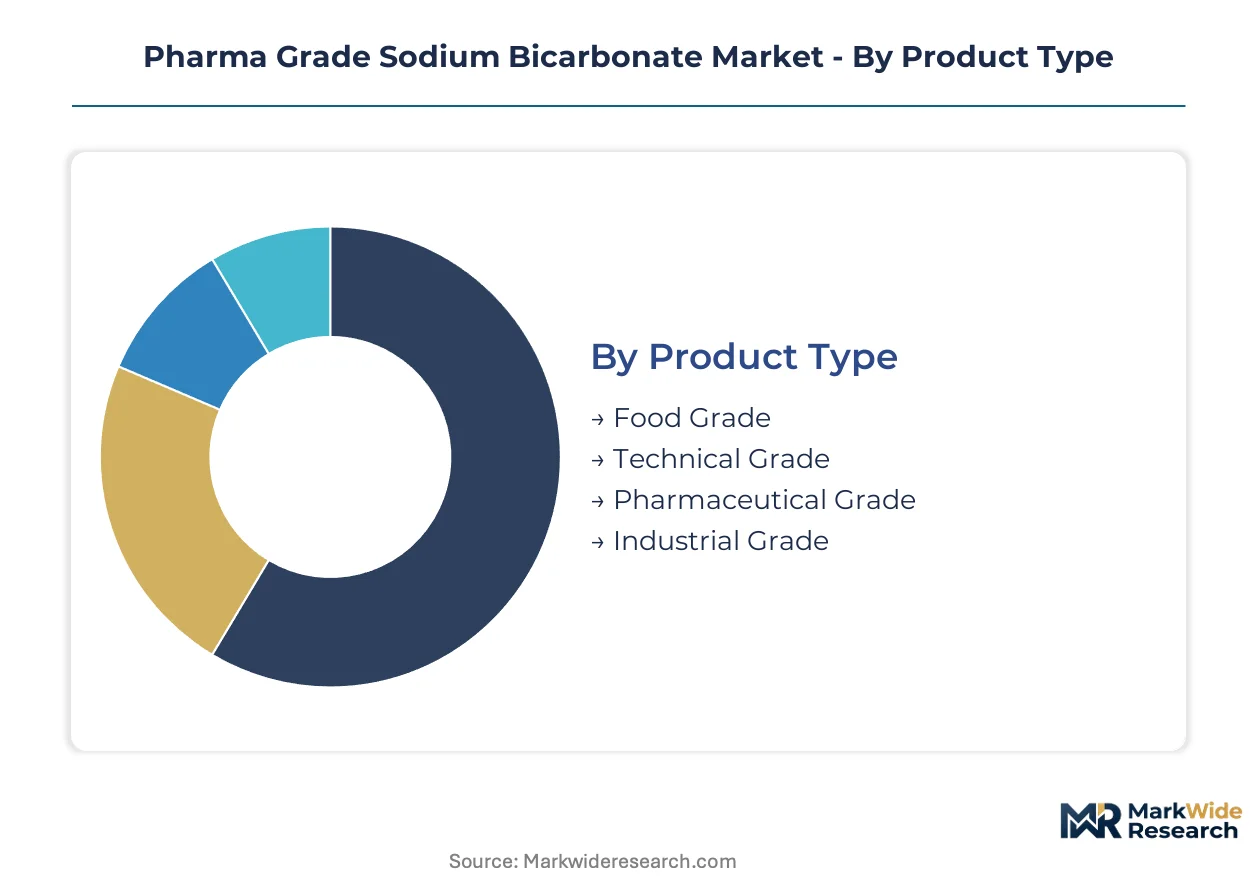
Pharma grade sodium bicarbonate flows through distinct channel configurations depending on sterility requirements and end-use criticality. Segmentation reveals how injectable grades command hospital direct contracts while oral formulations distribute through pharmacy wholesale networks.
Product Type:
Channel strategy diverges sharply between pharmaceutical-grade material and adjacent purity tiers, with only USP-NF compliant grades accessing parenteral supply chains.
- Pharmaceutical Grade:Sodium hydrogen carbonate meeting USP-NF and EP monograph purity thresholds, manufactured via controlled carbonation and crystallization with endotoxin monitoring. Hospital procurement cooperatives in Germany and the US 340B program absorb the majority of injectable-grade output under multi-year direct contracts.
- Food Grade:Lower-purity material governed by FCC standards, excluded from drug applications but serving nutritional supplement manufacturers with less stringent microbial limits. Distribution runs through food ingredient distributors rather than pharmaceutical wholesalers.
- Technical Grade:Industrial purity specifications for chemical synthesis and laboratory reagent applications, bypassing pharmacopeial validation entirely.
- Industrial Grade:Bulk material for non-pharmaceutical processes, sourced from commodity soda ash derivatives without crystallization refinement.
By volume, Food Grade leads across all channels. By growth pace, Pharmaceutical Grade is gaining share fastest as parenteral applications multiply.
Application:
Cost tier stratification separates commodity antacid tablets from high-value hemodialysis concentrates and biologic buffering applications.
- Drug Formulation:Excipient functions in effervescent tablets, parenteral solutions, and biologic stability protocols requiring precise particle-size distribution. CDSCO-registered facilities in Hyderabad and Ahmedabad are expanding sourcing of custom-granulometry material for direct-compression manufacturing.
- pH Regulation:Buffering agent in hemodialysis concentrates and dialysate preparation, where sterile-grade material commands premium positioning due to patient safety criticality. German and Japanese dialysis protocols are expanding per-patient bicarbonate consumption.
- Antacid:Active pharmaceutical ingredient in over-the-counter gastrointestinal relief products, manufactured to oral-grade specifications without endotoxin testing burdens.
- Nutritional Supplement:Alkalizing agent in sports nutrition and dietary products, competing with food-grade material on cost rather than pharmacopeial compliance.
By revenue contribution, pH Regulation dominates. By margin expansion, Drug Formulation is climbing the fastest.
Delivery Mode:
Volume concentration sits with oral administration, while margin capture favors sterile injectable formats subject to FDA 21 CFR Parts 210-211 and EMA Annex 1 oversight.
- Injectable:Sterile solutions for intravenous administration in critical care, hemodialysis, and metabolic acidosis treatment. EMA's revised Annex 1 environmental monitoring requirements are forcing barrier technology investments that add capital intensity per ton of output.
- Oral:Tablets, capsules, and effervescent powders for gastrointestinal and metabolic indications, retaining volume leadership across pharmacy and hospital channels without sterility validation costs.
- Topical:Limited dermatological and wound care applications with intermediate purity requirements between oral and injectable standards.
- Inhalation:Respiratory therapy applications requiring particle-size control for aerosol delivery, governed by specific pharmacopeial monographs for inhaled products.
By unit volume, Oral administration leads. By value per kilogram, Injectable is expanding most quickly.
End User:
Customer type determines procurement modality, with hospital networks consolidating supplier rosters while home care channels fragment across retail pharmacy.
- Hospitals:Integrated health systems and dialysis centers purchasing sterile-grade material through direct manufacturer contracts tied to annual volume commitments. German hospital procurement cooperatives and US 340B networks are compressing approved vendor lists to three per geography.
- Pharmacies:Retail and institutional channels for oral antacid and supplement products, increasingly served by direct manufacturer relationships replacing distributor intermediaries.
- Research Laboratories:Analytical and cell culture applications requiring documented purity certificates and batch traceability.
- Home Care:Patient-administered dialysis and nutritional supplementation, sourced through specialty pharmacy and direct-to-patient distribution models.
By procurement value, Hospitals lead. By channel expansion, Home Care shows the steepest trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances are redirecting pharmaceutical-grade bicarbonate flows as regional production capacity fails to match hospital demand growth. Shandong and Jiangsu provinces export disproportionate volumes toward European compounders. German and Indian facilities are absorbing redirected shipments previously routed through Dutch distributors.
United States
Wyoming-mined natural soda ash feeds domestic pharmaceutical-grade crystallization, though trace heavy metal variability complicates USP-NF compliance for injectable lines. FDA enforces Current Good Manufacturing Practice under 21 CFR Parts 210-211, governing batch release and validation protocols. The US Gulf Coast chemical cluster hosts synthetic soda ash production tied to natural gas pricing volatility.
Germany
Hospital procurement cooperatives consolidate supplier rosters to three approved vendors per geography for hemodialysis concentrate supply. EMA's revised Annex 1 on sterile manufacturing elevates environmental monitoring expectations, forcing barrier technology investments. The North Rhine-Westphalia industrial corridor anchors European injectable-grade capacity with integrated analytical capabilities.
China
Shandong and Jiangsu provinces concentrate disproportionate pharmaceutical-grade crystallization capacity, creating single-geography exposure for European and Indian formulators. The national pharmaceutical regulator enforces ICH Q7-aligned active pharmaceutical ingredient inspection frameworks. Yangtze River Delta facilities serve CDSCO-registered manufacturers in Hyderabad and Ahmedabad.
India
Domestic injectable manufacturers in Hyderabad and Ahmedabad expand sourcing of custom-granulometry material for direct-compression manufacturing. CDSCO aligns with ICH Q7 guidelines through its active pharmaceutical ingredient inspection framework, tightening access for non-compliant foreign suppliers. Gujarat's dedicated pharmaceutical lines anchor South Asian production for hospital procurement networks.
Saudi Arabia
Greenfield dialysis center construction under national health transformation programs absorbs import volumes previously routed through European distributors. The national pharmaceutical regulator enforces sterility standards for parenteral applications. Riyadh-based hospital infrastructure is expanding per-patient bicarbonate consumption through chronic kidney disease protocol adoption.
Pharma Grade Sodium Bicarbonate Market Competitive Environment
Concentration sits with integrated chemical-pharmaceutical hybrids possessing captive soda ash supply and in-house analytical capabilities. Mid-scale European facilities face exclusion from hemodialysis concentrate contracts without isolator-based carbonation investments. Three archetypes dominate: diversified chemical conglomerates with backward integration into feedstock production, regional specialists in custom particle-size engineering, and commodity producers pivoting toward pharmacopeial compliance. Competitive moves center on continuous crystallization technology licensing and direct hospital procurement contract capture.
Within the integrated chemical tier, Solvay SA and Tata Chemicals exemplify archetypes combining captive soda ash supply with pharmaceutical-grade finishing capacity. Dr. Paul Lohmann GmbH KG occupies a position among European specialists emphasizing custom engineering for effervescent tablet applications. These three entities represent distinct strategic postures: scale-driven feedstock integration, regional regulatory compliance depth, and formulation-specific technical differentiation.
| Leading Market Players |
|---|
| Dr. Paul Lohmann GmbH KG |
| CIECH S.A. |
| Solvay SA |
| Jost Chemical Co. |
| Natural Soda LLC |
| Tata Chemicals |
| GHCL Limited |
| Tronox Alkali Corporation |
| Novacarb (Novacap Group) |
| Others |
Value Chain & Pricing Dynamics
Ninety-day safety stock holdings among German hospital procurement cooperatives signal how inventory depth translates directly to contract pricing power for integrated manufacturers. This lead-time buffer allows buyers to withstand supply disruptions from Shandong and Jiangsu provinces, compressing spot premiums for non-contracted volumes.
Pricing Analysis
Hospital procurement cooperatives anchor contract-based long-term offtake structures that lock in annual volume commitments against fixed unit pricing. Price differentiation hinges on endotoxin certification tier and sterile-grade validation depth, with injectable material commanding substantial premiums over oral-grade equivalents. Cost compression in standard oral-grade tiers is intensifying because Chinese crystallization capacity expansion outpaces Western sterile-line investment. Research laboratories and compounding pharmacies exhibit highest price sensitivity, while integrated dialysis networks demonstrate lowest sensitivity due to patient safety criticality.
Supply Chain Analysis
Strategic stockpile preferences dominate among Japanese and German hospital networks, contrasting with just-in-time inventory models prevalent in Indian pharmaceutical manufacturing. Supply concentrates in China, India, and Germany, with crystallization capacity anchored in Shandong province and dedicated pharmaceutical lines in Gujarat. Raw material flows draw from synthetic soda ash in the US Gulf Coast and German chemical clusters, alongside Wyoming-mined natural trona. Single-geography exposure to Chinese crystallization infrastructure creates structural vulnerability to export licensing shifts. Distribution runs through direct manufacturer contracts to hospital procurement cooperatives, bypassing traditional pharmaceutical wholesalers for sterile-grade volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Continuous manufacturing adoption is reshaping competitive positioning, with process analytical technology integration creating winner-take-most dynamics among integrated producers.
For Market Incumbents: Shield market position by accelerating barrier technology investments for EMA Annex 1 compliance and securing captive soda ash supply through backward integration into feedstock production. Emerging Chinese crystallization capacity threatens margin structures for European oral-grade specialists lacking sterile-line differentiation. For New Entrants and Emerging Players: Differentiate on custom particle-size engineering for effervescent tablet direct-compression applications, targeting CDSCO-registered facilities in Hyderabad and Ahmedabad with granulometry specifications unavailable from commodity producers. White-space penetration favors Saudi Arabian greenfield dialysis center procurement, where European distributor relationships remain unconsolidated. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because sterile-grade validation burdens favor integrated chemical-pharmaceutical hybrids with in-house analytical capabilities over pure-play commodity producers. Acquisition targets should display captive feedstock supply and isolator-based carbonation infrastructure. Watch for EMA Annex 1 enforcement variance across German and Swiss facilities as inflection indicator for competitive exclusion dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Isolator-Based Carbonation Investment | EMA Annex 1 compliance secures hemodialysis concentrate supply contracts in German hospital networks. |
| CDSCO Registration Acceleration | ICH Q7-aligned inspections unlock access to domestic injectable manufacturers in Hyderabad and Ahmedabad. |
| Continuous Crystallization Technology Licensing | Process analytical technology integration halves batch cycle times for USP-NF compliance. |
| Custom Particle-Size Engineering Capability | Direct-compression granulometry specifications command premium positioning in OTC pharmacy channels. |
| Backward Integration into Soda Ash Supply | Captive feedstock production insulates margins from natural gas pricing volatility in European chemical clusters. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of FDA 21 CFR filings, EMA Annex 1 guidance documents, CDSCO inspection records, and customs trade data. Primary interviews engaged pharmaceutical plant managers, hospital procurement directors at German cooperatives, regulatory affairs leads at sodium bicarbonate manufacturers, and dialysis center supply chain heads. Secondary validation drew from USP-NF monograph revisions, ICH Q7 guideline updates, and SEC 10-K disclosures from integrated chemical producers. Bottom-up volume estimates from crystallization capacity utilization triangulate against top-down demand projections from hemodialysis patient population modeling.
Segmentation dimensions modeled span pharmaceutical grade tier, delivery mode, end-user channel, and regional regulatory cluster across the analysis window. CAGRs derive from regression analysis against historical price-volume relationships and capacity expansion announcements. Forecast inputs incorporate sterile-grade batch yield compression from endotoxin testing bottlenecks and continuous manufacturing adoption curves for process analytical technology.
Material uncertainties — feedstock energy cost volatility, Chinese export licensing shifts, and EMA Annex 1 enforcement variance — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable ICH Q7 alignment across CDSCO, FDA, and EMA jurisdictions. Revision becomes warranted when sterile-grade capacity utilization in Shandong and Jiangsu provinces crosses thresholds that trigger supply rationing to European compounders.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Citicoline Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Celecoxib API Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
Global Aspirin Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Antibiotics Active Pharmaceutical Ingredient (API) Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Metformin Hydrochloride API Market