
 Vitamins and Derivatives Market | 2026-2036
Vitamins and Derivatives Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamins and Derivatives Market Analytics
The EU Green Deal is consolidating demand around sustainably sourced vitamin precursors and lower-carbon fermentation pathways. DSM-Firmenich leverages integrated biotechnology platforms to secure positions in both human nutrition and animal feed vitamin streams. BASF anchors European supply through its Ludwigshafen complex while competing on carotenoid and vitamin E derivatives. Zhejiang NHU dominates bulk vitamin A and E intermediates through backward integration into petrochemical feedstocks.
Vitamins and derivatives comprise organic micronutrient compounds and their chemically modified forms, synthesized via fermentation, chemical synthesis, or extraction, with specifications typically expressed in international units per gram or as purified crystalline powders meeting pharmacopeial assay thresholds. These compounds primarily prevent deficiency disorders, enable metabolic cofactor functions, and serve as feed additives, pharmaceutical actives, and food fortificants. Vitamin D and Vitamin E product types command premium positioning due to expanding clinical evidence for immune and antioxidant applications. Animal nutrition and dietary supplements applications represent the deepest margin pools, while functional foods and fortified beverages face formulation stability challenges that constrain faster expansion.
FDA dietary supplement GMPs, EFSA health claim regulations, and China's NMPA pharmaceutical-grade vitamin standards collectively shape product purity requirements, label substantiation obligations, and cross-border market access conditions. Feed-grade vitamin manufacturers face additional scrutiny from EU REACH chemical registration and F-Gas Regulation constraints on solvent-based processes. Stakeholders must monitor evolving bioequivalence standards for derivative forms and the accelerating shift toward precision fermentation and cell-culture vitamin production methods.
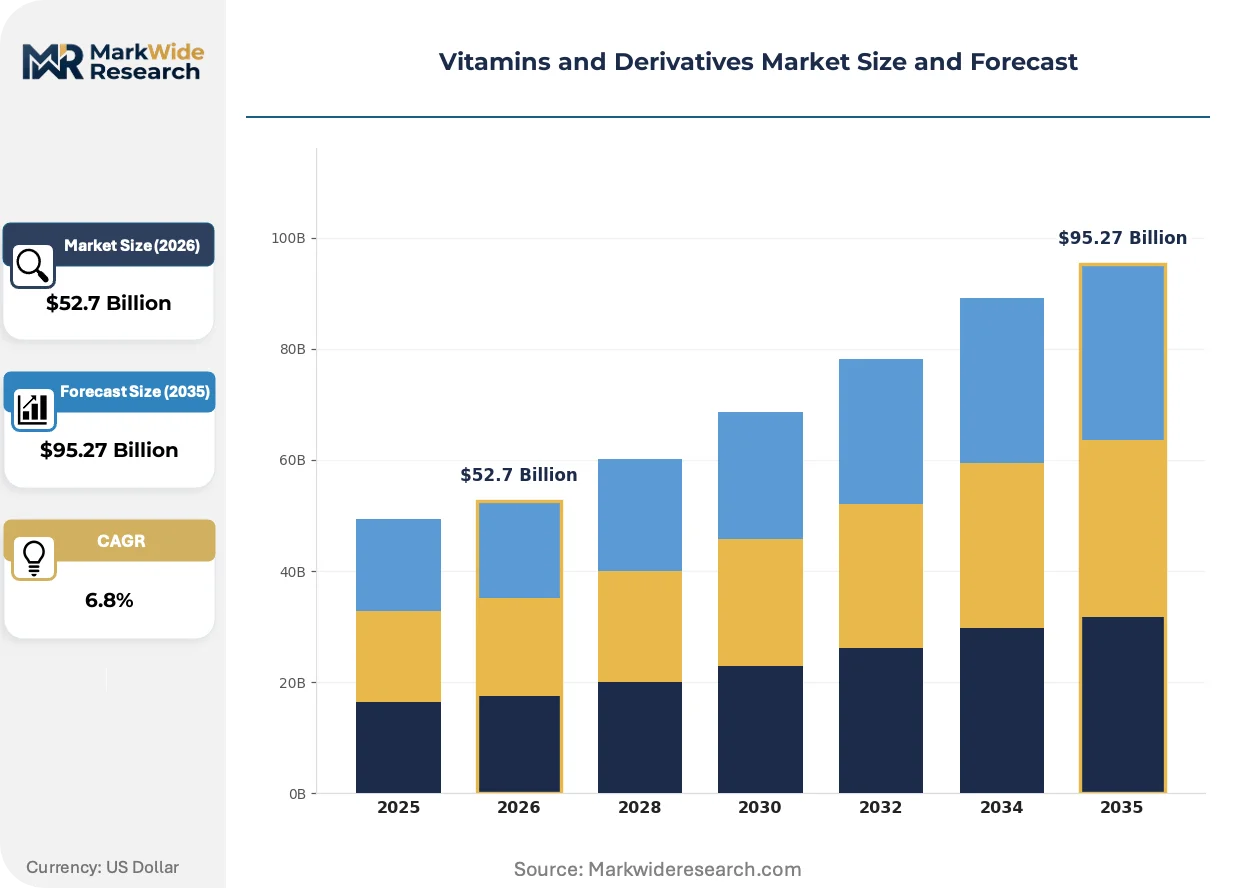
Market Dynamics
The EU Green Deal is forcing feed-grade vitamin manufacturers toward lower-carbon fermentation pathways and bio-based precursor sourcing, compressing margins for solvent-dependent producers while rewarding integrated biotechnology platforms.
Growth Catalysts
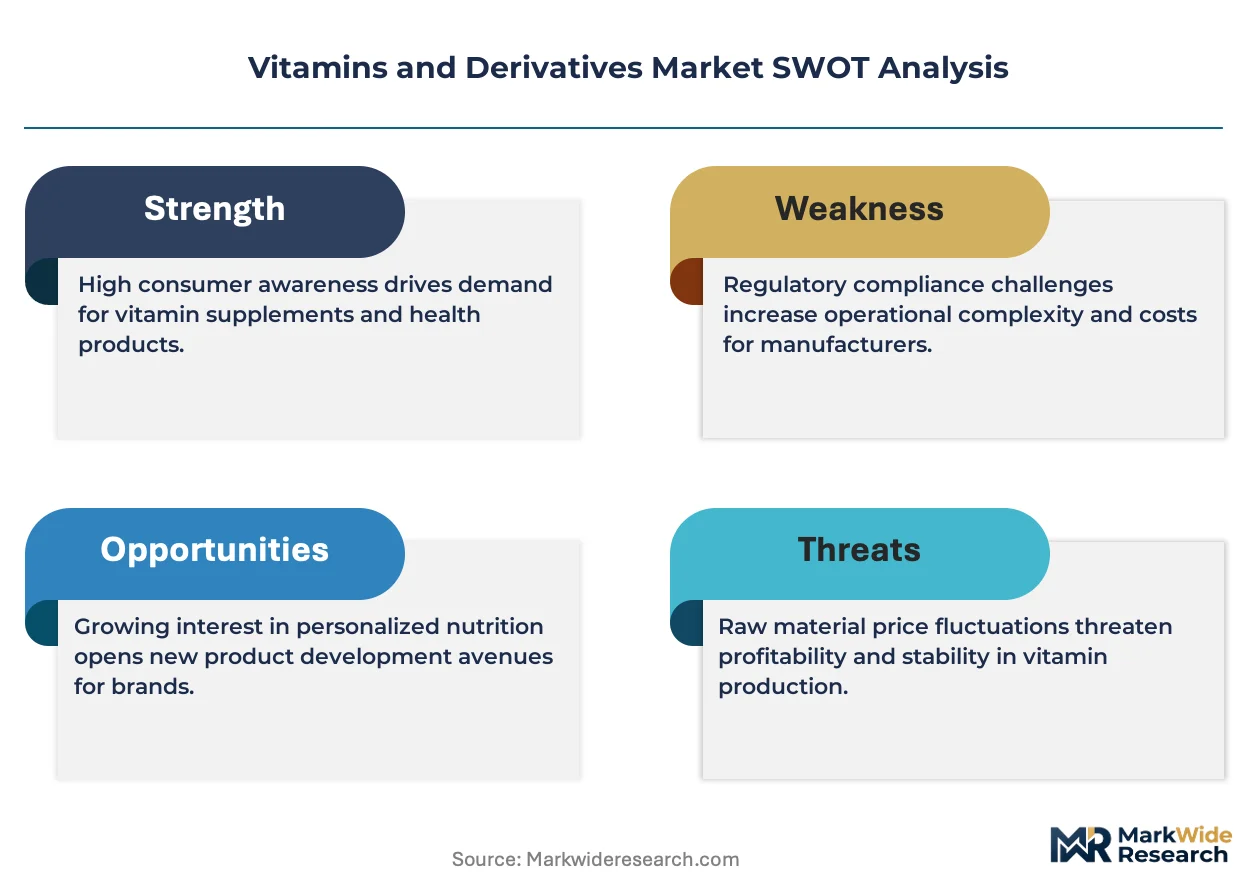
- EFSA health claim substantiation:Clinical validation of immune and antioxidant benefits for Vitamin D and Vitamin E derivatives is opening premium positioning in human nutrition applications.
- China's concentrated fermentation capacity:Cost-competitive bioprocessing infrastructure is drawing downstream formulation and packaging investments toward Zhejiang and Jiangsu provinces.
- Animal nutrition fortification mandates:EU livestock feed regulations are tightening minimum vitamin premix requirements, expanding volume commitments from compound feed manufacturers.
Market Restraints
- Petrochemical feedstock volatility:Bulk vitamin A and E intermediates depend on crude-derived acetone and isophytol, exposing margin stability to energy market swings.
- Raw material supply concentration:China dominates precursor chemical production, creating single-source vulnerability for European and North American formulators.
- F-Gas Regulation constraints:Solvent-based vitamin extraction processes face phase-down schedules under EU fluorinated gas rules, requiring capital-intensive process redesign.
Strategic Opportunities
- Precision fermentation scale-up:Cell-culture vitamin production methods are approaching commercial viability for pharmaceutical-grade specifications.
- India dietary supplement underpenetration:FSSAI regulatory harmonization and PLI scheme incentives are attracting contract manufacturing investments for export-oriented vitamin premix facilities.
- Functional beverage stability solutions:Microencapsulation and lipid-delivery technologies are resolving formulation degradation barriers in fortified drinks.
Industry Challenges
- Pharmacopeial assay compliance:USP and EP monograph updates for derivative forms are extending analytical validation timelines for new product registrations.
- Cross-platform bioprocess integration:Fermentation and chemical synthesis hybrid workflows require specialized metabolic engineering talent scarce outside Basel and Shanghai clusters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamins and Derivatives Market |
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $95.27 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin A, Vitamin C, Vitamin D, Vitamin E Application: Dietary Supplements, Functional Foods, Fortified Beverages, Animal Nutrition Form: Tablets, Capsules, Powders, Liquids End User: Retail Consumers, Healthcare Providers, Food Manufacturers, Gym Enthusiasts |
| Companies Covered | Prinova, Bactolac Pharmaceutical, DSM-Firmenich, CSPC Pharmaceutical Group, Zhejiang NHU, BASF, Vitaquest International, Kemin Industries, Merck KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamins and Derivatives Market Evolving Landscape
Biotechnology platforms are modularizing vitamin production workflows, while regulatory tightening around sustainability claims and supply chain transparency is compressing traditional competitive advantages.
Continuous fermentation systems with real-time metabolite monitoring are modularizing batch vitamin manufacturing into plug-and-play unit operations. Animal feed compounders in the Netherlands and Denmark are piloting these configurations for vitamin B2 and B12 production. The shift is compressing capital deployment timelines and enabling distributed manufacturing closer to formulation sites.
EU REACH chemical registration is tightening substance data requirements for vitamin derivatives imported from non-European Economic Area suppliers. The regulation is forcing third-country manufacturers to establish European legal entities or joint registration consortia. Feed-grade vitamin premix suppliers with Ludwigshafen or Geleen manufacturing footprints are capturing re-registration service revenue from Asian exporters.
Direct-to-practitioner distribution is displacing traditional wholesale channels for clinical nutrition vitamin formulations. Functional medicine clinics and integrative health networks are consolidating procurement through specialized distributors with cold-chain and lot-traceability capabilities. The pattern is most visible in Germany and Switzerland, where pharmacy compounding regulations permit customized vitamin derivative dosing.
Vitamins and Derivatives Market Segmentation
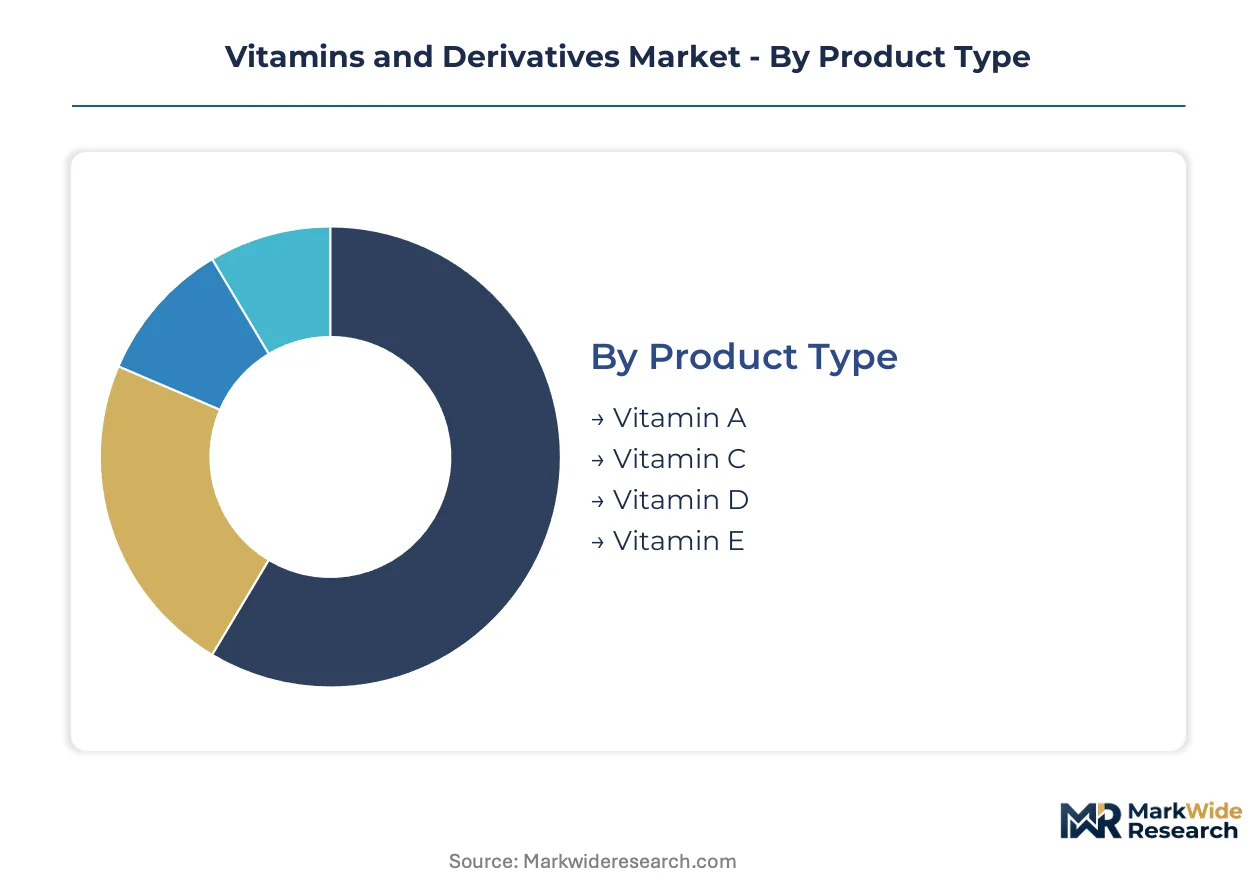
Vitamin and derivative segmentation reflects divergent technical specifications across pharmaceutical, nutraceutical, and feed applications. Each category captures distinct margin structures, regulatory pathways, and buyer procurement behaviors that reshape competitive positioning.
Product Type:
Formulation complexity and clinical validation depth drive buyer selection across vitamin categories.
- Vitamin A:Retinol and retinyl ester derivatives serve vision health and epithelial tissue maintenance specifications. Demand concentrates in animal feed fortification across the Netherlands and Denmark due to EU livestock nutrition mandates tightening premix inclusion rates.
- Vitamin D:Cholecalciferol and ergocalciferol forms command premium positioning through expanding immune function clinical evidence. Healthcare providers in Germany and Switzerland are consolidating procurement through direct-to-practitioner channels with cold-chain lot-traceability requirements.
- Vitamin C:Ascorbic acid and mineral ascorbates dominate volume production through established fermentation infrastructure in Zhejiang province.
- Vitamin E:Tocopherol and tocotrienol derivatives depend on isophytol precursors from petrochemical feedstocks, exposing margin stability to acetone price volatility.
Vitamin E leads on scale; Vitamin D leads on momentum.
Application:
Regulatory substantiation requirements and formulation stability challenges create divergent margin pools across end-use sectors.
- Dietary Supplements:Capsule and tablet formats targeting immune and antioxidant positioning face FDA GMP compliance and EFSA health claim validation timelines. Retail consumers in Germany and Switzerland are shifting procurement toward practitioner-dispensed clinical nutrition formulations with customized dosing protocols.
- Animal Nutrition:Feed-grade vitamin premixes for poultry, swine, and ruminant applications operate under EU REACH registration and F-Gas Regulation solvent constraints. Compound feed manufacturers in the Netherlands and Denmark are piloting continuous fermentation systems for vitamin B2 and B12 production.
- Functional Foods:Bakery, dairy, and cereal fortification applications confront thermal degradation and shelf-life stability barriers requiring microencapsulation investments.
- Fortified Beverages:Liquid vitamin dispersion in juices and sports drinks faces pH-dependent degradation challenges constraining faster expansion.
Animal Nutrition leads on scale; Fortified Beverages leads on momentum.
Form:
Manufacturing capital intensity and bioavailability engineering specifications shape procurement decisions across delivery formats.
- Tablets:Direct compression and granulation processes dominate high-volume dietary supplement production with established USP dissolution standards.
- Capsules:Gelatin and hydroxypropyl methylcellulose shells enable moisture-sensitive vitamin protection and modified-release formulations.
- Powders:Bulk premix and sachet applications serve food manufacturing and clinical compounding with blend uniformity validation requirements.
- Liquids:Emulsion and micellar delivery systems resolve lipophilic vitamin dispersion for pediatric and geriatric populations with swallowing difficulties.
Tablets lead on scale; Liquids leads on momentum.
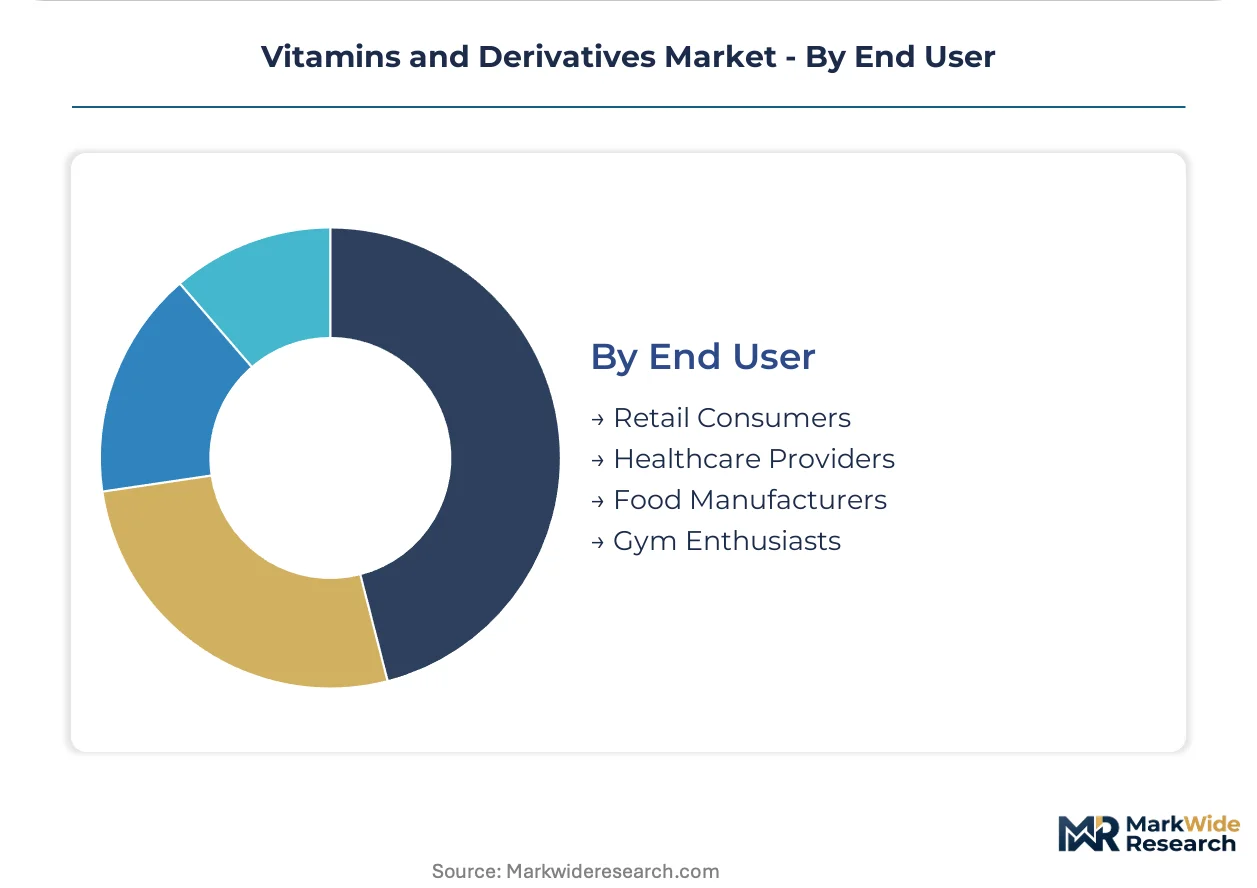
End User:
Channel structure and purchasing authority fragmentation create distinct service requirements across buyer categories.
- Retail Consumers:Mass-market and specialty vitamin purchasing through pharmacies, e-commerce, and direct-to-consumer subscription models.
- Healthcare Providers:Functional medicine clinics and integrative health networks in Germany and Switzerland consolidating procurement through specialized distributors.
- Food Manufacturers:Industrial vitamin premix procurement for bakery, dairy, and beverage fortification with FSSAI and FDA compliance documentation.
- Gym Enthusiasts:Sports nutrition and performance-oriented vitamin stacks through specialty retailers and fitness center distribution.
Retail Consumers leads on scale; Healthcare Providers leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vitamins and derivatives industry traces its modern scale to post-war pharmaceutical chemistry advances in Basel and Ludwigshafen, where integrated fermentation and petrochemical processing first achieved industrial vitamin A and E production. These European origins established quality standards and regulatory frameworks that now govern worldwide trade.
Germany
Ludwigshafen hosts BASF's integrated vitamin E and carotenoid complex, serving compound feed manufacturers across the Netherlands and Denmark. EFSA health claim regulations and EU REACH chemical registration enforce stringent purity documentation for derivative forms exported throughout the European Economic Area. Continuous fermentation pilots for vitamin B2 and B12 are operational in Geleen, drawing technology licensing interest from Asian premix suppliers.
China
Zhejiang province concentrates global fermentation capacity for vitamin C and bulk vitamin A intermediates, with Jiangsu province adding downstream formulation and packaging investments. NMPA pharmaceutical-grade standards and dual carbon goals are tightening energy efficiency requirements for acetone-dependent vitamin E precursor synthesis. Cost-competitive bioprocessing infrastructure in the Yangtze River Delta is capturing contract manufacturing for European and North American dietary supplement brands.
United States
FDA dietary supplement GMPs and USP monograph updates shape analytical validation requirements for retinol and tocopherol derivatives distributed through direct-to-practitioner channels. DSM-Firmenich maintains biotechnology platforms serving both human nutrition and animal feed vitamin streams. Functional medicine clinics in California and New York Metro are consolidating procurement through specialized distributors with cold-chain lot-traceability capabilities.
India
FSSAI regulatory harmonization and PLI scheme incentives are attracting export-oriented vitamin premix facility investments in Maharashtra and Gujarat. Contract manufacturers serve European and North American dietary supplement brands seeking cost-competitive tablet and capsule production. The underpenetrated domestic supplement market is drawing distribution partnerships from Zhejiang-based fermentation specialists.
Switzerland
Swissmedic pharmaceutical regulations and integrative health network procurement patterns favor clinical nutrition formulations with customized vitamin derivative dosing. DSM-Firmenich anchors European supply positions through biotechnology platforms spanning human and animal nutrition. Basel-area metabolic engineering talent supports hybrid fermentation-chemical synthesis workflows for pharmaceutical-grade specifications.
Vitamins and Derivatives Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the vitamins and derivatives sector, with integrated fermentation complexes facing pressure from specialized formulation houses. The market structure concentrates around biotechnology platforms with backward integration into petrochemical or bio-based precursors. Three archetypes dominate: integrated chemical-pharmaceutical conglomerates with Ludwigshafen or Basel-area manufacturing footprints, Chinese fermentation specialists with Zhejiang province cost structures, and contract manufacturers serving branded dietary supplement distributors. Competitive moves center on precision fermentation scale-up investments and distributed manufacturing partnerships closer to formulation sites.
Within the integrated chemical-pharmaceutical tier, DSM-Firmenich and BASF occupy positions spanning human nutrition and animal feed vitamin streams. Zhejiang NHU exemplifies the Chinese fermentation specialist archetype with concentrated bulk vitamin A and E intermediate production. Among contract manufacturing specialists, Bactolac Pharmaceutical represents the asset-light formulation house model serving branded distributors.
| Leading Market Players |
|---|
| Prinova |
| Bactolac Pharmaceutical |
| DSM-Firmenich |
| CSPC Pharmaceutical Group |
| Zhejiang NHU |
| BASF |
| Vitaquest International |
| Kemin Industries |
| Merck KGaA |
| Others |
Value Network & Pricing Analysis
Backward integration into petrochemical feedstocks and fermentation capacity anchors pricing power for bulk vitamin A and E producers in Zhejiang province, while European formulators absorb premium positions through EFSA health claim substantiation and REACH compliance services. This structural divide separates cost-competitive intermediate suppliers from margin-rich derivative specialists serving clinical nutrition channels in Germany and Switzerland.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, feed-grade, and food-grade certification levels stratifies the market, with USP and EP monograph compliance commanding substantial premia over FSSAI-aligned export specifications. Price differentiation rests on analytical validation depth and cold-chain lot-traceability capabilities rather than raw material input costs. Cost compression in feed-grade tocopherol derivatives is intensifying because acetone price volatility feeds directly into isophytol precursor economics. Compound feed manufacturers in the Netherlands and Denmark exhibit highest price sensitivity, while functional medicine clinics in Switzerland accept premium positioning for customized cholecalciferol dosing protocols.
Supply Chain Analysis
Metabolic engineering talent scarcity in Basel and Shanghai clusters constrains scale-up timelines for precision fermentation platforms targeting pharmaceutical-grade vitamin specifications. Manufacturing gravity centers on China for fermentation-derived ascorbic acid and bulk retinol intermediates, Germany for carotenoid and tocopherol derivative finishing, and India for export-oriented tablet and capsule formulation. Raw material flows draw from crude-derived acetone and isophytol for vitamin E synthesis, corn-derived dextrose for fermentation substrates, and petrochemical feedstocks for vitamin A precursors. Single-source vulnerability concentrates in Zhejiang province precursor chemical production. Distribution runs through direct-to-practitioner channels displacing traditional wholesale for clinical nutrition formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory compounder, with EU Green Deal carbon intensity mandates and F-Gas Regulation phase-down schedules accelerating demand for bio-based precursor sourcing and lower-carbon fermentation pathways.
For Market Incumbents: Extend biotechnology platform investments into continuous fermentation configurations with real-time metabolite monitoring, compressing capital deployment timelines for vitamin B2 and B12 production. Secure backward integration into bio-based precursor supply through partnerships with agricultural feedstock processors, defending against margin erosion from petrochemical price volatility. Anchor European legal entity structures to capture REACH re-registration service revenue from Asian exporters facing tightened substance data requirements.
For New Entrants and Emerging Players: Begin with contract manufacturing partnerships serving European and North American dietary supplement brands seeking cost-competitive Zhejiang-based fermentation capacity with FSSAI and FDA compliance documentation. Target India's underpenetrated domestic supplement market through distribution partnerships with Maharashtra and Gujarat premix facilities benefiting from PLI scheme incentives. Pursue microencapsulation technology licensing as the go-to-market angle for functional beverage stability solutions resolving pH-dependent degradation barriers.
For Investors and Strategic Acquirers: Roll-up economics work for specialized formulation houses with cold-chain and lot-traceability capabilities because direct-to-practitioner channel displacement concentrates procurement authority among fewer distributor entities. Five-to-ten-year viability favors asset-light designers with practitioner network relationships over capital-heavy fermentation complexes facing carbon transition costs. Target acquisition archetype: clinical nutrition specialists with customized vitamin derivative dosing protocols and Swissmedic regulatory positioning. Monitor precision fermentation scale-up milestones as the inflection signal for pharmaceutical-grade production cost parity.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Scale-Up | Modular plug-and-play configurations in Geleen compress vitamin B2 and B12 deployment timelines. |
| Backward Integration into Bio-Based Precursors | Agricultural feedstock partnerships reduce acetone price volatility exposure for tocopherol derivatives. |
| REACH Re-Registration Service Expansion | Ludwigshafen manufacturing footprints capture compliance revenue from Asian vitamin premix exporters. |
| Microencapsulation Technology Licensing | Lipid-delivery systems resolve thermal degradation barriers constraining fortified beverage expansion. |
| Direct-to-Practitioner Channel Development | Cold-chain lot-traceability capabilities consolidate procurement through German functional medicine networks. |
Research Methodology
Bottom-up animal nutrition and dietary supplement modeling reconciled against top-down fermentation capacity and petrochemical feedstock tracking forms the analytical core of this study. Primary interviews with compound feed procurement managers, pharmaceutical formulation scientists, regulatory affairs specialists at DSM-Firmenich and BASF, and functional medicine clinic distributors combined with secondary validation from NMPA pharmaceutical-grade standards documentation, EFSA health claim registers, EU REACH substance data submissions, and FSSAI regulatory harmonization notices. This dual approach enables triangulation between demand-side volume commitments and supply-side production constraints.
Input-output matrices mapping acetone and isophytol precursor flows through vitamin E synthesis pathways, dextrose fermentation yields for ascorbic acid production, and retinol intermediate conversion rates inform volume projections across the analysis window. Segmentation dimensions include product type (vitamin A, D, C, E), application (dietary supplements, animal nutrition, functional foods, fortified beverages), form (tablets, capsules, powders, liquids), and end user (retail consumers, healthcare providers, food manufacturers, gym enthusiasts). CAGRs derive from slope-intercept modeling of historical capacity additions correlated with EFSA regulatory milestone timing and EU livestock feed mandate implementation schedules.
Several conditions sit outside the modeled scope, including abrupt petrochemical feedstock price shocks, rapid precision fermentation cost breakthroughs, and trade policy disruptions affecting Zhejiang province export flows. Forecasts reflect assumptions around EFSA health claim validation timelines, F-Gas Regulation phase-down adherence, and PLI scheme incentive continuity. Material deviation in EU Green Deal carbon intensity enforcement or NMPA energy efficiency standard tightening warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Sulphonamides Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Growth Hormone Inhibiting Hormone Drugs Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Scopolamine Market
Pharmaceutical Ingredients
Originator Small Molecule Drug Market
Pharmaceutical Ingredients
Montelukast API Market
Pharmaceutical Ingredients
Oral Transmucosal Drugs Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Furosemide Market