
 Nortriptyline Hydrochloride Market | 2026-2036
Nortriptyline Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Nortriptyline Hydrochloride Market Insights
Psychiatric clinic procurement is collapsing toward long-term maintenance protocols while hospital emergency departments scale back acute tricyclic prescribing. Teva Pharmaceutical Industries leverages vertical integration across active pharmaceutical ingredient synthesis and finished dosage manufacturing to protect margin pools on oral solid forms. Pfizer anchors the branded legacy segment through established physician familiarity with original nortriptyline formulations. Dr. Reddy's Laboratories competes aggressively on abbreviated new drug application filings, sustaining price pressure across mature markets.
Nortriptyline hydrochloride is a dibenzocycloheptene-derivative tricyclic antidepressant with the molecular formula C19H21N·HCl, functioning as a potent norepinephrine and serotonin reuptake inhibitor prescribed for major depressive disorder, neuropathic pain, and migraine prevention. Tablet formulations dominate volume throughput due to manufacturing simplicity and decades of clinical familiarity, though capsule variants capture niche demand where excipient sensitivity complicates therapy. Pain Management applications now outpace traditional Depression prescribing in growth velocity as off-label neuropathic indications expand prescriber comfort. Hospital distribution channels retain bulk purchasing leverage, yet online pharmacies extend reach into rural patient populations previously underserved by brick-and-mortar retail.
FDA bioequivalence requirements under 21 CFR 320 govern generic substitution thresholds, while USP monographs enforce dissolution specification uniformity across manufacturers. The Drug Enforcement Administration maintains scheduling oversight that constrains production quota flexibility for controlled-substance analogs. EMA's Committee for Medicinal Products for Human Use periodically reviews tricyclic antidepressant benefit-risk profiles, influencing prescriber liability perceptions across European markets. Stakeholders must monitor FDA draft guidance on in-vitro dissolution testing modifications that could trigger reformulation investments or portfolio pruning decisions.
Market Dynamics
Generic pharmaceutical manufacturers now capture procurement volumes as FDA bioequivalence standards under 21 CFR 320 reshape formulation requirements and force portfolio rationalization among multi-source suppliers.
Growth Catalysts
- Neuropathic pain protocols:Psychiatric clinics expand off-label prescribing for diabetic neuropathy and post-herpetic neuralgia, extending nortriptyline utility beyond depression into pain management verticals.
- USP monograph updates:Dissolution specification uniformity enforcement creates compliance barriers that filter out subscale manufacturers, concentrating volume among qualified suppliers.
- Managed care formularies:United States payers prioritize cost-effective tricyclic antidepressant therapy over newer agents, sustaining volume throughput for mature oral solid forms.
Market Restraints
- Active pharmaceutical ingredient concentration:Synthesis capabilities cluster among Indian and Chinese contract manufacturers, creating single-source vulnerability for generic finished dosage producers.
- Cardiotoxicity liability:QT prolongation risk constrains dosing flexibility and requires electrocardiographic monitoring protocols that elevate treatment costs.
- Serotonin-norepinephrine reuptake inhibitor substitution:Duloxetine and venlafaxine displace tricyclics in depression-first prescribing, compressing addressable patient pools for nortriptyline monotherapy.
Strategic Opportunities
- Rural pharmacy networks:Online pharmacy distribution extends reach into underserved United States populations beyond brick-and-mortar retail catchment areas.
- Migraine prophylaxis expansion:Neurology practices adopt low-dose protocols for chronic migraine prevention, opening indication expansion pathways.
- EMA benefit-risk reassessment:Committee for Medicinal Products for Human Use periodic reviews create windows for prescriber education campaigns that recalibrate liability perceptions across European markets.
Industry Challenges
- Dissolution testing expertise:In-vitro method development for modified-release formulations requires analytical chemistry capabilities scarce among mid-scale generic houses.
- Legacy equipment revalidation:FDA draft guidance modifications trigger costly reformulation investments or forced portfolio pruning for oral solid lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nortriptyline Hydrochloride Market |
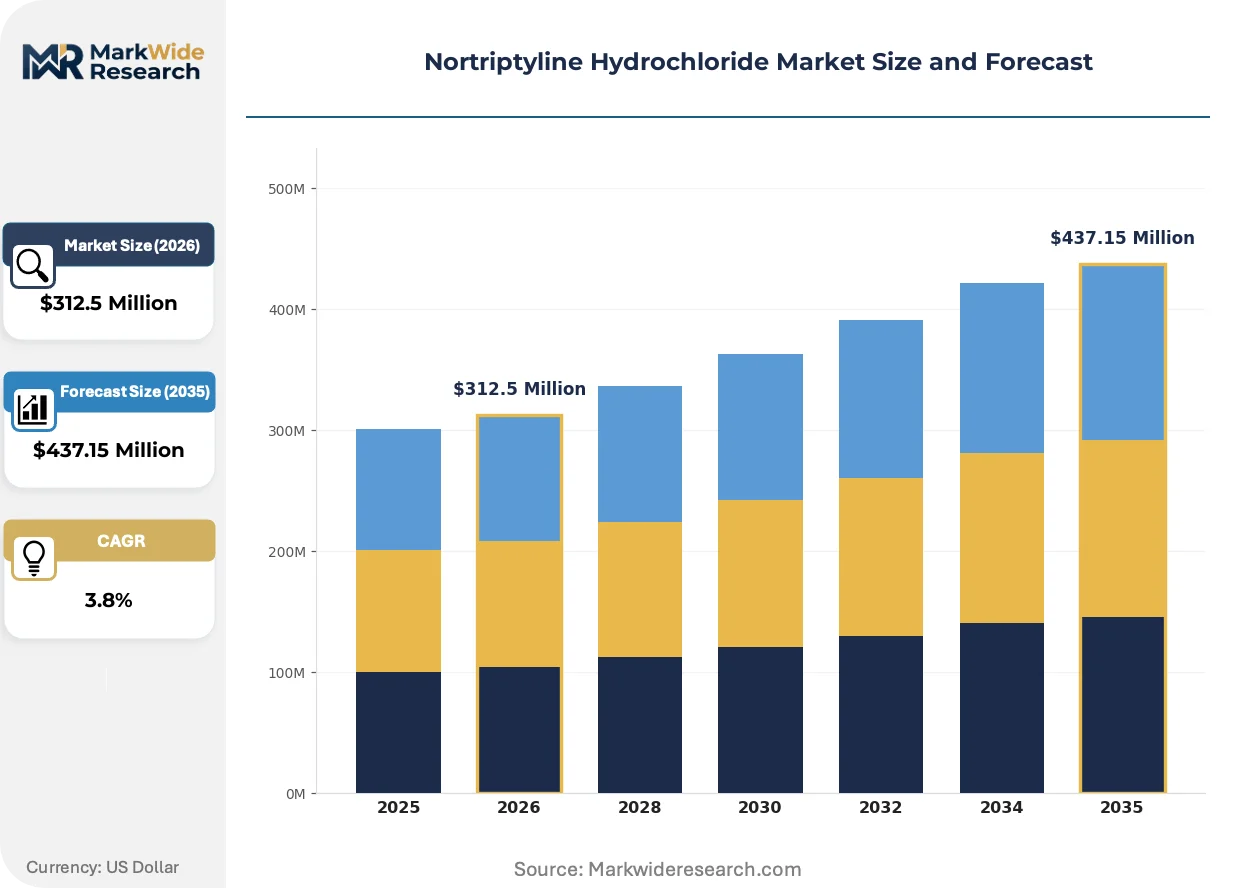
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $437.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
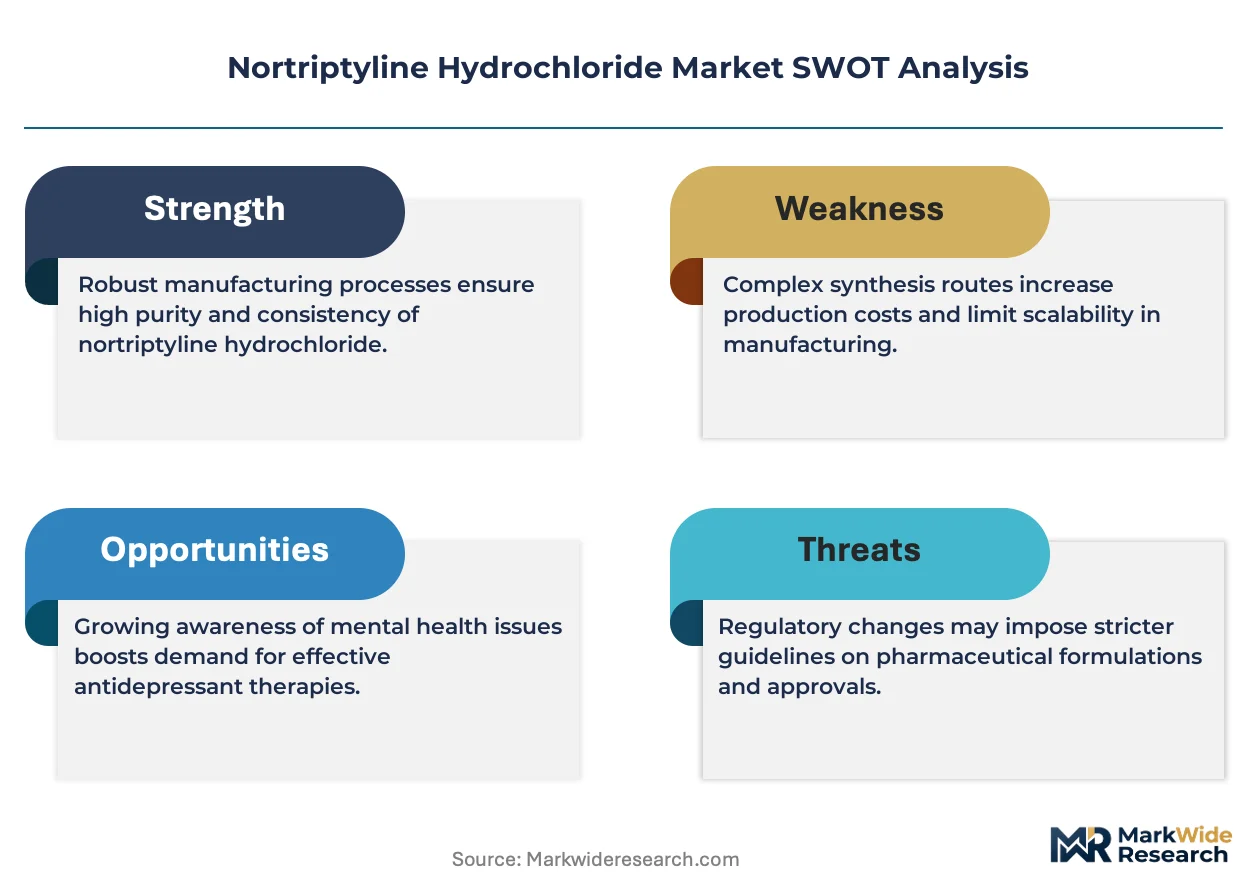
| Segmentation | Form: Tablet, Capsule, Solution, Injectable Distribution Channel: Pharmacies, Hospitals, Online Stores, Drug Distributors End User: Patients, Healthcare Providers, Research Institutions, Clinics Application: Depression, Anxiety Disorders, Pain Management, Neuropathic Disorders |
| Companies Covered | Pfizer, Novartis, Teva Pharmaceutical Industries, Mylan, Sandoz, Taro Pharmaceutical Industries, Dr. Reddy's Laboratories, Aurobindo Pharma, Eli Lilly and Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nortriptyline Hydrochloride Market Trends and Innovations
Formulation science and distribution architecture are undergoing parallel transformation as regulatory stringency rises and patient access models fragment across digital and physical channels.
Modified-release matrix technologies are fragmenting competitive positioning among oral solid manufacturers. Hydrophilic polymer systems enable once-daily dosing that improves adherence in chronic pain populations. Hospital systems and long-term care facilities are adopting these formulations at accelerating pace. The technology is fragmenting margin pools between premium modified-release products and commoditized immediate-release tablets.
EMA's Committee for Medicinal Products for Human Use has intensified tricyclic antidepressant benefit-risk surveillance, requiring updated cardiovascular safety data packages. This regulatory pressure is compressing approval timelines for generic entrants and elevating documentation burdens. European markets are responding with heightened pharmacovigilance investments and prescriber liability insurance adjustments.
Telehealth prescribing platforms are compressing the traditional physician-pharmacy-patient triad into direct-to-door fulfillment models. Rural patient populations previously dependent on retail pharmacy access now receive maintenance therapy through mail-order channels. This behavioral shift is most visible in United States markets where managed care formularies incentivize 90-day supply fulfillment through preferred online pharmacy networks.
Nortriptyline Hydrochloride Market Segmentation
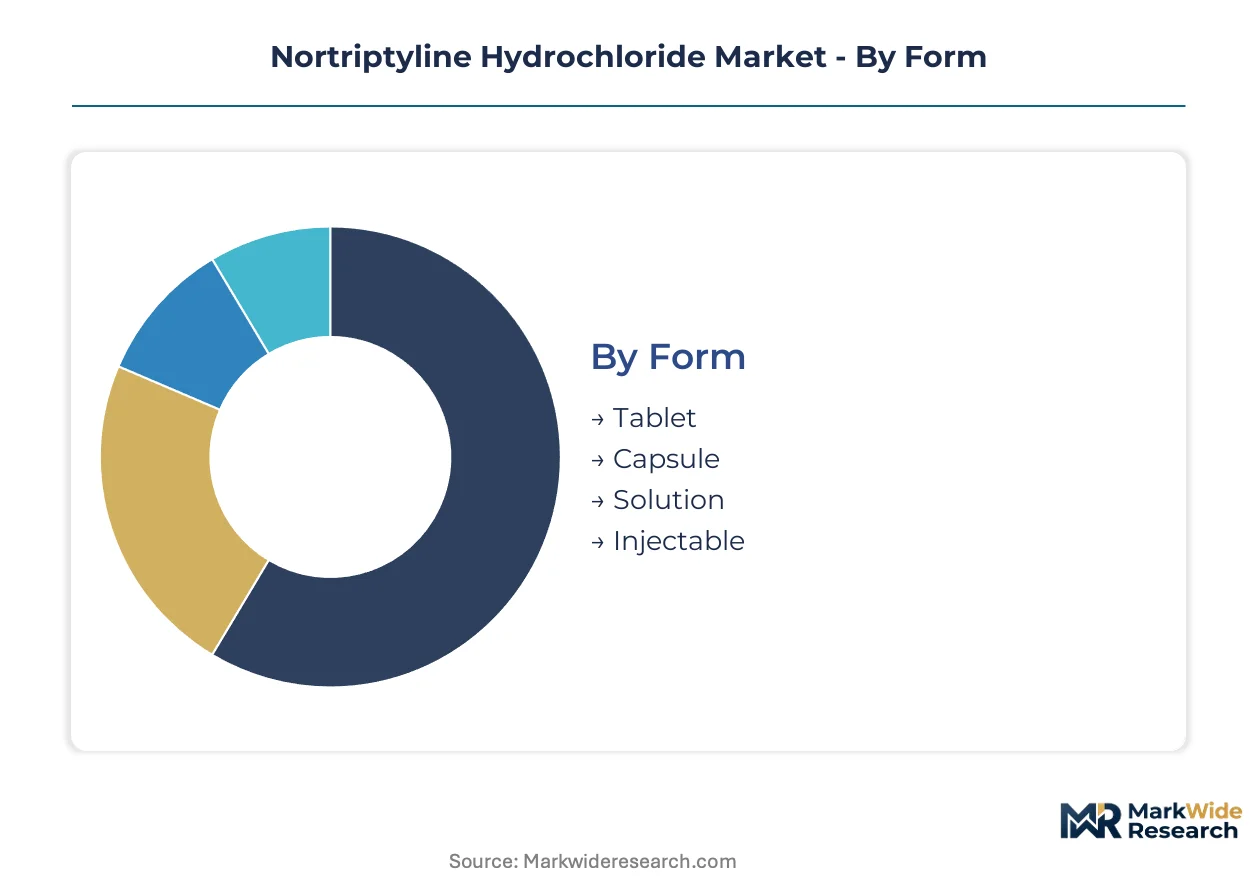
Nortriptyline hydrochloride's therapeutic versatility across psychiatric and pain indications fragments demand across formulation types and procurement channels. Generic manufacturers optimize portfolio mix against FDA bioequivalence thresholds while psychiatric clinics and pain management centers drive volume concentration in specific application verticals.
Form:
Tablet formulations flow through retail pharmacy and mail-order channels at highest velocity, while hospital procurement concentrates on injectable and solution variants for acute administration protocols.
- Tablet:Immediate-release compressed solids containing nortriptyline hydrochloride as the active pharmaceutical ingredient dominate manufacturing throughput due to decades of clinical familiarity and established USP dissolution specifications. Psychiatric clinics in the United States prescribe tablets for maintenance therapy in major depressive disorder, with managed care formularies prioritizing this cost-effective oral solid form over newer antidepressant classes.
- Capsule:Gelatin-encapsulated formulations accommodate patients with excipient sensitivities to tablet binders, capturing niche demand in specialized pain management practices. Neuropathic pain protocols in long-term care facilities favor capsules where modified-release polymer matrices enable once-daily dosing adherence.
- Solution:Liquid oral formulations serve pediatric populations and geriatric patients with dysphagia, distributed primarily through hospital outpatient pharmacies and specialty compounding networks.
- Injectable:Parenteral solutions reserve for emergency department acute agitation protocols and inpatient psychiatric units where oral administration is contraindicated.
Tablet dominates installed base. Capsule is where expansion concentrates.
Distribution Channel:
Channel economics stratify around prescription volume thresholds and formulary placement leverage, with 90-day supply fulfillment reshaping traditional pharmacy revenue capture.
- Pharmacies:Brick-and-mortar retail chains and independent dispensaries handle acute prescription fulfillment and first-fill patient counseling, though their share of maintenance therapy volume is compressing under mail-order displacement.
- Hospitals:Inpatient and outpatient pharmacy departments leverage bulk purchasing power for injectable and high-volume tablet procurement, anchoring formulary decisions that cascade into community prescribing patterns.
- Online Stores:Mail-order and specialty online pharmacies extend reach into rural United States populations beyond retail catchment areas, with preferred network status under managed care contracts driving 90-day supply consolidation.
- Drug Distributors:Wholesaler intermediaries including McKesson, AmerisourceBergen, and Cardinal Health manage inventory logistics and chargeback administration for generic manufacturers serving fragmented downstream accounts.
Drug distributors anchor supply chain infrastructure. Online stores are climbing the fastest.
End User:
Procurement authority and prescribing control fragment across institutional and individual decision-makers, with reimbursement mechanisms determining ultimate volume allocation.
- Patients:Individual consumers initiate demand through prescription fulfillment, with adherence patterns varying by indication—depression maintenance therapy shows higher discontinuation rates than neuropathic pain protocols where symptomatic relief reinforces compliance.
- Healthcare Providers:Psychiatrists, neurologists, and pain specialists exercise prescribing authority, with their formulary familiarity and liability risk tolerance shaping generic substitution acceptance.
- Research Institutions:Academic medical centers and contract research organizations procure nortriptyline for comparative effectiveness studies and bioequivalence trials supporting abbreviated new drug applications.
- Clinics:Outpatient psychiatric and pain management clinics concentrate volume through long-term maintenance protocols, with their procurement decisions increasingly governed by group purchasing organization contracts.
Healthcare providers control prescribing decisions. Clinics are gaining share fastest.
Application:
Indication expansion beyond psychiatric origins restructures demand composition, with off-label pain protocols reshaping prescriber training and patient education investments.
- Depression:Major depressive disorder remains the labeled indication with deepest prescriber familiarity, though serotonin-norepinephrine reuptake inhibitors displace tricyclics in first-line prescribing for treatment-naive patients.
- Anxiety Disorders:Off-label use for generalized anxiety and panic disorder persists in patients with comorbid depression, supported by nortriptyline's norepinephrine reuptake inhibition profile.
- Pain Management:Neuropathic pain applications including diabetic peripheral neuropathy and post-herpetic neuralgia now outpace depression in growth velocity, driven by psychiatric clinic expansion into integrated pain protocols.
- Neuropathic Disorders:Chronic migraine prophylaxis at low doses represents emerging demand concentration, with neurology practices adopting evidence-based protocols that extend nortriptyline utility into headache specialty.
Depression anchors historical volume. Pain management is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturers export nortriptyline hydrochloride intermediates to North American and European generic finished-dosage producers, creating a trade-flow dependency that shapes procurement security calculations across destination markets.
United States
Psychiatric clinic chains and pain management centers drive volume concentration through long-term maintenance protocols. FDA bioequivalence standards under 21 CFR 320 enforce dissolution specification uniformity that filters subscale generic suppliers. The New Jersey and Pennsylvania pharmaceutical corridor hosts formulation facilities serving managed care formulary networks.
Germany
EMA's Committee for Medicinal Products for Human Use maintains active tricyclic antidepressant benefit-risk surveillance that elevates documentation burdens for generic entrants. The country's statutory health insurance system reimburses nortriptyline at reference price levels that compress margin pools. The Rhine-Main pharmaceutical cluster concentrates analytical chemistry capabilities for dissolution testing method development.
India
Contract API synthesis capabilities cluster in Hyderabad and Ahmedabad, supplying nortriptyline hydrochloride to global generic finished-dosage manufacturers. CDSCO manufacturing facility inspections and US FDA audit protocols create compliance barriers that concentrate volume among qualified suppliers. The Telangana-Andhra Pradesh corridor anchors active pharmaceutical ingredient production for tricyclic antidepressant derivatives.
United Kingdom
National Institute for Health and Care Excellence guidelines influence prescriber liability perceptions for tricyclic antidepressant therapy in neuropathic pain applications. The NHS England formulary prioritizes cost-effective generic substitution that sustains volume throughput for mature oral solid forms. The Southeast England pharmaceutical corridor hosts distribution infrastructure serving European export markets.
Japan
PMDA periodic re-examination systems require updated cardiovascular safety data packages that extend approval timelines for tricyclic antidepressant generics. The country's aging demographic expands prescriber comfort with low-dose nortriptyline protocols for chronic pain management. The Kanto region's pharmaceutical formulation sector serves domestic hospital procurement networks.
Nortriptyline Hydrochloride Market Competitive Landscape
Player mix skews toward vertically integrated generic pharmaceutical manufacturers with captive API synthesis capabilities. Market structure concentrates volume among multi-source suppliers with demonstrated FDA bioequivalence compliance histories. Three strategic archetypes dominate: legacy branded incumbents with established physician familiarity, Indian and Israeli generic houses with backward-integrated API production, and mid-scale regional formulators serving niche excipient-sensitive segments. Competitive moves center on abbreviated new drug application filing velocity and dissolution testing capability investments.
Among legacy branded incumbents, Pfizer anchors original formulation familiarity through decades of prescriber exposure. Teva Pharmaceutical Industries exemplifies vertical integration across API synthesis and finished dosage manufacturing, protecting margin pools on oral solid forms. Dr. Reddy's Laboratories represents aggressive abbreviated new drug application filing strategies that sustain price pressure across mature markets. These three companies occupy positions that illustrate the competitive tension between originator heritage and generic manufacturing scale.
| Leading Market Players |
|---|
| Pfizer |
| Novartis |
| Teva Pharmaceutical Industries |
| Mylan |
| Sandoz |
| Taro Pharmaceutical Industries |
| Dr. Reddy's Laboratories |
| Aurobindo Pharma |
| Eli Lilly and Company |
| Others |
Pricing and Supply Chain Analysis
FDA bioequivalence standards under 21 CFR 320 gate both supplier qualification and price differentiation simultaneously, concentrating volume among manufacturers with demonstrated dissolution testing capabilities while compressing margins for subscale entrants lacking analytical chemistry infrastructure.
Pricing Analysis
Immediate-release tablet formulations command commodity pricing against modified-release capsule premiums. Three-tier pricing structure across premium modified-release, standard immediate-release tablets, and economy unbranded generics separates Teva's vertically integrated offerings from regional formulators. Cost compression in immediate-release segments is intensifying because Dr. Reddy's aggressive abbreviated new drug application filings sustain price pressure. Psychiatric clinics exhibit highest price sensitivity through group purchasing organization contracts, while hospital procurement shows lowest sensitivity due to formulary anchoring effects.
Supply Chain Analysis
Container availability constraints on Asia-North America trade lanes elevate inbound logistics costs for API shipments from Hyderabad and Ahmedabad manufacturing clusters. Active pharmaceutical ingredient production concentrates in India, China, and selected European facilities. Finished dosage manufacturing rests on nortriptyline hydrochloride intermediates, gelatin capsule shells, and hydrophilic polymer excipients. Single-source vulnerability in Indian API synthesis creates structural risk for North American generic producers. Distribution runs through McKesson, AmerisourceBergen, and Cardinal Health wholesaler networks serving fragmented downstream pharmacy accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Generic pharmaceutical manufacturing fragmentation creates acquisition opportunities as FDA dissolution specification enforcement filters subscale competitors and telehealth prescribing fragments patient access into specialized fulfillment niches.
For Market Incumbents: Shield margin pools by deepening backward integration into nortriptyline hydrochloride API synthesis in Telangana-Andhra Pradesh corridor facilities. Secure electrocardiographic monitoring partnerships with cardiology practices to differentiate against serotonin-norepinephrine reuptake inhibitor substitution threats in depression prescribing. For New Entrants and Emerging Players: Anchor in rural United States online pharmacy networks where managed care formulary incentives consolidate 90-day supply fulfillment beyond brick-and-mortar retail reach. Target migraine prophylaxis indication expansion through neurology practice direct-to-door fulfillment partnerships as lowest-competition entry vector. For Investors and Strategic Acquirers: FDA draft guidance on in-vitro dissolution testing modifications reshapes the acquisition landscape by forcing portfolio pruning among mid-scale generic houses lacking analytical chemistry capabilities. Five-to-ten year viability favors vertically integrated manufacturers with captive API production and demonstrated bioequivalence compliance histories. Monitor EMA Committee for Medicinal Products for Human Use benefit-risk reassessment timing as prescriber liability perception inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Synthesis | Captive nortriptyline hydrochloride production in Hyderabad clusters insulates margin pools from Indian contract manufacturer concentration risk. |
| Modified-Release Formulation Development | Hydrophilic polymer matrix capabilities enable once-daily dosing premiums in chronic pain populations and long-term care facilities. |
| Online Pharmacy Network Partnership | Preferred status under United States managed care contracts extends reach into rural populations beyond retail pharmacy catchment areas. |
| Dissolution Testing Method Investment | FDA bioequivalence compliance capabilities filter subscale competitors and secure abbreviated new drug application approval velocity. |
| Migraine Prophylaxis Indication Expansion | Neurology practice protocol adoption opens low-dose demand concentration in headache specialty verticals. |
Research Methodology
A standing panel of psychiatric clinic procurement directors, hospital pharmacy managers, generic pharmaceutical regulatory affairs leads, and pain management center formulary specialists provided ongoing calibration. Primary interview insights combined with secondary validation against FDA Orange Book filings, USP monograph updates, ClinicalTrials.gov protocol registrations, and managed care formulary databases. Bottom-up prescription volume modeling and top-down manufacturer revenue triangulation anchored market sizing across the analysis window.
Consistency checks validated volume and value outputs against external benchmarks including IMS Health prescription audit data and wholesaler chargeback disclosures. The analytical framework segmented by formulation type, distribution channel, end user archetype, and therapeutic indication across the projection horizon. CAGRs derived from patient population growth, prescriber protocol adoption curves, and generic substitution elasticity parameters. Forecast inputs incorporated FDA bioequivalence approval timelines, EMA benefit-risk reassessment cycles, and telehealth prescribing penetration trajectories.
Underlying assumptions cover sustained FDA 21 CFR 320 enforcement, stable Indian API export flows, and managed care tricyclic antidepressant tier placement, with deviation risk concentrated in EMA cardiovascular safety data package requirements and serotonin-norepinephrine reuptake inhibitor displacement velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
United Kingdom Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Glycylglycine Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Asia-Pacific Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Global Small Molecule API Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
China Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Mrna Synthesis Raw Materials Market