
 Global Barbiturate Drugs Market | 2026-2036
Global Barbiturate Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Barbiturate Drugs Market Foresight
India is tilting toward larger barbiturate API fermentation and synthesis capacity as Western manufacturers deprioritize older nervous-system agents. Pfizer Inc. leverages its hospital channel depth to sustain pentobarbital supply contracts across North American surgical networks. Hikma Pharmaceuticals anchors injectable anesthesia portfolios in the Middle East and Africa, where cold-chain reliability determines tender awards. Teva Pharmaceutical Industries Ltd. competes on cost-optimized phenobarbital tablets for epilepsy programs in lower-income markets.
Barbiturate drugs are central nervous system depressants derived from barbituric acid, typically formulated as sodium salts for parenteral delivery with strict pH buffering between 9 and 10.5 to prevent precipitation. These compounds primarily serve induction and maintenance of anesthesia, management of refractory seizures, and controlled sedation in intensive care settings. Phenobarbital still dominates volume across epilepsy therapy areas due to its inclusion on the WHO Essential Medicines List and decades of clinical familiarity. Intravenous routes of administration capture premium positioning in anesthesia and emergency sedation, while oral formulations face pricing pressure from generic substitution in outpatient psychiatric and neurological care.
The FDA's controlled-substance scheduling framework and the DEA's aggregate production quota system directly constrain annual manufacturing volumes and distribution licenses for schedule II and III barbiturates. India's CDSCO enforces batch-release testing and import license requirements that filter out non-compliant API suppliers, tightening the approved vendor pool for domestic formulators. The EU's REACH chemicals regime and EMA pharmacovigilance obligations add compliance layers for European manufacturers still active in this category. Stakeholders must monitor how controlled-substance scheduling reforms and essential-medicines procurement shifts in India and Africa reshape volume allocation between anesthesia and antiepileptic applications.
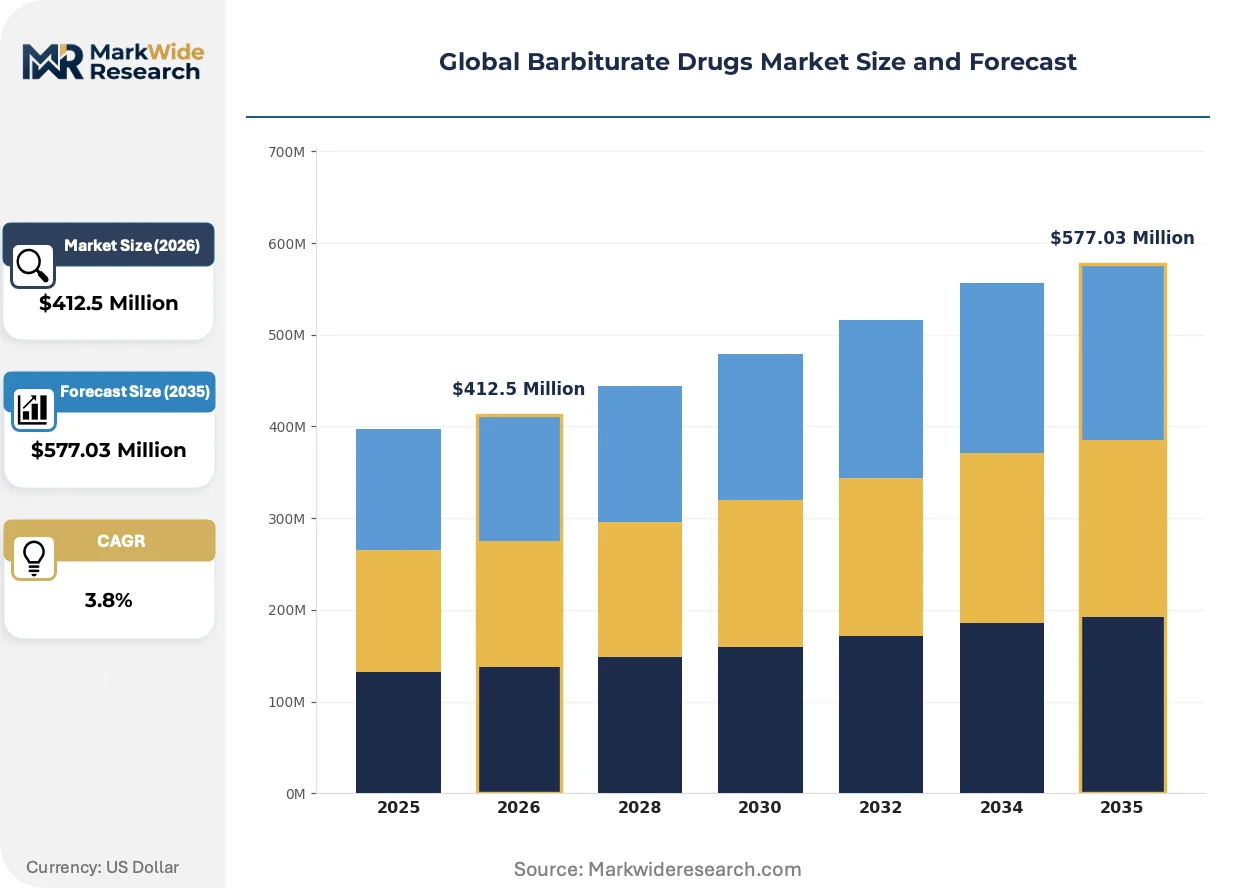
Market Dynamics
DEA aggregate production quotas and FDA controlled-substance scheduling are compressing annual manufacturing volumes while hospital procurement in India pulls remaining supply eastward, creating a bifurcated market where anesthesia-grade parenterals face scarcity and oral generics face commoditization.
Growth Catalysts
- Refractory seizure management protocols:Emergency departments in trauma centers are expanding phenobarbital stockpiles for status epilepticus cases where first-line benzodiazepines fail, sustaining demand for intravenous sodium salts.
- CDSCO batch-release testing:India's tightened import license requirements are filtering out non-compliant API suppliers, consolidating domestic formulator market share and accelerating fermentation capacity expansion.
- WHO Essential Medicines List inclusion:Phenobarbital's continued presence on the list anchors government hospital tenders across lower-income health systems, locking in volume commitments regardless of newer antiepileptic alternatives.
Market Restraints
- DEA quota compression:The DEA's annual aggregate production limits for schedule II barbiturates directly constrain manufacturing volumes, forcing allocation decisions between anesthesia and antiepileptic applications.
- Western API supplier withdrawal:European and North American active pharmaceutical ingredient manufacturers are deprioritizing older nervous-system agents, concentrating synthesis capacity in India and China.
- Benzodiazepine substitution in sedation:Propofol and midazolam are displacing thiopental and pentobarbital in procedural sedation protocols, eroding the anesthesia segment's volume base.
Strategic Opportunities
- Middle East hospital tender expansion:Saudi Arabia's Ministry of Health and UAE's MOHAP are issuing multi-year anesthesia supply contracts where cold-chain reliability determines vendor selection, rewarding established injectable specialists.
- EMA pharmacovigilance harmonization:The EU's tightened adverse-event reporting requirements for legacy CNS drugs are creating compliance moats for manufacturers with established European regulatory infrastructure.
- Lipid emulsion formulation convergence:Combining barbiturate sodium salts with lipid-based delivery systems is hybridizing parenteral stability profiles, opening patent-protected product differentiation in anesthesia maintenance.
Industry Challenges
- Controlled-substance compliance workforce scarcity:Qualified personnel for DEA and state-level distribution licensing, quota tracking, and diversion prevention are concentrated among a shrinking pool of legacy manufacturers.
- pH buffering validation timelines:Demonstrating sodium salt stability between 9 and 10.5 for parenteral formulations requires extended accelerated aging studies, compressing product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Barbiturate Drugs Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $577.03 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Phenobarbital, Pentobarbital, Secobarbital, Amobarbital, Butalbital, Thiopental Therapy Area: Epilepsy, Insomnia, Anesthesia, Sedation, Anxiety, Muscle Relaxation End User: Hospitals, Clinics, Ambulatory Surgical Centers, Psychiatric Facilities, Research Laboratories, Rehabilitation Centers Route of Administration: Oral, Intravenous, Intramuscular, Rectal, Sublingual, Transdermal |
| Companies Covered | Par Pharmaceutical, Akorn Operating Company LLC, Samarth Life Science Pvt. Ltd, Ethypharm, Abbott Laboratories, Hikma Pharmaceuticals, Pfizer Inc., Teva Pharmaceutical Industries Ltd., Fresenius Kabi AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Barbiturate Drugs Market Shifts & Advancements
Formulation chemistry and regulatory data infrastructure are converging to reshape how barbiturate drugs are manufactured, tracked, and delivered to end-use settings across hospital networks.
Continuous manufacturing platforms for sodium salt crystallization are hybridizing batch consistency with real-time release testing, enabling pharmaceutical contractors to meet DEA quota deadlines without sacrificing quality assurance. Hospital pharmacy buyers in North American surgical networks are adopting these supply lines for pentobarbital induction agents. The structural consequence is compression of traditional batch-release timelines from weeks to days.
REACH chemicals regime amendments are tightening barbituric acid derivative classification and waste-handling protocols across European manufacturing sites still active in this category. Industrial consequence includes mandatory substitution assessments for older synthesis pathways and heightened ECHA notification burdens. German and Swiss formulators with captive API capability are responding by consolidating European production into single-site operations with dedicated environmental compliance teams.
Hospital procurement committees are consolidating anesthesia drug purchasing through centralized tender platforms that unbundle product supply from technical support services. Middle East and African health systems are replacing fragmented distributor networks with direct manufacturer contracts where cold-chain documentation and batch pedigree transparency determine award outcomes. This pattern is most visible in Saudi Arabia's National Unified Procurement Company and UAE's Emirates Health Services tenders for surgical sedation portfolios.
Global Barbiturate Drugs Market Segmentation
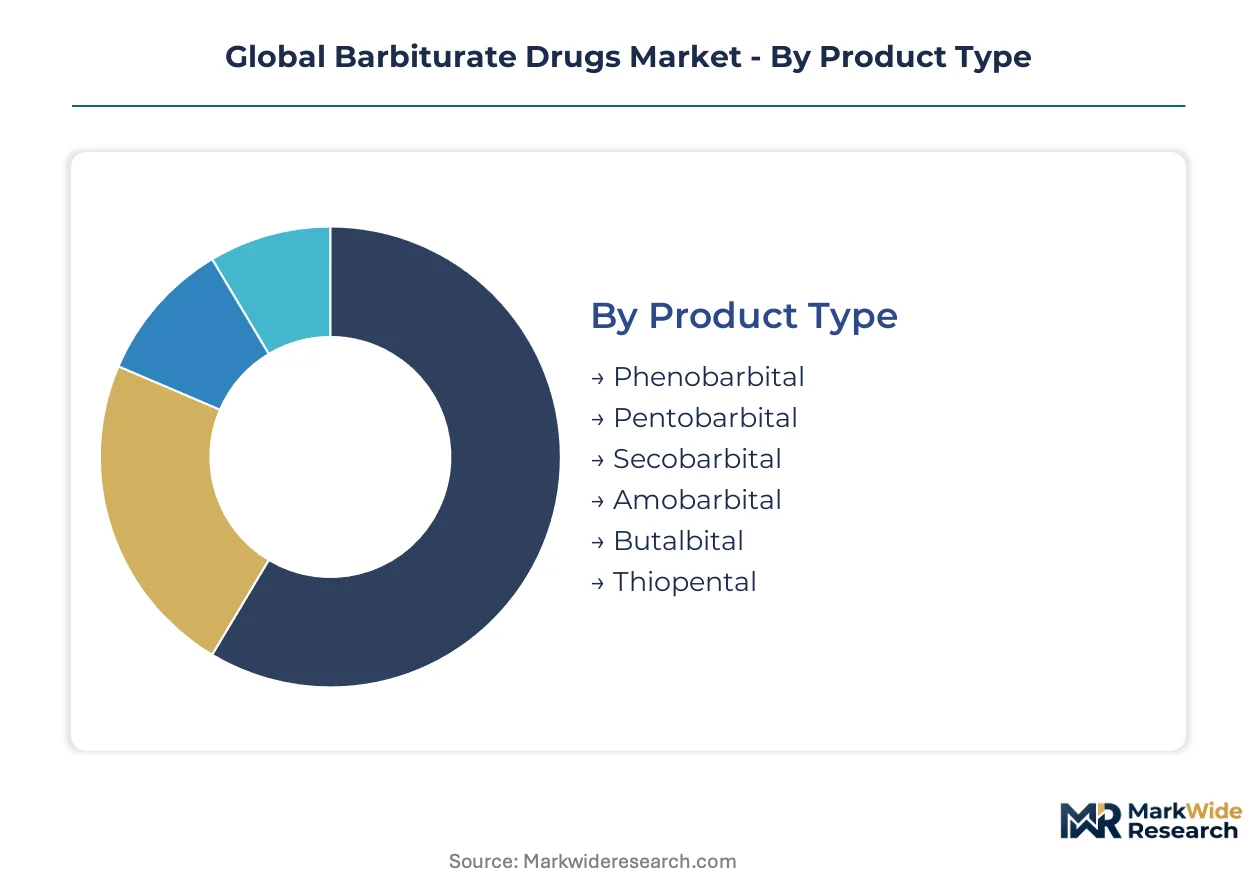
Barbiturate market value concentrates in therapy areas and administration routes where regulatory control intersects with clinical necessity. Segmentation reveals how DEA quotas and essential-medicines procurement allocate volume across product types and end-use settings.
Product Type:
Mature injectable anesthetics anchor hospital procurement while oral antiepileptics sustain volume through government tenders.
- Phenobarbital:Sodium salt formulations dominate epilepsy protocols across WHO Essential Medicines List programs. Government hospital tenders in India and Nigeria lock in multi-year volume commitments regardless of newer antiepileptic alternatives.
- Pentobarbital:Schedule II parenteral solutions serve induction anesthesia in North American trauma centers. DEA aggregate production quotas constrain annual manufacturing, forcing allocation decisions between surgical networks and veterinary euthanasia applications.
- Secobarbital:Short-acting hypnotic for preoperative sedation with declining clinical utilization.
- Amobarbital:Intermediate-duration agent restricted to diagnostic narcosynthesis and refractory seizure protocols.
- Butalbital:Fixed-dose combination component for tension headache management in outpatient settings.
- Thiopental:Ultra-short-acting IV anesthetic displaced by propofol in most Western surgical networks; residual demand concentrates in Middle Eastern and African cold-chain dependent tenders.
Phenobarbital handles the majority of throughput; Thiopental is the fastest mover on share as cold-chain reliability determines vendor selection in emerging health systems.
Therapy Area:
Cost tier stratification separates premium anesthesia-grade parenterals from commoditized oral psychiatric indications.
- Epilepsy:Phenobarbital tablets and sodium salt injections serve status epilepticus protocols where first-line benzodiazepines fail. India's CDSCO batch-release testing consolidates domestic formulator market share for government tender fulfillment.
- Anesthesia:Intravenous induction and maintenance agents command premium positioning in hospital surgical networks. Saudi Arabia's Ministry of Health and UAE's MOHAP issue multi-year supply contracts where pH stability documentation between 9 and 10.5 determines technical compliance.
- Insomnia:Declining barbiturate utilization amid benzodiazepine and Z-drug substitution.
- Sedation:Intensive care procedural sedation facing displacement by propofol and midazolam protocols.
- Anxiety:Historical indication with minimal current prescribing due to safety profile limitations.
- Muscle Relaxation:Niche application in tetanus management and refractory spasticity cases.
Anesthesia commands premium unit economics; Epilepsy delivers volume scale through essential-medicines procurement.
End User:
Customer type determines regulatory burden intensity and procurement channel structure across the value chain.
- Hospitals:Tier-one trauma centers and surgical networks anchor pentobarbital and thiopental demand through centralized pharmacy procurement. North American health systems maintain DEA-licensed vault infrastructure for schedule II controlled-substance storage.
- Ambulatory Surgical Centers:Outpatient procedural settings favor shorter-acting agents with rapid recovery profiles. Cold-chain reliability requirements filter vendor pools to established injectable specialists with dedicated logistics infrastructure.
- Clinics:Primary and specialty outpatient settings with limited controlled-substance licensing.
- Psychiatric Facilities:Inpatient behavioral health units with restricted formulary access.
- Research Laboratories:Preclinical and clinical trial supply subject to DEA research registration.
- Rehabilitation Centers:Detoxification protocols with declining barbiturate utilization amid safer alternatives.
Hospitals concentrate the highest-value procurement; Ambulatory Surgical Centers are expanding most quickly as outpatient surgery migration accelerates.
Route of Administration:
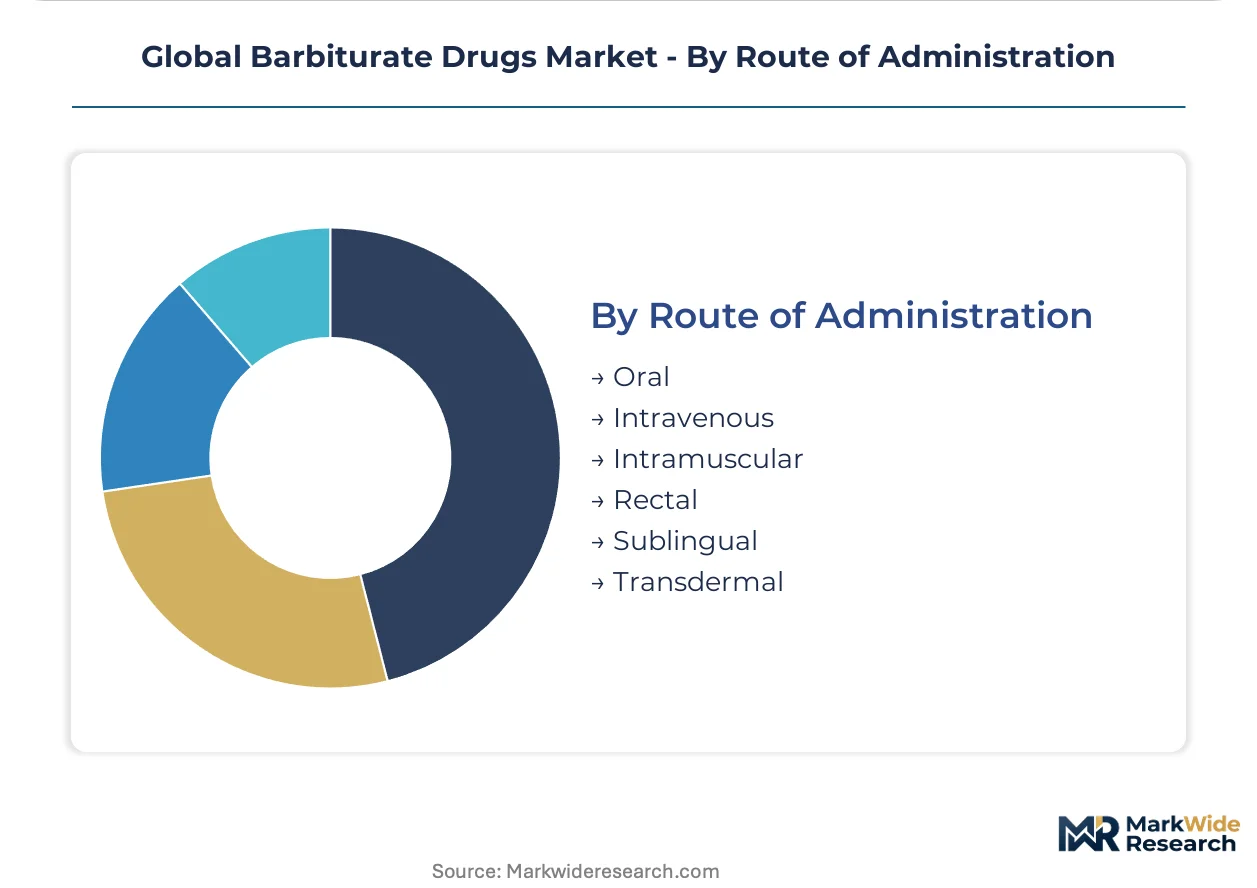
Supply concentration in parenteral manufacturing creates compliance moats that oral generic markets cannot replicate.
- Intravenous:Sodium salt solutions with mandatory pH buffering between 9 and 10.5 for precipitation prevention. Continuous manufacturing platforms for crystallization enable real-time release testing, compressing batch timelines from weeks to days for DEA quota compliance.
- Oral:Compressed tablets and elixirs face pricing pressure from generic substitution in outpatient neurological and psychiatric care. India's domestic API fermentation capacity expansion supports cost-optimized phenobarbital tablet production for government tenders.
- Intramuscular:Alternative parenteral route for emergency settings without IV access.
- Rectal:Pediatric and seizure rescue applications with limited commercial scale.
- Sublingual:Rapid absorption profile for preoperative anxiety management.
- Transdermal:Experimental delivery systems with minimal current clinical utilization.
Intravenous routes capture premium positioning; Oral formulations deliver volume through essential-medicines channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
CDSCO batch-release testing and import license requirements anchor India's expanding role in barbiturate API fermentation and government tender fulfillment. The DEA's aggregate production quota system constrains United States manufacturing volumes while hospital procurement pulls remaining supply toward emerging health systems.
United States
Tier-one trauma centers and surgical networks maintain pentobarbital stockpiles for anesthesia induction and refractory seizure protocols. The DEA's annual aggregate production limits for schedule II barbiturates directly constrain manufacturing volumes, forcing allocation decisions between surgical networks and veterinary applications. Greater Boston and the Pacific Northwest concentrate DEA-licensed vault infrastructure for controlled-substance storage.
India
Domestic API manufacturing capacity and government hospital tenders are pulling volume eastward from Western suppliers. CDSCO enforces batch-release testing and import license requirements that filter out non-compliant API suppliers, tightening the approved vendor pool for domestic formulators. Maharashtra and Gujarat anchor fermentation and synthesis capacity expansion for phenobarbital tablet production.
Germany
EMA pharmacovigilance obligations and REACH chemicals regime amendments add compliance layers for manufacturers still active in barbituric acid derivatives. Industrial sites in Bavaria and North Rhine-Westphalia are consolidating European production into single-site operations with dedicated environmental compliance teams. German formulators with captive API capability face mandatory substitution assessments for older synthesis pathways.
Saudi Arabia
The Ministry of Health issues multi-year anesthesia supply contracts where cold-chain reliability determines vendor selection. The National Unified Procurement Company consolidates anesthesia drug purchasing through centralized tender platforms that unbundle product supply from technical support services. Riyadh and the Eastern Province concentrate hospital procurement committees adopting direct manufacturer contracts.
United Arab Emirates
MOHAP tenders for surgical sedation portfolios reward established injectable specialists with dedicated logistics infrastructure. Emirates Health Services replaces fragmented distributor networks with direct manufacturer contracts where batch pedigree transparency determines award outcomes. Dubai and Abu Dhabi anchor cold-chain documentation requirements for parenteral sodium salt formulations.
Global Barbiturate Drugs Market Competitive Landscape
Hospital-channel specialists and cost-optimized generic manufacturers split the market along therapy-area lines. The vendor base concentrates among legacy pharmaceutical companies with established controlled-substance licensing infrastructure and DEA quota allocation history. Three archetypes dominate: injectable anesthesia specialists with cold-chain logistics depth, essential-medicines suppliers capturing government tenders in lower-income markets, and diversified pharmaceutical conglomerates maintaining hospital network relationships. Competitive moves center on geographic expansion into Middle East and African tender markets and backward integration into API fermentation capacity.
Among diversified pharmaceutical conglomerates, Pfizer Inc. and Teva Pharmaceutical Industries Ltd. occupy positions reflecting hospital network scale and essential-medicines procurement reach respectively. Hikma Pharmaceuticals exemplifies the injectable anesthesia specialist archetype with established Middle East and Africa presence. These three companies represent the strategic spectrum from premium parenteral positioning to cost-optimized tablet supply for government tenders.
| Leading Market Players |
|---|
| Par Pharmaceutical |
| Akorn Operating Company LLC |
| Samarth Life Science Pvt. Ltd |
| Ethypharm |
| Abbott Laboratories |
| Hikma Pharmaceuticals |
| Pfizer Inc. |
| Teva Pharmaceutical Industries Ltd. |
| Fresenius Kabi AG |
| Others |
Supply & Pricing Matrix
Overcapacity in Western API fermentation facilities is compressing contract manufacturing rates while Indian suppliers absorb displaced volume, creating divergent pricing postures between legacy manufacturers defending premium anesthesia contracts and domestic formulators competing on phenobarbital tablet tenders.
Pricing Analysis
Geographic price spreads between North American hospital procurement and Indian government tenders exceed three-to-one for equivalent phenobarbital sodium salt formulations. Contract-based long-term offtake dominates anesthesia-grade parenterals where DEA quota scarcity locks in premium positioning, while oral generics face commodity spot dynamics driven by CDSCO batch-release consolidation. Price differentiation hinges on cold-chain certification grade and volume scale, with Saudi Arabia's Ministry of Health tenders rewarding technical compliance over unit cost. Pricing pressure stems from benzodiazepine substitution in procedural sedation, eroding thiopental and pentobarbital margins. Ambulatory surgical centers exhibit highest price sensitivity due to formulary budget constraints; tier-one trauma centers demonstrate lowest sensitivity given protocol-locked procurement.
Supply Chain Analysis
Extended payment terms from Middle Eastern hospital procurement committees are forcing working-capital restructuring among injectable specialists without captive API capability. Supply concentrates in India, China, and residual European sites in Germany and Switzerland, with Maharashtra and Gujarat anchoring fermentation capacity expansion. Barbituric acid derivatives and sodium salt precursors draw from petrochemical and fine-chemical feedstocks, while pH buffering agents and lipid emulsion carriers rest on specialized excipient supply chains. Single-source vulnerability concentrates in DEA-licensed controlled-substance distribution infrastructure, where qualified personnel scarcity constrains vault operator expansion. Distribution runs through direct manufacturer contracts replacing fragmented distributor networks in Middle East and African health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
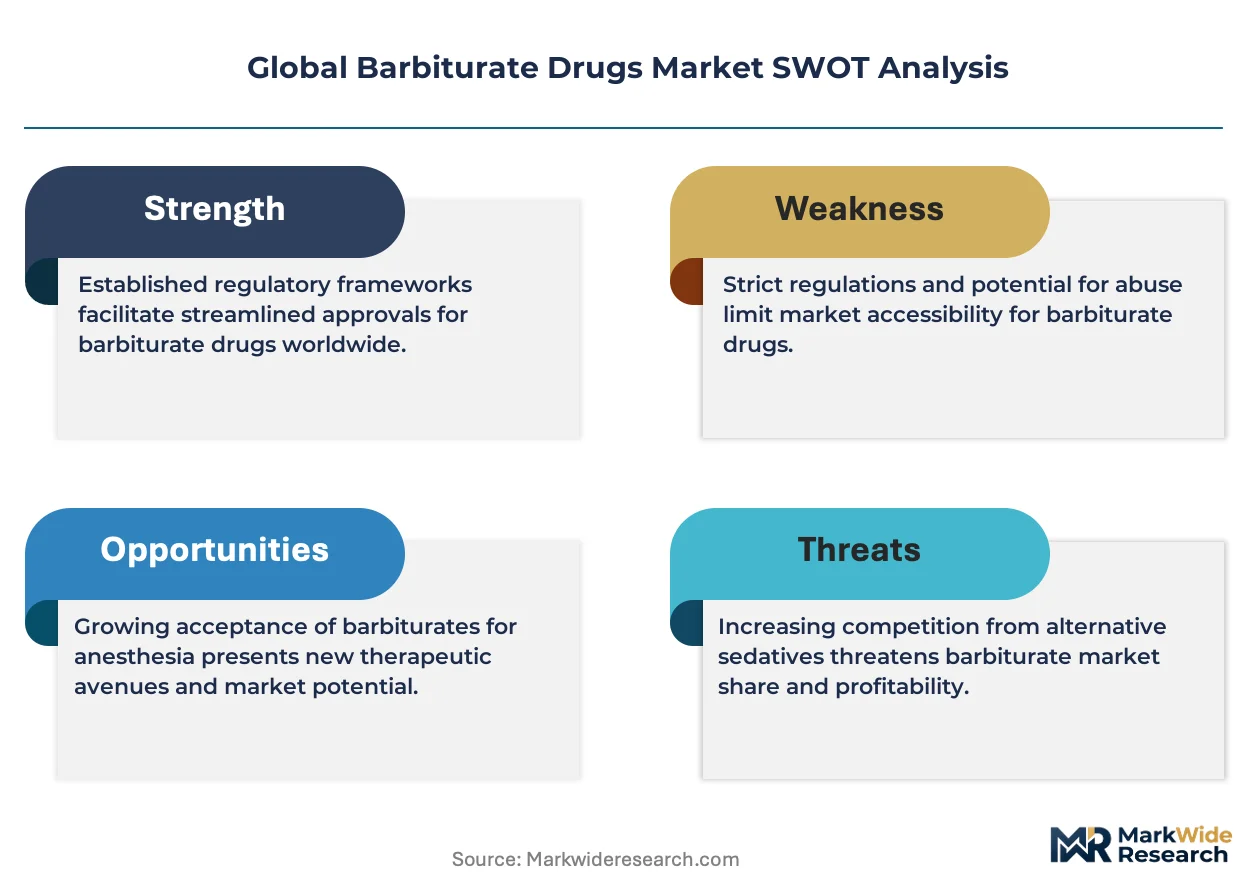
Incumbents face a substitution defense against propofol and midazolam protocols displacing barbiturate anesthesia share, requiring strategic repositioning around essential-medicines indispensability and controlled-substance regulatory moats.
For Market Incumbents: Pre-empt benzodiazepine encroachment by deepening backward integration into Indian API fermentation capacity, securing CDSCO-compliant supply chains for phenobarbital government tenders. Anchor hospital network relationships through technical service bundling that generic substitutes cannot replicate, leveraging DEA quota allocation history as competitive barrier. For New Entrants and Emerging Players: Cold-chain logistics gaps in sub-Saharan African hospital networks represent the most penetrable entry point for injectable anesthesia specialists with dedicated distribution infrastructure. Target status epilepticus protocol expansion in Southeast Asian trauma centers where phenobarbital stockpile requirements outstrip local manufacturing. Pursue regulatory sandbox partnerships with national health procurement agencies to accelerate tender qualification. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across parenteral formulation manufacturing as continuous processing platforms and environmental compliance investments reshape cost structures. Acquire mid-tier Indian formulators with captive API capability and established CDSCO batch-release track records. Monitor DEA aggregate production quota allocation hearings as inflection signal for anesthesia-grade supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into API Fermentation | Captive phenobarbital sodium salt production insulates margin pressure from Western supplier withdrawal. |
| Cold-Chain Logistics Infrastructure Expansion | Dedicated distribution networks unlock Saudi MOH and UAE MOHAP multi-year anesthesia tenders. |
| Continuous Manufacturing Platform Adoption | Real-time release testing compresses DEA quota compliance timelines from weeks to days. |
| EMA Pharmacovigilance Harmonization Investment | Established European regulatory infrastructure creates compliance moats against non-EU competitors. |
| Lipid Emulsion Formulation Development | Patent-protected delivery systems differentiate anesthesia maintenance portfolios from commodity injectables. |
Research Methodology
Initial hypotheses were tested against primary input from hospital pharmacy directors, anesthesia department chiefs, CDSCO regulatory affairs leads, controlled-substance compliance officers, and government tender procurement managers, and refined through secondary validation against FDA controlled-substance scheduling filings, DEA aggregate production quota records, CDSCO import license databases, WHO Essential Medicines List procurement reports, and EMA pharmacovigilance disclosure archives. Bottom-up volume triangulation across product type, therapy area, and administration route segments was cross-checked against top-down market value estimates.
Demand-supply balance modeling anchored forecast outputs, with segmentation across product type, therapy area, end user, and route of administration dimensions supplemented by regional regulatory cluster differentiation. CAGRs were derived from trajectory fitting to historical volume patterns and forward projection of quota-constrained supply ceilings. Industry-specific forecast inputs included DEA schedule II manufacturing allocation trends and CDSCO batch-release testing capacity expansion timelines across the analysis window.
Practitioners should monitor DEA quota compression severity, benzodiazepine protocol substitution velocity, and Indian API fermentation capacity utilization for early signals of pricing inflection. Forecasts reflect documented assumptions regarding controlled-substance scheduling stability and essential-medicines procurement continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Synthetic Lethality-Based Drugs and Targets Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Pemetrexed Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
Cetrorelix Acetate API Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
France Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Silver Sulfadiazine Market
Pharmaceutical Ingredients
Duloxetine API Market
Pharmaceutical Ingredients
Pharmaceutical Indicator Strips Market
Pharmaceutical Ingredients
Amphetamine Drug Market