
 Global Fibrate Drugs Market | 2026-2036
Global Fibrate Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fibrate Drugs Market Foresight
Continuous manufacturing technology is reshaping how fibrate active pharmaceutical ingredients are synthesized and formulated, replacing batch processes with flow chemistry platforms that reduce solvent waste and improve yield consistency. Sun Pharmaceutical Industries Ltd leverages its integrated API-to-finished-dosage infrastructure to control cost structures across fenofibrate product lines. Abbott Laboratories anchors its position through sustained investment in extended-release formulation patents that extend product lifecycles beyond standard generic erosion curves.
Fibrate drugs constitute a class of peroxisome proliferator-activated receptor-alpha agonists prescribed primarily for reducing elevated triglyceride levels and modifying low-density lipoprotein cholesterol profiles, with fenofibrate and gemfibrozil representing the most widely prescribed members based on established efficacy in hyperlipidemia management. Among therapy areas, hypertriglyceridemia treatment commands the largest prescription volume due to its prevalence in diabetic and metabolic syndrome patient populations, while cardiovascular risk reduction applications represent the fastest-expanding segment as clinicians increasingly prescribe fibrates within secondary prevention protocols. Oral tablets dominate dosage form distribution through retail pharmacy channels, though extended-release formulations capture disproportionate margin pools due to patent-protected delivery mechanisms and reduced dosing frequency.
The FDA maintains bioequivalence standards for generic fenofibrate through its Office of Generic Drugs, while the EMA oversees fibrate marketing authorizations across European member states under centralized and decentralized procedures. These frameworks determine market access timelines for new entrants and shape R&D allocation toward formulation differentiation rather than novel molecular entities. Stakeholders must monitor evolving cardiovascular outcome trial data and payer reimbursement criteria for combination lipid therapies to anticipate shifts in prescriber behavior and procurement priorities.
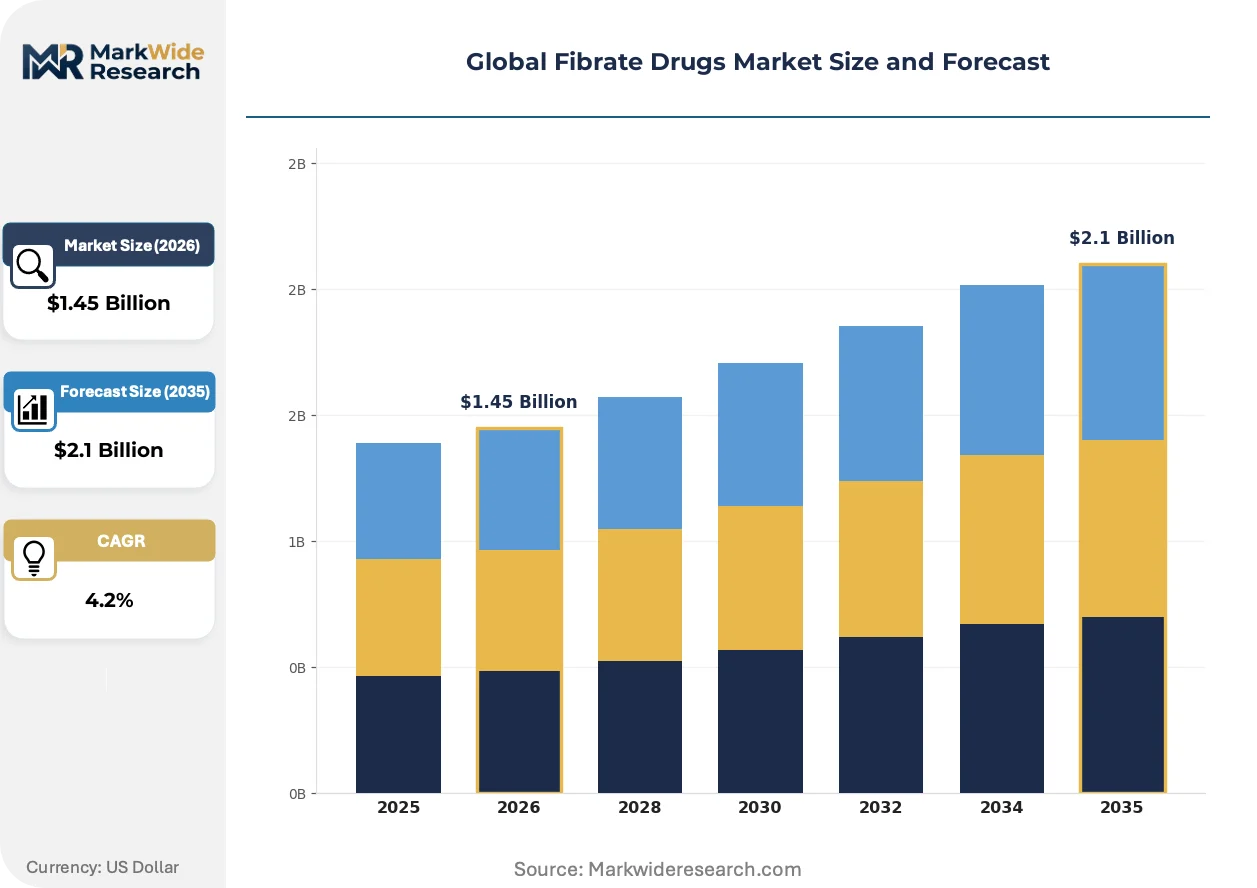
Market Dynamics
Continuous manufacturing technology is compressing batch cycle times for fenofibrate synthesis while FDA bioequivalence updates force generic manufacturers toward real-time release testing protocols.
Growth Catalysts
- Medicare Reimbursement Policy:United States federal coverage expansion for lipid-lowering combination therapies in primary care settings accelerates prescriber adoption of fibrate-statin co-therapy protocols.
- Hypertriglyceridemia Prevalence:Diabetic and metabolic syndrome patient populations in India and Brazil generate rising prescription volumes for gemfibrozil and fenofibrate as first-line triglyceride management.
- Continuous Flow Chemistry:Pharmaceutical manufacturers deploy flow chemistry platforms for API synthesis, reducing solvent waste volumes and improving yield consistency across fenofibrate production lines.
Market Restraints
- API Supply Concentration:China dominates active pharmaceutical ingredient production for fenofibrate, creating geographic single-source vulnerability for Western formulation facilities.
- Generic Erosion Dynamics:Extended-release formulation patents expire, accelerating price compression across standard fenofibrate tablet categories in retail pharmacy channels.
- Statin Substitution Pressure:High-intensity statin therapies displace fibrates in cardiovascular risk reduction protocols, narrowing the addressable patient pool for pure fibrate prescriptions.
Strategic Opportunities
- Extended-Release Formulation Differentiation:Patent-protected delivery mechanisms enabling reduced dosing frequency capture disproportionate margin pools in United States retail and hospital procurement.
- Combination Therapy Development:Fibrate-statin fixed-dose combinations align with EMA centralized procedure pathways for cardiovascular outcome claims in European member states.
- Continuous Manufacturing Adoption:Real-time process analytical technology integration enables smaller-footprint production facilities with faster regulatory approval timelines.
Industry Challenges
- Bioequivalence Validation Complexity:FDA Office of Generic Drugs requires increasingly sophisticated pharmacokinetic studies for fenofibrate formulations with variable food effects.
- Formulation Scientist Talent Scarcity:Specialized expertise in lipid-based drug delivery systems and amorphous solid dispersion technology commands premium compensation in competitive labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fibrate Drugs Market |
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $2.1 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fenofibrate, Gemfibrozil, Ciprofibrate, Clofibrate, Bezafibrate Therapy Area: Hyperlipidemia, Mixed Dyslipidemia, Cardiovascular Risk Reduction, Metabolic Syndrome, Hypertriglyceridemia End User: Hospitals, Specialty Clinics, Retail Pharmacies, Clinical Research Organizations Dosage Form: Oral Tablets, Capsules, Extended Release, Oral Suspensions |
| Companies Covered | Sun Pharmaceutical Industries Ltd, Abbott Laboratories, Lupin Ltd, Cipla Inc., AbbVie Inc, Sanofi, Mylan N.V., Teva Pharmaceutical Industries Ltd, Aurobindo Pharma USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fibrate Drugs Market Shifts & Advancements
Process analytical technology and real-time release testing are displacing traditional end-point quality control, while payer preference for outcome evidence reshapes clinical trial investment priorities.
Process analytical technology deployment is digitizing fenofibrate manufacturing quality assurance. Pharmaceutical manufacturers integrate in-line spectroscopic sensors and chemometric models to monitor crystallization kinetics during API synthesis. Large-scale generic producers in India and the United States adopt these systems fastest, driven by FDA inspection readiness requirements. This shift is digitizing batch record review, compressing release timelines from weeks to hours while reducing laboratory testing overhead.
EMA's updated guidelines on cardiovascular outcome trials for lipid-modifying agents now require hard endpoint data for new combination indications. This policy revision elevates clinical trial costs and extends development timelines for fibrate-containing fixed-dose products. European marketing authorization applications for novel formulations face heightened evidence thresholds, prompting sponsors to prioritize United States FDA submission pathways where surrogate endpoint acceptance remains broader.
Hospital procurement consolidation in the United States concentrates purchasing power through group purchasing organizations and integrated delivery networks. These entities negotiate sole-source contracts for formulary placement, displacing traditional wholesale distribution relationships. Cardiovascular protocol standardization across major health systems accelerates this shift, with formulary committees demanding real-world evidence packages and total cost-of-care analyses for fibrate therapy selections.
Global Fibrate Drugs Market Segmentation
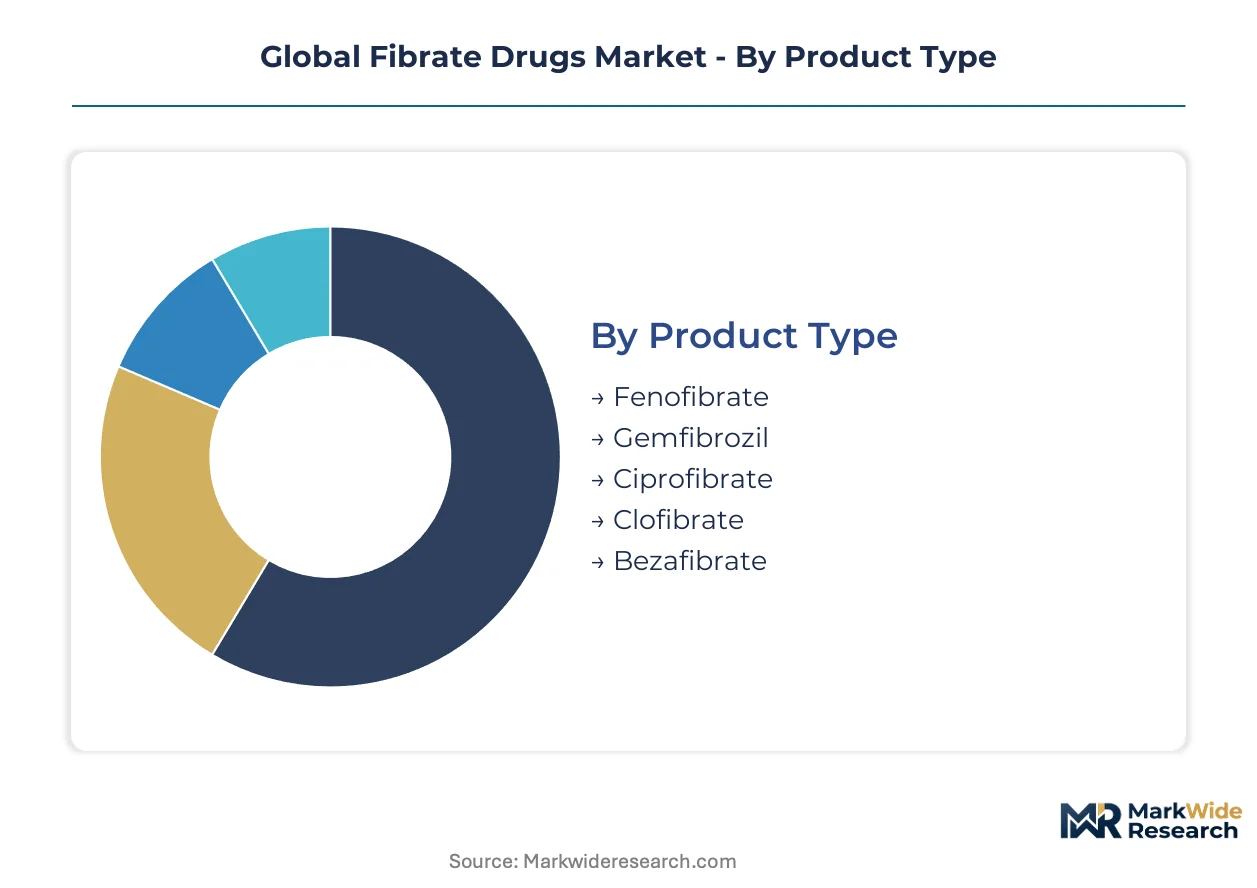
Fibrate drug segmentation reveals distinct competitive arenas where formulation technology, prescriber channel preferences, and disease-state targeting determine margin capture. Manufacturers allocate R&D resources across these dimensions based on regulatory pathway clarity and reimbursement elasticity.
Product Type:
Maturity varies sharply across this spectrum, with legacy molecules facing generic saturation while differentiated formulations sustain premium positioning.
- Fenofibrate:The most prescribed fibrate globally, available in immediate-release and micronized formulations with established bioequivalence pathways. Hospital procurement in the United States concentrates demand for this agent as cardiovascular protocols standardize fibrate-statin co-therapy. Medicare reimbursement policies favor its inclusion in lipid-lowering combination regimens.
- Gemfibrozil:An earlier-generation fibrate with distinct pharmacokinetic properties and specific drug interaction profiles that limit statin co-prescription. Prescription volumes in India and Brazil are climbing as diabetic populations expand and first-line triglyceride management protocols adopt this lower-cost alternative.
- Ciprofibrate:A potent, longer-acting fibrate with once-daily dosing advantages in European markets where EMA marketing authorizations support its use.
- Clofibrate:The first-generation fibrate with declining utilization due to safety profile concerns and superior successor molecules.
- Bezafibrate:A non-selective PPAR agonist with broader metabolic effects, retaining niche prescribing in select European and Asian markets.
Fenofibrate retains volume leadership; Gemfibrozil holds the steepest expansion curve among established molecules.
Therapy Area:
Application-driven demand splits between triglyceride-focused management and comprehensive cardiovascular risk modification.
- Hyperlipidemia:The foundational indication encompassing elevated cholesterol and triglyceride management, capturing the broadest prescriber base across primary care settings. United States retail pharmacy channels move substantial volume here as preventive care protocols expand.
- Hypertriglyceridemia:Severe triglyceride elevation requiring aggressive pharmacologic intervention, particularly prevalent in insulin-resistant populations. Diabetic and metabolic syndrome patient pools in emerging markets generate accelerating prescription growth for first-line fibrate therapy.
- Mixed Dyslipidemia:Combined lipid abnormalities where fibrates complement statin therapy or serve as monotherapy for statin-intolerant patients.
- Cardiovascular Risk Reduction:Secondary prevention applications where fibrates are prescribed within broader risk-modification protocols.
- Metabolic Syndrome:Clustered cardiovascular risk factors where triglyceride elevation represents one diagnostic criterion.
Hyperlipidemia anchors prescription volume; Hypertriglyceridemia is gaining share fastest as diabetes prevalence climbs.
End User:
Channel concentration reflects procurement consolidation trends and the shift toward integrated care delivery models.
- Retail Pharmacies:The dominant distribution channel for maintenance fibrate therapy, capturing recurring prescription volume through established patient relationships. United States Medicare Part D formularies and pharmacy benefit manager networks concentrate purchasing power here.
- Hospitals:Acute care and outpatient settings where formulary committees standardize cardiovascular protocols. Group purchasing organizations negotiate sole-source contracts that displace traditional wholesale relationships.
- Specialty Clinics:Lipidology and endocrinology practices managing complex dyslipidemia cases requiring specialized monitoring.
- Clinical Research Organizations:Contract research entities conducting bioequivalence studies and cardiovascular outcome trials for fibrate formulations.
Retail Pharmacies maintain volume dominance; Hospitals are expanding share fastest through procurement consolidation.
Dosage Form:
Technology differentiation separates commoditized immediate-release products from patent-protected delivery systems commanding premium pricing.
- Extended Release:Patent-protected formulation technologies enabling reduced dosing frequency and improved patient adherence. United States retail and hospital procurement channels capture disproportionate margin pools here as manufacturers leverage formulation exclusivity.
- Oral Tablets:The standard dosage form dominating generic substitution and volume-based procurement. Immediate-release tablets face accelerating price compression as multiple generic entrants compete.
- Capsules:Alternative solid dosage forms with specific dissolution profiles, often employed for micronized fenofibrate formulations.
- Oral Suspensions:Liquid formulations serving pediatric populations and patients with swallowing difficulties, representing a niche but stable demand segment.
Oral Tablets command volume leadership; Extended Release delivers the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indian API manufacturers ship fenofibrate intermediates to formulation facilities in the United States and Europe, establishing a trade-flow corridor that shapes procurement patterns across Western markets.
United States
Medicare Part D reimbursement expansion for lipid-lowering combination therapies drives hospital formulary adoption of fibrate-statin protocols. FDA bioequivalence guidelines for generic fenofibrate formulations require real-time release testing that elevates manufacturing compliance costs. New Jersey and North Carolina host major formulation operations where Abbott Laboratories maintains extended-release production capacity.
Germany
EMA centralized marketing authorization procedures attract combination therapy developers seeking cardiovascular outcome claims across European member states. German statutory health insurance funds negotiate reference pricing for generic fenofibrate that compresses retail pharmacy margins. The Rhine-Main cluster around Frankfurt concentrates pharmaceutical distribution infrastructure serving Central European markets.
India
Diabetic population expansion in Maharashtra and Gujarat generates accelerating gemfibrozil prescription volumes for first-line hypertriglyceridemia management. CDSCO manufacturing facility inspections enforce data integrity standards that filter substandard API producers from export markets. Hyderabad and Ahmedabad anchor active pharmaceutical ingredient production for Western generic formulation clients.
Brazil
Metabolic syndrome prevalence in São Paulo and Rio de Janeiro metropolitan areas expands retail pharmacy demand for affordable triglyceride management options. ANVISA pharmaceutical pricing controls limit premium formulation penetration while favoring volume-based generic procurement. The São Paulo state pharmaceutical manufacturing corridor supplies domestic formulation demand and Andean export markets.
China
NMPA consistency evaluation requirements for generic fenofibrate tablets accelerate industry consolidation among domestic manufacturers. Zhejiang and Jiangsu province chemical parks dominate fenofibrate API synthesis capacity serving global formulation customers. Ningbo and Taizhou industrial clusters face environmental compliance upgrades that reshape cost structures for Western procurement contracts.
Global Fibrate Drugs Market Competitive Landscape
Channel-controlling players compete with product-specialist players across hospital procurement, retail pharmacy, and specialty clinic segments. The market structure separates into three tiers: multinational pharmaceutical corporations with extended-release patent portfolios, large-scale generic manufacturers with integrated API-to-finished-dosage infrastructure, and regional formulation specialists serving price-sensitive emerging markets. Dominant competitive moves include portfolio diversification into combination therapies and strategic partnerships with group purchasing organizations for hospital formulary placement.
Within the integrated API-manufacturer tier, Sun Pharmaceutical Industries Ltd and Lupin Ltd represent archetypal players controlling cost structures through captive supply chains. Abbott Laboratories occupies a position exemplifying patent-protected formulation differentiation, while Teva Pharmaceutical Industries Ltd anchors the scale-driven generic segment. These three companies illustrate divergent strategic postures: backward integration into active pharmaceutical ingredients, extended-release delivery mechanism exclusivity, and high-volume commoditized production respectively.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries Ltd |
| Abbott Laboratories |
| Lupin Ltd |
| Cipla Inc. |
| AbbVie Inc |
| Sanofi |
| Mylan N.V. |
| Teva Pharmaceutical Industries Ltd |
| Aurobindo Pharma USA |
| Others |
Supply & Pricing Matrix
Ningbo-to-Rotterdam container freight corridors carry fenofibrate API intermediates from Zhejiang province chemical parks to European formulation facilities, with bunker fuel surcharges and canal transit fees compressing margin pools for spot-market buyers while contract holders with volume commitments capture price stability. This logistics cost wedge amplifies the advantage of integrated manufacturers with captive API supply, forcing pure-play formulation specialists toward either long-term offtake agreements or exit from premium dosage form competition.
Pricing Analysis
Cost-plus contracts with API feedstock indexation to para-chlorobenzoyl chloride and isobutyric acid commodity benchmarks dominate procurement between Indian API manufacturers and Western generic formulation clients. Three-tier pricing structure across extended-release, micronized immediate-release, and standard tablet categories separates patent-protected delivery mechanisms from commodity generics, with quality-grade differentiation (FDA inspection history, EDQM certification) commanding additional premia. Cost compression in standard fenofibrate tablets is intensifying because Chinese API oversupply and Brazilian ANVISA price controls force cross-border arbitrage. Hospital procurement through United States group purchasing organizations exhibits lowest price sensitivity due to protocol standardization, while Brazilian retail pharmacy chains face maximum pressure from government reference pricing.
Supply Chain Analysis
Para-chlorobenzoyl chloride and isobutyric acid feedstock supply draws from Zhejiang and Jiangsu province petrochemical clusters, with fenofibrate API synthesis capacity concentrating in China, India, and Italy. Raw material dependencies extend to micronization equipment for particle size engineering, gelatin capsule shells, and hydroxypropyl methylcellulose for extended-release matrix systems. Single-source vulnerability in Chinese API intermediates creates exposure to environmental compliance shutdowns and export license suspensions. Distribution runs through Mumbai and Ahmedabad export hubs to formulation facilities in New Jersey, North Carolina, and the Rhine-Main corridor, with secondary consolidation at Rotterdam and Singapore for European and Asia-Pacific markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The fibrate drugs market is entering a cyclical recovery phase as cardiovascular outcome trial data refreshes prescriber confidence and Medicare reimbursement policies stabilize combination therapy protocols. Patent cliff dynamics for extended-release formulations and API supply consolidation create asymmetric opportunity windows across stakeholder positions.
For Market Incumbents: Harden formulary lock-in through exclusive group purchasing organization contracts that embed real-world evidence dashboards for hospital procurement committees. Deepen backward integration into fenofibrate API production via acquisition of CDSCO-inspected Indian manufacturers to neutralize Chinese supply disruption risk. Anchor defensive positioning against high-intensity statin substitution by accelerating fixed-dose combination development through FDA bioequivalence pathways.
For New Entrants and Emerging Players: Brazilian retail pharmacy underpenetration for affordable gemfibrozil generics offers the most accessible volume ramp, with ANVISA pricing controls favoring domestic formulation producers over imports. Target Maharashtra and Gujarat diabetic population expansion with localized production partnerships that bypass import duty structures. Deploy direct-to-clinic detailing models for endocrinology practices managing severe hypertriglyceridemia, bypassing consolidated hospital procurement gatekeepers.
For Investors and Strategic Acquirers: Mid-scale API-to-formulation integrators with CDSCO and FDA dual-inspection status represent the optimal acquisition target archetype, capturing margin expansion from supply chain regionalization and quality-tier pricing premia. Long-term viability hinges on continuous manufacturing technology adoption curves and EMA cardiovascular outcome evidence requirements reshaping R&D productivity. Monitor FDA Office of Generic Drugs bioequivalence study backlog clearance rates as the inflection signal for generic entry timing and price erosion velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Manufacturing Scale-Up | Flow chemistry deployment at Sun Pharmaceutical's Ahmedabad facility reduces solvent waste and accelerates FDA inspection readiness. |
| Extended-Release Patent Extension | Abbott Laboratories' formulation exclusivity in United States retail channels sustains margin pools beyond standard generic erosion curves. |
| Fixed-Dose Combination Development | Fibrate-statin co-therapy alignment with Medicare reimbursement policies drives hospital formulary adoption through GPO contracts. |
| API Supply Regionalization | Indian CDSCO-inspected manufacturers capture share from Chinese producers facing NMPA environmental compliance upgrades. |
| Real-World Evidence Generation | Hospital system partnerships delivering cardiovascular outcome data satisfy formulary committee demands for total cost-of-care analyses. |
Research Methodology
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary interview findings were cross-validated against FDA ANDA filings, EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, and United States Medicare Part D formulary databases. Bottom-up prescription volume modeling and top-down pharmaceutical market sizing were triangulated to constrain estimate variance.
Scenario-bracketing around bioequivalence approval timelines, API supply disruption frequencies, and cardiovascular outcome trial readouts structured the analytical framework across the projection horizon. Segmentation dimensions included product type, therapy area, dosage form technology, end-user channel, and regional regulatory cluster. CAGRs were derived from prescription volume trend extrapolation, pricing elasticity modeling, and patent expiry impact assessment, with inputs from continuous manufacturing adoption curves and EMA guideline revision schedules.
Practitioners should monitor FDA bioequivalence backlog clearance rates, NMPA environmental enforcement actions in Zhejiang province, and ANVISA pricing control announcements for early signals of forecast revision. Cross-checking against IQVIA prescription audit data and CMS Medicare expenditure trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Thermal Analysis Market
Pharmaceutical Ingredients
Alpha Lipoic Acid API Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Epcam Antagonists Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Heparin Sodium API Market
Pharmaceutical Ingredients
Fipronil Market
Pharmaceutical Ingredients
Global Tizanidine Market
Pharmaceutical Ingredients
Non-Steroidal Anti-Inflammatory Drugs (Nsaids) Market
Pharmaceutical Ingredients
Global Glycine Supplement Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Silica Gel Market