
 Ferrous Succinate Market | 2026-2036
Ferrous Succinate Market Size, Share, and Industry Trends Forecast 2026-2036
Ferrous Succinate Market Insights
Asset-light contract manufacturing is tilting competitive dynamics toward firms that outsource production rather than build captive capacity. Sanofi leverages its European formulation network to serve regulated markets without heavy manufacturing commitments. DSM Nutritional Products anchors its position through backward integration into iron precursor sourcing, securing supply continuity for succinate salt production.
Ferrous succinate is an iron(II) salt of butanedioic acid, typically formulated at 100-200mg elemental iron equivalent per unit dose, manufactured through controlled precipitation of ferrous sulfate with succinic acid under inert atmosphere to prevent oxidation. The compound serves primarily as a bioavailable iron supplement with documented lower gastrointestinal irritation compared to ferrous sulfate equivalents. Tablets dominate current revenue pools due to established hospital procurement contracts and patient compliance advantages, while liquid formulations represent the fastest-expanding segment driven by pediatric and geriatric administration needs. Therapy area concentration in iron deficiency anemia reflects sustained clinical prescribing patterns, though nutritional supplement applications are gaining traction through direct-to-consumer channels.
The US FDA maintains bioequivalence requirements for generic iron supplements under ANDA pathways, while India's CDSCO enforces BIS purity standards for domestically manufactured ferrous salts. The EU's REACH framework governs succinic acid feedstock registration, creating compliance thresholds for imported active pharmaceutical ingredients. Stakeholders must monitor evolving pharmacopeial monograph revisions that could redefine dissolution specifications and force portfolio-wide reformulation decisions.
Market Dynamics
Pharmaceutical-grade iron salt production is consolidating around contract manufacturing networks that outsource precipitation and tableting operations, compressing capital requirements for market entry while raising quality-assurance barriers through EU REACH and FDA bioequivalence mandates.
Growth Catalysts
- Hospital network expansion:Government-funded anemia treatment programs across Southeast Asian markets are standardizing ferrous succinate procurement for oral solid dosage regimens in clinic settings.
- Purity standard harmonization:India's BIS and CDSCO alignment on ferrous salt specifications is streamlining export documentation for domestic manufacturers targeting regulated markets.
- Feedstock availability:Succinic acid production from bio-based fermentation routes is stabilizing precursor costs for salt precipitation processes.
Market Restraints
- Ferrous ion oxidation sensitivity:Inert atmosphere requirements during precipitation add nitrogen blanketing costs that ferrous sulfate production avoids.
- API import dependency:European formulators rely on Chinese and Indian active pharmaceutical ingredient suppliers, exposing schedules to customs inspection backlogs.
- Substitute competition:Ferrous bisglycinate and iron polysaccharide complex formulations compete for pediatric and geriatric prescriptions where gastrointestinal tolerability is prioritized.
Strategic Opportunities
- Liquid formulation white space:Pediatric administration protocols in Vietnamese and Indonesian public health programs are creating demand for non-tablet iron delivery systems.
- Direct-to-consumer channels:Nutritional supplement positioning through e-commerce platforms bypasses hospital procurement bottlenecks for maintenance-dose iron products.
- Green chemistry incentives:EU Green Deal funding streams favor bio-succinic acid feedstock adoption, qualifying reformulated products for preferential tender scoring.
Industry Challenges
- Analytical method transfer:Dissolution testing protocol variations between USP and EP monographs force dual-validation investments for multi-territory submissions.
- Packaging integrity certification:Child-resistant closure compliance for liquid ferrous succinate bottles requires specialized blow-fill-seal line upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ferrous Succinate Market |
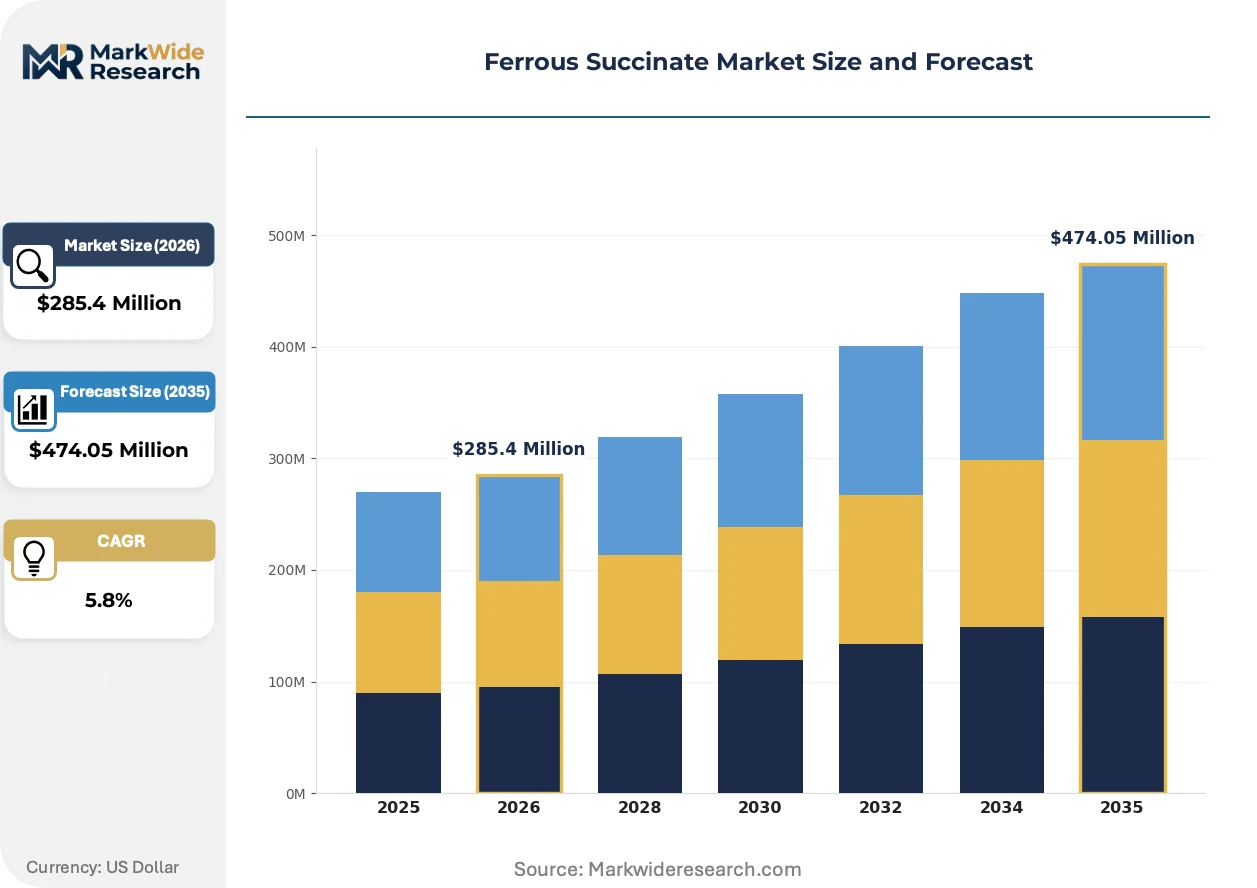
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Liquids Therapy Area: Iron Deficiency, Anemia, Nutritional Supplements, Gastrointestinal Disorders End User: Hospitals, Clinics, Pharmacies, Home Care Distribution Channel: Online Retail, Drug Stores, Supermarkets, Wholesalers |
| Companies Covered | Sanofi, Pfizer Inc., Novartis AG, Bayer AG, Abbott Laboratories, GlaxoSmithKline plc, Merck & Co., Inc., DSM Nutritional Products, Amgen Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ferrous Succinate Market Trends and Innovations
Process analytical technology adoption is transforming batch-release protocols for iron salt manufacturing, compressing quality control timelines while tightening deviation detection thresholds across GMP-certified facilities.
Continuous manufacturing platforms for oral solid dosage production are virtualizing traditional batch-scale precipitation and drying operations. European contract manufacturers are retrofitting fluid bed granulation lines with real-time release testing capability. This technology shift is collapsing the minimum efficient scale for ferrous succinate tablet production, enabling mid-volume regional supply without dedicated facility construction.
EMA's revised elemental impurities guideline ICH Q3D implementation is forcing reformulation of excipient matrices and coating systems for iron-containing products. Manufacturers must document risk assessments for catalytic metal contamination across succinic acid supply chains. Pediatric liquid formulations face the tightest scrutiny given chronic exposure dosing patterns in prophylactic anemia programs.
Hospital procurement consortia are consolidating iron supplement purchasing through centralized tender platforms that unbundle formulation from packaging and distribution services. Generic ferrous salt suppliers compete on total cost-to-patient metrics rather than unit dose pricing alone. This behavior shift is most pronounced in German and French hospital networks where regional purchasing alliances now cover sixty percent of inpatient anemia therapy volume.
Ferrous Succinate Market Segmentation
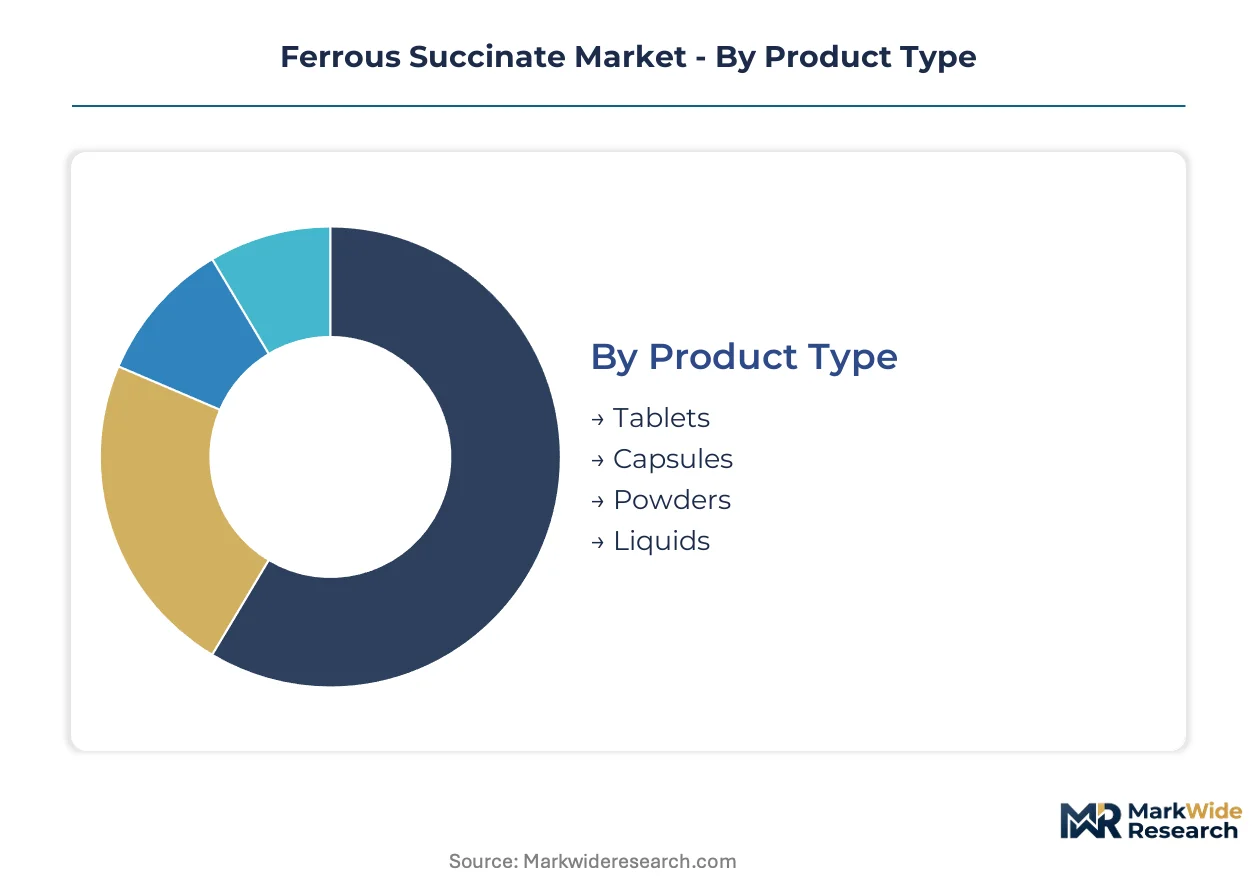
Ferrous succinate procurement patterns diverge sharply across administration formats and care settings. Hospital tenders favor solid oral dosage reliability, while direct-to-consumer channels reward formulation innovation for pediatric and geriatric populations.
Product Type:
After-sales service intensity concentrates in liquid formulations requiring stability monitoring and patient counseling support, whereas tablets demand minimal post-sale intervention beyond batch traceability.
- Tablets:Compressed ferrous succinate at 100-200mg elemental iron per unit dose dominates institutional procurement through established dissolution profiles and blister-pack stability. German and French hospital consortia standardize tablet specifications for anemia treatment protocols, locking in multi-year supply agreements with contract manufacturers.
- Liquids:Aqueous suspensions with flavor masking and dose flexibility serve Vietnamese and Indonesian pediatric prophylaxis programs where tablet administration fails. Child-resistant packaging compliance and cold-chain stability requirements elevate service costs for this segment.
- Capsules:Gelatin-encapsulated powders offer gastric acid protection through enteric coatings, appealing to gastroenterology prescriptions in Japanese clinics.
- Powders:Bulk active pharmaceutical ingredient shipments feed European contract formulation networks and Indian generic tablet producers.
By volume, Tablets leads. By growth pace, Liquids is ahead.
Therapy Area:
Margin profiles separate acute therapeutic applications from maintenance supplementation, with anemia protocols commanding premium pricing through clinical validation requirements.
- Iron Deficiency:Prophylactic dosing in Southeast Asian public health programs drives volume procurement through centralized tenders. India's CDSCO registration requirements for iron-fortification claims filter supplier participation.
- Anemia:Hospital-based intravenous-to-oral transition protocols in Chinese provincial medical centers specify ferrous succinate for hemoglobin recovery maintenance. Reimbursement coding specificity limits generic substitution.
- Nutritional Supplements:Direct-to-consumer positioning through European e-commerce platforms bypasses prescription channels, requiring FSSAI compliance for Indian-manufactured exports.
- Gastrointestinal Disorders:Succinate salt tolerability advantages over ferrous sulfate capture gastroenterology prescriptions where mucosal irritation contraindicates standard iron therapy.
Revenue concentrates in Anemia applications. Nutritional Supplements expands most quickly through channel diversification.
End User:
Customer concentration patterns map to procurement sophistication, with hospital networks consolidating purchasing power while home care fragments across retail touchpoints.
- Hospitals:Regional purchasing alliances in Germany and France cover sixty percent of inpatient iron therapy volume through unbundled tender structures separating API from packaging services.
- Clinics:Government-funded anemia screening programs across Indonesian district health centers standardize ferrous succinate for oral solid regimens.
- Pharmacies:Community dispensaries in Indian urban corridors stock generic ferrous salts for over-the-counter maintenance dosing.
- Home Care:Long-term care facilities in Japan favor liquid formulations for dysphagia patients requiring assisted administration.
Hospitals anchor procurement volume. Home Care climbs fastest on aging-population dosing needs.
Distribution Channel:
Supply chain configuration determines geographic reach and margin retention, with digital platforms collapsing traditional wholesale markups for branded supplement positioning.
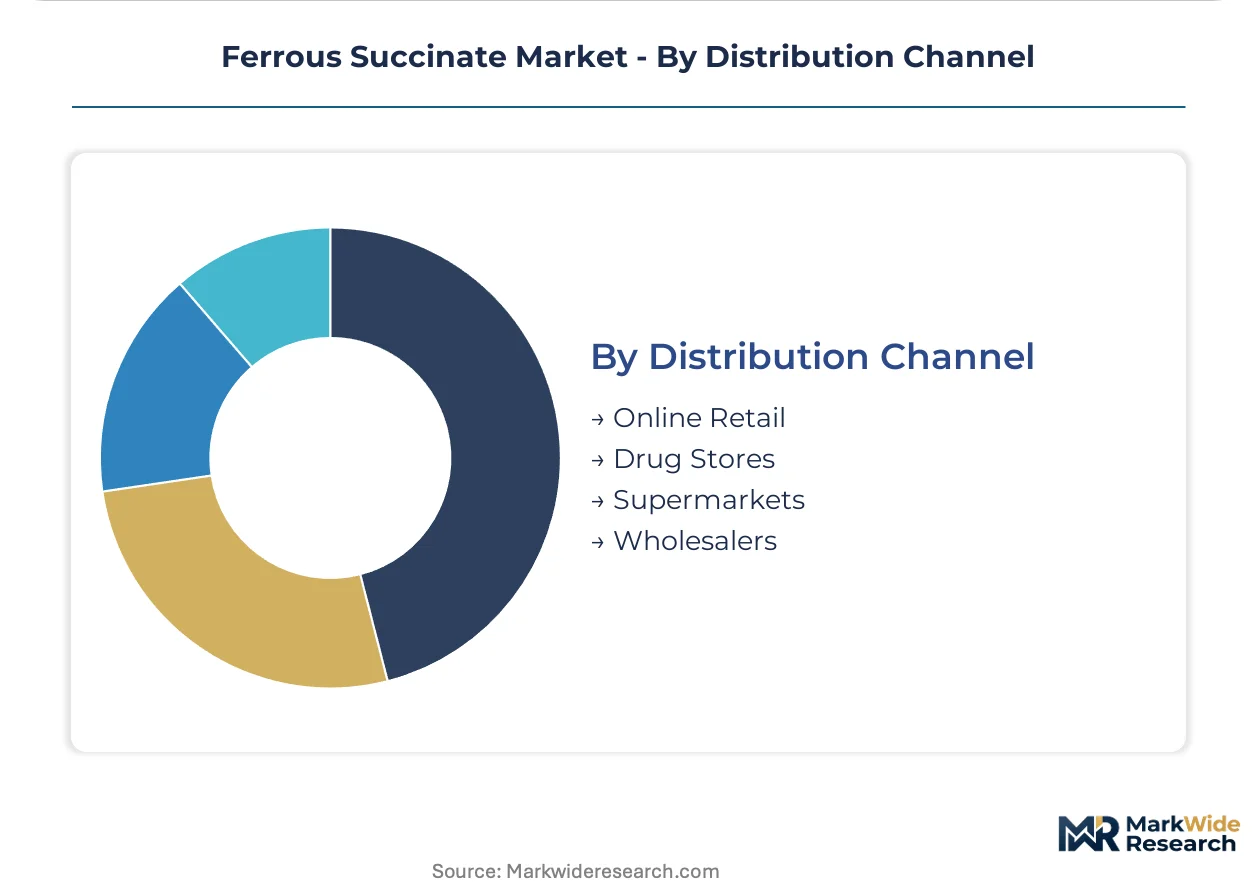
- Online Retail:Amazon and regional platforms capture nutritional supplement demand through subscription models, requiring EU REACH documentation for cross-border succinic acid traceability.
- Drug Stores:Pharmacy chains in Brazil and Mexico stock prescription-grade ferrous succinate behind-the-counter with ANVISA serialization compliance.
- Supermarkets:Mass-market iron fortification products in US retail channels face FDA bioequivalence scrutiny for generic substitution claims.
- Wholesalers:Hospital procurement consortia in Europe bypass wholesale tiers through direct manufacturer contracting for anemia therapy volumes.
Wholesalers move the largest tonnage. Online Retail gains share fastest on direct-to-consumer supplement growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in ferrous succinate trace a clear arc: Chinese and Indian API producers supply European formulators, while Southeast Asian governments deploy domestic procurement for public health programs. This trade pattern concentrates value capture in formulation networks while fragmenting upstream production.
China
Provincial medical centers in Jiangsu and Zhejiang specify ferrous succinate for hemoglobin recovery protocols following intravenous iron transitions. NMPA registration pathways for iron supplements tighten documentation requirements for elemental impurity risk assessments. Contract manufacturers in the Yangtze River Delta retrofit fluid bed granulation lines with real-time release testing to serve EU hospital tenders.
India
Domestic pharmaceutical manufacturers scale tablet production to supply expanding clinic networks under the National Iron Plus Initiative. CDSCO alignment with BIS purity standards streamlines export documentation for regulated markets. API producers in Hyderabad and Ahmedabad consolidate precipitation capacity to capture contract manufacturing demand from European formulators.
Germany
Regional hospital purchasing alliances in Bavaria and North Rhine-Westphalia unbundle API procurement from packaging services for anemia therapy volumes. EMA's ICH Q3D implementation forces reformulation of iron-containing excipient matrices and coating systems. Contract manufacturers in the Frankfurt-Rhine-Main cluster upgrade blow-fill-seal lines for child-resistant liquid packaging compliance.
France
ANSM oversight of nutritional supplement positioning tightens claims substantiation for direct-to-consumer iron products. Hospital consortia in Île-de-France and Auvergne-Rhône-Alpes standardize ferrous succinate tablet specifications through multi-year supply agreements. Bio-succinic acid feedstock adoption qualifies reformulated products for EU Green Deal preferential tender scoring.
Vietnam
District health centers in Hanoi and Ho Chi Minh City deploy liquid ferrous succinate for pediatric prophylaxis programs where tablet administration fails. Government-funded anemia screening protocols standardize oral solid regimens in clinic settings. Cold-chain stability requirements for liquid formulations elevate service costs for distributors serving Mekong Delta provinces.
Ferrous Succinate Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in API and precursor supply. The vendor base stratifies between multinational pharmaceutical conglomerates with formulation networks and regional contract manufacturers with precipitation expertise. Three archetypes dominate: backward-integrated nutraceutical suppliers, asset-light European formulators outsourcing production, and Indian generic API producers scaling for export. Competitive moves concentrate on M&A for manufacturing capacity and strategic partnerships for bio-succinic acid feedstock security.
Within the asset-light formulator tier, Sanofi leverages its European network to serve regulated markets without heavy manufacturing commitments. DSM Nutritional Products anchors the backward-integrated archetype through upstream control over iron precursor sourcing. Among Indian generic producers, Dr. Reddy's Laboratories and Cipla occupy positions scaling API output for hospital procurement consortia.
| Leading Market Players |
|---|
| Sanofi |
| Pfizer Inc. |
| Novartis AG |
| Bayer AG |
| Abbott Laboratories |
| GlaxoSmithKline plc |
| Merck & Co., Inc. |
| DSM Nutritional Products |
| Amgen Inc. |
| Others |
Pricing and Supply Chain Analysis
API import dependency on Chinese and Indian precipitation capacity exposes European formulators to customs inspection backlogs that widen pricing spreads between pharmaceutical-grade and nutritional-grade tiers while compressing margins across contract manufacturing networks.
Pricing Analysis
Hospital procurement consortia anchor a contract-based long-term offtake structure where pricing stratifies across pharmaceutical-grade, nutritional-grade, and bulk API tiers driven by EU REACH documentation burden and CDSCO registration depth. Price differentiation hinges on elemental impurity certification and dissolution profile validation, with German hospital alliances least price-sensitive due to unbundled tender structures while Indian generic tablet producers face intensifying cost compression from BIS purity standard alignment investments.
Supply Chain Analysis
Hyderabad and Ahmedabad contract manufacturers hold precipitation capacity serving European formulators who lack captive ferrous salt production. Supply concentrates in India and China for API precipitation, with European contract manufacturers handling final tableting and packaging. Raw material dependencies include bio-succinic acid feedstock, ferrous sulfate precursor, and nitrogen blanketing systems for oxidation prevention. Single-source vulnerability runs through Yangtze River Delta precipitation clusters. Distribution runs through hospital procurement consortia in Germany and France, with direct-to-consumer channels bypassing wholesale tiers for nutritional supplement positioning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital purchasing alliance consolidation across German and French networks has shifted bargaining power toward buyers, fragmenting supplier pricing power and forcing unbundled service competition.
For Market Incumbents: Insulate formulation margins by securing bio-succinic acid offtake agreements ahead of EU Green Deal tender scoring implementation, and deepen backward integration into iron precursor sourcing to offset API import dependency exposure to Indian precipitation capacity. DSM Nutritional Products' upstream control model demonstrates defensive positioning against substitute competition from ferrous bisglycinate and iron polysaccharide complex entrants. For New Entrants and Emerging Players: Establish a beachhead in Vietnamese and Indonesian liquid formulation procurement for pediatric prophylaxis programs where tablet administration fails and incumbent service costs are elevated. Target direct-to-consumer nutritional supplement channels through Amazon and regional e-commerce platforms, leveraging FSSAI compliance for Indian-manufactured exports to bypass hospital procurement bottlenecks. For Investors and Strategic Acquirers: EMA's ICH Q3D elemental impurities guideline implementation reshapes the acquisition landscape by forcing reformulation investments that favor targets with validated excipient risk assessment capabilities and blow-fill-seal line certifications for child-resistant packaging. Long-term viability centers on contract manufacturers with real-time release testing infrastructure and bio-succinic acid feedstock relationships. Watch NMPA registration pathway tightening in China as inflection signal for regional capacity rationalization.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Succinic Acid Feedstock Security | EU Green Deal preferential tender scoring rewards fermentation-derived precursor adoption. |
| Real-Time Release Testing Deployment | Fluid bed granulation retrofitting collapses minimum efficient scale for regional supply. |
| Liquid Formulation Line Certification | Child-resistant blow-fill-seal compliance captures Vietnamese pediatric program demand. |
| Backward Integration into Iron Precursors | Captive ferrous sulfate sourcing insulates against Indian API export documentation delays. |
| Direct-to-Consumer Channel Launch | E-commerce subscription models bypass German hospital consortium pricing compression. |
Research Methodology
A standing panel of pharmaceutical manufacturing executives, CDSCO regulatory affairs leads, European hospital procurement managers, and contract formulation specialists provided ongoing calibration throughout the study. Primary interview data combined with secondary validation from FDA ANDA filings, EMA submission databases, BIS purity standard revisions, and EU REACH registration records. Bottom-up tablet and liquid volume estimates triangulated against top-down anemia therapy market assessments across the analysis window.
Scenario-bracketing framed projections across pharmaceutical-grade, nutritional-grade, and bulk API segments with dosage form, therapy area, and regional regulatory cluster dimensions modeled throughout the forecast period. CAGRs derived from hospital tender volume trajectories, clinic network expansion rates, and direct-to-consumer channel penetration curves. Inputs included bio-succinic acid feedstock cost stabilization assumptions and dissolution testing protocol harmonization timelines between USP and EP monographs.
Stress conditions across succinic acid supply disruption, customs inspection backlog duration, and ICH Q3D implementation pace were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about procurement alliance consolidation and regulatory alignment trajectories. Quarterly review of NMPA registration pathway changes, EU Green Deal funding disbursement rates, and Indian PLI scheme iron salt eligibility is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Grade Beta-Alanine Market
Pharmaceutical Ingredients
Pharma Grade Ibuprofen API Market
Pharmaceutical Ingredients
Global Pharmaceutical Grade Sodium Chloride Market
Pharmaceutical Ingredients
Oral Doxycycline Hyclate Market
Pharmaceutical Ingredients
Germany Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Pharma-Grade Magnesium Trisilicate Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Histamine H2-Receptor Antagonists Market
Pharmaceutical Ingredients
Vitamins and Derivatives Market
Pharmaceutical Ingredients
United States Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Active Pharmaceutical Ingredient for Cancer Market
Pharmaceutical Ingredients
Co-Crystal Ingredient Market
Pharmaceutical Ingredients
Global Tacrolimus Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Pharmaceutical Excipients for Taste Masking Market
Pharmaceutical Ingredients
Global Antazoline Market