
 Originator Small Molecule Drug Market | 2026-2036
Originator Small Molecule Drug Market Size, Share, and Industry Trends Forecast 2026-2036
Originator Small Molecule Drug Market Analytics
Patent cliff revenue recovery is narrowing as biosimilar competition intensifies and originator firms pivot toward combination therapies. Pfizer Inc. leverages its manufacturing scale to defend blockbuster franchises, while Merck & Co. Inc. anchors its position through deep oncology specialization. F. Hoffmann-La Roche Ltd differentiates via diagnostic-companion drug integration, sustaining premium positioning across European and Asian markets.
Originator small molecule drugs are synthetically produced chemical compounds, typically under 900 daltons in molecular weight, manufactured through multi-step organic synthesis with defined stereochemistry and purity profiles exceeding 99.5%, designed for oral or parenteral delivery to modulate specific biological targets. These agents serve as the backbone of chronic disease management, offering standardized dosing, established bioequivalence frameworks, and scalable production relative to biologics. Oncology formulations command the largest therapy area share, driven by kinase inhibitors and immune-modulatory small molecules, while injectable delivery systems represent the fastest-expanding formulation category as hospitals prioritize acute care administration. Hospital distribution channels capture the dominant volume flow, though online pharmacy penetration is accelerating for maintenance therapies in reimbursed markets.
FDA breakthrough therapy designation and EMA PRIME eligibility reshape competitive timelines by compressing Phase II-to-approval intervals for qualifying small molecules. REACH compliance and FDA current good manufacturing practice standards enforce purity thresholds that elevate capital requirements for new entrants, reinforcing incumbent advantages. Stakeholders must monitor payer consolidation trends and indication expansion strategies as primary determinants of long-term originator profitability.
Market Dynamics
Patent cliff pressures are compressing originator revenue windows as biosimilar entries accelerate and FDA breakthrough designations reward first-movers with truncated approval timelines. Kinase inhibitor portfolios face concentrated generic erosion, forcing reinvestment into combination regimens and diagnostic-companion integrations.
Growth Catalysts
- FDA Breakthrough Therapy Designation:Compressed Phase II-to-approval intervals reward qualifying oncology small molecules with expedited market entry and extended exclusivity premiums.
- Hospital oncology procurement expansion:Chronic disease burdens in the United States, China, and Germany sustain volume commitments for injectable kinase inhibitors and immune-modulatory formulations.
- EMA PRIME eligibility:Priority medicines status accelerates scientific advice and accelerated assessment pathways for unmet medical need indications.
Market Restraints
- API supply concentration:China and India dominate active pharmaceutical ingredient manufacturing, creating single-source vulnerabilities for multi-step synthetic intermediates.
- REACH compliance costs:European Chemicals Agency registration requirements for novel synthetic intermediates elevate capital barriers for European manufacturing expansion.
- Biosimilar substitution threat:Oncology and immunology biologics displace small molecule market share in rheumatoid arthritis and colorectal cancer treatment protocols.
Strategic Opportunities
- Diagnostic-companion integration:CDx co-development with biomarker platforms enables premium positioning and payer justification for targeted small molecule therapies.
- Online pharmacy channel penetration:Maintenance therapy dispensing through reimbursed digital platforms reduces hospital dependency for chronic oral formulations.
- India PLI scheme for APIs:Production-linked incentives for domestic pharmaceutical intermediates offer alternative sourcing bases to Chinese supply concentration.
Industry Challenges
- Stereochemistry control talent scarcity:Multi-step chiral synthesis expertise concentrates among legacy chemists, constraining workforce expansion for complex kinase inhibitor manufacturing.
- cGMP facility capex intensity:FDA current good manufacturing practice compliance for sub-100 nanogram impurity thresholds requires continuous investment in analytical and purification infrastructure.
- IP litigation complexity:Crystalline form and polymorph patent disputes delay generic entry planning and create licensing negotiation friction for originator defense strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Originator Small Molecule Drug Market |
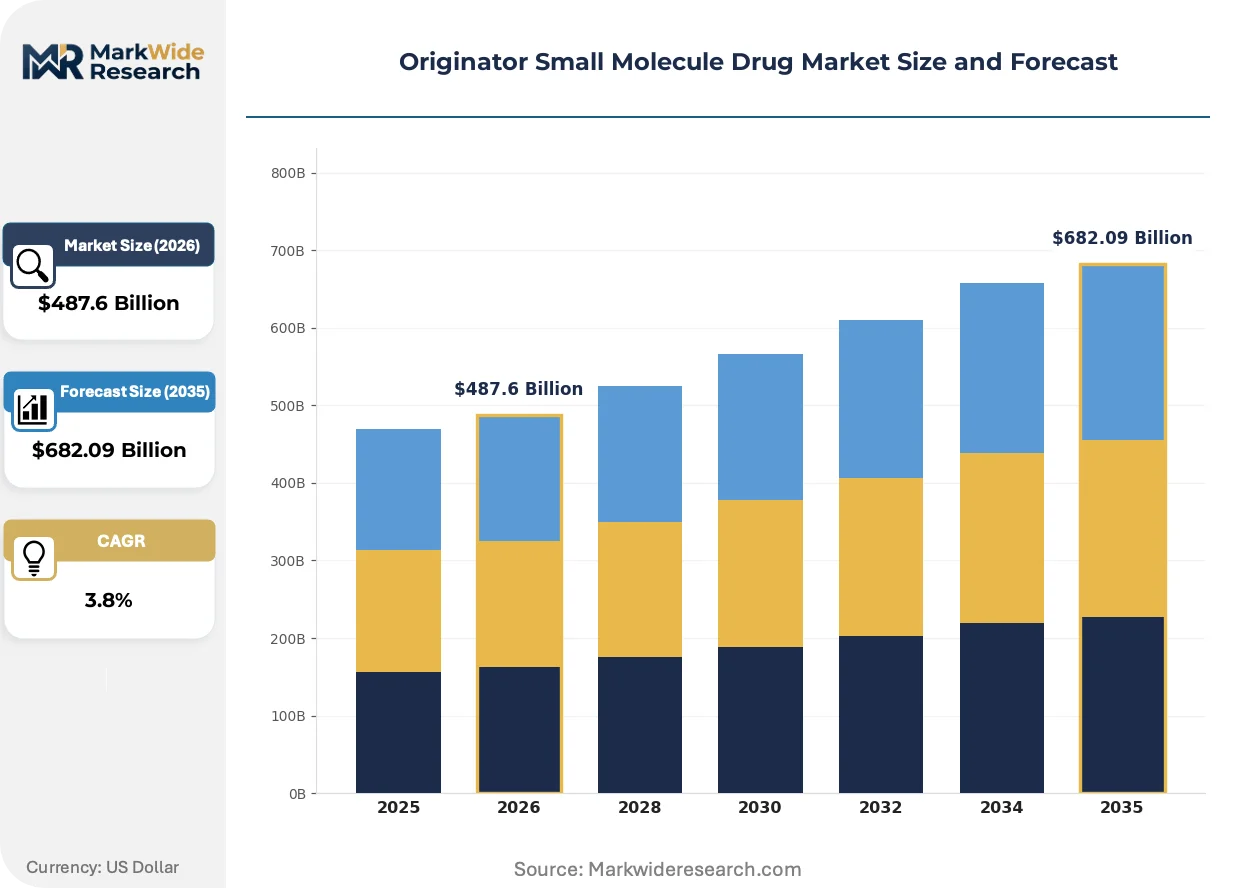
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $682.09 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Therapy Area: Oncology, Cardiovascular, Neurology, Infectious Diseases Formulation Type: Tablet, Capsule, Injectable, Solution Distribution Channel: Pharmacies, Hospitals, Online, Clinics End User: Healthcare Providers, Research Institutions, Patients, Contract Manufacturers |
| Companies Covered | Pfizer Inc., Merck & Co. Inc., GlaxoSmithKline PLC, F. Hoffmann-La Roche Ltd, Eli Lilly and Company, Bayer AG, Johnson & Johnson, AstraZeneca, Novartis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Originator Small Molecule Drug Market Evolving Landscape
Continuous manufacturing adoption is redrawing capital deployment patterns across synthetic chemistry operations, compressing batch cycle times and elevating real-time release testing standards. These shifts intersect with regulatory digitalization and procurement consolidation to reshape competitive positioning.
Continuous flow reactor technology is migrating from pilot-scale demonstration to commercial-scale kinase inhibitor production, enabling Pfizer and Merck to compress residence times from days to hours while maintaining stereochemical purity above 99.5%. Contract manufacturing organizations in Germany and Switzerland are retrofitting legacy batch facilities to accommodate modular flow chemistry skids. This migration from batch to continuous processing is enabling just-in-time inventory models that reduce working capital requirements and API waste streams by substantial margins.
EMA's PRIME scheme and FDA's breakthrough therapy designation are converging to create dual-track accelerated pathways, compressing development timelines for oncology small molecules addressing unmet needs. These frameworks reward early biomarker validation and adaptive trial designs with rolling regulatory reviews. European and American developers of KRAS and EGFR inhibitors are restructuring Phase II programs to capture these designations, prioritizing response-rate endpoints over survival data for initial approvals.
Hospital procurement consolidation is centralizing oncology formulary decisions under integrated delivery networks in the United States and hospital group purchasing organizations in Germany. These entities are unbundling drug acquisition from administration services, demanding outcome data and total-cost-of-care evidence for premium small molecule placement. Chinese tertiary hospitals are adopting similar consolidated purchasing through provincial centralized procurement platforms, compressing price negotiation windows for originator therapies.
Originator Small Molecule Drug Market Segmentation
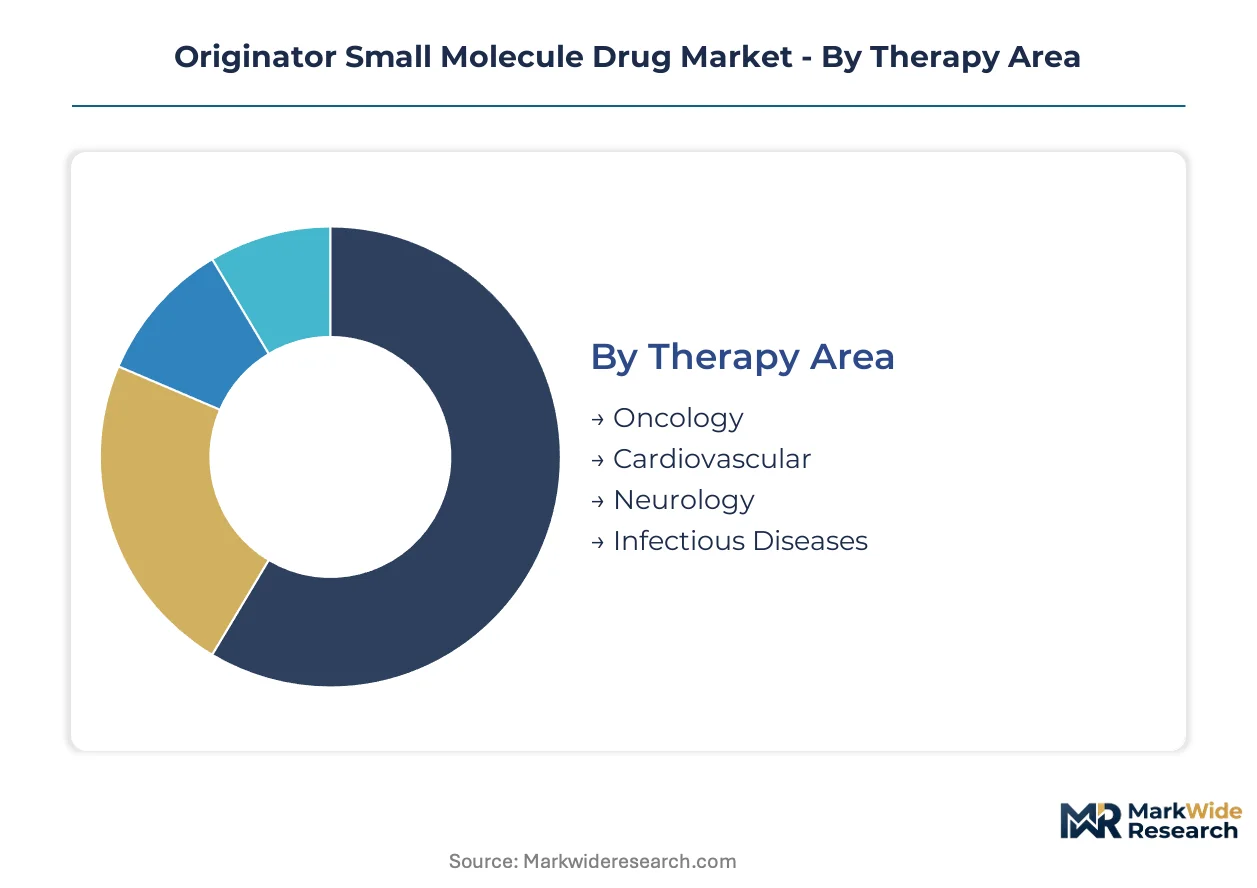
Segmentation in originator small molecule drugs reveals how therapeutic focus, delivery technology, and channel strategy determine pricing power and exclusivity duration. Kinase inhibitors and continuous manufacturing capabilities now separate premium portfolios from commodity-exposed segments.
Therapy Area:
Mature cardiovascular franchises coexist with emerging neurology pipelines as patent cliffs reshape investment allocation across therapeutic domains.
- Oncology:Kinase inhibitors and immune-modulatory small molecules dominate hospital procurement in the United States, China, and Germany. FDA breakthrough therapy designation compresses Phase II-to-approval intervals for qualifying agents, extending premium pricing windows before biosimilar erosion.
- Cardiovascular:Anticoagulant and antihypertensive formulations represent mature revenue streams facing concentrated generic substitution. Maintenance therapy demand sustains volume but compresses margin as payer consolidation intensifies price negotiation leverage.
- Neurology:Alzheimer's and Parkinson's disease small molecules command development priority as unmet need indications attract EMA PRIME eligibility and adaptive trial frameworks.
- Infectious Diseases:Antiviral and antibiotic formulations serve acute care protocols with shorter treatment durations and hospital-centric distribution.
Oncology handles the majority of throughput; neurology is expanding most quickly on share as amyloid-targeting small molecules advance through regulatory pathways.
Formulation Type:
Cost tier differentiation separates high-complexity sterile injectables from commoditized oral solids in capital deployment and margin structure.
- Injectable:Sterile kinase inhibitor solutions for hospital oncology administration require continuous manufacturing infrastructure and real-time release testing. Pfizer and Merck deploy modular flow chemistry skids to compress residence times while maintaining stereochemical purity thresholds above 99.5%.
- Tablet:Oral solid dosage forms for chronic cardiovascular and neurology maintenance therapy scale through conventional batch processing with established bioequivalence frameworks.
- Capsule:Encapsulated formulations accommodate moisture-sensitive APIs and modified-release profiles for gastrointestinal-targeted delivery.
- Solution:Liquid oral and parenteral preparations serve pediatric and geriatric populations with swallowing difficulties or precise titration requirements.
Injectable captures the steepest expansion trajectory as integrated delivery networks prioritize acute care administration; tablet retains the largest volume base for maintenance regimens.
Distribution Channel:
Customer type concentration determines whether originators negotiate with consolidated hospital systems or fragmented retail networks.
- Hospitals:Integrated delivery networks in the United States and hospital group purchasing organizations in Germany centralize oncology formulary decisions. These entities unbundle drug acquisition from administration services and demand total-cost-of-care evidence for premium placement.
- Pharmacies:Retail and specialty pharmacy channels dispense maintenance therapies for cardiovascular and neurology indications with established reimbursement pathways.
- Online:Digital pharmacy platforms accelerate penetration for chronic oral formulations as reimbursed markets reduce hospital dependency for refill dispensing.
- Clinics:Outpatient infusion centers and physician office settings administer injectable regimens with lower overhead than tertiary hospital facilities.
Hospitals dominate value throughput; online channels are climbing the fastest as provincial centralized procurement platforms in China and digital health infrastructure mature.
End User:
Margin structure varies sharply between direct patient access and institutional procurement with outcome-based contracting requirements.
- Healthcare Providers:Physicians and hospital systems prescribe originator therapies based on clinical guidelines, payer formularies, and companion diagnostic integration. EMA PRIME eligibility and FDA accelerated pathways influence prescribing confidence for novel mechanisms.
- Patients:Direct acquisition through specialty pharmacies or patient assistance programs addresses high-deductible plan exposure and coinsurance burdens in the United States.
- Research Institutions:Academic medical centers and contract research organizations source reference standards and investigational supplies for bioequivalence and clinical trial comparator arms.
- Contract Manufacturers:CDMOs in Germany and Switzerland retrofit legacy batch facilities for continuous flow reactor technology, serving originator firms seeking capacity flexibility without captive cGMP infrastructure investment.
Healthcare providers command the dominant prescription volume; contract manufacturers are gaining share fastest as originators externalize complex synthesis steps.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity diverges sharply across procurement systems. United States integrated delivery networks negotiate outcome-based contracts that sustain premium positioning for patented kinase inhibitors. Chinese provincial centralized procurement platforms compress margins through volume-based tendering, forcing originators to accept steep discounts for hospital formulary access.
United States
FDA breakthrough therapy designation accelerates Phase II-to-approval intervals for oncology small molecules addressing unmet needs. Hospital group purchasing organizations and integrated delivery networks in the Northeast and Midwest unbundle drug acquisition from administration services, demanding total-cost-of-care evidence for premium placement. Greater Boston and San Francisco Bay Area anchor clinical trial density for adaptive oncology protocols.
China
NMPA priority review pathways and provincial centralized procurement platforms reshape competitive dynamics for originator therapies. Volume-based procurement in Jiangsu and Guangdong provinces forces multinational firms to bid against domestic manufacturers for tertiary hospital formulary slots. Yangtze River Delta manufacturing clusters in Shanghai and Suzhou concentrate active pharmaceutical ingredient synthesis for export markets.
Germany
EMA PRIME eligibility and accelerated assessment pathways reward early biomarker validation for novel small molecule mechanisms. Hospital group purchasing organizations in North Rhine-Westphalia and Bavaria centralize oncology formulary decisions, requiring pharmacoeconomic evidence for premium positioning. Baden-Württemberg contract manufacturing organizations retrofit batch facilities for continuous flow reactor technology serving European originator demand.
India
CDSCO accelerated approval frameworks and PLI scheme incentives for domestic pharmaceutical intermediates attract multinational sourcing diversification. Maharashtra and Gujarat API manufacturing clusters offer alternative supply bases to Chinese concentration for multi-step synthetic intermediates. Telangana and Karnataka clinical research organizations expand bioequivalence and comparator arm supply capabilities.
Switzerland
Swissmedic regulatory efficiency and bilateral mutual recognition agreements with EMA sustain rapid market entry for innovative small molecules. Basel and Zurich anchor diagnostic-companion drug integration capabilities, enabling biomarker-linked therapy positioning. Swiss contract manufacturing organizations specialize in high-potency oncology API synthesis with containment infrastructure exceeding standard cGMP requirements.
Originator Small Molecule Drug Market Competitive Landscape
Capability concentration sits with specialized oncology developers; scale advantage sits with diversified pharmaceutical conglomerates. The market structure tiers between integrated innovators with diagnostic-companion platforms and manufacturing-heavy defenders of mature cardiovascular franchises. Two archetypes dominate: precision oncology specialists leveraging biomarker integration, and broad-portfolio giants deploying manufacturing scale to defend blockbuster revenue streams. Competitive moves center on continuous manufacturing infrastructure deployment and diagnostic-companion co-development partnerships.
Within the diversified pharmaceutical tier, Pfizer Inc. and Merck & Co. Inc. occupy positions defined by manufacturing scale and oncology specialization respectively. F. Hoffmann-La Roche Ltd exemplifies the diagnostic-integrated archetype, anchoring premium positioning through biomarker-linked therapy development. These three firms represent contrasting strategic postures: scale-driven defense, therapeutic area depth, and companion diagnostic synergy.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Merck & Co. Inc. |
| GlaxoSmithKline PLC |
| F. Hoffmann-La Roche Ltd |
| Eli Lilly and Company |
| Bayer AG |
| Johnson & Johnson |
| AstraZeneca |
| Novartis |
| Others |
Value Network & Pricing Analysis
Yangtze River Delta API manufacturing clusters anchor global intermediate supply, and their capacity utilization rates transmit directly into originator pricing power for kinase inhibitors and immune-modulatory formulations. Hospital procurement consolidation in the United States, China, and Germany amplifies this leverage, as integrated delivery networks demand total-cost-of-care evidence while provincial tendering platforms force steep discount acceptance.
Pricing Analysis
After-sales revenue through diagnostic-companion integration and patient assistance programs drives lifetime value for originator small molecules. Value-based contracting with hospital group purchasing organizations separates premium kinase inhibitor positioning from commoditized cardiovascular formulations. Pricing pressure stems from Chinese provincial centralized procurement platforms compressing margins through volume-based tendering. Research institutions and contract manufacturers exhibit highest price sensitivity due to budget constraints, while integrated delivery networks in the United States demonstrate lowest sensitivity when outcome data supports premium placement.
Supply Chain Analysis
Export-control restrictions on dual-use chemical processing equipment limit technology transfer to emerging API manufacturing hubs. Active pharmaceutical ingredient synthesis concentrates in China and India, with Swiss and German contract manufacturing organizations serving high-potency oncology containment requirements. Multi-step synthetic intermediates, chiral catalysts, and specialized solvents constitute critical input dependencies. Single-source vulnerability pervades the supply base as legacy chemists with stereochemistry control expertise retire without replacement training. Distribution runs through hospital group purchasing organizations and integrated delivery networks for oncology formulations, with online pharmacy channels expanding for maintenance therapy refill dispensing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Diagnostic-companion drug platforms are reconfiguring this market around biomarker-linked therapy ecosystems, with FDA breakthrough therapy designation and EMA PRIME eligibility creating interoperability standards that reward early biomarker validation. This platform-economics inflection favors developers who integrate CDx co-development into Phase II program structures.
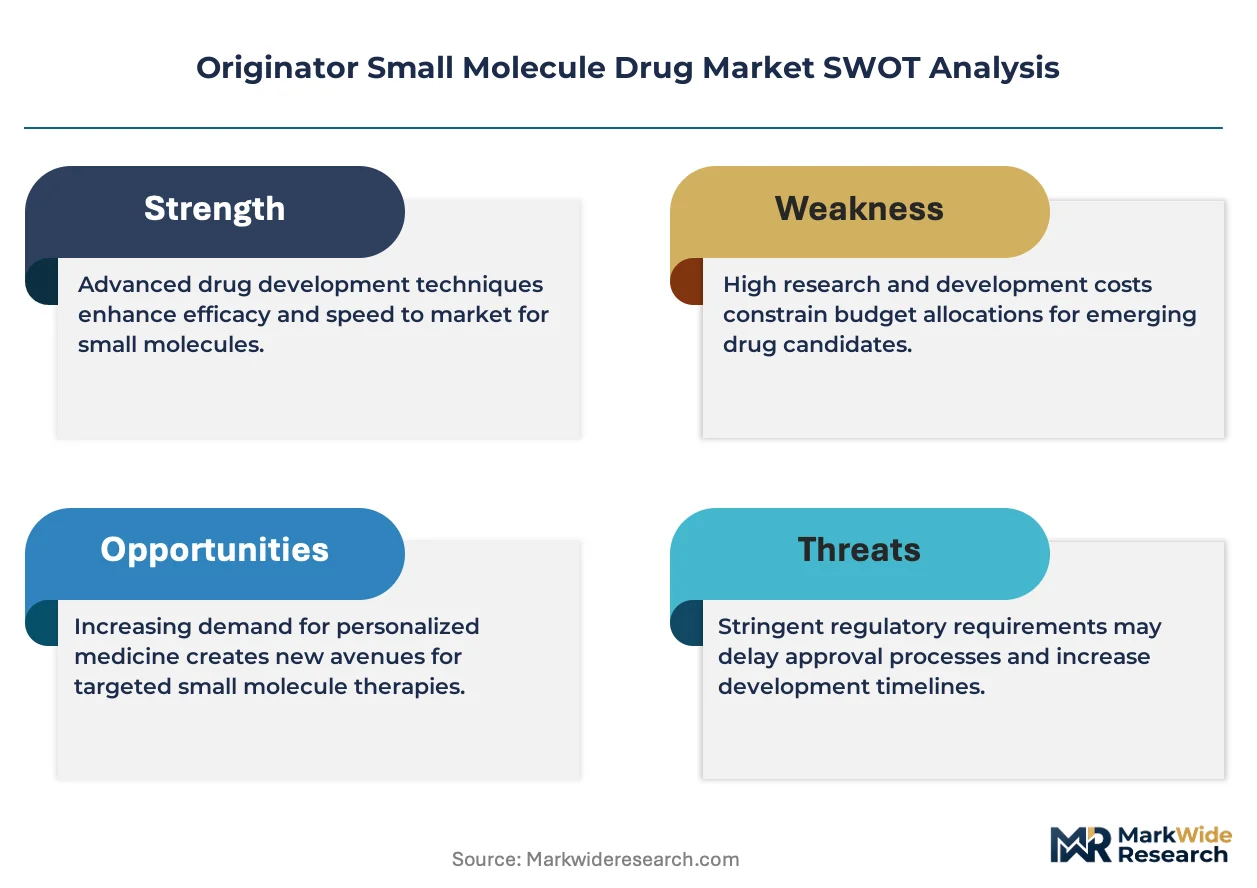
For Market Incumbents: Build regulatory exclusivity moats through FDA breakthrough therapy designation capture and EMA PRIME eligibility maintenance. Defend against biosimilar substitution by accelerating combination regimen development and securing companion diagnostic partnerships. Backward integration into continuous manufacturing infrastructure reduces API waste streams and compresses batch cycle times. Capacity expansion in Swiss and German high-potency containment facilities reinforces premium positioning for oncology formulations.
For New Entrants and Emerging Players: Establish a beachhead in neurology indications with EMA PRIME eligibility and adaptive trial frameworks, where amyloid-targeting small molecules face less entrenched competition than kinase inhibitor portfolios. Target online pharmacy channel penetration for chronic cardiovascular and neurology maintenance therapies, where hospital procurement consolidation has created distribution gaps. White-space exists in diagnostic-companion integration services for mid-tier originators lacking in-house biomarker platforms. Go-to-market leverage rests on CDx co-development partnerships with academic medical centers.
For Investors and Strategic Acquirers: Long-term, this sits as a capability-scarcity play because stereochemistry control expertise concentrates among legacy chemists approaching retirement without adequate replacement pipelines. Acquisition targets should display continuous manufacturing infrastructure deployment or diagnostic-companion platform integration. Signal to monitor: FDA breakthrough therapy designation density by therapeutic area, as compression of Phase II-to-approval intervals indicates where premium pricing windows will extend longest.
| Strategic Initiative | Industry Significance |
|---|---|
| Diagnostic-Companion Integration | CDx co-development with biomarker platforms enables premium payer justification for targeted kinase inhibitors. |
| Continuous Manufacturing Scale-Up | Modular flow chemistry skids compress residence times while maintaining FDA-mandated stereochemical purity thresholds. |
| Regulatory Acceleration Pathway | FDA breakthrough therapy designation and EMA PRIME eligibility compress development timelines for oncology small molecules. |
| API Supply Diversification | India PLI scheme incentives attract multinational sourcing away from Chinese intermediate concentration. |
| Online Pharmacy Channel Expansion | Digital dispensing platforms reduce hospital dependency for chronic oral formulation maintenance therapy refills. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up volume estimates across therapy areas, formulation types, and distribution channels were triangulated against top-down market sizing from trade data and industry association reports.
Calibration anchored on historical approval timelines for kinase inhibitors and immune-modulatory small molecules, with projection mechanics spanning therapy area, formulation complexity, and regional regulatory cluster. CAGRs were derived from patent expiry schedules, biosimilar entry assumptions, and hospital procurement expansion trajectories. Forecast inputs incorporated FDA breakthrough therapy designation density, EMA PRIME eligibility rates, and provincial centralized procurement platform penetration in China.
Sensitivities concentrate around regulatory pathway acceleration, biosimilar substitution velocity, and API supply disruption scenarios. Forecasts reflect documented assumptions regarding payer consolidation trends and indication expansion strategies. Material shifts in FDA breakthrough therapy designation criteria, EMA accelerated assessment pathways, or Chinese volume-based procurement scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Pharmaceutical Lactose Market
Pharmaceutical Ingredients
Cyprosin Market
Pharmaceutical Ingredients
Kitasamycin Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Tiapride Hydrochloride API Market
Pharmaceutical Ingredients
Transdermal Drugs Market
Pharmaceutical Ingredients
Acetaminophen API Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Global Active Pharmaceutical Ingredients CDMO Market
Pharmaceutical Ingredients
Calcium Citrate Market
Pharmaceutical Ingredients
Oridonin Market
Pharmaceutical Ingredients
Penciclovir API Market
Pharmaceutical Ingredients
Pharmaceutical Grade Magnesium Hydroxide Market
Pharmaceutical Ingredients
Pharmaceutical Grade Amino Acid Market
Pharmaceutical Ingredients
Small-Molecule Injectable Market