
 Pharmaceutical Sterility Testing Market | 2026-2036
Pharmaceutical Sterility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Sterility Testing Market Intelligence
Modular test kit bundling is rebalancing procurement patterns among mid-size biopharmaceutical companies seeking scalable sterility workflows. Thermo Fisher Scientific leverages its consumables portfolio to anchor recurring revenue streams. Charles River Laboratories sustains competitive positioning through specialized biologics testing services. Sartorius AG differentiates with integrated membrane filtration platforms that reduce manual handling steps.
Pharmaceutical sterility testing comprises validated analytical methods designed to detect viable microorganisms in drug products, raw materials, and manufacturing environments, typically requiring incubation periods of fourteen days under controlled aerobic and anaerobic conditions to ensure absence of bacterial and fungal contamination. Its primary purpose is to verify that parenteral preparations, ophthalmic solutions, and implantable devices meet pharmacopeial standards before release to patients. Membrane filtration commands the largest share among test types due to its suitability for large-volume parenterals and antibiotic formulations where direct inoculation risks inhibition. Reagents and consumables generate the steadiest margin pools because laboratories must replenish these materials with every batch test cycle. Software segments exhibit the fastest structural expansion as laboratories integrate automated colony counting with laboratory information management systems.
FDA sterility testing guidelines, USP Chapter 71, and EU GMP Annex 1 collectively mandate environmental monitoring, media fill validation, and rapid microbiological methods where scientifically justified, elevating compliance costs while accelerating adoption of automated platforms. Health Canada and Japan's PMDA maintain aligned but distinct pharmacopeial requirements that create regional certification burdens for multinational manufacturers. Stakeholders must weigh capital deployment between rapid microbial detection technologies and conventional compendial methods as regulatory acceptance of alternative methodologies continues to evolve.
Market Dynamics
Automated membrane filtration platforms are compressing manual labor requirements while FDA and EMA sterility guideline revisions force laboratories to revalidate entire workflows, creating simultaneous cost pressure and capability investment demands across contract testing organizations and in-house quality labs.
Growth Catalysts
- Cell and gene therapy manufacturing scale-up:Biopharmaceutical companies building commercial-scale autologous therapy facilities require validated sterility testing capacity that matches batch complexity and patient-specific release timelines.
- EU GMP Annex 1 revision:The 2022 update mandates enhanced environmental monitoring and rapid microbiological method acceptance criteria, compelling facilities across Germany, France, and Italy to upgrade detection infrastructure.
- Membrane filtration automation:Integrated platforms reducing handling steps accelerate batch release decisions for large-volume parenteral manufacturers facing antibiotic formulation inhibition challenges.
Market Restraints
- Specialized media supply concentration:Soybean-casein digest broth and fluid thioglycollate media production concentrates among limited US and European suppliers, exposing laboratories to raw material allocation risks during agricultural commodity volatility.
- Compendial method lock-in:USP Chapter 71 and Ph. Eur. 2.6.1 fourteen-day incubation requirements create technical friction against rapid microbial detection adoption despite scientific validation.
- Capital intensity of isolator technology:Restricted access barrier systems for sterility testing require seven-figure installation investments that freeze mid-size contract laboratories in conventional cleanroom configurations.
Strategic Opportunities
- India biologics manufacturing expansion:CDSCO's phased alignment with ICH Q5A and Q5D guidelines creates certification pathways for sterile product export facilities in Hyderabad and Bengaluru clusters.
- ATMP rapid release integration:Short shelf-life cell therapies with 24-48 hour patient administration windows create demand for ATP bioluminescence and flow cytometry methods that bypass conventional incubation.
- Laboratory information management convergence:Automated colony counting systems interfacing with LIMS platforms enable electronic batch records that satisfy FDA 21 CFR Part 11 and EMA Annex 11 data integrity requirements.
Industry Challenges
- Microbiology technician scarcity:Aseptic technique proficiency and compendial method expertise shortages constrain laboratory expansion plans in competitive talent markets including Boston, Basel, and Shanghai.
- Legacy LIMS integration complexity:Automated sterility platforms face data mapping friction when interfacing with decade-old quality management systems that lack API architecture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Sterility Testing Market |
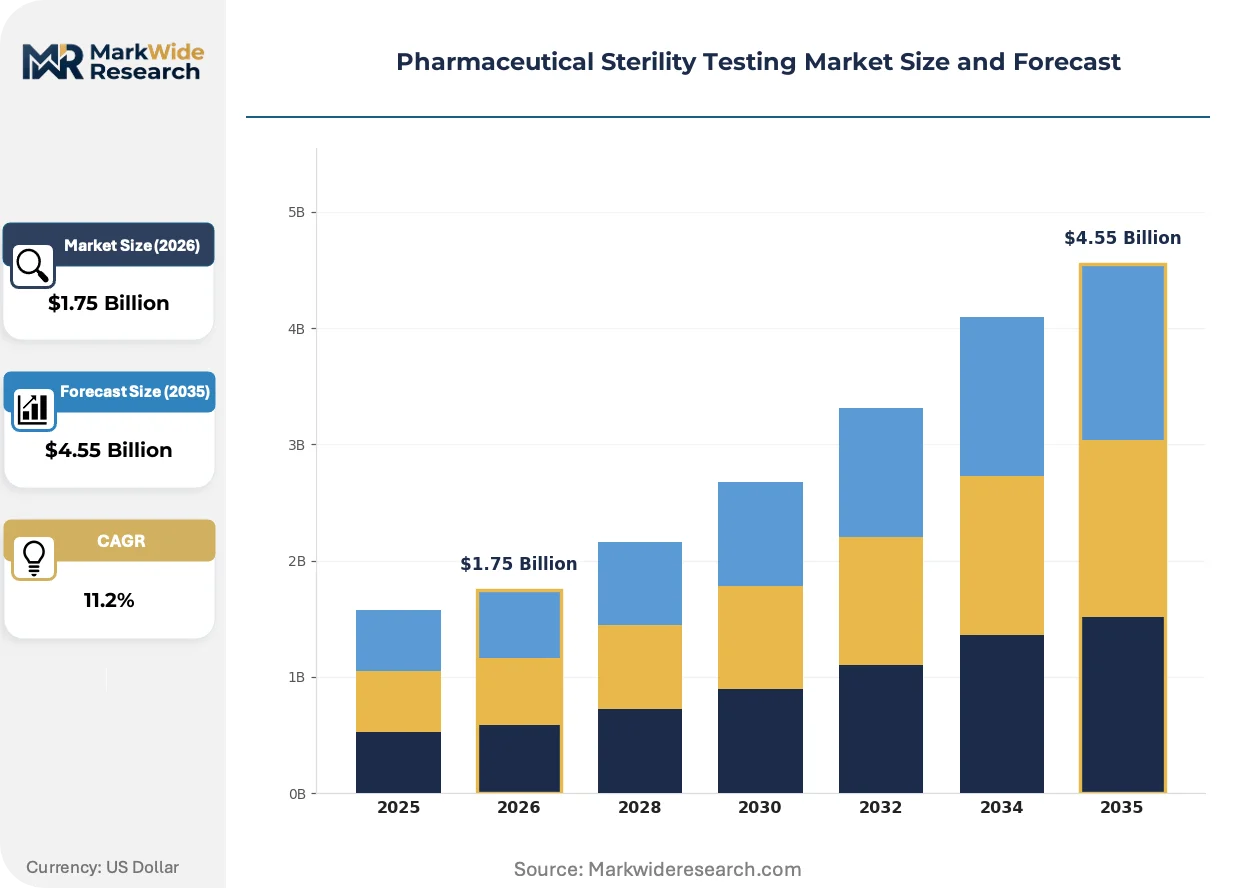
| Market Size in 2026 | $1.75 Billion |
| Market Size in 2035 | $4.55 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Direct Transfer, Membrane Filtration, Enrichment, Terminal Sterilization End User: Biopharmaceutical Companies, Contract Manufacturing Organizations, Research Institutions, Hospitals Method: Microbial Limit Test, Bioburden Testing, Container Closure Integrity, Sterility Assurance Level Product Type: Reagents, Consumables, Equipment, Software |
| Companies Covered | Eurofins Scientific, Sartorius AG, Charles River Laboratories, Labcorp, STERIS plc, Thermo Fisher Scientific, Merck KGaA, WuXi Apptec, SGS SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Sterility Testing Market Strategic Shifts & Innovations
Rapid microbiological methods are crossing the regulatory acceptance threshold while procurement patterns fragment between insourced validation laboratories and specialized contract testing partnerships, reshaping competitive positioning across the value chain.
Isolator-based sterility testing workstations are consolidating market share among parenteral drug manufacturers seeking to eliminate false positives from human-borne contamination. Large-volume injectable producers in the United States and Germany are replacing conventional cleanrooms with restricted access barrier systems at accelerated capital deployment cycles. This consolidation is compressing demand for traditional laminar flow hood installations and manual handling consumables.
EMA's 2024 guidance on alternative microbiological methods is clarifying validation pathways for ATP bioluminescence and solid-phase cytometry in European sterile product release. The industrial consequence is a bifurcation between early-adopting biologics manufacturers pursuing rapid batch release and generic injectable producers maintaining fourteen-day incubation protocols for cost containment. ATMP manufacturers with perishable cell therapies face the most acute pressure to demonstrate method equivalence under the new framework.
Mid-size biopharmaceutical companies are unbundling sterility testing from full-service quality contracts and establishing direct relationships with specialized microbiology laboratories. This channel disintermediation fragments volume concentration previously captured by integrated CROs and redirects procurement toward niche providers with specific ATMP or ophthalmic expertise. The shift is most visible in the Boston-Cambridge and Research Triangle Park clusters where cell therapy developers prioritize turnaround speed over geographic convenience.
Pharmaceutical Sterility Testing Market Segmentation
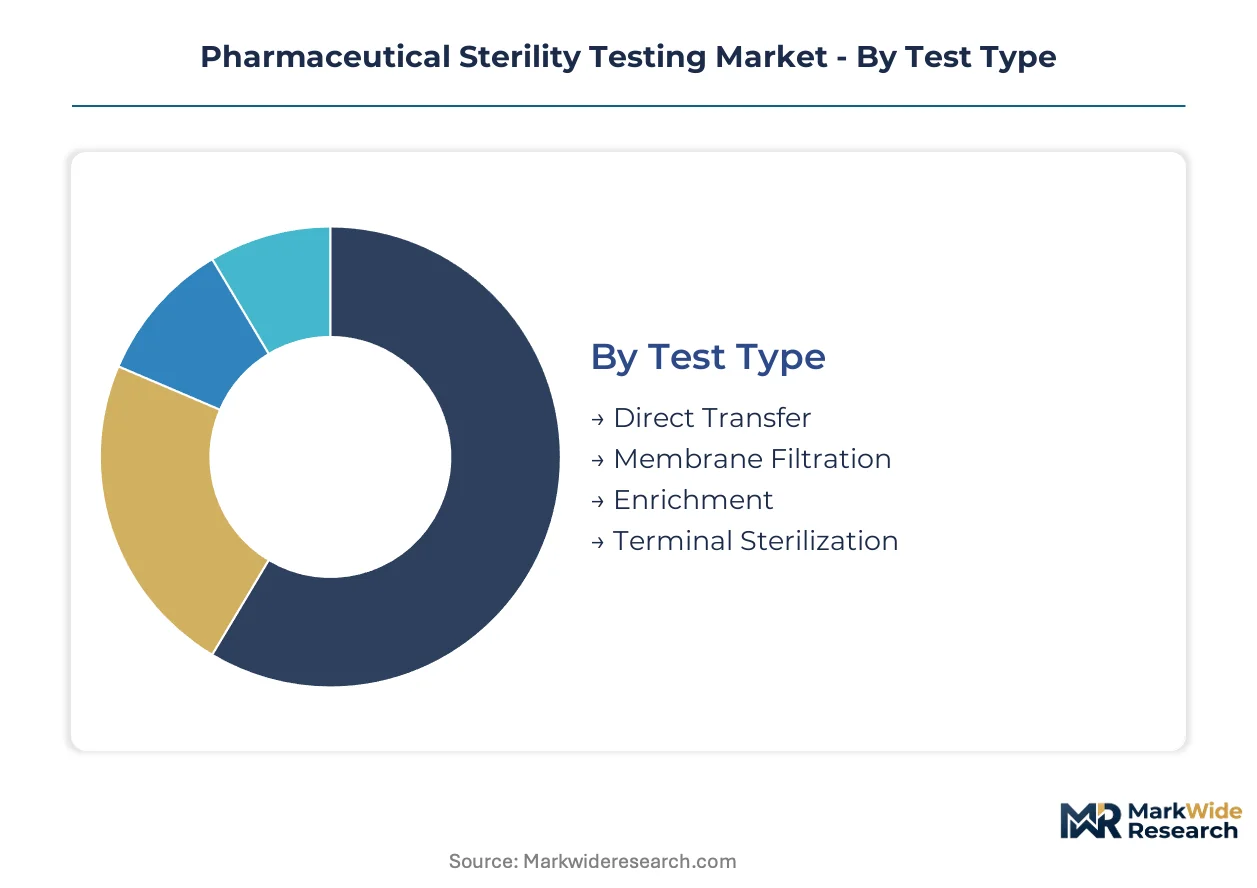
Segmentation in pharmaceutical sterility testing reveals distinct procurement behaviors across test methodologies and buyer types. Biopharmaceutical companies prioritize rapid release capabilities while contract manufacturers optimize for throughput economics. Understanding these divergent requirements illuminates where technology investments and pricing power concentrate across the value chain.
Test Type:
Laboratory directors select test methodologies based on sample volume, antimicrobial interference risk, and compendial acceptance requirements.
- Membrane Filtration:Passes liquid samples through 0.45-micron membranes that trap microorganisms for direct surface cultivation. Large-volume parenteral manufacturers in Germany and the United States deploy this method for antibiotic formulations where direct inoculation risks growth inhibition from residual antimicrobial activity.
- Direct Transfer:Introduces product directly into sterile culture media without filtration steps, suitable for small-volume injectables and ophthalmic preparations with limited antimicrobial content. ATMP developers in Boston-Cambridge clusters favor this approach for patient-specific cell therapy batches requiring minimal handling steps.
- Enrichment:Pre-incubates samples in non-selective broth to resuscitate stressed or injured microorganisms before standard testing protocols.
- Terminal Sterilization:Validates sterility assurance for products undergoing final sterilization processes such as gamma irradiation or ethylene oxide exposure.
Membrane filtration leads on scale; direct transfer leads on momentum.
End User:
Procurement authority and volume commitments vary sharply across organizational types with different regulatory exposure and capital access.
- Biopharmaceutical Companies:Maintain in-house quality laboratories for proprietary product pipelines, investing in isolator technology and rapid microbiological method validation. Cell and gene therapy developers in Research Triangle Park and Basel clusters drive demand for ATP bioluminescence platforms that compress release timelines.
- Contract Manufacturing Organizations:Operate high-throughput sterility testing facilities serving multiple sponsor clients under varied quality agreements. CDMOs in India and Ireland face acute pressure from EU GMP Annex 1 revisions requiring environmental monitoring infrastructure upgrades.
- Research Institutions:Conduct sterility testing for investigational products under pre-clinical and early-phase clinical protocols with limited batch volumes.
- Hospitals:Perform point-of-release testing for compounded sterile preparations and pharmacy-manufactured parenteral nutrition.
Biopharmaceutical companies concentrate premium spending; contract manufacturing organizations aggregate the largest test volumes.
Method:
Regulatory acceptance timelines and scientific validation requirements shape adoption curves across detection methodologies.
- Sterility Assurance Level:Quantifies probability of non-sterility, typically 10^-6 for terminally sterilized products, through validated sterilization cycle parameters and biological indicator challenge studies. Parenteral drug manufacturers facing FDA pre-approval inspections prioritize SAL documentation for product licensure submissions.
- Container Closure Integrity:Detects package defects that compromise sterility barrier function through vacuum decay, high-voltage leak detection, or dye ingress methods. Pre-filled syringe and vial manufacturers in Switzerland and Germany integrate CCI testing with sterility protocols to satisfy EMA guidance on product lifecycle management.
- Microbial Limit Test:Enumerates viable aerobic and specified microorganisms to demonstrate compliance with pharmacopeial acceptance criteria.
- Bioburden Testing:Quantifies microbial population in raw materials, in-process samples, and manufacturing environments before sterilization processing.
Sterility assurance level anchors regulatory compliance; container closure integrity is gaining share fastest.
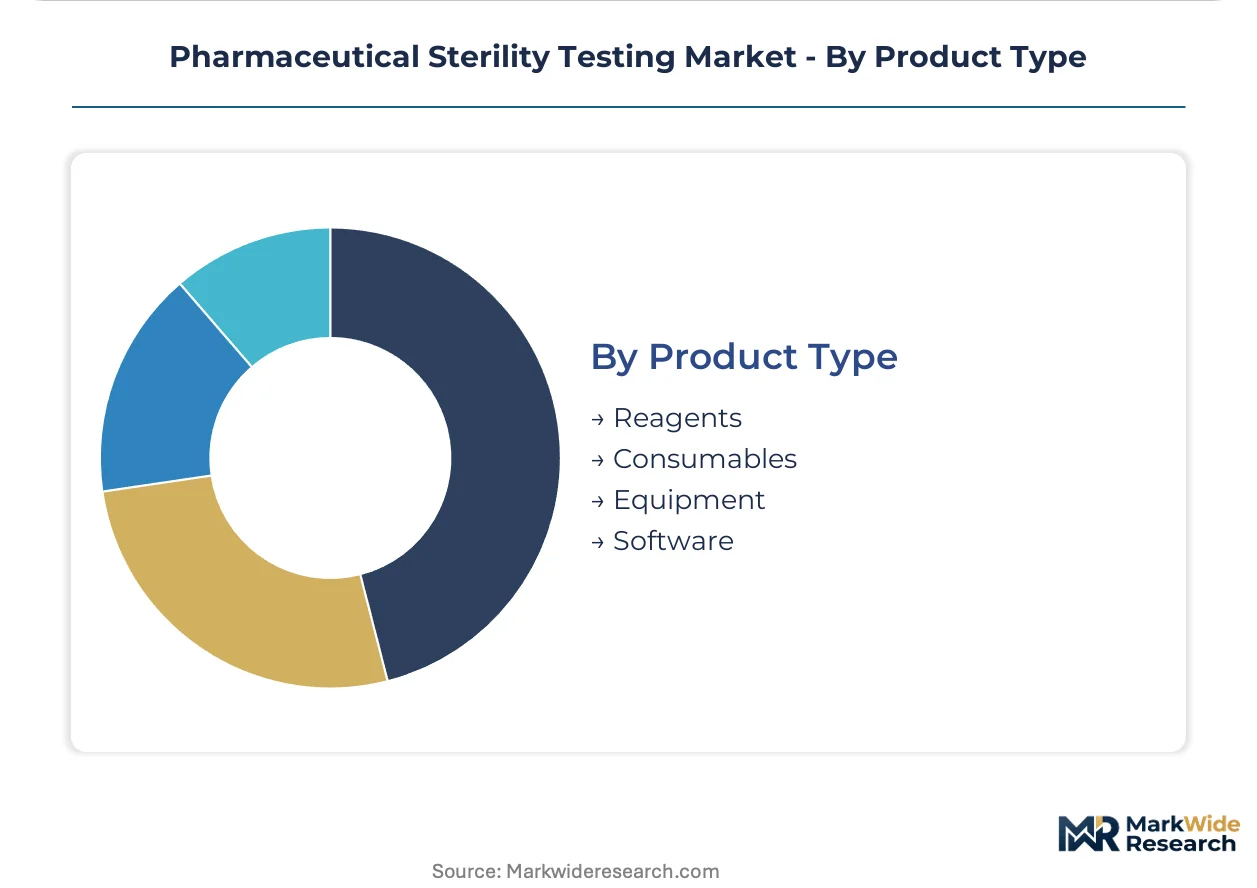
Product Type:
Margin structures and purchase frequency diverge between disposable consumables and capital-intensive instrumentation platforms.
- Reagents:Encompass culture media, diluents, and indicator solutions requiring lot-to-lot consistency and documented supply chain traceability. Soybean-casein digest broth and fluid thioglycollate media suppliers in the United States and Europe face agricultural commodity price volatility that propagates into laboratory cost structures.
- Consumables:Include membrane filters, sterile pipettes, and culture vessels consumed in proportion to test batch frequency. High-volume contract testing laboratories in China negotiate multi-year supply agreements to secure pricing stability against raw material allocation risks.
- Equipment:Comprises incubators, laminar flow workstations, and membrane filtration hardware with depreciation cycles spanning five to seven years.
- Software:Delivers laboratory information management, automated colony counting, and electronic batch record functionality subject to FDA 21 CFR Part 11 validation requirements.
Reagents lead on recurring revenue; software exhibits the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical sterility testing emerged from European pharmacopeial traditions in the late 19th century before industrializing in the United States during the post-war antibiotics boom. Contemporary demand concentrates in jurisdictions with stringent parenteral drug manufacturing requirements and active biologics investment pipelines.
United States
FDA pre-approval inspection requirements and USP Chapter 71 compliance drive sustained investment in automated membrane filtration platforms. The 21 CFR Part 11 data integrity framework compels laboratories to upgrade electronic batch record systems. Boston-Cambridge and Research Triangle Park clusters host the densest concentration of cell therapy developers requiring rapid sterility release capabilities.
Germany
Large-volume parenteral manufacturers in Baden-Württemberg and Bavaria anchor European demand for isolator-based sterility testing workstations. EU GMP Annex 1 revisions mandate enhanced environmental monitoring infrastructure across sterile manufacturing facilities. The Rhine-Main and Rhine-Neckar metropolitan regions concentrate CDMO capacity serving global pharmaceutical sponsors.
China
NMPA's phased alignment with ICH Q5A and Q5D guidelines accelerates certification of sterile biologics export facilities. Yangtze River Delta pharmaceutical clusters in Shanghai and Suzhou deploy membrane filtration automation to meet international sponsor quality agreements. Domestic vaccine manufacturers drive demand for sterility assurance level validation capacity.
India
CDSCO's adoption of ICH sterility guidelines creates regulatory pathways for Hyderabad and Bengaluru facilities supplying regulated markets. Parenteral generic manufacturers in Gujarat and Maharashtra invest in isolator technology to satisfy FDA and EMA inspection standards. Contract testing laboratories aggregate volume from multinational sponsors seeking cost-competitive sterile release services.
Switzerland
Swissmedic's stringent biologics licensing requirements sustain premium pricing for specialized sterility testing services. Basel's pharmaceutical corridor hosts in-house quality laboratories for global biopharmaceutical headquarters. Pre-filled syringe and vial manufacturers integrate container closure integrity testing with sterility protocols under EMA product lifecycle management guidance.
Pharmaceutical Sterility Testing Market Key Industry Players
Premium-margin players sit above commodity-margin players across technology sophistication and regulatory certification depth. The market structures around three tiers: integrated life science conglomerates with consumables-recurring revenue models, specialized contract testing organizations with biologics expertise, and regional equipment fabricators serving cost-sensitive generic manufacturers. Consolidation pressures intensify as mid-size biopharmaceutical companies disintermediate full-service contracts in favor of direct relationships with niche microbiology laboratories. Dominant competitive moves include isolator technology licensing partnerships and rapid microbiological method validation service expansion.
Among the integrated conglomerate tier, Thermo Fisher Scientific and Merck KGaA represent archetypal positions anchored by consumables portfolios generating recurring revenue streams. Sartorius AG occupies a distinct position exemplifying specialized membrane filtration platform integration. Within contract testing, Charles River Laboratories and Eurofins Scientific exemplify the biologics-specialized archetype, while WuXi Apptec represents the Asia-Pacific scale-driven model. These named entities serve as structural anchors for understanding competitive positioning without implying specific strategic actions or market shares.
| Leading Market Players |
|---|
| Eurofins Scientific |
| Sartorius AG |
| Charles River Laboratories |
| Labcorp |
| STERIS plc |
| Thermo Fisher Scientific |
| Merck KGaA |
| WuXi Apptec |
| SGS SA |
| Others |
Cost & Logistics Intelligence
Soybean-casein digest broth and fluid thioglycollate media costs cascade from agricultural commodity markets through laboratory procurement tiers, with US and European suppliers commanding premium pricing against Asian alternatives while CDMOs in India and China negotiate multi-year supply agreements to buffer volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates isolator-equipped laboratories serving FDA-inspected biologics manufacturers from conventional cleanroom operators and commodity contract testing facilities. Price differentiation hinges on certification grade (FDA 21 CFR Part 11, EU GMP Annex 1) and volume scale, with large-batch CDMOs extracting steeper discounts than patient-specific ATMP developers. Cost compression in the economy tier is intensifying because mid-size biopharmaceutical companies unbundle testing from full-service contracts. Generic injectable manufacturers in India exhibit highest price sensitivity; Swiss biologics headquarters tolerate premium pricing for rapid release capabilities.
Supply Chain Analysis
Freight costs for temperature-controlled culture media shipments from US and European production hubs to Asian manufacturing clusters have reshored procurement calculations for time-sensitive reagents. Supply concentrates in the United States, Germany, and China for membrane filtration hardware; India and Ireland for high-throughput contract testing capacity. Raw material dependencies include soybean meal, casein derivatives, and pharmaceutical-grade filtration membranes. Single-source vulnerability concentrates among limited fluid thioglycollate media suppliers. Distribution runs through direct manufacturer relationships with biopharmaceutical quality labs, bypassing traditional distributor networks for consumables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pharmaceutical sterility testing market compounds steadily as regulatory tightening across FDA, EMA, and NMPA jurisdictions mandates recurring compliance investments that laboratories cannot defer.
For Market Incumbents: Anticipate rapid microbiological method validation services displacing conventional fourteen-day incubation protocols by embedding ATP bioluminescence expertise into existing isolator platforms. Defend recurring revenue streams through consumables bundling that locks CDMOs into multi-year membrane filtration supply agreements. Capacity addition in Hyderabad and Bengaluru clusters captures India biologics manufacturing expansion before local competitors achieve EMA certification equivalence. For New Entrants and Emerging Players: Automated colony counting systems interfacing with legacy LIMS platforms offer a technology-first wedge into mid-size biopharmaceutical companies struggling with data integrity compliance. Target Boston-Cambridge and Research Triangle Park ATMP developers requiring 24-48 hour sterility release for perishable cell therapies. Go-to-market angle: rapid method validation consulting paired with equipment leasing to bypass capital intensity barriers. For Investors and Strategic Acquirers: Roll-up economics work for specialized microbiology laboratories because EU GMP Annex 1 revisions force fragmented regional players to seek scale for compliance infrastructure investment. Long-term viability rests on consolidation of niche ATMP and ophthalmic testing expertise into platform networks. Acquisition target archetype: isolator-technology-equipped contract laboratories with existing FDA and EMA inspection histories. Signal to watch: CDSCO certification acceleration in Hyderabad and Bengaluru clusters indicating India export facility readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Rapid Microbiological Method Validation | ATP bioluminescence platforms bypass fourteen-day incubation for ATMP release timelines. |
| Isolator Technology Licensing | Restricted access barrier systems eliminate false positives from human-borne contamination. |
| LIMS Integration Partnership | Automated colony counting satisfies FDA 21 CFR Part 11 data integrity requirements. |
| Consumables Supply Agreement | Multi-year membrane filtration contracts lock CDMOs into recurring revenue streams. |
| India Certification Pathway | CDSCO alignment with ICH guidelines opens sterile product export facility opportunities. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with microbiology laboratory directors, regulatory affairs leads at biopharmaceutical companies, CDMO quality officers, and sterility testing equipment procurement managers with secondary validation against FDA 483 observations, EMA inspection reports, USP and Ph. Eur. compendial updates, and sterile manufacturing facility certification databases. Bottom-up test volume estimates from individual laboratories triangulated against top-down biologics production capacity data.
Comparable-period anchoring matched historical sterility test frequency patterns against projected biologics manufacturing expansion across the analysis window. Segmentation dimensions modeled include test methodology, end-user organization type, detection method, and regional regulatory cluster. CAGRs derived from installed base growth rates for membrane filtration platforms and rapid method adoption curves, incorporating cell and gene therapy facility build-out pipelines and EU GMP Annex 1 compliance investment cycles as industry-specific forecast inputs.
The model holds under steady regulatory tightening trajectories; deviation in rapid microbiological method acceptance timelines or agricultural commodity price shocks would shift consumables margin assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
INR Test Meter Market
Testing Services
Pyrogen Testing Market
Testing Services
Thyroid Test Market
Testing Services
Pregnancy Point of Care Testing Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
ATP Assays Market
Testing Services
Fecal Occult Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Chromatin Immunoprecipitation Testing Market
Testing Services
Global C-Reactive Protein Testing Market
Testing Services
Nicotine Testing Market
Testing Services
Rapid Sterility Testing Market