
 Thyroid Test Market | 2026-2036
Thyroid Test Market Size, Share, and Industry Trends Forecast 2026-2036
Thyroid Test Market Outlook
Hospital reference laboratory outsourcing is reshaping how thyroid testing reaches patients, with centralized hubs replacing fragmented in-house chemistry operations. Quest Diagnostics leverages its national logistics footprint to sustain next-day TSH turnaround across rural catchments. Laboratory Corporation of America Holdings anchors its competitive position through managed care contracts that lock in preferred provider status. Abbott Laboratories differentiates via point-of-care immunoassay systems deployed in urgent care settings.
Thyroid tests measure circulating levels of thyroid-stimulating hormone, free thyroxine, free triiodothyronine, and thyroid antibodies using chemiluminescent or electrochemiluminescent detection methods, primarily to diagnose hypothyroidism, hyperthyroidism, and autoimmune thyroid disorders. TSH Test dominates routine screening panels ordered during annual physicals and prenatal visits, generating the highest test volume but facing reimbursement compression. Molecular Diagnostics represents the fastest-expanding technology segment as next-generation sequencing panels identify somatic mutations in indeterminate thyroid nodules, commanding premium pricing from academic medical centers. Home Care is emerging as a structural growth channel as direct-to-consumer platforms ship dried blood spot kits for monitoring levothyroxine therapy.
FDA oversight of laboratory-developed tests and CLIA proficiency requirements shape product development timelines and commercialization pathways for novel thyroid biomarkers. The EU In Vitro Diagnostic Regulation imposes stricter clinical evidence standards on antibody test manufacturers seeking CE marking, elevating barriers for smaller reagent suppliers. Stakeholders must monitor how payer coverage policies for molecular thyroid nodule classifiers evolve, as these determinations will dictate whether genomic testing displaces diagnostic fine-needle aspiration in community endocrinology practices.
Market Dynamics
Hospital laboratory consolidation is compressing vendor access points, forcing thyroid test manufacturers to secure sole-source agreements with integrated delivery networks or risk volume exclusion from standardized formulary panels.
Growth Catalysts
- CLIA laboratory expansion:Diagnostic laboratories in the United States are adding autoimmune thyroiditis panels to capture referral flows from endocrinology practices seeking comprehensive antibody profiling.
- Point-of-care immunoassay miniaturization:Urgent care networks are deploying cartridge-based TSH systems that eliminate send-out delays for same-day clinical decisions.
- FDA LDT oversight redirection:The agency's evolving framework is pushing developers toward IVD-compliant platforms, accelerating platform standardization and reducing validation duplication.
Market Restraints
- Reagent supply concentration:Chemiluminescent detection chemistry depends on a narrow supplier base for acridinium ester conjugates, creating vulnerability to single-source disruptions.
- Reimbursement compression:CMS fee schedules for routine TSH testing have flattened, squeezing margin on high-volume screening panels that dominate laboratory economics.
- EU IVDR clinical evidence burden:The In Vitro Diagnostic Regulation imposes expanded performance study requirements on antibody test manufacturers seeking CE marking renewal.
Strategic Opportunities
- Direct-to-consumer dried blood spot platforms:Home Care channels for levothyroxine monitoring are bypassing traditional laboratory networks, capturing patient-initiated testing demand.
- Next-generation sequencing integration:Molecular Diagnostics for indeterminate thyroid nodules is hybridizing with cytopathology workflows, creating premium-priced classifier opportunities in academic medical centers.
- Managed care preferred provider lock-ins:Exclusive reference laboratory contracts with United States integrated delivery networks are securing multi-year volume commitments against competitive displacement.
Industry Challenges
- Cross-platform harmonization complexity:Laboratories running multiple immunoassay architectures face calibration drift between chemiluminescent and electrochemiluminescent systems, complicating longitudinal patient monitoring.
- Proficiency testing program participation costs:CLIA-mandated external quality assessment for esoteric thyroid antibodies imposes recurring operational overhead on smaller reference laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thyroid Test Market |
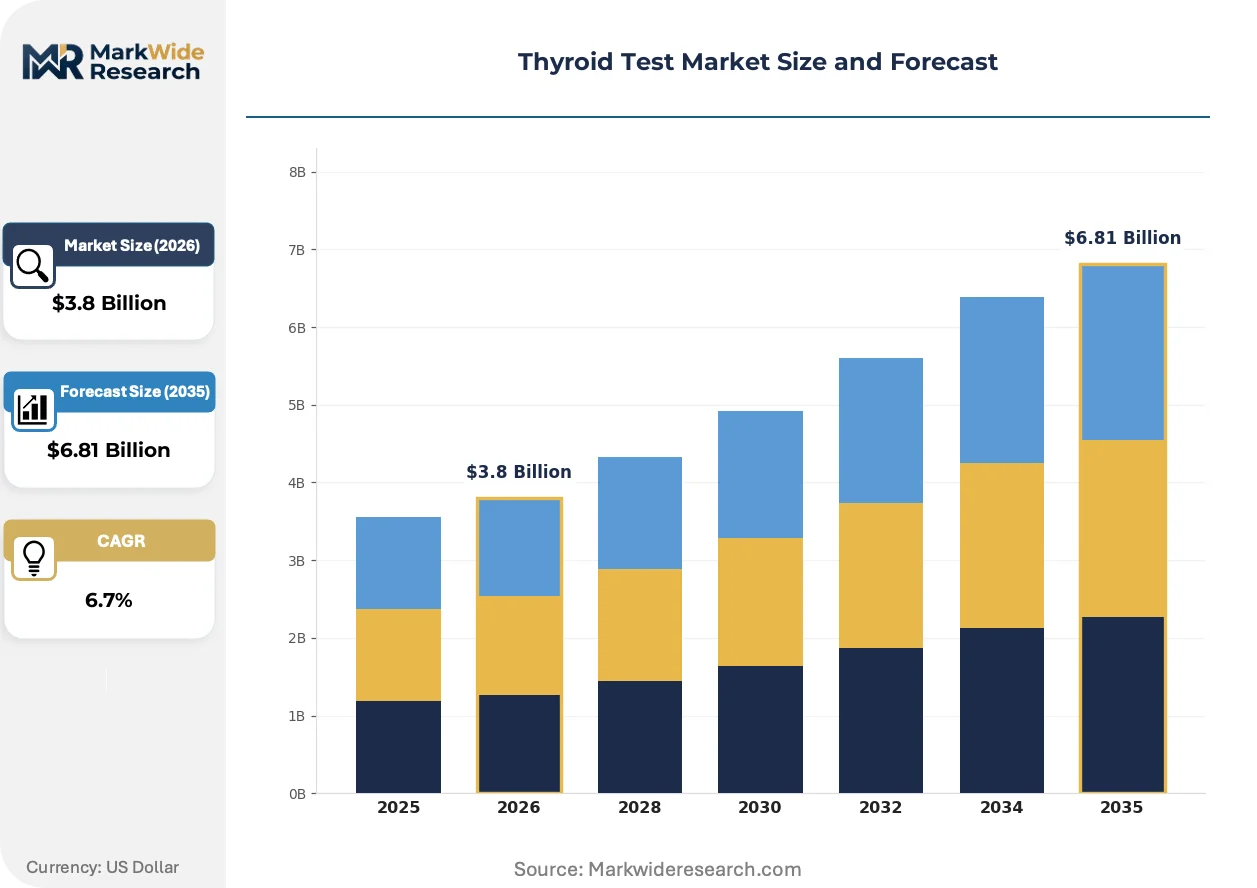
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: TSH Test, Free T4 Test, Free T3 Test, Thyroid Antibody Test End User: Hospitals, Diagnostic Laboratories, Home Care, Clinics Technology: Immunoassay, Molecular Diagnostics, Chromatography, Biosensors Product Type: Kits, Reagents, Consumables, Equipment |
| Companies Covered | Quest Diagnostics, Laboratory Corporation of America Holdings, Abbott Laboratories, Siemens Healthineers, Roche Diagnostics, Thermo Fisher Scientific Inc., DiaSorin S.p.A., Danaher Corporation, Bio-Rad Laboratories, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thyroid Test Market Strategic Shifts
Thyroid diagnostics is bifurcating between commoditized screening panels and high-complexity molecular classifiers, with automation and connectivity investments determining which laboratories capture profitable esoteric volume.
Multiplexed antibody detection platforms are hybridizing chemiluminescent signal generation with microfluidic sample processing, enabling simultaneous TPOAb, TgAb, and TRAb quantification from single serum aliquots. Regional reference laboratories in the United States are adopting these systems to reduce batch turnaround and consolidate send-out referrals. The technology is hybridizing previously fragmented autoimmune workups into unified panels that displace sequential single-analyte ordering.
The FDA's LDT oversight framework is recalibrating development timelines for novel thyroid biomarkers, requiring IVD pathway compliance for tests previously validated under laboratory-developed protocols. Manufacturers are restructuring clinical trial designs to accommodate premarket submission requirements. High-complexity molecular thyroid nodule classifiers face the steepest compliance burden, with academic medical center developers absorbing extended validation costs.
Integrated delivery networks in the United States are consolidating reference laboratory contracts into sole-source arrangements that standardize testing menus across affiliated hospitals. Community endocrinology practices are losing direct laboratory relationships as procurement authority centralizes to system-level supply chain functions. This concentration is most visible in the Southeast and Midwest, where hospital system mergers have compressed vendor access points to three or fewer approved reference laboratories per network.
Thyroid Test Market Segmentation
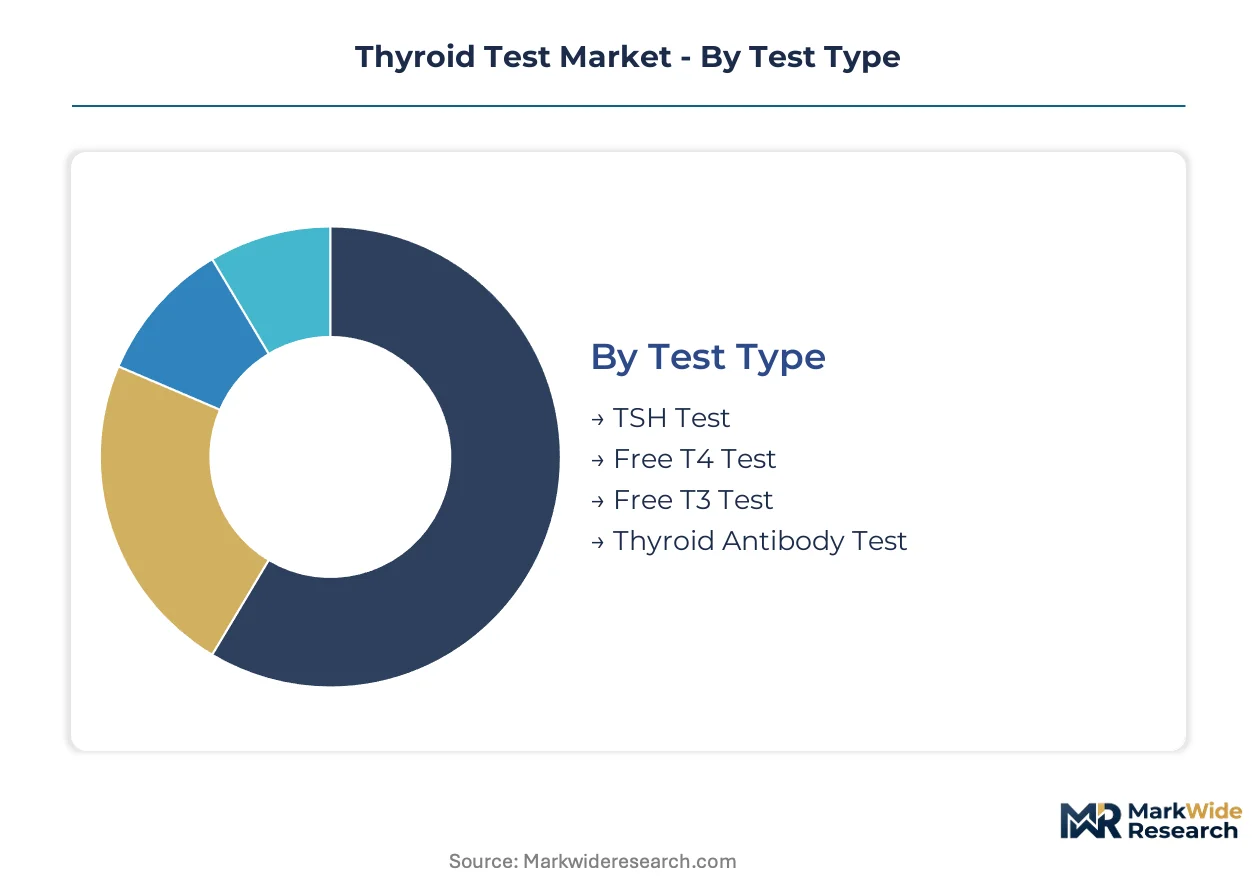
Thyroid test segmentation reveals distinct procurement patterns across clinical settings, with technology choices and end-user concentration determining margin structures and competitive positioning for manufacturers.
Test Type:
Clinical utility spans routine screening through specialized autoimmune profiling, with reimbursement tiers and ordering frequency creating divergent commercial profiles.
- TSH Test:Chemiluminescent immunoassay measuring thyroid-stimulating hormone in serum or plasma. Annual physicals and prenatal visits in United States primary care networks drive the highest test volume, though CMS fee schedule compression squeezes unit economics.
- Thyroid Antibody Test:Multiplexed detection of TPOAb, TgAb, and TRAb markers using microfluidic platforms. Academic medical centers and specialty endocrinology practices in Germany and France command premium pricing for comprehensive autoimmune profiling panels.
- Free T4 Test:Direct equilibrium dialysis or analog immunoassay for unbound thyroxine quantification.
- Free T3 Test:Specialized immunoassay for unbound triiodothyronine measurement in hyperthyroidism confirmation.
Established volume favors TSH Test; emerging adoption favors Thyroid Antibody Test.
End User:
Channel concentration is accelerating as procurement authority migrates toward centralized purchasing functions.
- Diagnostic Laboratories:High-throughput chemiluminescent analyzers processing thousands of samples daily. Quest Diagnostics and Laboratory Corporation of America Holdings in the United States lock in multi-year managed care contracts that freeze out smaller competitors.
- Home Care:Direct-to-consumer dried blood spot platforms shipping levothyroxine monitoring kits. United States telehealth-integrated startups bypass traditional laboratory networks entirely.
- Hospitals:Inpatient and emergency department testing using integrated chemistry-immunoassay systems.
- Clinics:Point-of-care cartridge-based TSH systems in urgent care settings for same-day clinical decisions.
Procurement consolidation favors Diagnostic Laboratories; patient-initiated demand expansion favors Home Care.
Technology:
Detection methodology determines regulatory pathway complexity and capital intensity requirements.
- Immunoassay:Chemiluminescent and electrochemiluminescent signal generation dominates routine screening. Abbott Laboratories deploys point-of-care cartridge systems in United States urgent care networks.
- Molecular Diagnostics:Next-generation sequencing panels identifying somatic mutations in indeterminate thyroid nodules. Academic medical centers in the United States absorb premium pricing for genomic classifiers that displace diagnostic fine-needle aspiration.
- Chromatography:Liquid chromatography-tandem mass spectrometry for reference method calibration.
- Biosensors:Electrochemical and optical transducer platforms under development for miniaturized testing.
Platform standardization favors Immunoassay; steepest expansion trajectory belongs to Molecular Diagnostics.
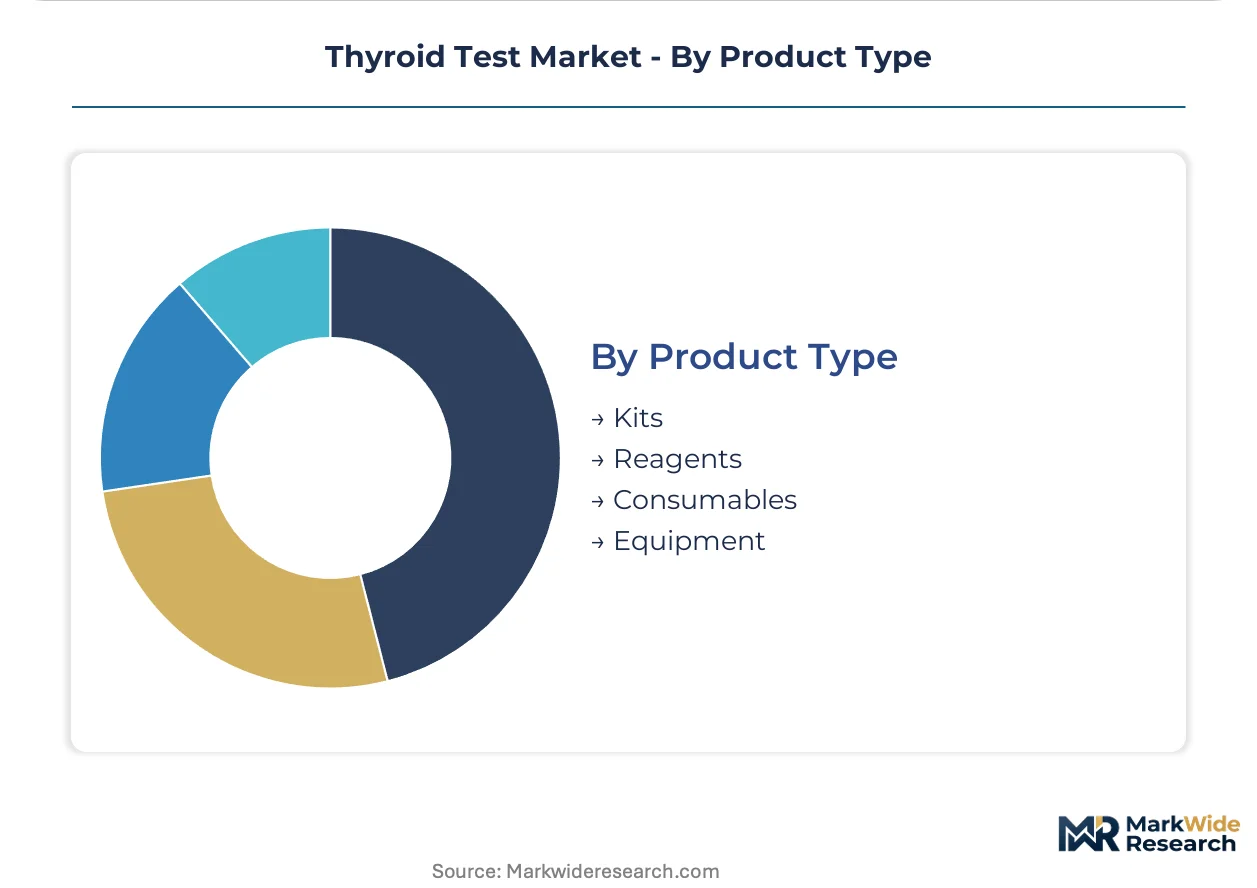
Product Type:
Supply chain configuration separates recurring consumable revenue from capital equipment cycles.
- Reagents:Acridinium ester conjugates and antibody-coated magnetic microparticles for signal generation. United States reagent supply concentration creates vulnerability to single-source disruptions.
- Kits:Pre-packaged assay panels combining calibrators, controls, and consumables. European Union IVDR compliance costs burden smaller manufacturers seeking CE marking renewal.
- Consumables:Pipette tips, reaction vessels, and sample containers.
- Equipment:Automated immunoassay analyzers and molecular diagnostic platforms.
Recurring revenue concentration favors Reagents; regulatory compliance burden heaviest for Kits.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's evolving LDT oversight framework redirects test development strategies toward IVD-compliant platforms across multiple jurisdictions. Germany's EMA-aligned regulatory environment and Japan's PMDA pathways similarly reshape commercialization timelines. Procurement consolidation in hospital networks concentrates demand in specific metropolitan clusters.
United States
Integrated delivery networks in the Southeast and Midwest consolidate reference laboratory contracts into sole-source arrangements. CMS fee schedule compression for routine TSH testing squeezes margins on high-volume screening panels. The Boston-Cambridge corridor anchors molecular diagnostics development for indeterminate thyroid nodule classifiers.
Germany
Academic medical centers in Munich and Heidelberg command premium pricing for comprehensive autoimmune profiling panels. The EU IVDR imposes expanded performance study requirements on antibody test manufacturers seeking CE marking renewal. The Rhine-Main cluster concentrates reagent manufacturing for chemiluminescent detection chemistry.
Japan
PMDA regulatory pathways for novel thyroid biomarkers require extended validation timelines compared to laboratory-developed test frameworks. METI industrial policy supports point-of-care immunoassay miniaturization for urgent care deployment. The Kanto region around Tokyo hosts concentrated diagnostic laboratory networks processing thousands of samples daily.
China
NMPA oversight of in vitro diagnostic reagents intensifies clinical evidence requirements for domestic manufacturers. The Yangtze River Delta around Shanghai anchors high-throughput immunoassay analyzer production. Hospital system consolidation in tier-one cities compresses vendor access points to standardized formulary panels.
India
CDSCO regulatory harmonization with IVD standards accelerates platform standardization for imported diagnostic systems. The Maharashtra-Gujarat corridor concentrates private diagnostic laboratory chains expanding test menus for autoimmune thyroiditis. Mumbai and Ahmedabad hubs process referral flows from fragmented endocrinology practices seeking comprehensive antibody profiling.
Thyroid Test Market Competitive Environment
On the supply side, the industry is consolidating around three structural tiers: multinational reference laboratory networks, diversified diagnostics conglomerates, and specialized immunoassay manufacturers. National logistics footprints and managed care contract lock-ins define the first archetype. Point-of-care miniaturization capabilities and reagent supply concentration characterize the second. The third archetype focuses on molecular classifier development for academic medical centers. Competitive moves concentrate on sole-source agreements with integrated delivery networks and IVD pathway compliance investments.
Among United States-based reference laboratory networks, Quest Diagnostics and Laboratory Corporation of America Holdings exemplify the scale-driven archetype through multi-year managed care contracts. Abbott Laboratories represents the diversified point-of-care segment with urgent care cartridge deployment. These three occupy positions across distinct procurement channels rather than direct product competition.
| Leading Market Players |
|---|
| Quest Diagnostics |
| Laboratory Corporation of America Holdings |
| Abbott Laboratories |
| Siemens Healthineers |
| Roche Diagnostics |
| Thermo Fisher Scientific Inc. |
| DiaSorin S.p.A. |
| Danaher Corporation |
| Bio-Rad Laboratories, Inc. |
| Others |
Value Chain & Pricing Dynamics
Single-source dependency for acridinium ester conjugates determines both the compression of routine TSH test margins and the geographic clustering of chemiluminescent reagent manufacturing. FDA's evolving LDT oversight framework simultaneously elevates compliance costs for premium molecular classifiers while flattening reimbursement for high-volume screening panels.
Pricing Analysis
Certification level creates the primary spread between IVD-compliant platforms and laboratory-developed test alternatives, with FDA-grade submissions commanding substantial premiums over CLIA-validated equivalents. Three-tier pricing structure across premium molecular diagnostics, standard immunoassay panels, and economy point-of-care cartridges reflects this regulatory stratification. Pricing pressure stems from CMS fee schedule compression on routine TSH screening, which squeezes margin on the highest-volume test category. Diagnostic laboratories exhibit the greatest price sensitivity due to managed care contract lock-ins, while academic medical centers absorb premium pricing for genomic classifiers with less procurement resistance.
Supply Chain Analysis
Export-control restrictions on electrochemiluminescent detection technologies limit flow of advanced immunoassay architectures to certain end markets, reshaping vendor access patterns. Manufacturing concentration rests on the United States, Germany, and Japan for chemiluminescent analyzer production, with China anchoring magnetic microparticle substrate supply. Acridinium ester conjugates, antibody-coated beads, and calibration sera constitute the critical input trio. Single-source vulnerability for signal-generation chemistry creates systemic exposure to supplier disruptions. Distribution runs through integrated delivery network procurement hubs rather than direct hospital relationships, centralizing vendor negotiation leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where IVD-compliant assay architectures are displacing laboratory-developed protocols, with interoperability across health system EHRs becoming the decisive ecosystem gate.
For Market Incumbents: Harden defensive positions by securing sole-source agreements with Southeast and Midwest integrated delivery networks before contract consolidation completes. Deepen backward integration into acridinium ester conjugate production to neutralize single-source supply risk. Prioritize CLIA-waived point-of-care cartridge development to capture urgent care volume migration. For New Entrants and Emerging Players: Direct-to-consumer dried blood spot platforms for levothyroxine monitoring in United States telehealth-integrated channels represent the most penetrable entry point with minimal incumbent saturation. Molecular classifier development for indeterminate thyroid nodules at European academic medical centers offers secondary white-space with premium pricing tolerance. Pursue regulatory sandbox partnerships to accelerate IVD pathway navigation. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated reagent manufacturers with captive supply of detection chemistry. Long-term viability hinges on platform standardization investments that lock in health system switching costs. Monitor FDA premarket submission timelines for molecular thyroid nodule classifiers as the signal indicating whether genomic testing displaces diagnostic fine-needle aspiration.| Strategic Initiative | Industry Significance |
|---|---|
| IVD Pathway Compliance Investment | FDA premarket submissions for molecular classifiers secure premium reimbursement from academic medical centers. |
| Sole-Source IDN Contracting | Exclusive agreements with United States integrated delivery networks freeze out competitive reference laboratories. |
| Point-of-Care Miniaturization | Cartridge-based TSH systems capture urgent care volume seeking same-day clinical decision support. |
| Direct-to-Consumer Platform Launch | Telehealth-integrated dried blood spot kits bypass traditional laboratory networks for patient-initiated testing. |
| Reagent Supply Backward Integration | In-house acridinium ester production neutralizes single-source vulnerability in chemiluminescent detection chemistry. |
Study Parameters
Cross-validation between primary interviews with diagnostic laboratory directors, endocrinology practice administrators, hospital procurement officers, and regulatory affairs specialists anchors the qualitative findings. Secondary validation draws from FDA 510(k) filings, CMS fee schedule publications, EU IVDR guidance documents, and hospital system merger announcements. Bottom-up test volume modeling triangulates against top-down market sizing across immunoassay, molecular diagnostics, and point-of-care technology segments.
Calibration against historical reimbursement trajectories and regulatory approval timelines shapes the analytical framework. Segmentation dimensions span test type, technology platform, end-user channel, and geographic regulatory cluster. CAGRs derive from test volume elasticity to screening guideline updates and molecular adoption curves in academic versus community settings. Payer coverage policy evolution for genomic classifiers and CLIA laboratory expansion rates constitute key forecast inputs.
Stress conditions across CMS reimbursement compression severity, EU IVDR implementation pace, and integrated delivery network consolidation velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding molecular diagnostic penetration and point-of-care miniaturization adoption. Material shifts in FDA LDT oversight finalization or major health system bankruptcy reorganizations would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Friability Tester Market
Testing Services
Large Molecule Bioanalytical Testing Services Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
In-Vitro Diagnostic Services Market
Testing Services
Home Menopause Testing Market
Testing Services
Toxicology Drug Screening Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Drug Testing Market
Testing Services
Radiographic Testing Market
Testing Services
Infusion Toxicology Services Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Global Cannabis Testing Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Testing and Analysis Services Market