
 Global ENT Workstations Market | 2026-2036
Global ENT Workstations Market Size, Share, and Industry Trends Forecast 2026-2036
Global ENT Workstations Market Foresight
The divergence between premium and commodity tiers in ENT workstations is hardening around imaging fidelity, software integration depth, and after-sales service bundling. ATMOS MedizinTechnik GmbH & Co. KG leverages its German manufacturing base to sustain high-margin positions in modular microscope-endoscope combinations. Euroclinic Medi-Care Solutions anchors Southern European demand through compact, price-accessible configurations suited for smaller ENT clinics. Optomic competes aggressively on HD video pipeline performance across Latin American and Middle Eastern distributor networks.
An ENT workstation constitutes an integrated diagnostic and surgical platform combining optical visualization, digital image capture, patient data management, and procedure-specific instrumentation within a single ergonomic console, typically supporting 1080p to 4K video resolution and DICOM-compliant archiving. Its primary commercial purpose centers on enabling otolaryngologists to perform examinations, minor interventions, and preoperative assessments without relocating equipment or patients across facility zones. Imaging systems command the deepest margin pools due to recurring software license and calibration service revenue, while wireless connectivity represents the fastest-expanding technology dimension as clinics prioritize cable-reduced environments and tablet-based control interfaces. Endoscopes remain the most mature product category, with price competition intensifying among Asian manufacturers.
The FDA's Quality System Regulation and the EU Medical Device Regulation jointly shape product development timelines, clinical validation requirements, and market access costs for workstation manufacturers seeking dual-territory approval. Japan's PMDA imposes additional electromagnetic compatibility and biological safety testing layers that filter out smaller competitors lacking dedicated regulatory affairs capacity. Stakeholders must monitor how impending harmonization between ISO 13485 revisions and EU notified body expectations reshapes supplier qualification criteria and aftermarket service obligations.
Market Dynamics
The EU Medical Device Regulation is compressing product development timelines while simultaneously elevating aftermarket service obligations, forcing workstation manufacturers to restructure quality systems and clinical validation protocols around notified body expectations.
Growth Catalysts
- Ambulatory surgical center expansion:Freestanding surgical facilities in the United States are consolidating diagnostic and minor interventional capabilities into single-suite configurations, driving procurement of integrated ENT workstation platforms.
- Wireless connectivity protocols:Bluetooth 5.3 and Wi-Fi 6E implementations are enabling cable-reduced examination environments, with tablet-based control interfaces gaining preference among German and Japanese clinic operators seeking ergonomic flexibility.
- MDR harmonization momentum:The EU Medical Device Regulation's tightened quality system requirements are filtering out marginal competitors, creating volume concentration opportunities for manufacturers with dedicated regulatory affairs capacity across Germany, France, and Italy.
Market Restraints
- Optical component supply concentration:High-resolution CMOS sensors and precision lens assemblies depend on concentrated Taiwanese and South Korean foundry capacity, exposing manufacturers to geopolitical disruption risk.
- Software license cost escalation:DICOM-compliant archiving modules and AI-assisted diagnostic algorithms carry recurring per-seat fees that inflate total cost of ownership for mid-sized ENT clinics in Southern Europe.
- Endoscope commoditization pressure:Asian manufacturers are compressing margins on rigid and flexible endoscope categories through scaled production of 1080p-compatible insertion tubes.
Strategic Opportunities
- India's diagnostic infrastructure buildout:The country's PLI scheme for medical devices is incentivizing local assembly of ENT workstations, creating first-mover advantages for manufacturers establishing technical training partnerships with Mumbai and Delhi clinic networks.
- 4K-8K video pipeline convergence:Integration of broadcast-grade image processing with surgical documentation workflows is opening premium pricing tiers for configurations supporting uncompressed video archiving.
- Remote calibration services:Cloud-connected diagnostic tools are enabling manufacturer-direct technical support, bypassing traditional distributor service margins in Middle Eastern and Latin American markets.
Industry Challenges
- Electromagnetic compatibility certification:Japan's PMDA imposes additional EMC testing layers that extend product registration timelines by 8-14 months for manufacturers lacking Tokyo-based regulatory representation.
- Legacy system interoperability:Clinic information systems using non-standard HL7 implementations require custom middleware development, complicating workstation deployment in established European hospital networks.
- Biomedical engineering talent scarcity:Specialized expertise in optical-mechanical integration and embedded software development concentrates in southern Germany and northern Italy, constraining R&D expansion for competitors elsewhere.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global ENT Workstations Market |
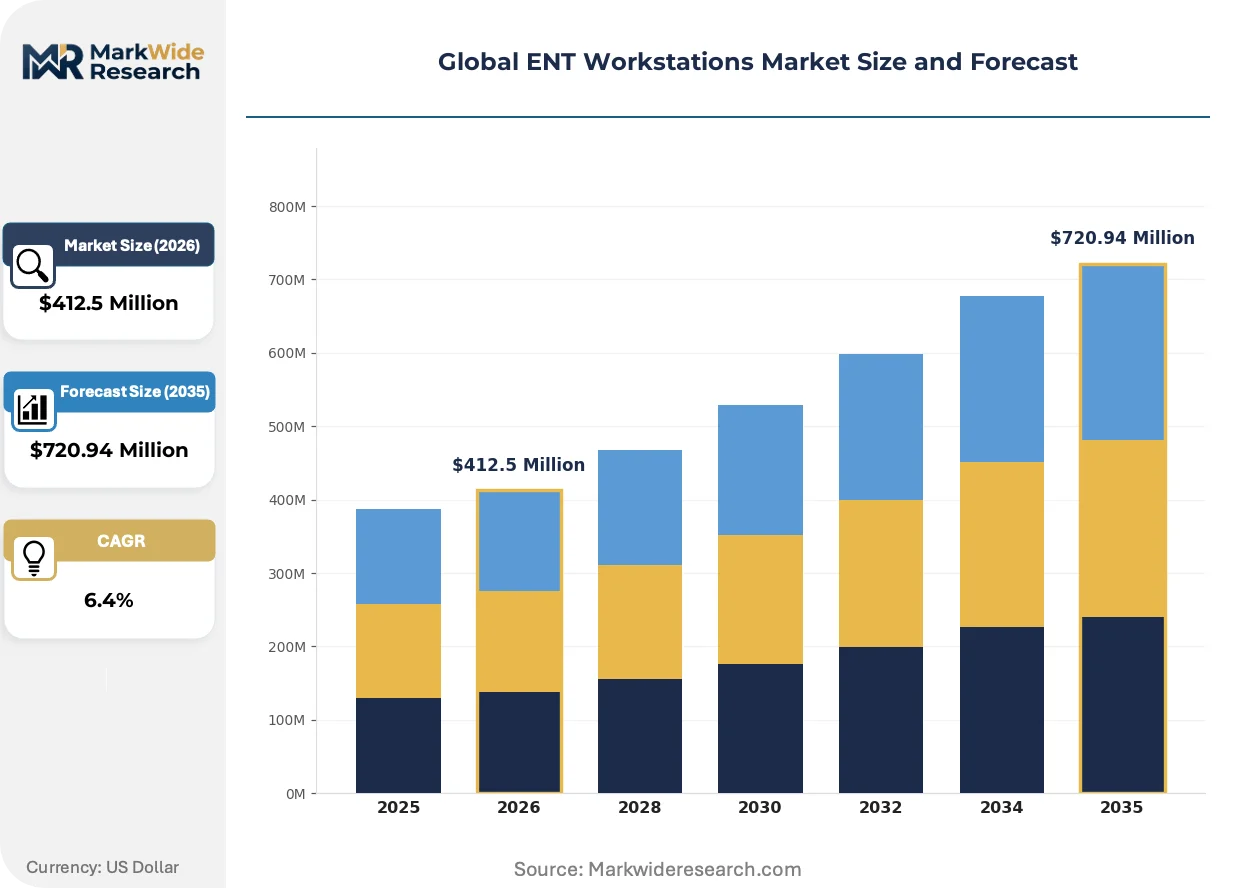
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Endoscopes, Imaging Systems, Audio Testing Devices Technology: 3D Imaging, HD Video, Wireless Connectivity, Digital Signal Processing Application: Hearing Assessment, Sinus Surgery, Voice Diagnostics, Sleep Apnea Evaluation End User: ENT Clinics, Diagnostic Laboratories, Ambulatory Surgical Centers, Research Institutes |
| Companies Covered | ATMOS MedizinTechnik GmbH & Co. KG, CHAMMED, Entermed B.V., dantschke Medizintechnik GmbH & Co. KG, ANA-MED, Euroclinic Medi-Care Solutions, Foshan Gladent Medical Instrument Co., Ltd, Optomic, Heinemann Medizintechnik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global ENT Workstations Market Shifts & Advancements
Digital image capture architectures are displacing analog visualization pipelines, while regulatory harmonization between ISO 13485 revisions and EU notified body expectations is reshaping supplier qualification criteria across manufacturing bases.
4K video processing chipsets are integrating directly into ENT workstation core boards, replacing external capture boxes and reducing cable routing complexity. German and Japanese university hospital networks are adopting these configurations fastest, with procurement committees prioritizing single-vendor accountability for image quality. This consolidation is compressing the addressable market for third-party video accessories while elevating software integration depth as the primary competitive differentiator.
REACH substance restrictions are compelling manufacturers to reformulate cable jacketing and PCB conformal coatings around halogen-free alternatives, extending material qualification cycles by 6-9 months. The regulatory friction falls heaviest on compact workstation producers serving price-sensitive Southern European markets, where reformulation costs cannot be passed through without volume erosion. German manufacturers with captive chemical engineering resources are absorbing these transitions more efficiently than competitors dependent on Asian contract assemblers.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchase agreements, negotiating direct technical support relationships with manufacturers while relegating traditional distributors to logistics-only roles. This disintermediation is most advanced in France and the Netherlands, where group purchasing organizations have consolidated negotiating leverage across regional clinic networks. Distributor margins are compressing 40-60% in these markets, forcing channel restructuring toward inventory financing and installation coordination rather than service bundling.
Global ENT Workstations Market Segmentation
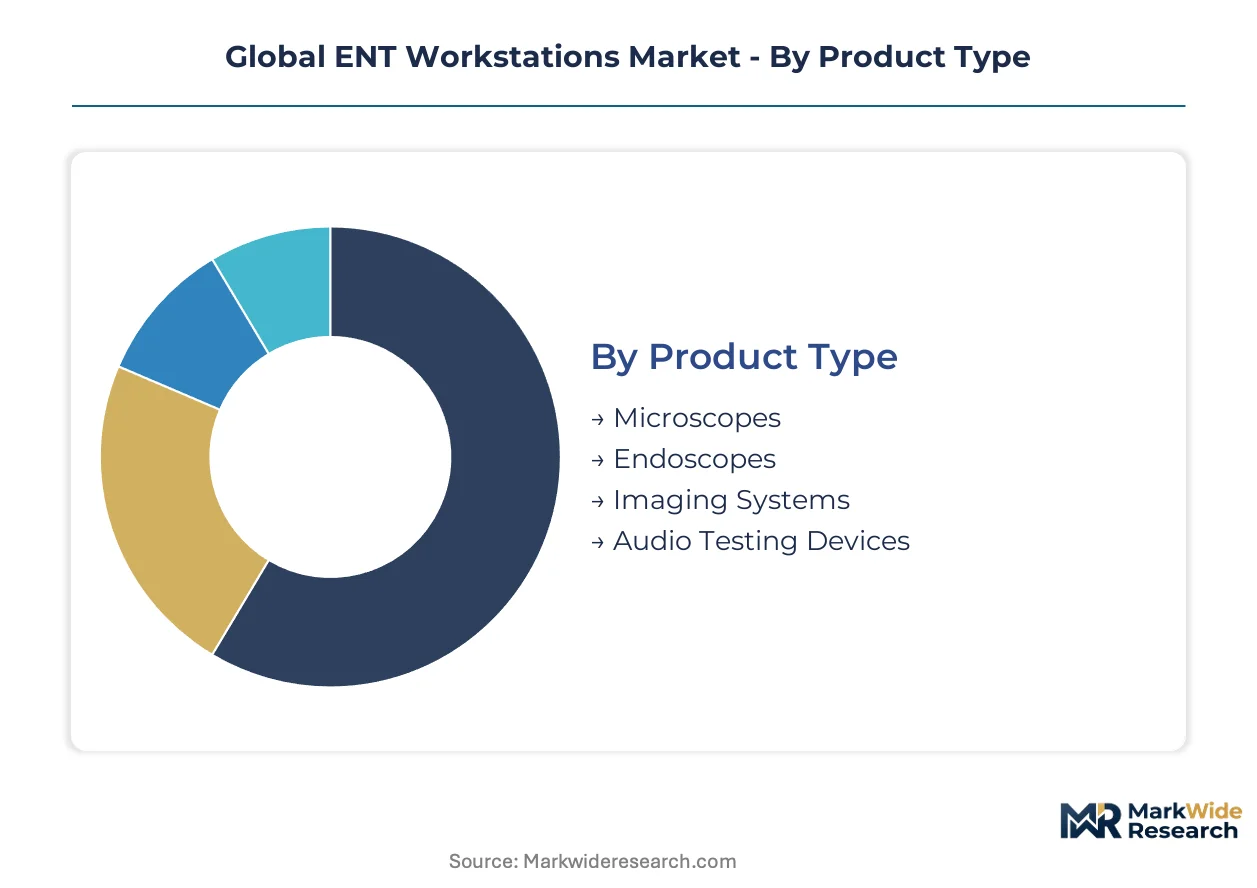
ENT workstation procurement patterns diverge sharply across clinical settings, with upgrade cycles ranging from 5-7 years for imaging systems to 10-12 years for optical benches. Segmentation reveals how technology maturity, reimbursement rates, and procedural volume shape replacement timing and feature prioritization across installed bases.
Product Type:
Replacement cycles accelerate where software-dependent components face obsolescence pressure from regulatory and connectivity standards evolution.
- Microscopes:Modular optical-mechanical platforms with 200-400mm working distances and integrated LED illumination dominate German and Japanese university hospital procurement. Demand concentrates in configurations supporting microscope-endoscope combination modes for complex skull base procedures.
- Imaging Systems:Digital capture architectures with 1080p to 4K resolution and DICOM-compliant archiving command premium positioning through recurring calibration service contracts. German specialized ENT clinics drive volume for systems with AI-assisted diagnostic overlays.
- Endoscopes:Rigid and flexible insertion tubes with CMOS sensor integration face margin compression from scaled Asian manufacturing.
- Audio Testing Devices:Audiometry modules with tympanometry and otoacoustic emission capabilities complete workstation suites for hearing assessment workflows.
Volume placements concentrate in imaging systems; the faster expansion belongs to microscope-endoscope combinations.
Technology:
Technology selection tracks the tension between cable-reduced clinic environments and legacy infrastructure compatibility constraints.
- Wireless Connectivity:Bluetooth 5.3 and Wi-Fi 6E implementations enable tablet-based control interfaces and cable-reduced examination rooms. Japanese clinic operators prioritize these configurations for ergonomic flexibility in space-constrained urban facilities.
- HD Video:1080p pipeline architectures with broadcast-grade image processing remain the workhorse standard for mid-tier ENT clinics in Southern Europe and Latin America.
- 3D Imaging:Stereoscopic visualization for surgical planning applications gains traction in French and Dutch university hospital networks.
- Digital Signal Processing:Real-time audio enhancement algorithms support voice diagnostics and intraoperative nerve monitoring functions.
Procurement volumes favor HD video architectures; wireless connectivity is climbing the fastest as clinics modernize examination infrastructure.
Application:
Application-specific workstation configurations align with reimbursement density and procedural complexity gradients across healthcare systems.
- Hearing Assessment:Integrated audiometry, tympanometry, and otoacoustic emission testing in single-console layouts dominate German clinic procurement due to strong statutory health insurance coverage for audiology services.
- Sinus Surgery:Navigation-compatible workstations with image-guided instrumentation interfaces concentrate in ambulatory surgical centers consolidating endoscopic sinus procedure capabilities.
- Voice Diagnostics:Stroboscopy and acoustic analysis modules serve laryngology subspecialists in academic medical centers.
- Sleep Apnea Evaluation:Drug-induced sleep endoscopy and upper airway assessment tools integrate with polysomnography workflows.
Installed base density peaks in hearing assessment; sinus surgery applications are gaining share fastest through ambulatory facility expansion.
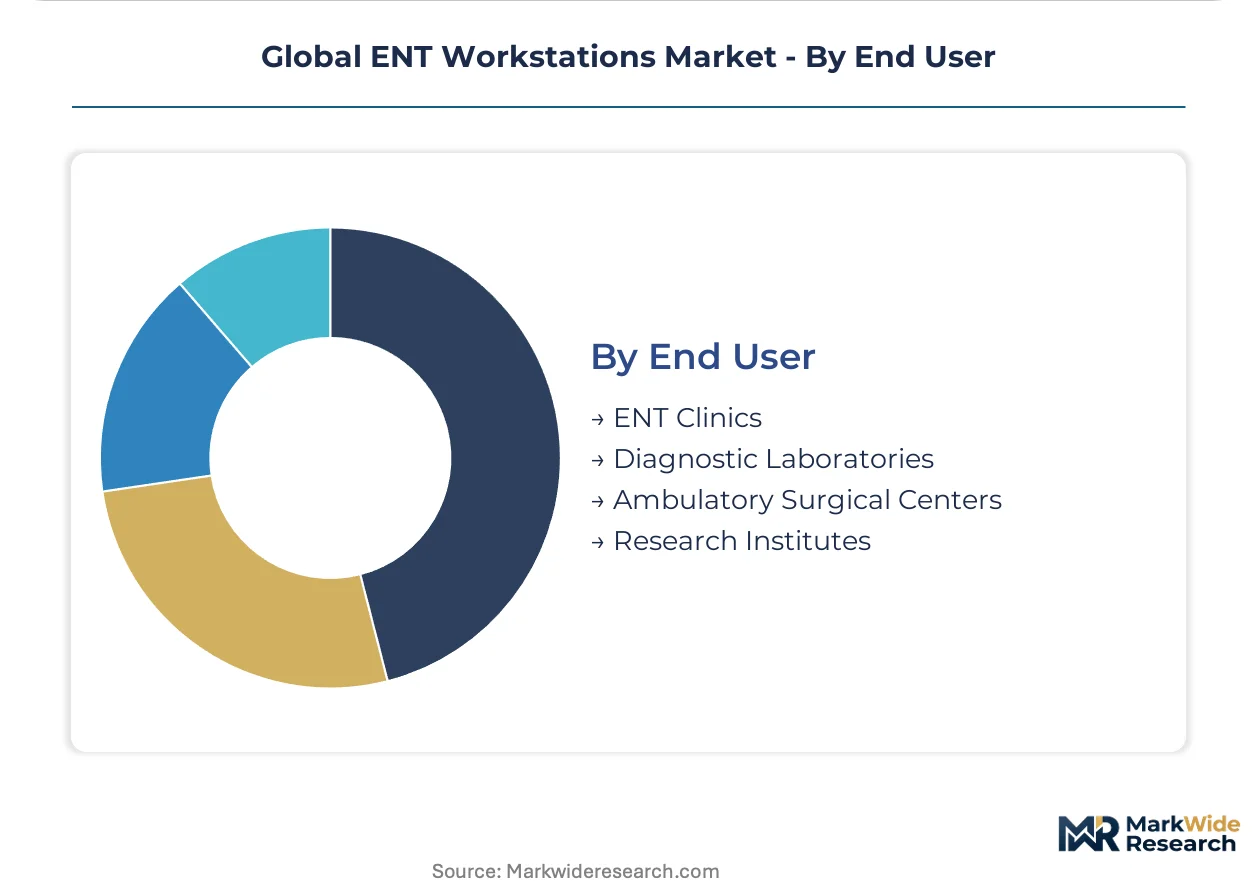
End User:
End-user category determines capital availability, procurement centralization, and service contract negotiation leverage.
- ENT Clinics:Specialized otolaryngology practices in Germany, France, and Italy drive demand for premium-tier configurations with comprehensive optical and audiological capabilities.
- Ambulatory Surgical Centers:Freestanding surgical facilities in the United States consolidate diagnostic and interventional capabilities into single-suite platforms.
- Diagnostic Laboratories:Independent testing facilities prioritize audio testing device integration for hearing screening service lines.
- Research Institutes:University hospital networks in Japan and Germany procure experimental configurations for clinical trial and training applications.
Procurement volume concentrates in ENT clinics; ambulatory surgical centers show the steepest expansion trajectory through facility buildout programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Munich anchors European ENT workstation demand through its dense cluster of university hospitals and specialized otolaryngology practices. The city's integration of diagnostic imaging with surgical planning workflows sets procurement standards across the continent.
Germany
Specialized ENT clinics in Bavaria and Baden-Württemberg drive premium-tier procurement for microscope-endoscope combinations with integrated audiology modules. The EU Medical Device Regulation's quality system requirements filter out marginal competitors, concentrating volume among manufacturers with dedicated notified body relationships. Stuttgart's medical technology corridor houses engineering talent for optical-mechanical integration.
United States
Ambulatory surgical centers in Texas and Florida consolidate diagnostic and minor interventional capabilities into single-suite ENT workstation configurations. The FDA's Quality System Regulation shapes clinical validation timelines and aftermarket service obligations for dual-territory approval seekers. The Dallas-Fort Worth metroplex hosts distributor networks serving the Southeast and Southwest clinic markets.
Japan
Tokyo's space-constrained urban clinics prioritize wireless connectivity configurations with tablet-based control interfaces for ergonomic flexibility. The PMDA imposes additional electromagnetic compatibility and biological safety testing layers that extend product registration timelines. Osaka's university hospital networks adopt 4K video processing chipsets fastest, prioritizing single-vendor accountability.
India
Mumbai and Delhi clinic networks expand procurement of compact, price-accessible ENT workstation configurations suited for diagnostic infrastructure buildout. The PLI scheme for medical devices incentivizes local assembly, creating first-mover advantages for manufacturers establishing technical training partnerships. Bangalore's medical device manufacturing zone attracts component suppliers for CMOS sensor integration.
France
Paris and Lyon university hospital networks drive demand for 3D imaging configurations in surgical planning applications. Group purchasing organizations consolidate negotiating leverage across regional clinic networks, unbundling after-sales service contracts from equipment purchase agreements. The EMA's harmonization with ISO 13485 revisions reshapes supplier qualification criteria for diagnostic imaging components.
Global ENT Workstations Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the ENT workstation market, with integrated platform manufacturers facing pressure from modular component specialists. The vendor base organizes into three tiers: premium German and Japanese manufacturers commanding imaging system margins, mid-tier European assemblers serving price-sensitive Southern European markets, and Asian fabricators compressing endoscope pricing through scaled production. Consolidation accelerates through strategic partnerships for wireless connectivity module integration and geographic expansion into India's diagnostic infrastructure buildout.
Within the premium-tier archetype, ATMOS MedizinTechnik GmbH & Co. KG and Heinemann Medizintechnik occupy positions sustained by German manufacturing bases and modular optical-mechanical platforms. Euroclinic Medi-Care Solutions represents the mid-tier configuration, anchoring Southern European demand through compact layouts. Optomic exemplifies aggressive distributor-network competition across Latin American and Middle Eastern markets. These three names illustrate how geographic origin and company structure correlate with strategic positioning across imaging fidelity, software integration depth, and after-sales service bundling vectors.
| Leading Market Players |
|---|
| ATMOS MedizinTechnik GmbH & Co. KG |
| CHAMMED |
| Entermed B.V. |
| dantschke Medizintechnik GmbH & Co. KG |
| ANA-MED |
| Euroclinic Medi-Care Solutions |
| Foshan Gladent Medical Instrument Co., Ltd |
| Optomic |
| Heinemann Medizintechnik |
| Others |
Supply & Pricing Matrix
Procurement committee unbundling of after-sales service contracts across French and Dutch group purchasing organizations is forcing manufacturers to absorb distributor margin compression while restructuring toward direct technical support relationships, elevating software licensing and calibration service revenue as the primary pricing anchors.
Pricing Analysis
Value-based pricing anchored to imaging system uptime guarantees and DICOM-compliant archiving throughput dominates premium-tier configurations. Three-tier pricing structure across premium, standard, and economy levels separates German-manufactured microscope-endoscope combinations from mid-tier European assemblers and Asian endoscope fabricators. Cost compression in rigid and flexible endoscope categories is intensifying because scaled Asian manufacturing feeds volume into price-sensitive Southern European markets. Mid-sized ENT clinics in Italy and Spain exhibit highest price sensitivity due to recurring per-seat software license fees, while Japanese university hospital networks show lowest sensitivity given prioritization of single-vendor accountability for 4K image quality.
Supply Chain Analysis
Direct-to-hospital channels handle German and Japanese university hospital demand for integrated workstation suites, while distributor networks with inventory financing capabilities serve Latin American and Middle Eastern markets. High-resolution CMOS sensors and precision lens assemblies draw from concentrated Taiwanese and South Korean foundry capacity. REACH substance restrictions on cable jacketing and PCB conformal coatings extend material qualification cycles. Single-source vulnerability in optical component supply exposes manufacturers to geopolitical disruption risk across the East Asian manufacturing corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biomedical engineering talent scarcity in optical-mechanical integration and embedded software development props pricing for German and Italian manufacturers with captive R&D capacity, constraining supply expansion for competitors lacking southern Germany or northern Italy engineering clusters.
For Market Incumbents: Anchor premium positioning through exclusive notified body relationships under the EU Medical Device Regulation, filtering out marginal competitors lacking dedicated regulatory affairs capacity. Deepen backward integration into CMOS sensor calibration capabilities to offset Taiwanese foundry concentration risk. Defend against Asian endoscope commoditization by bundling AI-assisted diagnostic overlays with imaging system service contracts. For New Entrants and Emerging Players: Launch via technical training partnerships with Mumbai and Delhi clinic networks to capture India's PLI scheme incentives for local medical device assembly. Target compact, price-accessible configurations for Southern European markets where REACH reformulation costs have eroded incumbent margins. Pursue cloud-connected remote calibration services as a go-to-market angle to bypass traditional distributor service margins in Middle Eastern markets. For Investors and Strategic Acquirers: The window for entry favors manufacturers with captive regulatory affairs capacity across dual-territory FDA and EU approval pathways. Long-term viability hinges on software integration depth rather than hardware fabrication scale. Watch PMDA electromagnetic compatibility certification timelines as an inflection indicator for Japanese market access bottlenecks that filter out undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | EU MDR quality system alignment accelerates notified body approval timelines for imaging system manufacturers. |
| Hospital System Partnership | Direct technical support relationships with French GPOs compress distributor margins while securing recurring calibration revenue. |
| Software Companion Development | AI-assisted diagnostic overlays for German specialized ENT clinics differentiate premium-tier microscope-endoscope combinations. |
| Reimbursement Strategy | Statutory health insurance coverage alignment for audiology modules drives procurement in Bavarian clinic networks. |
| Wireless Connectivity Module Integration | Bluetooth 5.3 and Wi-Fi 6E implementations capture Japanese demand for cable-reduced examination environments. |
Research Methodology
Independent corroboration across hospital purchasing committee interviews, biomedical engineering directors at German university hospitals, and regulatory affairs leads at notified bodies underwrites the qualitative findings. Secondary validation draws from FDA Quality System Regulation filings, EMA medical device registration databases, and PMDA electromagnetic compatibility certification records. Bottom-up procurement volume estimates from ambulatory surgical centers and top-down ENT clinic infrastructure spending patterns were reconciled through iterative triangulation.
Rate-of-change decomposition across product type, technology architecture, application workflow, and end-user category segments shaped the analytical framework over the projection horizon. CAGRs were derived from installed base replacement cycle analysis and ambulatory facility expansion trajectories. Modeled inputs include 5-7 year imaging system upgrade cycles for software-dependent components and 10-12 year optical bench lifecycles.
Regulatory harmonization delays between ISO 13485 revisions and EU notified body expectations, geopolitical disruption in East Asian optical component supply, and reimbursement rate compression in Southern European healthcare systems are the dominant revision risks. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
North America Hearing Aid Market
ENT
Global Sinusitis Treatment Market
ENT
Electrolarynx Market
ENT
ENT Examination Chair Market
ENT
Custom Hearing Aids Market
ENT
Audiology Devices Market
ENT
Europe Hearing Aids Market
ENT
Denmark Hearing Aids Market
ENT
ENT Disorder Treatment Market
ENT
Global Audiological Devices Market
ENT
Europe Speech Therapy Market
ENT
US Hearing Aids Market
ENT
Surgical ENT Devices Market
ENT
Hearing Amplifiers Market
ENT
Ear Health Market