
 ATP Assays Market | 2026-2036
ATP Assays Market Size, Share, and Industry Trends Forecast 2026-2036
ATP Assays Market Analysis
Bioluminescence detection sensitivity is narrowing the performance gap between benchtop and high-throughput platforms, forcing vendors to recalibrate instrument architectures. Thermo Fisher Scientific anchors its position through integrated reagent-instrument workflows that reduce protocol variability. Promega Corporation specializes in luciferase-based assay chemistries that sustain premium positioning in cell viability applications. Abcam plc competes through recombinant antibody paired detection systems that extend assay specificity.
ATP assays quantify adenosine triphosphate concentration through enzymatic luciferin-luciferase reactions, producing photon outputs proportional to metabolic activity in living cells; this measurement principle underpins sterility verification, cytotoxicity screening, and bioburden enumeration across GMP environments. Luminescence assays dominate the product type landscape due to femtomole detection limits and minimal sample preparation burden, while fluorescent assays occupy faster-growing niches where multiplexing with viability dyes adds diagnostic depth. Research organizations represent the most concentrated end user segment, though pharmaceutical companies are expanding internal assay validation capabilities to accelerate IND-enabling toxicology timelines.
The FDA enforces GMP compliance through 21 CFR Part 211 guidelines that mandate validated microbial detection methods, directly shaping ATP assay qualification requirements for pharmaceutical manufacturing. ISO 14698 cleanroom standards and the European Pharmacopoeia 5.1.6 bioburden methodology create parallel compliance architectures that vendors must address for multi-regional product registration. Stakeholders should monitor evolving pharmacopeial harmonization between USP, EP, and JP ATP detection chapters, as divergence in acceptance criteria could fragment assay standardization investments and force territory-specific kit formulations.
Market Dynamics
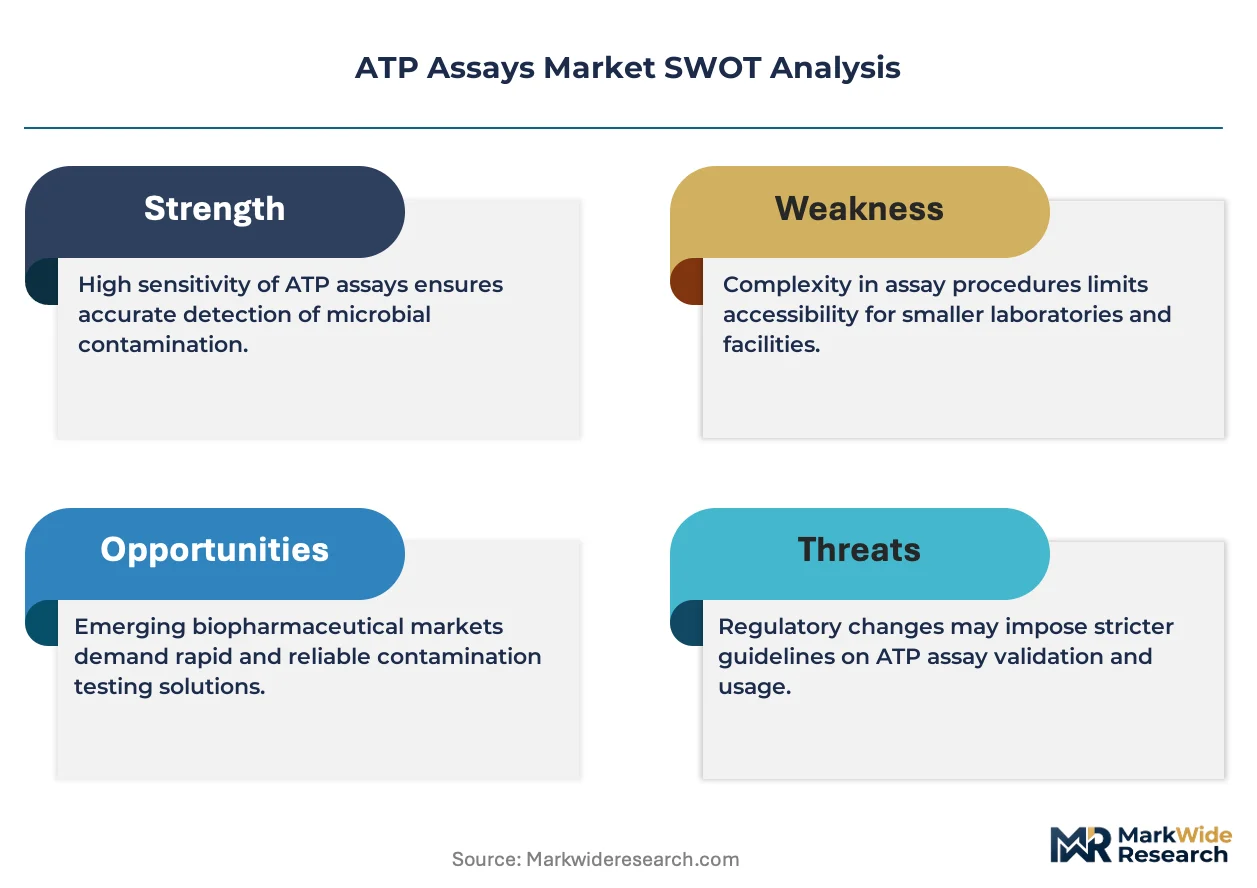
Bioluminescence sensitivity thresholds are compressing the performance premium between benchtop and high-throughput ATP detection platforms, forcing vendors to differentiate through integrated reagent-instrument workflows rather than raw detection limits alone.
Growth Catalysts
- FDA 21 CFR Part 211 enforcement:The agency's tightened microbial detection validation requirements for pharmaceutical manufacturing are mandating ATP-based sterility verification, expanding kit qualification demand across GMP facilities.
- Cell and gene therapy pipelines:Advanced therapy developers require rapid metabolic activity screening for cell viability assessment, accelerating adoption of luminescent ATP assays in IND-enabling toxicology workflows.
- ISO 14698 cleanroom standards:Bioburden enumeration protocols in aseptic manufacturing environments are standardizing ATP detection as a primary environmental monitoring tool across multi-site operations.
Market Restraints
- Luciferase reagent cost volatility:Firefly luciferase supply concentrates in specialized fermentation facilities, creating input cost instability for assay kit manufacturers.
- Cross-reactivity limitations:Non-mammalian ATP sources and detergent interference produce false-positive signals in complex sample matrices, constraining assay reliability in environmental testing applications.
- Pharmacopeial divergence:Misaligned acceptance criteria between USP, EP, and JP ATP detection chapters fragment standardization investments and force territory-specific kit formulations.
Strategic Opportunities
- Point-of-care microbial detection:Portable luminometer platforms are opening ATP-based hygiene verification in food service and healthcare settings beyond traditional laboratory environments.
- Multiplexing with fluorescent viability dyes:Assay developers are combining ATP detection with membrane integrity markers to create dual-parameter cell health readouts for high-content screening applications.
- Biopharma R&D outsourcing:CRO infrastructure expansion in the United States is creating concentrated demand for validated ATP assay protocols in contract toxicology services.
Industry Challenges
- Assay standardization complexity:Harmonizing ATP extraction efficiency across diverse cell types and tissue matrices requires extensive validation labor, extending product development timelines.
- Instrument-reagent compatibility:Proprietary detection chemistries lock users into single-vendor ecosystems, complicating procurement flexibility for multi-site research organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ATP Assays Market |
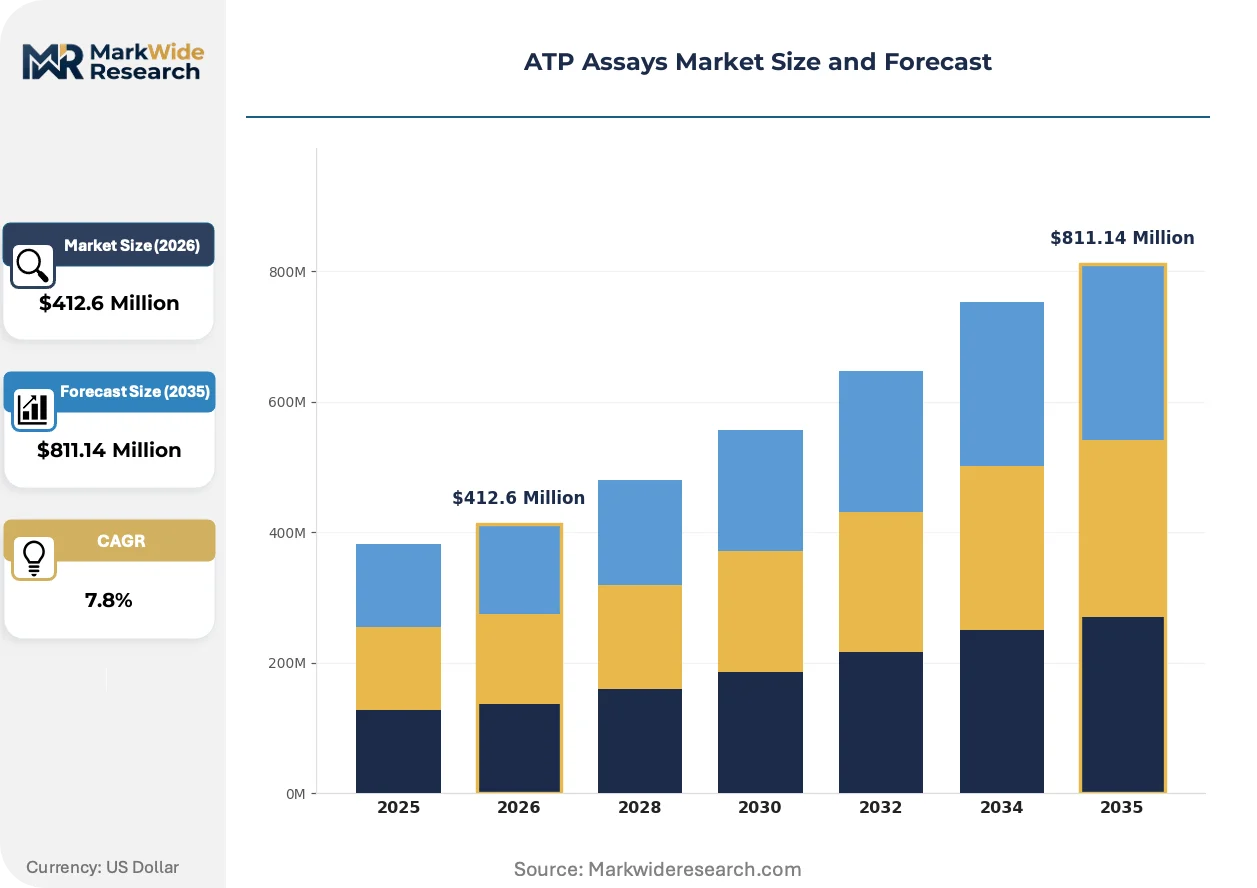
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $811.14 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Luminescence Assays, Colorimetric Assays, Fluorescent Assays, Quenching Assays End User: Clinical Laboratories, Research Organizations, Pharmaceutical Companies, Food & Beverage Industry Application: Microbial Detection, Cell Viability Testing, Bioburden Testing, Environmental Monitoring Technology: ATP Measurement, Bioluminescence, Enzymatic Reaction, Detection Systems |
| Companies Covered | PerkinElmer Inc., 3M Company, Thermo Fisher Scientific Inc., Abcam plc, Lonza Group, Merck KGaA, Agilent Technologies Inc., Neogen Corporation, Promega Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ATP Assays Market Emerging Trajectories
Digital integration and assay miniaturization are converging to reshape how ATP detection workflows are executed, validated, and reported across regulated and research environments.
Microfluidic cartridge platforms are digitizing sample handling and reagent dispensing for ATP assays, eliminating manual pipetting variability. Pharmaceutical quality control labs are adopting these systems to compress sterility testing turnaround times from days to hours. The technology is digitizing compliance documentation through embedded chain-of-custody logging and automated data integrity safeguards.
REACH chemical registration requirements in Europe are tightening scrutiny on luciferin substrate formulations and their synthetic precursors. Assay vendors are reformulating detection chemistries to eliminate substances of very high concern from manufacturing processes. Biopharma manufacturers in Germany and Switzerland are prioritizing EU Green Deal-aligned suppliers to preempt regulatory friction in multi-regional product registrations.
Consolidated procurement through centralized biorepository and assay service contracts is displacing decentralized kit purchasing in large research institutions. Core facility managers at academic medical centers are negotiating enterprise-wide ATP assay supply agreements that bundle reagents, instrumentation, and technical support. This concentration is most visible in the United States, where NIH-funded institutions are leveraging scale to extract preferential pricing and priority technical service commitments.
ATP Assays Market Segmentation
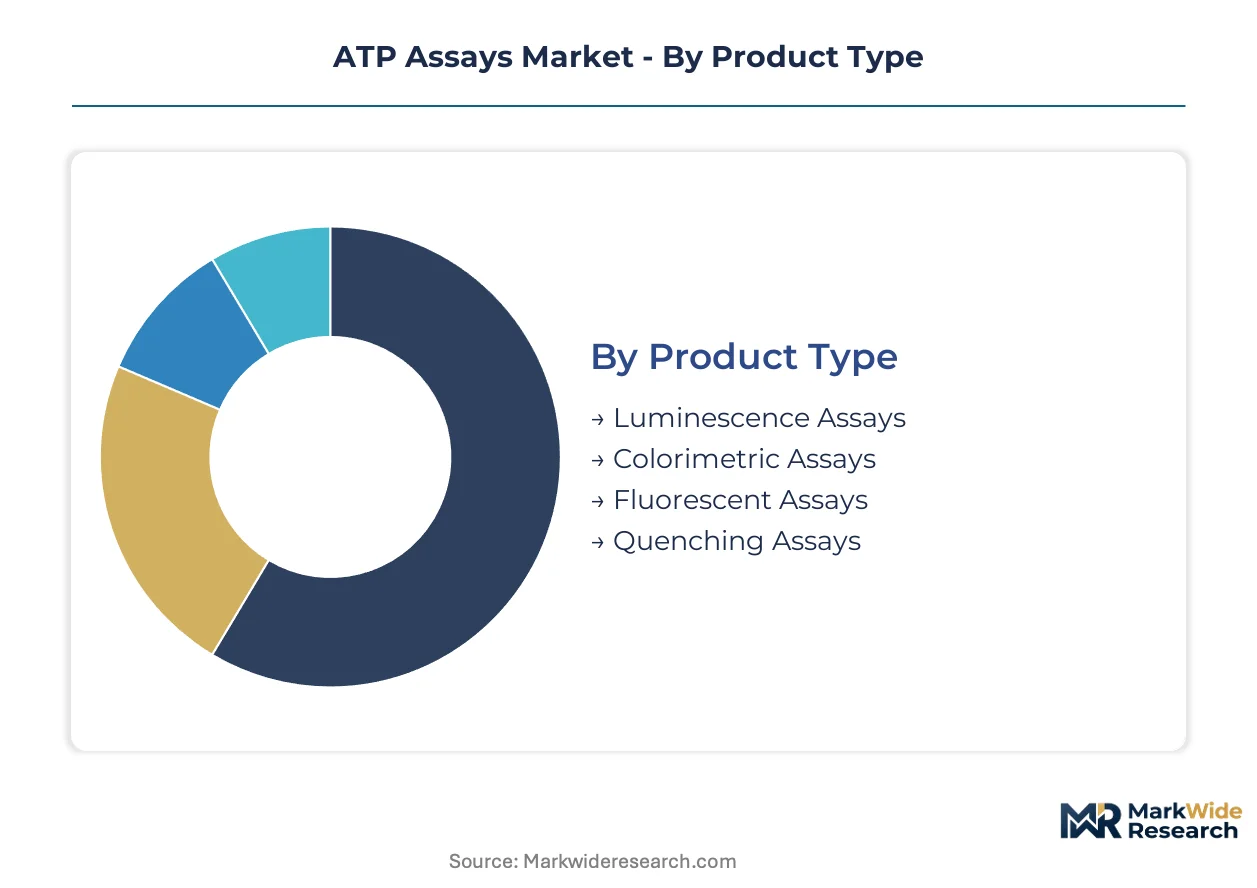
ATP assay architectures diverge sharply across detection modalities and deployment contexts, with each segment demanding distinct validation protocols, instrumentation investments, and regulatory compliance pathways. Understanding these fault lines enables vendors to align R&D priorities with concentrated demand pockets rather than spreading capabilities thin across incompatible use cases.
Product Type:
Luminescence assays anchor routine workflows while fluorescent and colorimetric variants carve specialized niches where multiplexing or cost constraints reshape purchasing criteria.
- Luminescence Assays:Firefly luciferase-driven photon generation achieves femtomole ATP sensitivity with minimal sample preparation, making these the default choice for GMP sterility verification in United States pharmaceutical manufacturing. Thermo Fisher and Promega have built integrated reagent-instrument ecosystems around this chemistry, locking in multi-year supply contracts with top-20 biopharma manufacturers.
- Fluorescent Assays:Coumarin or resorufin-based detection enables simultaneous ATP quantification with membrane integrity dyes, creating dual-parameter readouts for high-content screening in contract research organizations. The format gains traction where IND-enabling toxicology studies require viability normalization against metabolic activity baselines.
- Colorimetric Assays:Simpler enzymatic cascades produce visible absorbance shifts suitable for resource-limited settings lacking luminometer infrastructure.
- Quenching Assays:Signal suppression architectures reduce background interference in complex environmental matrices where non-mammalian ATP sources complicate interpretation.
Established volume favors Luminescence Assays; emerging adoption favors Fluorescent Assays.
End User:
Procurement authority and validation burden split unevenly across customer types, with pharmaceutical internalization of assay capabilities disrupting traditional CRO service relationships.
- Pharmaceutical Companies:Cell and gene therapy developers are building in-house ATP assay validation teams to compress IND timelines, directly purchasing GMP-qualified kits rather than outsourcing to contract laboratories. FDA 21 CFR Part 211 enforcement has elevated sterility verification from quality control checkbox to board-level compliance priority.
- Research Organizations:NIH-funded academic medical centers concentrate procurement through centralized biorepository contracts, extracting enterprise pricing from vendors willing to bundle reagents, instrumentation, and technical support across multi-site deployments.
- Clinical Laboratories:Hospital-based microbiology units apply ATP detection to rapid sterility confirmation in blood culture workflows.
- Food & Beverage Industry:Dairy and meat processors deploy portable luminometers for hygiene verification on production lines.
Research Organizations command the largest installed base; Pharmaceutical Companies are climbing the fastest.
Application:
Regulatory mandate intensity varies dramatically across use cases, with GMP-enforced applications commanding price premiums over research-grade deployments.
- Cell Viability Testing:Advanced therapy manufacturers require metabolic activity screening for potency release of CAR-T and stem cell products, with ATP assays serving as the pharmacodynamic endpoint in FDA-reviewed manufacturing protocols. The application ties directly to batch release decisions with patient safety implications.
- Microbial Detection:Sterility testing of parenteral drugs and biologics operates under FDA 21 CFR Part 211 and EU GMP Annex 1, mandating validated ATP-based methods with documented detection limits for specific organisms.
- Bioburden Testing:Environmental monitoring of cleanroom surfaces and personnel in aseptic fill-finish suites follows ISO 14698 methodologies.
- Environmental Monitoring:Wastewater and drinking water utilities apply ATP detection to rapid microbial enumeration outside pharmaceutical regulatory frameworks.
Microbial Detection absorbs the highest regulatory investment; Cell Viability Testing shows the steepest expansion trajectory.
Technology:
Detection physics and signal processing architectures determine sensitivity ceilings, throughput scalability, and compatibility with automated liquid handling platforms.
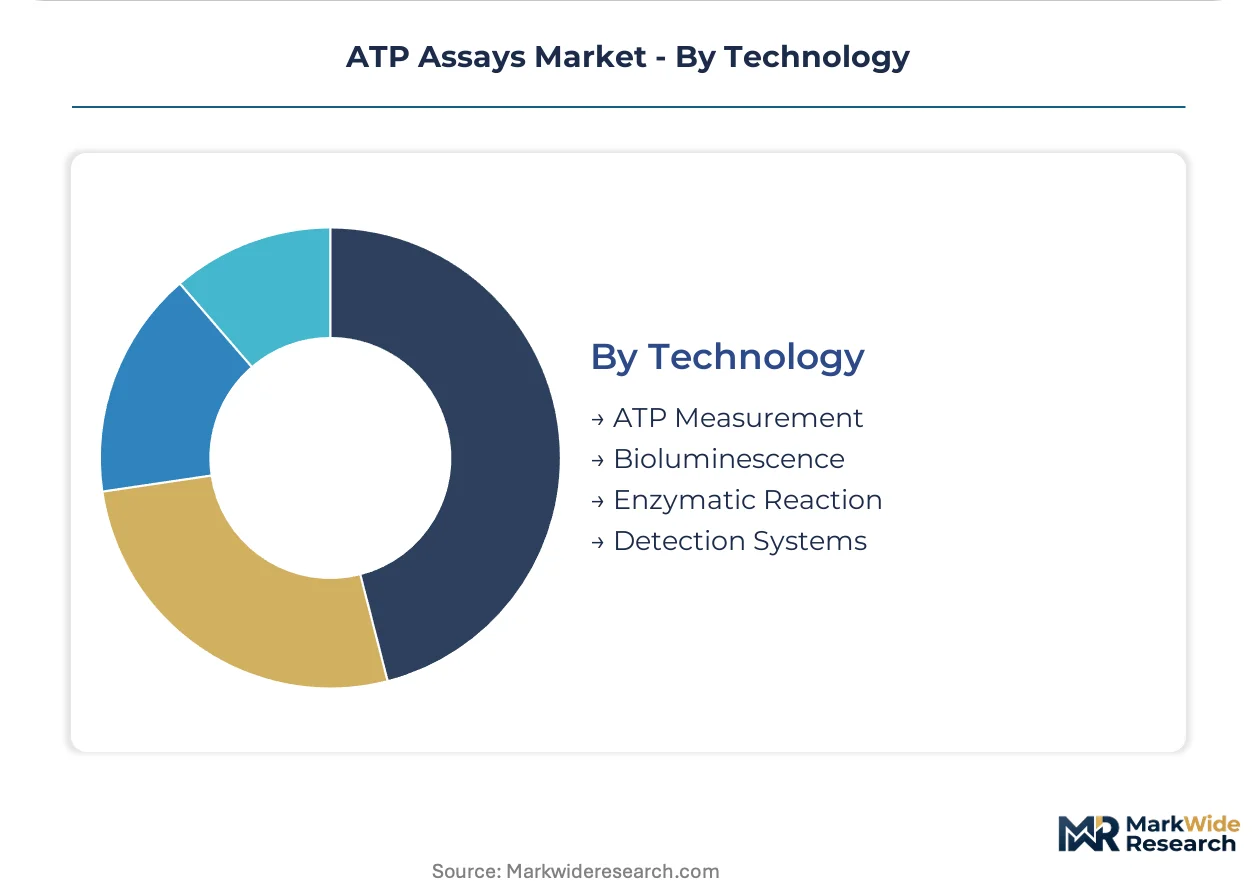
- Bioluminescence:Luciferin-luciferase chemistry produces photon outputs proportional to ATP concentration, with cooled photomultiplier tubes or CMOS sensors capturing signal across 10-decade dynamic ranges. The technology dominates where femtomole sensitivity differentiates viable from non-viable cell populations.
- ATP Measurement:Direct quantification protocols standardize extraction efficiency across mammalian, bacterial, and fungal cell walls through detergent-based lysis optimization.
- Enzymatic Reaction:Hexokinase or glyceraldehyde-3-phosphate dehydrogenase cascades provide alternative ATP detection without luciferase supply dependencies.
- Detection Systems:Luminometer hardware spans portable single-tube devices to 1536-well microplate readers with integrated stackers and barcode tracking.
Bioluminescence retains technology leadership; Detection Systems hardware is gaining share fastest through microfluidic digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Biopharma contract research organizations and advanced therapy developers concentrate procurement authority in jurisdictions with dense regulatory infrastructure and GMP manufacturing ecosystems. FDA enforcement timelines and pharmacopeial harmonization gaps reshape territory-specific kit qualification strategies.
United States
Cell and gene therapy developers in Massachusetts and California drive demand for IND-enabling ATP assay validation. FDA 21 CFR Part 211 enforcement mandates GMP-qualified sterility verification methods. The Boston-Cambridge cluster hosts concentrated CRO infrastructure serving multi-site pharmaceutical manufacturing protocols.
Germany
REACH chemical registration requirements tighten scrutiny on luciferin substrate formulations and synthetic precursors. ECHA substance-of-very-high-concern listings force reformulation of detection chemistries. Bavarian and Baden-Württemberg biopharma manufacturers prioritize EU Green Deal-aligned suppliers to preempt multi-regional registration friction.
Switzerland
Swissmedic guidance on advanced therapy product characterization elevates ATP-based potency release testing requirements. Basel and Zurich host concentrated biologics manufacturing with internalized assay validation capabilities. Swiss facilities negotiate enterprise-wide supply agreements bundling reagents, instrumentation, and technical support.
United Kingdom
MHRA post-Brexit divergence from EU pharmacopeial standards creates parallel kit qualification pathways. London-Oxford-Cambridge research institutions centralize procurement through NIH-aligned biorepository contracts. UK CROs expand contract toxicology services requiring validated ATP protocols for IND submissions.
Japan
PMDA harmonization initiatives with FDA and EMA reshape acceptance criteria for ATP detection methods. Tokyo-Osaka pharmaceutical corridors internalize cell viability testing to compress batch release timelines. Japanese manufacturers demand instrument-reagent compatibility across multi-vendor environments to preserve procurement flexibility.
ATP Assays Market Vendor Landscape
Channel-controlling players compete with product-specialist players across integrated workflow and standalone reagent segments. The vendor base organizes around three archetypes: diversified life science conglomerates with captive instrument platforms, luciferase chemistry specialists with premium reagent positioning, and recombinant detection system developers extending assay specificity. Consolidation pressure operates through strategic partnerships binding reagent supply to hardware ecosystems, while geographic expansion targets CRO-dense clusters in the United States and Western Europe.
Among diversified conglomerates with integrated reagent-instrument workflows, Thermo Fisher Scientific Inc. anchors the channel-control archetype through multi-year supply contracts with top-tier biopharma manufacturers. Promega Corporation occupies the chemistry-specialist position, sustaining premium positioning in cell viability applications through luciferase-based assay expertise. Abcam plc exemplifies the recombinant detection tier, competing through antibody-paired systems that extend assay specificity in complex sample matrices.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| 3M Company |
| Thermo Fisher Scientific Inc. |
| Abcam plc |
| Lonza Group |
| Merck KGaA |
| Agilent Technologies Inc. |
| Neogen Corporation |
| Promega Corporation |
| Others |
Supply Flow & Price Mechanics
The Rotterdam-Antwerp pharmaceutical logistics corridor anchors ATP assay kit distribution across Western Europe, with freight cost volatility compressing margins for manufacturers sourcing firefly luciferase from specialized fermentation facilities in Germany and Switzerland. This transport-cost pressure amplifies pricing power for integrated reagent-instrument vendors while forcing standalone kit suppliers toward volume-based contract structures.
Pricing Analysis
Cost-plus contracts with luciferase price indexation dominate long-term supply agreements between assay kit manufacturers and biopharma purchasers. Three-tier pricing structure across premium, standard, and economy levels separates GMP-qualified validation-grade kits from research-use-only formulations and bulk unvalidated reagents. Pricing pressure stems from NIH-funded academic medical centers consolidating procurement through enterprise-wide biorepository contracts. Contract research organizations exhibit highest price sensitivity due to pass-through client billing constraints, while cell and gene therapy developers prioritize qualification documentation over per-kit cost.
Supply Chain Analysis
Tariff exposure between the United States and China concentrates supply risk for ATP assay manufacturers dependent on CMOS photodetector components and specialized plastic consumables. Firefly luciferase production concentrates in Germany, Switzerland, and the United States, with recombinant enzyme fermentation drawing from glucose feedstock and precision bioreactor engineering. Single-source vulnerability characterizes high-sensitivity photomultiplier tube supply from Japanese electronics manufacturers. Distribution runs through authorized distributor networks serving GMP-qualified pharmaceutical manufacturing sites, with direct procurement displacing intermediaries in large research institutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ATP detection workflows are shifting toward platform-economics dynamics as microfluidic cartridge standardization and cloud-connected luminometer ecosystems create interoperability expectations that favor integrated vendors over standalone reagent suppliers.
For Market Incumbents: Entrench multi-year enterprise contracts by bundling GMP validation support with instrument placement programs, neutralizing the threat from emerging portable luminometer entrants targeting point-of-care microbial detection. Deepen backward integration into recombinant luciferase fermentation capacity in Switzerland and Germany to preempt supply cost volatility. Prioritize FDA pre-submission engagement for novel multiplexed assay formats to accelerate IND-enabling toxicology adoption timelines.
For New Entrants and Emerging Players: Food and beverage hygiene verification in the United States and Western Europe represents the most penetrable entry point, with dairy processors and meatpacking facilities underserved by legacy pharmaceutical-focused assay vendors. Portable single-tube luminometer platforms with simplified reagent cartridges address this white-space where laboratory infrastructure is absent. Pursue co-development partnerships with industrial hygiene service providers to embed ATP detection into recurring facility audit workflows rather than capital equipment sales.
For Investors and Strategic Acquirers: FDA harmonization initiatives with PMDA and EMA on cell therapy potency assay acceptance criteria reshape the acquisition landscape toward vendors with multi-regional pharmacopeial validation capabilities. Long-term viability centers on platform ecosystems rather than standalone chemistry intellectual property. Target acquisition profiles emphasize microfluidic cartridge developers with embedded compliance documentation capabilities. Monitor Swissmedic guidance evolution on advanced therapy product characterization as the signal indicating accelerated consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Microfluidic Cartridge Platform Launch | Compresses sterility testing turnaround from days to hours in GMP facilities. |
| GMP Validation Service Bundling | Locks biopharma manufacturers into multi-year reagent supply commitments. |
| Backward Integration into Luciferase Fermentation | Insulates margins from firefly enzyme supply cost volatility. |
| Multiplexed Fluorescent Assay Development | Captures high-content screening demand from contract toxicology CROs. |
| EU Green Deal Chemistry Reformulation | Preempts REACH substance-of-very-high-concern regulatory friction in Europe. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with drug development executives, regulatory affairs leads at advanced therapy manufacturers, GMP quality control directors, and core facility managers at NIH-funded academic medical centers; and secondary validation against FDA 21 CFR Part 211 guidance documents, EMA advanced therapy quality guidelines, ISO 14698 cleanroom standards, USP and EP pharmacopeial chapters, and SEC filings from publicly traded life science tools vendors. Bottom-up triangulation across assay kit volume estimates and top-down reconciliation against biopharma R&D expenditure patterns anchored market sizing.
Forecast inputs incorporated product type segmentation across luminescence, fluorescent, colorimetric, and quenching assay architectures; end user segmentation spanning pharmaceutical companies, research organizations, clinical laboratories, and food and beverage processors; application segmentation across cell viability testing, microbial detection, bioburden testing, and environmental monitoring; and technology segmentation across bioluminescence chemistry, direct ATP measurement protocols, enzymatic reaction cascades, and detection systems hardware. CAGRs were derived from regression analysis of historical adoption curves adjusted for regulatory mandate intensity. Industry-specific forecast inputs included FDA cell and gene therapy pipeline expansion rates and ISO 14698 cleanroom standard revision timelines.
Macroeconomic conditions sit as an overlay; deviation in biopharma venture capital availability, NIH appropriations levels, or EU REACH enforcement intensity would shift the trajectory. Forecasts reflect documented assumptions regarding pharmacopeial harmonization progress and luciferase fermentation capacity expansion. Material shifts in FDA advanced therapy guidance timelines or firefly luciferase supply concentration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Minimal Residual Disease Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Nipah Virus Testing Market
Testing Services
Blood Borne Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Self-Testing Market
Testing Services
Drug Testing Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Bimetallic Thermometer Market
Testing Services
US & Europe Extractable and Leachable Testing Services Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Indoor Allergen and Particulate Exposure Assessment Test Devices Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
Fecal Calprotectin Test Market
Testing Services
Pharmaceutical Analytical Testing Market