
 INR Test Meter Market | 2026-2036
INR Test Meter Market Size, Share, and Industry Trends Forecast 2026-2036
INR Test Meter Market Foresight
Subscription-based remote monitoring platforms is restructuring how INR test meter vendors capture recurring revenue beyond hardware sales. Roche Diagnostics leverages its integrated digital health ecosystem to sustain patient adherence through cloud-connected dashboards. Abbott Laboratories anchors its competitive stance with pharmacy-channel distribution density across North American and European markets. Siemens Healthineers differentiates through hospital-grade calibration protocols that extend into outpatient coagulation networks.
An INR test meter is a portable or benchtop electrochemical or optical analytical device that quantifies blood clotting time via prothrombin time/international normalized ratio (PT/INR) measurement from capillary whole blood samples, primarily enabling therapeutic monitoring of vitamin K antagonist therapy such as warfarin. Portable meters command the dominant installed base due to fingerstick sampling convenience and Bluetooth-linked data transmission to anticoagulation clinics. Point-of-care devices represent the fastest-growing product category as urgent care centers and physician offices adopt CLIA-waived systems for same-visit dosing decisions. Electrochemical technology occupies the largest technology share while microfluidic platforms attract development investment for reduced sample volume requirements.
The US FDA regulates INR meters as Class II medical devices requiring 510(k) premarket notification, while the EU Medical Device Regulation (MDR) mandates notified body conformity assessment and post-market surveillance for CE-marked systems. ISO 15197 standards govern analytical performance criteria for blood glucose and coagulation self-testing systems, directly influencing manufacturer design verification protocols. Stakeholders must monitor evolving MDR transition timelines and FDA digital health guidance to align quality management investments with compliance deadlines.
Market Dynamics
Bluetooth-enabled data transmission to anticoagulation clinics is compressing the traditional clinic-visit model for warfarin patients. This connectivity shift is restructuring how therapeutic monitoring gets reimbursed and delivered across outpatient networks.
Growth Catalysts
- 510(k) OTC Clearance Pathway:The US FDA's streamlined premarket notification for over-the-counter INR devices eliminates prescription barriers and expands retail pharmacy access for self-testing patients.
- Atrial Fibrillation Disease Management Programs:Germany's structured reimbursement frameworks for self-monitoring systems embed test meters into chronic care pathways for anticoagulated patients.
- Capillary Sampling Convenience:Fingerstick-based portable meters reduce venipuncture dependency and enable real-time dosing adjustments without laboratory infrastructure.
Market Restraints
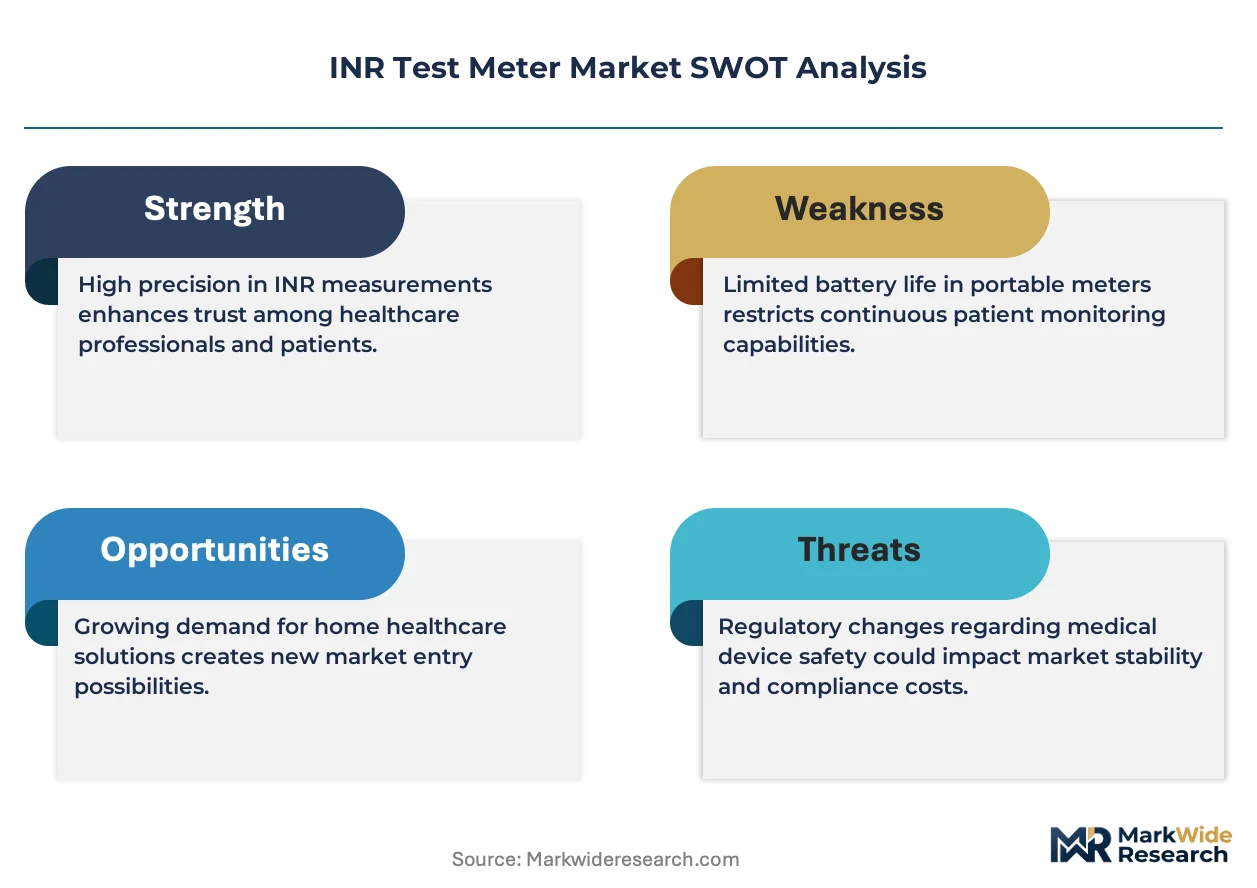
- Electrochemical Sensor Cost Concentration:Reagent strip manufacturing concentrates among specialty chemical suppliers, exposing device margins to palladium and silver price volatility.
- EU MDR Transition Friction:The Medical Device Regulation's notified body conformity assessment creates certification bottlenecks and extended timeline uncertainty for CE-marked system renewals.
- Direct Oral Anticoagulant Substitution:DOACs such as apixaban and rivaroxaban eliminate routine monitoring requirements for eligible patient populations.
Strategic Opportunities
- India's Diagnostic Infrastructure Gap:Tier-2 and Tier-3 cities lack accessible coagulation laboratories, creating white space for pharmacy-distributed point-of-care systems.
- Remote Patient Monitoring Integration:Cloud-connected dashboards that feed into electronic health records enable subscription-based recurring revenue beyond hardware sales.
- CLIA-Waived Urgent Care Adoption:Physician office laboratories and walk-in clinics are adopting waived-complexity systems for same-visit INR results and immediate warfarin dosing.
Industry Challenges
- ISO 15197 Analytical Performance Verification:Design validation for coagulation self-testing systems demands extensive clinical correlation studies against laboratory reference methods.
- Legacy Anticoagulation Clinic Integration:Hospital-based coagulation services resist data interoperability with patient-owned devices, fragmenting care continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | INR Test Meter Market |
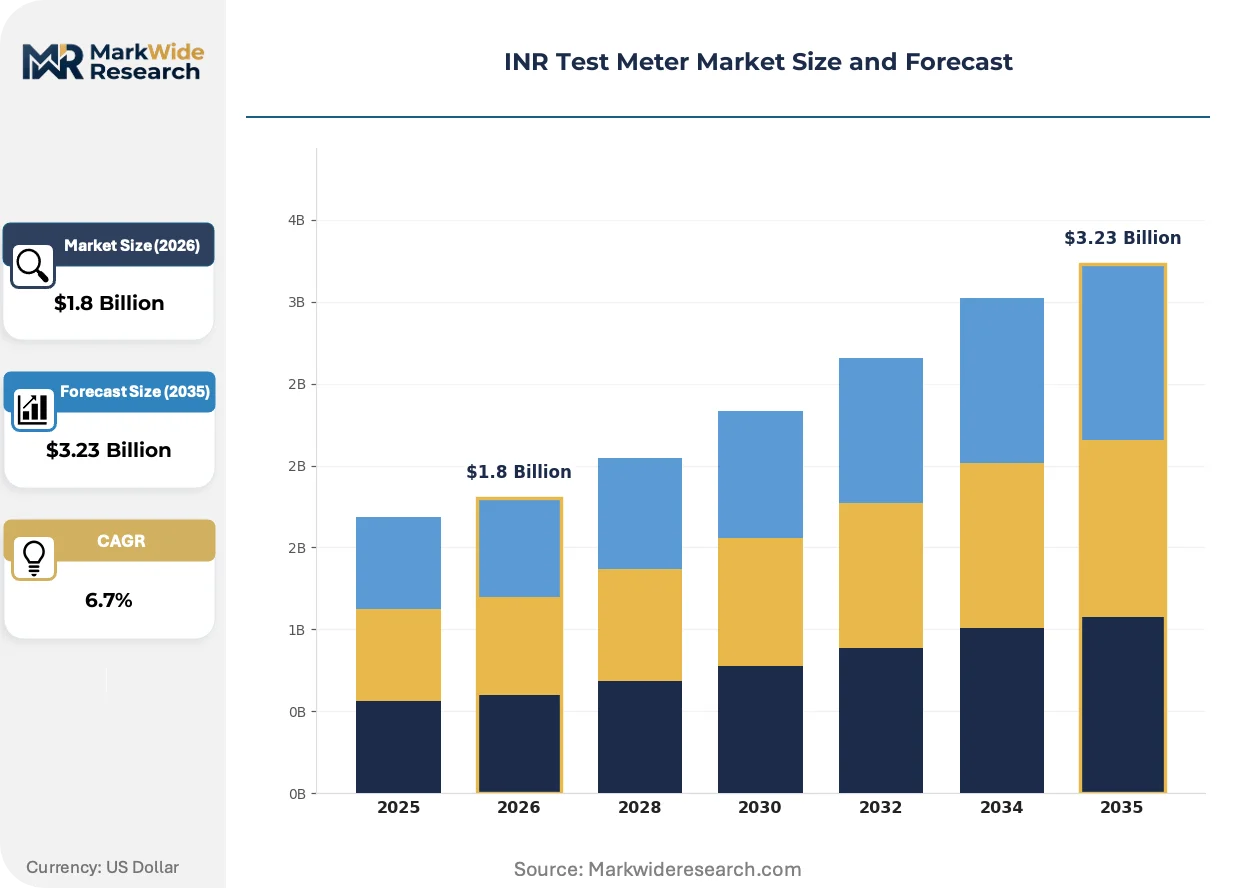
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Lab-Based Meters, Handheld Meters, Point-of-Care Devices End User: Clinics, Hospitals, Home Users, Diagnostic Centers Technology: Optical Technology, Electrochemical Technology, Colorimetric Technology, Microfluidic Technology Delivery Mode: Direct Sales, Online Sales, Distributors, Retail Stores |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Werfen, Sysmex Corporation, F. Hoffmann-La Roche Ltd, ACON Laboratories, Lepu Medical Technology, Eurolyser Diagnostica GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
INR Test Meter Market Shifts & Advancements
Digital health ecosystems are absorbing point-of-care diagnostics into longitudinal patient management platforms. This convergence is blurring hardware boundaries and redefining how therapeutic monitoring generates sustainable revenue.
Microfluidic cartridge technology is absorbing sample processing functions previously requiring benchtop centrifugation and reagent preparation. Urgent care centers and physician office laboratories are adopting these platforms to compress turnaround times for same-visit clinical decisions. The technology is absorbing capital expenditure from centralized laboratories into distributed settings.
The EU Medical Device Regulation's post-market surveillance requirements are mandating systematic vigilance reporting for CE-marked INR systems. Manufacturers must establish periodic safety update reports and trend analysis protocols that extend beyond premarket clinical data. Class IIa coagulation monitoring devices face heightened scrutiny of analytical performance under real-world conditions.
Anticoagulation clinics are unbundling device provisioning from professional interpretation services. Patients now purchase meters through retail channels while clinics bill separately for remote monitoring and dose management. This separation is most advanced in Germany and the Netherlands where statutory health insurance recognizes distinct reimbursement codes for self-testing equipment versus clinical oversight.
INR Test Meter Market Segmentation
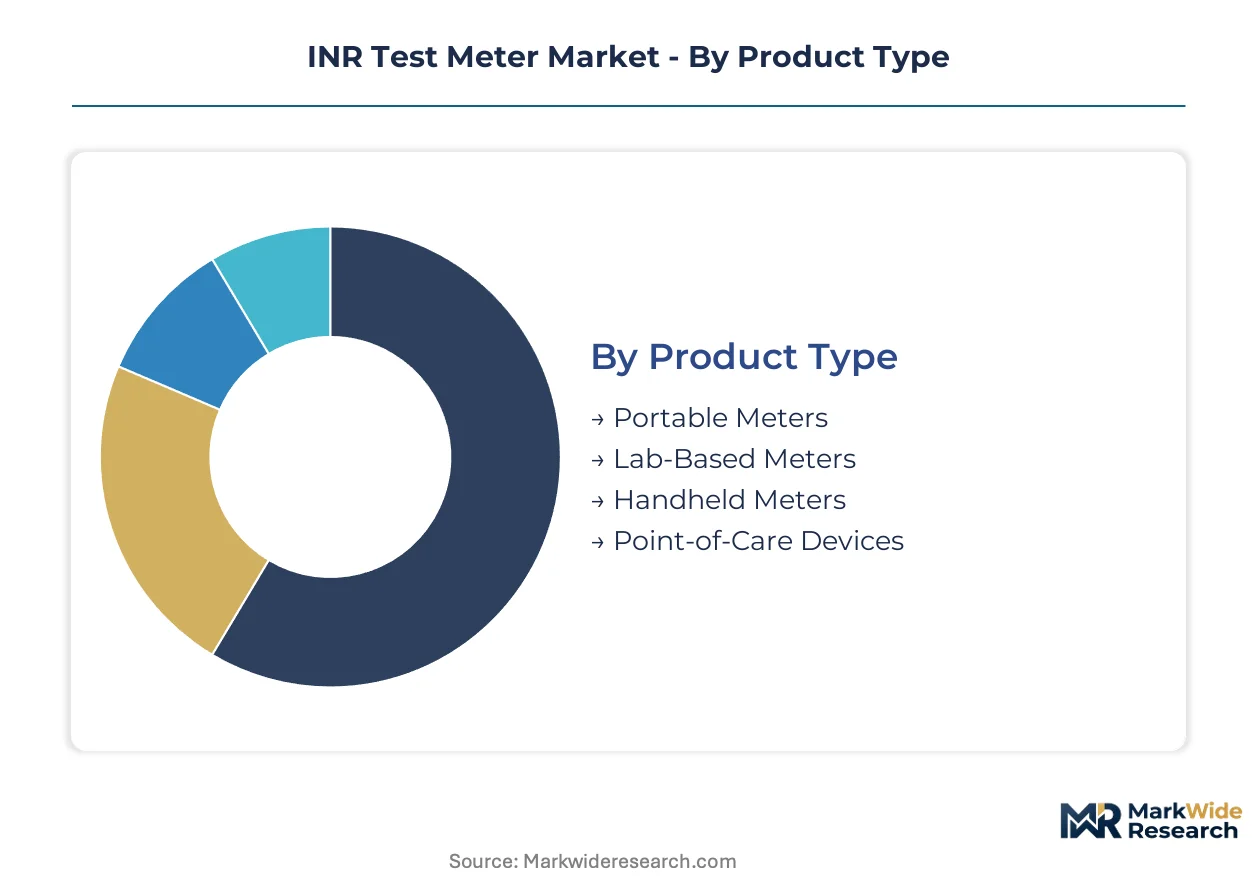
INR test meter segmentation reveals how device portability, testing location, and data connectivity reshape procurement patterns across anticoagulation care pathways. Manufacturers align product configurations with reimbursement codes, regulatory clearance pathways, and patient self-management readiness.
Product Type:
Portability requirements fragment this category from laboratory-grade precision instruments to smartphone-connected home units, with each tier demanding distinct calibration protocols and quality assurance investments.
- Portable Meters:Battery-powered electrochemical analyzers weighing under 500 grams process capillary whole blood via single-use reagent strips. Fingerstick sampling convenience drives concentration among warfarin patients in Germany and the Netherlands where statutory health insurance reimburses self-testing equipment separately from clinical oversight.
- Point-of-Care Devices:CLIA-waived systems deliver laboratory-comparable PT/INR results within minutes from 25-50 microliter samples. Urgent care centers and physician office laboratories across the United States adopt these platforms for same-visit dosing decisions, compressing traditional anticoagulation clinic visit cycles.
- Handheld Meters:Compact units bridge home and clinical use with Bluetooth-linked data transmission to cloud dashboards.
- Lab-Based Meters:Benchtop analyzers with centrifugation modules serve high-throughput hospital coagulation laboratories requiring batch processing capabilities.
Leading the category by volume: Portable Meters. Growing fastest: Point-of-Care Devices.
End User:
Procurement authority and reimbursement eligibility diverge sharply across this category, with institutional purchasers negotiating volume contracts while individual patients navigate retail pharmacy channels.
- Home Users:Anticoagulated patients on long-term warfarin therapy purchase devices through pharmacy retail or online channels, then seek remote monitoring subscriptions from anticoagulation clinics. FDA 510(k) over-the-counter clearances eliminate prescription barriers, expanding access for atrial fibrillation patients with stable therapeutic ranges.
- Hospitals:Central laboratories and specialized coagulation services demand ISO 15197-compliant systems with extensive clinical correlation documentation against reference methods. EU MDR transition timelines create procurement uncertainty as notified body conformity assessments extend renewal cycles for existing installed bases.
- Clinics:Anticoagulation services and cardiology practices prioritize data interoperability with electronic health record systems.
- Diagnostic Centers:Independent laboratories serving outpatient networks require high-throughput platforms with automated sample handling.
Home Users generate the steepest volume expansion trajectory. Hospitals retain the largest installed base concentration.
Technology:
Sensor architecture determines reagent cost structures, calibration frequency, and susceptibility to environmental interference across deployment environments.
- Electrochemical Technology:Amperometric detection of thrombin generation via palladium-doped electrodes dominates portable and handheld segments. Reagent strip manufacturing concentrates among specialty chemical suppliers, exposing device margins to silver and palladium price volatility while delivering the precision required for narrow therapeutic index management.
- Microfluidic Technology:Cartridge-based platforms integrate sample preparation, reaction chambers, and optical detection into disposable units. Development investment flows toward reduced sample volume requirements, with emerging systems targeting sub-10 microliter thresholds for pediatric and geriatric populations with compromised capillary perfusion.
- Optical Technology:Turbidimetric and chromogenic detection methods persist in laboratory settings requiring visual clot formation assessment.
- Colorimetric Technology:Visual readout systems serve resource-limited settings without electrical infrastructure.
Electrochemical Technology commands dominant share. Microfluidic platforms attract the most intensive R&D allocation.
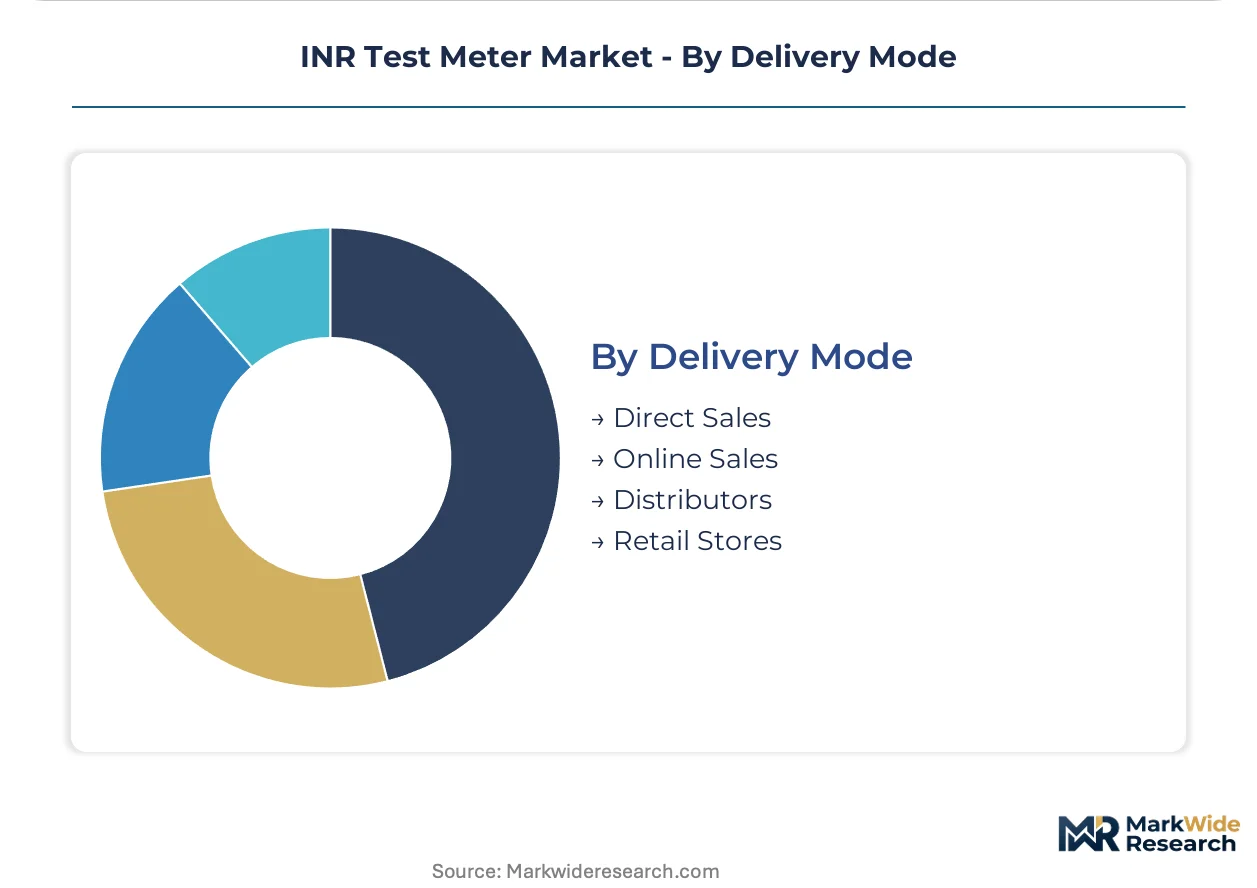
Delivery Mode:
Channel strategy reflects purchaser sophistication, with institutional buyers demanding field service support while retail consumers prioritize price transparency and subscription bundling.
- Distributors:Regional medical device distributors with coagulation specialization dominate hospital and diagnostic center procurement in Europe, offering installation validation, operator training, and preventive maintenance contracts. Germany's structured disease management programs channel self-testing systems through pharmacy wholesalers with established relationships to statutory health insurance funds.
- Online Sales:Direct-to-consumer platforms and pharmacy e-commerce capture home user segments with subscription-based remote monitoring bundles. Cloud-connected dashboard integration enables recurring revenue capture beyond hardware margins, with vendors embedding patient adherence tools into digital health ecosystems.
- Direct Sales:Manufacturer field organizations serve high-volume hospital accounts with customized service level agreements.
- Retail Stores:Pharmacy chains and medical supply outlets provide immediate device availability for prescription-to-purchase conversion.
Distributors retain institutional channel dominance. Online Sales expand most quickly among home user segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Device assembly concentrates in Germany and Switzerland while consumption spreads across outpatient networks in the United States, Germany, and Japan. The production-consumption gap widens as Asian contract manufacturers capture electrochemical sensor fabrication.
United States
Atrial fibrillation patients drive home-testing adoption through Medicare Advantage remote monitoring benefits. The FDA's 510(k) pathway for over-the-counter clearance eliminates prescription barriers for self-testing systems. Minneapolis and Boston anchor hospital procurement clusters where anticoagulation clinics negotiate volume contracts for CLIA-waived point-of-care devices.
Germany
Structured disease management programs embed INR meters into chronic care pathways for warfarin patients. Statutory health insurance funds reimburse self-testing equipment separately from clinical oversight through distinct procedure codes. The Rhine-Ruhr corridor concentrates pharmacy-wholesaler distribution networks serving statutory health insurance beneficiaries.
Japan
Aging demographics expand the anticoagulated population eligible for self-monitoring reimbursement under universal health coverage. The PMDA regulates point-of-care coagulation devices through pharmaceutical and medical device combined review pathways. Tokyo and Osaka metropolitan areas concentrate specialized coagulation laboratories that validate patient-owned device accuracy.
India
Tier-2 and Tier-3 cities lack accessible coagulation laboratories, creating white space for pharmacy-distributed point-of-care systems. The CDSCO requires import licenses and clinical performance documentation for in-vitro diagnostic devices. Maharashtra and Karnataka host diagnostic distributor networks expanding into cardiac care centers in Pune and Bengaluru.
Netherlands
Integrated care networks prioritize patient self-management for stable warfarin patients through remote monitoring subscriptions. The Dutch Healthcare Authority regulates reimbursement for telemonitoring services separate from device provisioning. The Randstad urban corridor concentrates anticoagulation clinics unbundling equipment sales from professional interpretation billing.
INR Test Meter Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the INR test meter landscape. Electrochemical sensor manufacturing demands palladium and silver supply chain control, while software-integrated platform developers capture recurring revenue through cloud subscriptions. Three archetypes dominate: diversified diagnostics conglomerates with hospital-grade calibration protocols, mid-scale specialists in pharmacy-channel distribution, and emerging microfluidic technology developers. Consolidation pressures intensify through strategic partnerships linking device manufacturers with remote monitoring platform operators.
Among diversified diagnostics conglomerates, Roche Diagnostics and Abbott Laboratories exemplify scale-driven positioning through integrated digital health ecosystems and pharmacy-channel density. Siemens Healthineers occupies a position bridging hospital-grade precision with outpatient network expansion. Werfen represents the mid-scale specialist archetype with concentrated coagulation expertise.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Werfen |
| Sysmex Corporation |
| F. Hoffmann-La Roche Ltd |
| ACON Laboratories |
| Lepu Medical Technology |
| Eurolyser Diagnostica GmbH |
| Others |
Supply & Pricing Matrix
Anticoagulation clinic procurement clusters in Minneapolis and Boston concentrate demand for CLIA-waived point-of-care systems, anchoring contract-based pricing with volume tiering and preventive maintenance bundling. This buyer concentration shapes pricing power toward institutional purchasers while home users face retail markups through pharmacy channels.
Pricing Analysis
Margin tightening in portable meter tiers reflects palladium and silver price volatility on electrochemical reagent strips. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 15197 compliance grade and Bluetooth connectivity features. Cost-down pressure accelerates because DOAC substitution erodes the addressable warfarin patient pool. Home users in Germany and the Netherlands exhibit highest price sensitivity where statutory insurance caps reimbursement, while hospital laboratories show lowest sensitivity due to total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for medical devices are reshaping sourcing toward local electrochemical sensor fabrication. Manufacturing concentrates in Germany, Switzerland, and China, with Asian contract manufacturers capturing palladium-doped electrode production. Raw material dependencies center on specialty chemical suppliers for silver chloride inks, polymer substrates, and precision-machined capillary channels. Single-source vulnerability concentrates in palladium refining capacity. Distribution runs through regional medical device distributors with coagulation specialization in Europe and pharmacy-wholesaler networks in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU MDR transition timeline erects a cost-of-compliance barrier that favors incumbents with notified body relationships and post-market surveillance infrastructure, creating a moat against undercapitalized entrants.
For Market Incumbents: Acquire cloud-connected remote monitoring platforms to capture recurring revenue beyond hardware margins. Siemens Healthineers should deepen hospital-grade calibration protocols into outpatient coagulation networks. Abbott Laboratories must defend pharmacy-channel density against emerging microfluidic entrants. Backward integration into palladium supply hedges reagent strip margin exposure.
For New Entrants and Emerging Players: The price-point gap between premium Bluetooth-enabled systems and economy visual-readout meters opens white space in India's Tier-2 and Tier-3 cities. Target pharmacy-distributed point-of-care systems for urgent care centers lacking laboratory infrastructure. Pursue CDSCO import license partnerships with Maharashtra and Karnataka distributor networks expanding into cardiac care centers.
For Investors and Strategic Acquirers: The window for entry favors microfluidic technology developers with sub-10 microliter sample volume capabilities. Long-term viability hinges on integration with electronic health record systems and subscription-based remote monitoring revenue models. Watch FDA 510(k) OTC clearance velocity as inflection indicator for home user segment expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body relationships accelerate conformity assessment timelines for Class IIa devices. |
| Hospital System Partnership | Anticoagulation clinic data interoperability agreements secure installed base loyalty against fragmentation. |
| Software Companion Development | Cloud-connected dashboards embedding patient adherence tools sustain recurring subscription revenue. |
| Reimbursement Strategy | Distinct procedure codes for self-testing equipment versus clinical oversight unlock German statutory insurance. |
| Backward Integration | In-house palladium supply control insulates reagent strip margins from commodity price volatility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving anticoagulation clinic directors, biomedical engineers, GPO contracts managers, and pharmacy procurement leads. FDA 510(k) premarket notification databases, EU MDR notified body certificates, CMS Medicare reimbursement schedules, and ISO 15197 compliance documentation provided validation layers. Bottom-up device shipment modeling and top-down healthcare expenditure triangulation reconciled volume estimates.
Data-stream reconciliation across product type, technology platform, end-user setting, and geographic regulatory cluster enabled segmentation integrity throughout the projection horizon. CAGRs derived from patient population epidemiology, warfarin prescription trends, and self-testing reimbursement expansion trajectories. Electrochemical sensor cost curves and microfluidic R&D investment flows informed technology adoption pacing.
Underlying measurement precision varies by segment; point-of-care device forecasts carry tighter precision than emerging microfluidic platform projections due to commercial maturity differentials. Forecasts reflect assumptions around DOAC substitution rates, MDR transition timeline adherence, and remote monitoring reimbursement code expansion. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pneumonia Testing Market
Testing Services
Cannabis Testing Services Market
Testing Services
Rift Valley Fever Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Industrial Radiography Testing Market
Testing Services
Specific Protein Testing Market
Testing Services
Blood Testing Market
Testing Services
Global C-Reactive Protein Testing Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Rapid Hepatitis Testing Market
Testing Services
Global at-Home Drug of Abuse (DOA) Testing Market
Testing Services
Warfarin Sensitivity Testing Market
Testing Services
Active B12 Test Market
Testing Services
Fecal Occult Testing Market