
 Chromatin Immunoprecipitation Testing Market | 2026-2036
Chromatin Immunoprecipitation Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Chromatin Immunoprecipitation Testing Market Outlook
Next-generation sequencing integration is reconfiguring how chromatin immunoprecipitation workflows are designed and executed in commercial laboratories. Thermo Fisher Scientific leverages its sequencing platform ecosystem to anchor comprehensive ChIP-to-sequencing pipelines. Abcam plc specializes in high-affinity antibody development for histone modification targets. Cell Signaling Technology competes through validated ChIP-grade antibody portfolios that reduce assay variability.
Chromatin immunoprecipitation testing isolates DNA-protein complexes using antibody-mediated capture followed by DNA recovery and analysis, typically requiring cross-linking with formaldehyde and sonication or enzymatic fragmentation to achieve chromatin sizes of 200–1000 base pairs. The technique enables mapping of transcription factor binding sites and histone modification patterns across genomes. ChIP kits and antibodies command the largest product segments due to recurring consumable demand in high-throughput academic settings. Next-generation sequencing technology leads technology adoption as researchers shift from qPCR-based readouts to genome-wide profiling. Epigenomics and disease research applications attract the fastest-growing investment as pharmaceutical sponsors fund target validation studies.
The US FDA regulates companion diagnostic development where ChIP-derived biomarkers may support oncology drug approvals, while the NIH establishes research standards through its Roadmap Epigenomics Project. ISO 15189 accreditation requirements shape quality management in contract research organizations performing regulated ChIP assays. Stakeholders must monitor how epigenetic biomarker qualification pathways evolve under FDA guidance to anticipate commercialization timelines for precision medicine applications.
Market Dynamics
Next-generation sequencing integration is compressing assay timelines and expanding data throughput for chromatin immunoprecipitation workflows, forcing kit manufacturers and antibody suppliers to reconfigure product architectures around unified ChIP-to-sequencing pipelines rather than standalone qPCR readouts.
Growth Catalysts
- NIH Roadmap Epigenomics Project:Federal funding consortia in the United States prioritize chromatin mapping initiatives, sustaining recurring consumable demand across academic medical centers and research institutes.
- Pharmaceutical target validation:Oncology drug sponsors invest in ChIP-derived biomarker studies to support mechanistic proof-of-concept for epigenetic therapies entering clinical pipelines.
- Enzymatic fragmentation methods:Replacement of sonication with micrococcal nuclease-based protocols reduces sample input requirements and improves reproducibility in low-cell-number applications.
Market Restraints
- Antibody supply concentration:Validated ChIP-grade antibody production concentrates among specialized biotechnology suppliers, creating batch-to-batch variability risks and qualification bottlenecks.
- High-throughput infrastructure costs:Sequencing platform access and bioinformatics pipeline maintenance require substantial capital allocation, limiting adoption in underfunded research settings.
- Cross-linking artifacts:Formaldehyde-based fixation introduces protein-protein interaction noise and epitope masking that complicate data interpretation for transcription factor studies.
Strategic Opportunities
- Single-cell epigenomics:Droplet-based microfluidics convergence with ChIP protocols opens genome-wide profiling at cellular resolution for heterogeneous tissue samples.
- Contract research expansion:Pharmaceutical sponsors outsource regulated ChIP assays to ISO 15189-accredited CROs, creating service revenue streams beyond kit and reagent sales.
- Companion diagnostic pathways:FDA biomarker qualification frameworks for epigenetic signatures in oncology create commercialization channels for ChIP-derived clinical assays.
Industry Challenges
- Bioinformatics talent scarcity:Peak calling, differential binding analysis, and pathway interpretation require specialized computational biology expertise that outpaces training pipeline output.
- Reproducibility standardization:ENCODE consortium guidelines lack universal enforcement, generating protocol drift across laboratories that undermines cross-study comparability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chromatin Immunoprecipitation Testing Market |
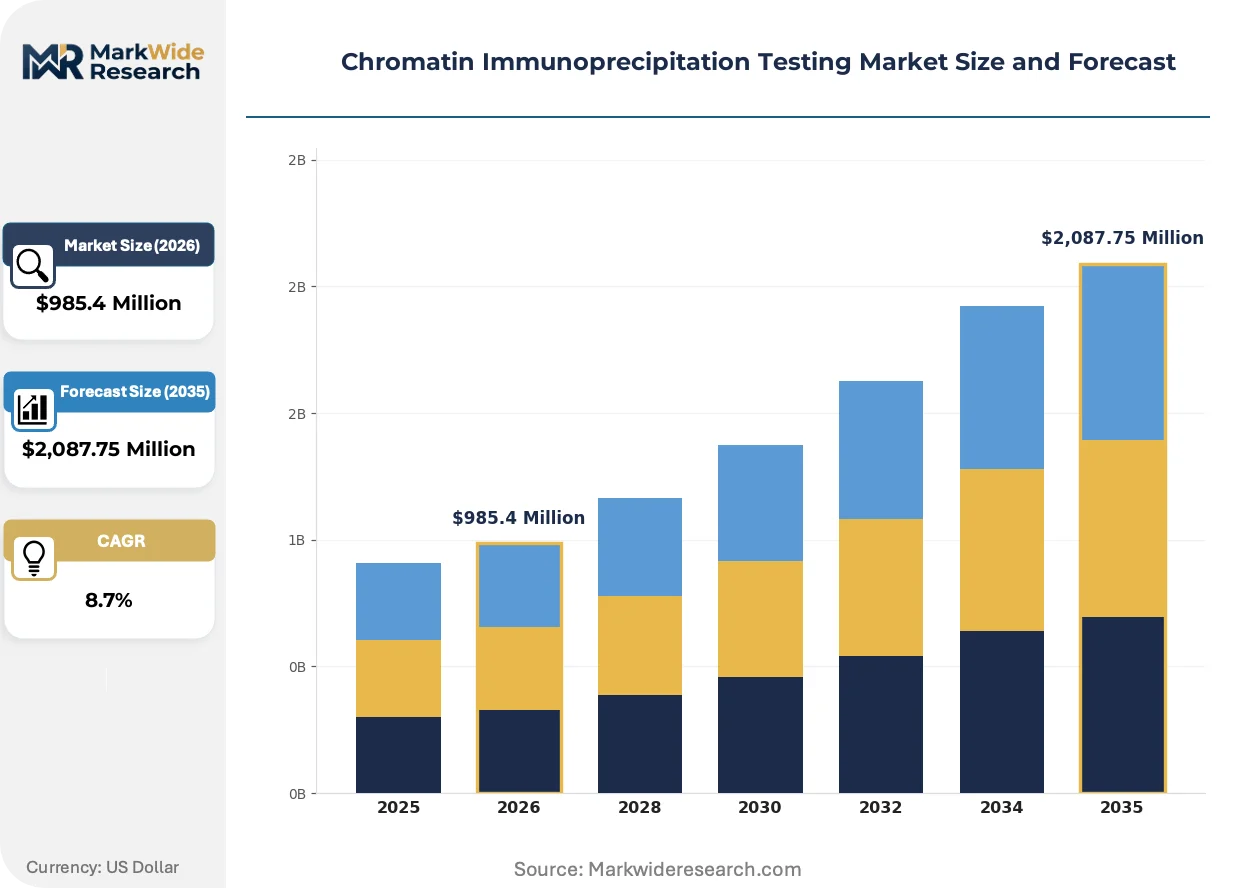
| Market Size in 2026 | $985.4 Million |
| Market Size in 2035 | $2,087.75 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ChIP Kits, Antibodies, Reagents, Consumables Technology: Next-Generation Sequencing, qPCR, Microarray, Mass Spectrometry Application: Gene Regulation, DNA-Protein Interaction, Epigenomics, Disease Research End User: Academic Institutions, Research Laboratories, Biopharmaceutical Companies, Contract Research Organizations |
| Companies Covered | Abcam plc, Cell Signaling Technology, Thermo Fisher Scientific Inc., Active Motif, BioLegend, Merck KGaA, Bio-Techne, Creative Diagnostics, Bio-Rad Laboratories, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chromatin Immunoprecipitation Testing Market Strategic Shifts
Technological convergence between chromatin biochemistry and sequencing instrumentation is redefining workflow architectures, while regulatory pressure on biomarker qualification and shifting procurement patterns among research funders reshape competitive positioning across the value chain.
Cut-and-run protocols are hybridizing enzymatic cleavage with streamlined antibody pulldown to reduce assay duration from days to hours. Academic core facilities in the United States and Europe adopt these methods for high-sample-throughput screening. The technology is hybridizing equipment requirements, compressing capital expenditure barriers for mid-scale laboratories entering epigenomic research.
EMA qualification guidance for epigenetic biomarkers in oncology drug development is tightening analytical validation requirements for ChIP-based assays submitted as companion diagnostics. Contract research organizations in Europe invest in CLIA-equivalent quality systems to serve pharmaceutical sponsor needs. Histone modification profiling for patient stratification faces heightened scrutiny under evolving EMA evidentiary standards.
Bundled reagent-and-service procurement models are displacing standalone kit purchases among multi-investigator research institutes. Core facility directors negotiate multi-year supply agreements that integrate technical support, protocol optimization, and data analysis consultation. This shift concentrates purchasing power in the United States and Germany, where centralized sequencing infrastructure dominates institutional budgets.
Chromatin Immunoprecipitation Testing Market Segmentation
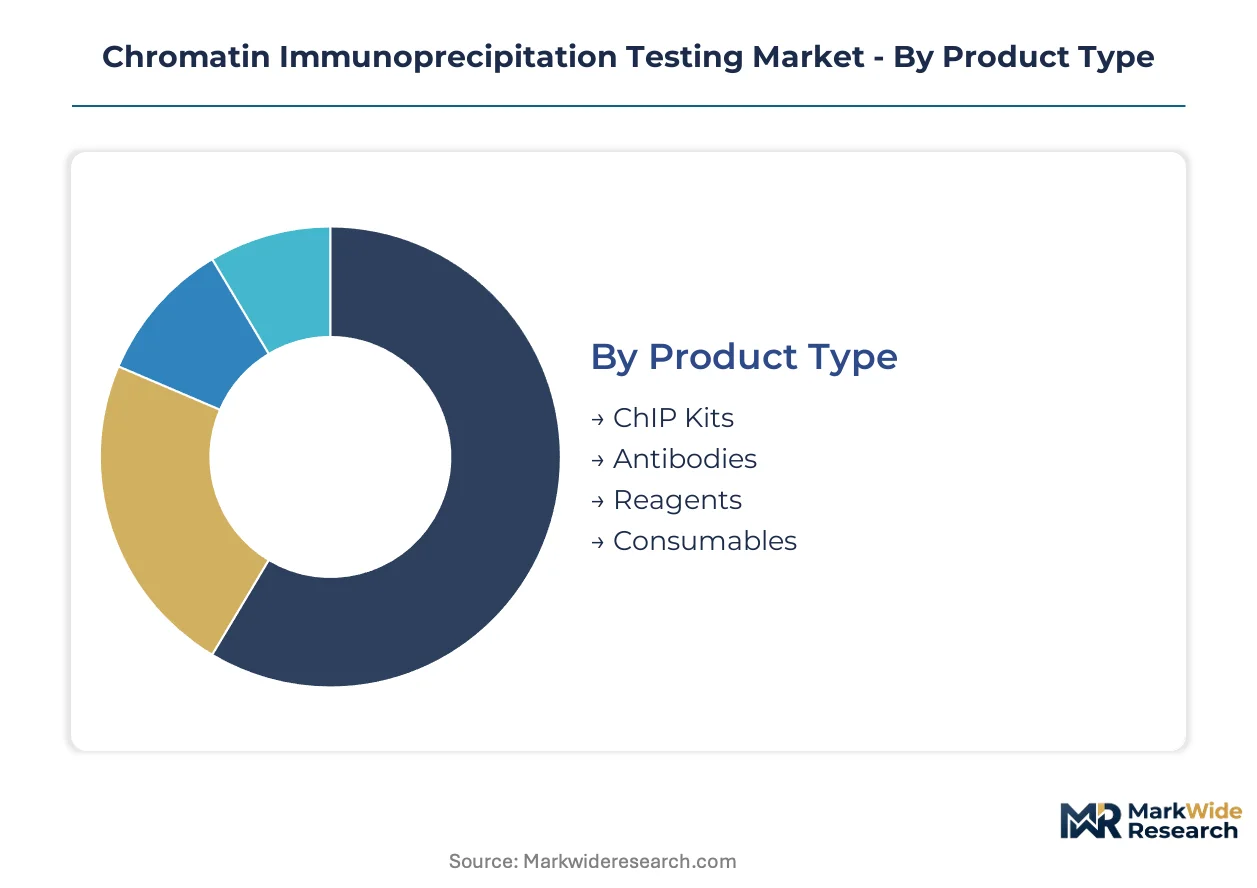
Segmentation in chromatin immunoprecipitation testing reveals distinct procurement patterns across product architectures, readout technologies, and institutional buyer types. Each dimension carries different margin profiles and service intensity requirements that reshape vendor go-to-market strategies.
Product Type:
After-sales service intensity varies sharply across product categories, with antibody portfolios demanding intensive technical validation support while consumables operate on transactional replenishment cycles.
- ChIP Kits:Integrated reagent systems bundle cross-linking buffers, blocking solutions, and DNA purification modules for standardized workflow execution. Academic core facilities in the United States negotiate multi-year supply agreements that embed protocol optimization and troubleshooting consultation. By volume, ChIP Kits lead. By growth pace, Antibodies is ahead.
- Antibodies:High-affinity immunoglobulins targeting histone modifications and transcription factors require batch-specific validation certificates and lot-to-lot consistency guarantees. Biopharmaceutical sponsors in Germany and Switzerland drive premium pricing for ChIP-grade certified reagents with documented cross-reactivity profiles.
- Reagents:Specialized buffers, beads, and wash solutions support protocol customization in experienced laboratories.
- Consumables:Columns, tubes, and plasticware generate recurring revenue through high-throughput screening operations.
Margin structures concentrate in antibody manufacturing where technical differentiation commands pricing power against commodity consumable alternatives.
Technology:
Capital deployment patterns separate institutional adopters, with sequencing infrastructure requiring seven-figure investments while qPCR readouts accommodate constrained budgets.
- Next-Generation Sequencing:Genome-wide chromatin profiling via Illumina and Thermo Fisher platforms enables single-base-pair resolution mapping of protein-DNA interactions. NIH-funded consortia in the United States anchor demand through Roadmap Epigenomics Project mandates for comprehensive epigenomic atlases.
- qPCR:Targeted amplicon quantification remains viable for hypothesis-driven validation of specific binding sites in resource-limited settings.
- Microarray:Hybridization-based detection offers intermediate throughput for focused gene set analysis in older core facilities.
- Mass Spectrometry:Proteomic characterization of co-precipitated proteins extends ChIP applications toward interactome mapping.
Platform migration accelerates from array and qPCR foundations toward sequencing-centric architectures as library preparation costs decline.
Application:
Funding source differentiation shapes application demand, with federal research grants sustaining basic science while pharmaceutical sponsorship drives translational epigenomics.
- Epigenomics:Systematic mapping of histone modification landscapes and chromatin accessibility states across cell types and disease conditions. EMA qualification pathways for oncology companion diagnostics tighten analytical validation requirements for ChIP-based histone signatures in European pharmaceutical development programs.
- Disease Research:Mechanistic studies linking chromatin dysregulation to cancer, neurological disorders, and autoimmune pathologies attract venture-backed biotechnology investment.
- Gene Regulation:Transcription factor binding site identification supports regulatory network reconstruction.
- DNA-Protein Interaction:Fundamental biochemistry applications persist in academic structural biology departments.
Commercial sponsorship concentrates in disease-focused epigenomics while gene regulation maintains foundational academic support.
End User:
Procurement sophistication diverges across institutional categories, with contract research organizations demanding ISO 15189-compliant quality systems versus academic tolerance for protocol variability.
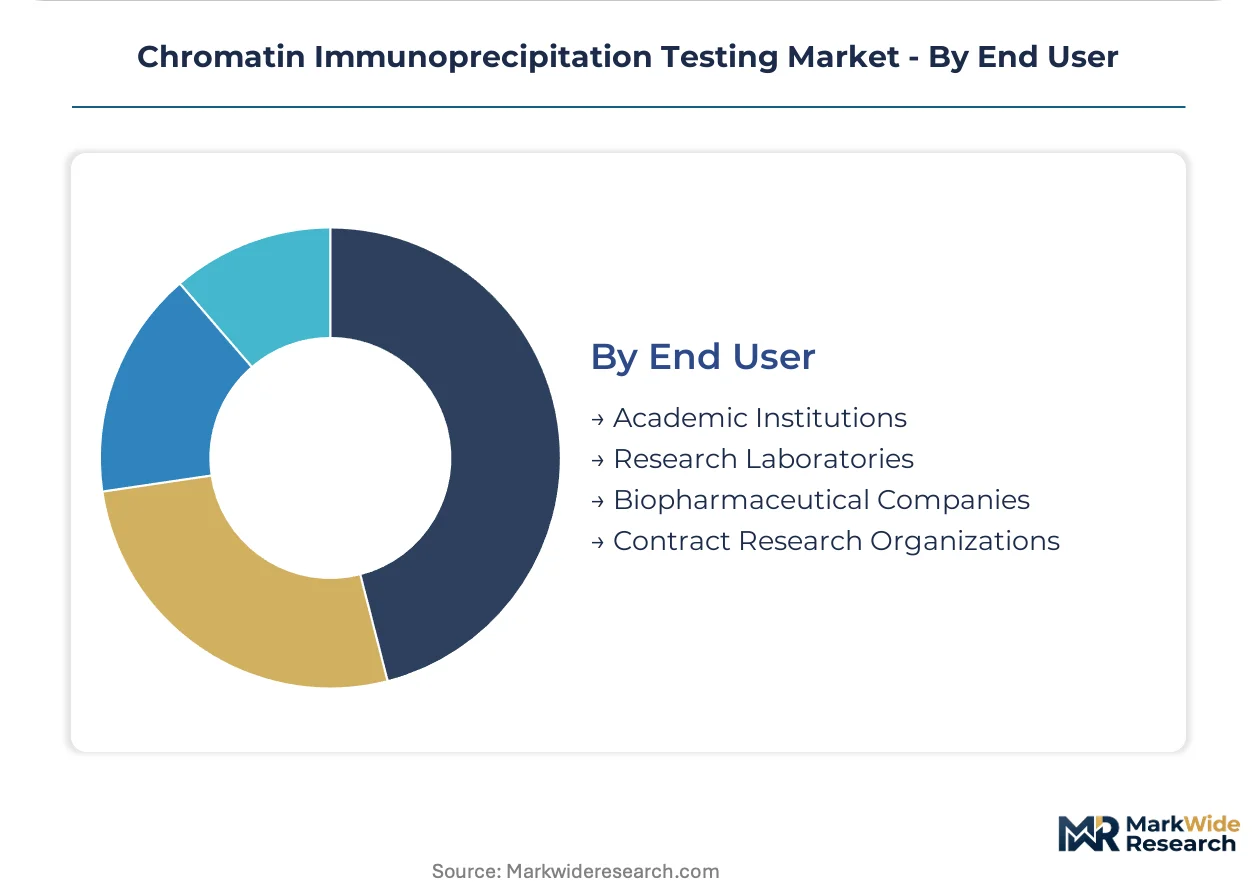
- Academic Institutions:University core facilities and medical school laboratories constitute the volume foundation for ChIP reagent consumption. Multi-investigator institutes in Germany and the United States centralize sequencing infrastructure through bundled reagent-and-service procurement models that displace standalone kit purchases.
- Contract Research Organizations:ISO 15189-accredited service providers perform regulated ChIP assays for pharmaceutical sponsors seeking biomarker qualification support. European CROs invest in CLIA-equivalent quality systems to capture EMA-directed epigenetic biomarker validation contracts.
- Biopharmaceutical Companies:Internal target validation groups maintain captive ChIP capabilities for proprietary epigenetic therapeutic programs.
- Research Laboratories:Government and nonprofit institutes operate between academic and commercial quality standards.
Outsourcing momentum favors CRO expansion as sponsors prioritize variable cost structures over fixed infrastructure maintenance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States-based reagent suppliers export ChIP-grade antibodies and sequencing-integrated kits to research institutes across Germany, Japan, and the United Kingdom, establishing transatlantic trade corridors in epigenomic research materials.
United States
NIH Roadmap Epigenomics Project funding sustains consumable demand at academic medical centers in Boston and San Francisco. FDA biomarker qualification frameworks shape companion diagnostic development pathways for ChIP-derived oncology signatures. The Greater Boston biotech corridor concentrates pharmaceutical sponsor investment in target validation studies.
Germany
Max Planck Institute networks and Helmholtz Association centers drive high-throughput chromatin mapping workflows in Munich and Heidelberg. EMA qualification guidance for epigenetic biomarkers tightens analytical validation standards for contract research organizations. The Munich biotech cluster anchors ISO 15189-accredited service provider expansion.
United Kingdom
Wellcome Trust and Cancer Research UK grants sustain core facility operations at Cambridge and Oxford. MHRA oversight of in vitro diagnostic regulations influences ChIP-based clinical assay development timelines. The Cambridge-London biotech corridor concentrates antibody validation and sequencing service provision.
Japan
AMED program funding and RIKEN institute mandates expand epigenomic research infrastructure in Tokyo and Osaka. PMDA consultation pathways for epigenetic companion diagnostics guide pharmaceutical sponsor assay development. The Kanto region anchors sequencing platform deployment at national research institutes.
Switzerland
Roche and Novartis pharmaceutical headquarters drive outsourced ChIP assay demand for proprietary therapeutic programs. Swissmedic medical device regulations shape quality system requirements for diagnostic kit commercialization. The Basel biotech cluster concentrates contract research provider investment.
Chromatin Immunoprecipitation Testing Market Competitive Environment
Channel-controlling players compete with product-specialist players across three discernible tiers. Thermo Fisher Scientific anchors sequencing-integrated platform ecosystems that bundle reagent supply with instrument access. Specialized antibody developers concentrate technical differentiation in histone modification targeting. Mid-scale reagent suppliers compete on protocol customization and regional service proximity. Dominant competitive moves include strategic partnerships between kit manufacturers and sequencing platform providers, plus geographic expansion of ISO-accredited contract research services.
Within the platform-integrated tier, Thermo Fisher Scientific Inc. anchors comprehensive ChIP-to-sequencing pipeline offerings. Among specialized antibody developers, Abcam plc and Cell Signaling Technology occupy positions defined by ChIP-grade certification and batch-to-lot consistency guarantees. These three entities exemplify the competitive tension between scale-driven platform ecosystems and technical-specialist positioning in epigenomic research supply.
| Leading Market Players |
|---|
| Abcam plc |
| Cell Signaling Technology |
| Thermo Fisher Scientific Inc. |
| Active Motif |
| BioLegend |
| Merck KGaA |
| Bio-Techne |
| Creative Diagnostics |
| Bio-Rad Laboratories |
| Others |
Value Chain & Pricing Dynamics
Antibody production concentration in the United States and Germany concentrates margin capture among specialized biotechnology suppliers, while sequencing platform bundling downstream redistributes pricing power toward integrated instrument manufacturers.
Pricing Analysis
qPCR-to-sequencing platform migration creates a three-tier pricing structure across premium, standard, and economy levels. ChIP-grade certified antibodies command premium positioning through ISO 15189 batch validation and lot-to-lot consistency guarantees, while economy consumables compete on volume scale for high-throughput academic screening. Pricing pressure stems from enzymatic fragmentation methods reducing per-sample reagent consumption as researchers adopt streamlined protocols. Academic core facilities exhibit highest price sensitivity due to grant-funded budget constraints, whereas biopharmaceutical sponsors prioritize analytical validation over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China complicates magnetic bead and specialized resin sourcing for DNA purification modules. Manufacturing concentrates in the United States, Germany, and Switzerland for ChIP-grade antibodies, while China and South Korea anchor sequencing consumable production. Raw material dependencies center on recombinant protein expression systems, synthetic histone peptides, and surface-modified magnetic beads. Single-source vulnerability persists for validated antibody clones where replacement qualification timelines extend development cycles. Distribution runs through academic core facility procurement offices in the United States and Germany, with direct sales teams serving biopharmaceutical accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue from protocol optimization and bioinformatics consultation expands faster than standalone kit sales as core facilities outsource technical troubleshooting to vendor specialists.
For Market Incumbents: Entrench platform ecosystem control by deepening sequencing instrument-reagent bundling that locks academic customers into multi-year supply agreements. Defend against cut-and-run protocol disruption by acquiring enzymatic fragmentation specialists and embedding these methods into certified workflow portfolios. Prioritize ISO 15189 accreditation investment to capture pharmaceutical sponsor outsourcing demand as regulatory validation requirements tighten. For New Entrants and Emerging Players: Pursue white-space opportunity in single-cell epigenomics reagent systems where droplet microfluidics convergence with ChIP protocols lacks established supply relationships. Target mid-scale European research institutes in the Netherlands and Sweden where centralized sequencing infrastructure creates bundled procurement entry points. Differentiate through technical consultation-heavy service models that compensate for absence of platform brand recognition. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed contract research organizations holding ISO 15189-accredited ChIP service capabilities but lacking sequencing platform integration. Long-term viability hinges on biomarker qualification pathway maturation under FDA and EMA frameworks for epigenetic companion diagnostics. Monitor EMA qualification guidance publication timelines as the critical inflection signal for service provider valuation expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Sequencing Platform Integration | Thermo Fisher anchors comprehensive ChIP-to-sequencing pipelines that consolidate reagent purchasing decisions. |
| Antibody Validation Certification | Abcam and Cell Signaling Technology compete through ChIP-grade batch consistency guarantees that reduce assay variability. |
| Contract Research Expansion | ISO 15189-accredited CROs capture pharmaceutical sponsor outsourcing as sponsors prioritize variable cost structures. |
| Enzymatic Protocol Development | Cut-and-run methods compress assay timelines and reduce sample input requirements for low-cell-number applications. |
| Companion Diagnostic Pathway Investment | FDA biomarker qualification frameworks create commercialization channels for ChIP-derived clinical assays in oncology. |
Study Parameters
A spread of perspectives from core facility directors, antibody product managers, pharmaceutical target validation scientists, and regulatory affairs specialists converged on the working assumptions underlying this analysis. Primary interviews combined with secondary validation from NIH funding databases, EMA qualification guidance documents, FDA biomarker submission records, and ENCODE consortium protocol standards. Bottom-up reagent volume estimates triangulated against top-down sequencing platform deployment data across the analysis window.
Demand-supply balance dynamics anchored the forecast framework across product type, technology platform, application focus, and end-user institutional category. CAGRs derived from segment-level growth trajectory analysis incorporating NIH Roadmap Epigenomics Project funding allocations, pharmaceutical R&D pipeline disclosures, and sequencing cost decline curves. Industry-specific inputs included antibody batch failure rates, core facility sample throughput benchmarks, and biomarker qualification timeline assumptions.
Sensitivities concentrate around federal research funding volatility, antibody validation standard evolution, and sequencing platform technology transitions. Forecasts reflect documented assumptions regarding enzymatic fragmentation adoption curves and pharmaceutical outsourcing propensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Bilirubin Colorimeter Assay Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Calprotectin Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Nucleic Acid Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Ready-To-Use Laboratory Test Kits Market
Testing Services
Global Extractables and Leachables Testing Services Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Global Medical Device Testing and Certification Market
Testing Services
Activated Partial Thromboplastin Test Market
Testing Services
Global Electronystagmography Testing Market
Testing Services
India GMP Testing Service Market
Testing Services
Pharmaceutical Dosage Form Testing Systems Market
Testing Services
Osmometer Market