
 Global Pipettes and Pipettors Market | 2026-2036
Global Pipettes and Pipettors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pipettes and Pipettors Market Foresight
Modular tip-rack bundling with electronic pipette platforms is hardening as the dominant procurement pattern for high-throughput pharmaceutical laboratories. Thermo Fisher Scientific leverages its integrated consumables ecosystem to lock in recurring revenue streams. Eppendorf sustains premium positioning through precision engineering and German manufacturing heritage. Sartorius competes by extending its bioanalytical instrumentation portfolio into automated pipetting workflows.
Pipettes and pipettors are precision liquid handling instruments that displace calibrated volumes through piston-driven air displacement or positive displacement mechanisms, with accuracy tolerances typically within one percent for Class A devices. Their primary commercial purpose centers on reproducible sample preparation across quantitative analytical chemistry, molecular biology, and clinical diagnostic protocols. Electronic pipettes command the strongest margin pools among product type segments due to motor-driven precision and programmable protocol storage, while multichannel configurations are capturing accelerated demand from 96-well and 384-well plate automation in pharmaceutical screening operations. Research laboratories anchor volume demand among end users, though clinical diagnostics represents the fastest-expanding addressable base as decentralized testing networks proliferate.
FDA 21 CFR Part 820 quality system regulations govern pipette manufacturing for US clinical applications, while EU IVDR and ISO 8655 calibration standards shape European market access and recertification cycles. EPA Good Laboratory Practice guidelines further constrain environmental testing protocols where traceable liquid handling validates analytical results. Stakeholders must monitor evolving harmonization between regional metrology standards and automated platform interoperability requirements.
Market Dynamics
Automated liquid handling platforms are compressing replacement cycles for mechanical pipettes while tightening vendor lock-in through integrated consumables ecosystems in pharmaceutical quality control laboratories.
Growth Catalysts
- EU IVDR compliance mandates:European diagnostic manufacturers face expanded metrological traceability requirements that accelerate recertification spending and replacement of non-compliant legacy equipment.
- CRISPR screening workflows:Gene editing research programs in contract research organizations drive multichannel pipette demand for 384-well plate processing at scale.
- German precision manufacturing:Concentrated engineering expertise in Baden-Württemberg and Saxony sustains premium positioning for ISO 8655-certified devices serving regulated pharmaceutical environments.
Market Restraints
- Platinum-iridium alloy volatility:Piston tip material costs fluctuate with precious metal markets, squeezing margin pools on precision air-displacement models.
- Single-source ceramic piston suppliers:Japanese and German specialty ceramics manufacturers create concentration risk for high-precision positive displacement mechanisms.
- ISO 8655 calibration burden:Mandatory annual recertification cycles impose recurring compliance costs that delay equipment refresh decisions in budget-constrained academic laboratories.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives attract contract assembly operations for electronic pipettes serving South Asian diagnostic networks.
- Point-of-care molecular diagnostics:Decentralized PCR testing infrastructure creates demand for battery-operated portable pipetting systems in rural clinic deployments.
- Cloud-connected calibration tracking:IoT-enabled pipettes integrating with laboratory information management systems enable predictive maintenance revenue streams.
Industry Challenges
- Cross-platform software interoperability:Proprietary protocol formats from competing automated workstation vendors fragment workflow standardization in high-throughput screening facilities.
- Metrology technician scarcity:Specialized calibration expertise for gravimetric verification procedures limits service capacity expansion in emerging diagnostic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pipettes and Pipettors Market |
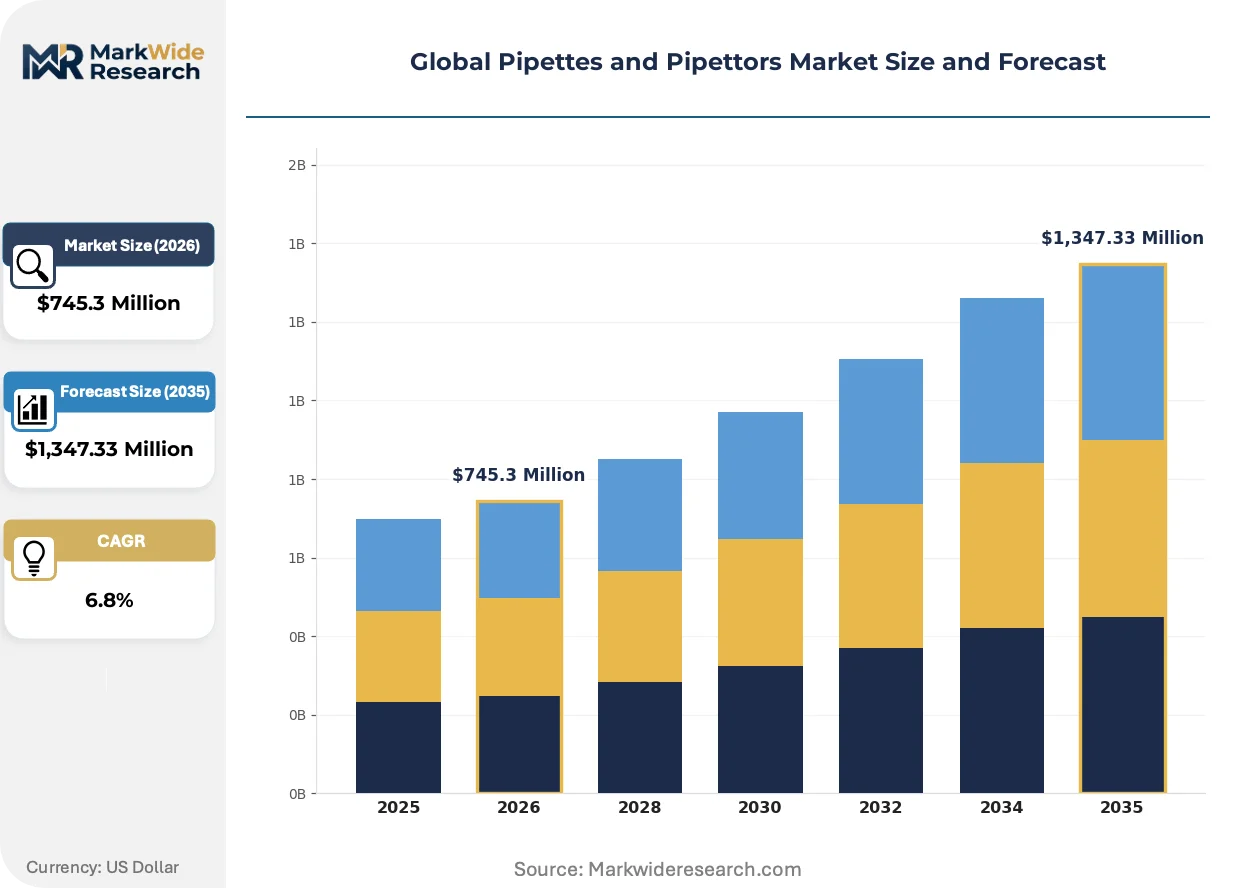
| Market Size in 2026 | $745.3 Million |
| Market Size in 2035 | $1,347.33 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electronic Pipettes, Manual Pipettes, Multichannel Pipettes, Disposable Pipettes End User: Research Laboratories, Pharmaceutical Companies, Clinical Diagnostics, Academic Institutions Volume Range: 5-10 µL, 10-100 µL, 100-1000 µL, 1-10 mL Distribution Channel: Online Retail, Direct Sales, Distributors, Specialty Stores |
| Companies Covered | Thermo Fisher Scientific, Eppendorf, Sartorius, Mettler Toledo, Hamilton Company, Brand GmbH + Co KG, Integra Biosciences, Gilson, Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pipettes and Pipettors Market Shifts & Advancements
Digital traceability and modular platform architectures are displacing standalone mechanical instruments across regulated laboratory environments, with vendor ecosystems becoming the primary competitive battleground.
Adaptive pipetting algorithms using pressure-based liquid level detection are integrating into next-generation electronic platforms. Contract development and manufacturing organizations in the United States and Germany adopt these systems to reduce protocol development time for complex sample matrices. This capability is integrating serendipitous error correction that previously required manual operator intervention, compressing training burdens in high-turnover laboratory staffing environments.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of lubricant coatings used in piston seals and O-rings. European manufacturers face supply chain requalification timelines of eighteen to twenty-four months for alternative fluoropolymer-free materials. Electronic pipette product lines with all-ceramic drive mechanisms bypass this constraint and command preference in EU member state procurement tenders.
Consolidated procurement through group purchasing organizations now dominates hospital system and academic consortium acquisitions in North America. Distributors respond by bundling calibration services and extended warranty programs to defend margin pools as equipment prices compress. This concentration is most visible in United States integrated delivery networks where standardization across dozens of affiliated laboratories overrides individual principal investigator preferences.
Global Pipettes and Pipettors Market Segmentation
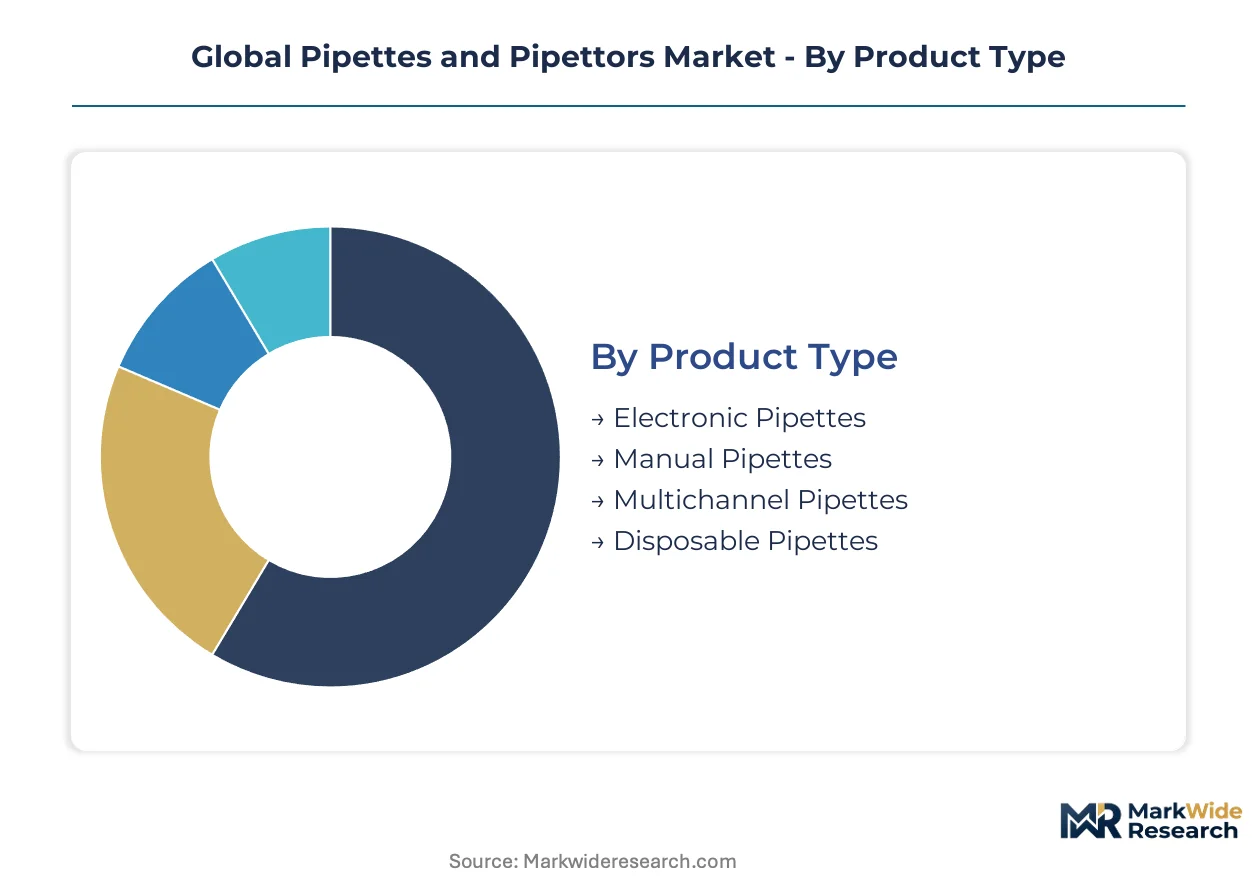
Pipettes and pipettors segment across precision tiers, end-use protocols, and procurement pathways that determine compliance burden and margin capture. Each dimension carries distinct certification requirements, from ISO 8655 gravimetric verification to FDA 21 CFR Part 820 quality system documentation. Understanding these splits enables targeted positioning across regulated pharmaceutical environments, high-throughput screening operations, and decentralized diagnostic networks.
Product Type:
ISO 8655 calibration standards apply universally across all mechanical variants, while electronic pipettes face additional IEC 61010 electrical safety certification and FDA 510(k) clearance for clinical diagnostic applications in the United States. EU IVDR traceability mandates weigh heaviest on positive displacement mechanisms used in infectious disease testing protocols.
- Electronic Pipettes:Motor-driven piston mechanisms with programmable protocol storage and adaptive liquid level detection. Demand concentrates in German pharmaceutical quality control laboratories where FDA 21 CFR Part 820 compliance and EU IVDR traceability requirements drive replacement of mechanical instruments. Recurring software validation costs and integrated consumables lock-in compress vendor switching.
- Manual Pipettes:Spring-loaded piston systems with adjustable volume dials and ergonomic grip profiles. Academic institutions in the United States dominate procurement volume, though ISO 8655 annual recertification burdens delay refresh cycles in budget-constrained research environments. Lightweight polymer construction reduces operator fatigue during high-repetition protocols.
- Multichannel Pipettes:Eight- and twelve-channel configurations for 96-well and 384-well plate processing. Contract research organizations in China deploy these for CRISPR screening workflows at scale.
- Disposable Pipettes:Single-use polystyrene or borosilicate glass instruments for contamination-sensitive applications. Point-of-care molecular diagnostics in rural Indian clinics drive volume expansion.
Leading the category by volume: Manual Pipettes. Growing fastest: Electronic Pipettes.
End User:
Cost tier stratification separates capital-intensive automated platform investments from maintenance-constrained academic procurement, with compliance spending as the primary differentiation lever.
- Research Laboratories:Principal investigator-driven purchasing with fragmented brand loyalty across molecular biology and analytical chemistry disciplines. United States National Institutes of Health grant funding cycles create lumpy replacement demand. Open-protocol electronic pipettes gain preference for multi-user environments with high technician turnover.
- Pharmaceutical Companies:Integrated liquid handling workstations with vendor-locked consumables ecosystems. German manufacturing clusters in Baden-Württemberg anchor supply relationships for ISO 8655-certified precision instruments. Quality control laboratories prioritize gravimetric traceability documentation for FDA inspection readiness.
- Clinical Diagnostics:Decentralized PCR testing networks and hospital central laboratories. India's PLI scheme for medical devices attracts contract assembly for South Asian diagnostic procurement.
- Academic Institutions:Group purchasing organization consolidation in North American university systems. Extended warranty and bundled calibration services defend distributor margins against equipment price compression.
Research Laboratories anchor absolute volume. Clinical Diagnostics climbs the fastest on decentralized testing infrastructure buildout.
Volume Range:
Application specificity determines specification clustering, with nucleic acid protocols and protein assays driving divergent precision requirements across the microliter-to-milliliter spectrum.
- 5-10 µL:Ultra-low volume positive displacement mechanisms for PCR master mix preparation and next-generation sequencing library construction. Genomics core facilities in the United States and Germany concentrate demand. Ceramic piston architectures bypass REACH-restricted lubricant coatings.
- 10-100 µL:The workhorse specification for ELISA workflows and cell culture media formulation. Pharmaceutical screening operations in China absorb volume at scale.
- 100-1000 µL:Sample dilution and reagent preparation in environmental testing laboratories. EPA Good Laboratory Practice guidelines constrain gravimetric verification protocols.
- 1-10 mL:Bulk liquid handling for cell banking and bioprocessing applications. Contract development and manufacturing organizations prioritize ergonomic designs for repetitive large-volume transfers.
10-100 µL commands the largest installed base. 5-10 µL gains share fastest on genomics workflow expansion.
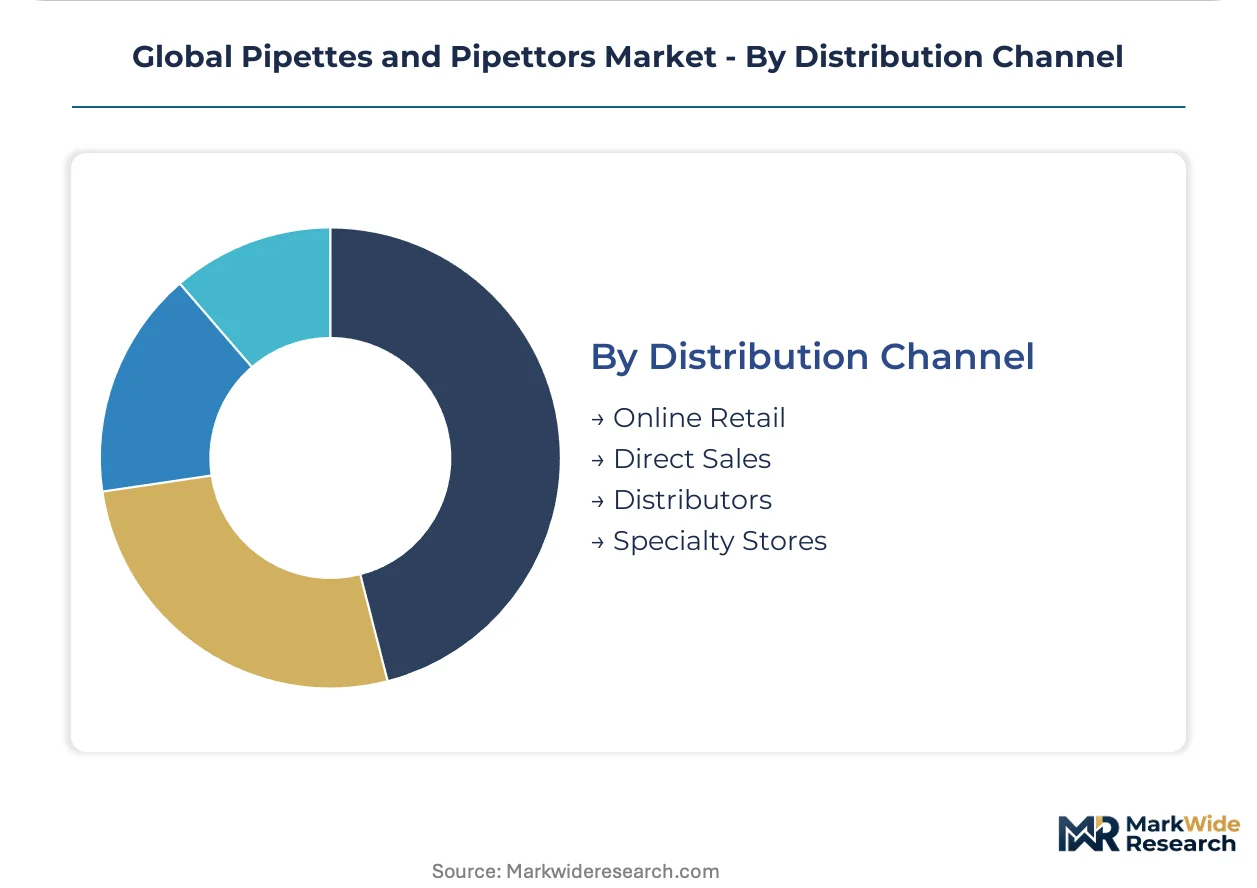
Distribution Channel:
Customer type fragmentation—individual principal investigators versus consolidated procurement departments—shapes channel viability and service bundling requirements.
- Direct Sales:Enterprise agreements with pharmaceutical manufacturers and diagnostic instrument OEMs. Field application scientists provide on-site protocol optimization and IQ/OQ/PQ qualification documentation.
- Distributors:Multi-brand portfolios with value-added calibration and repair services. United States integrated delivery networks leverage GPO-negotiated pricing across affiliated hospital laboratories.
- Online Retail:E-commerce platforms serving small research groups and startup biotechnology companies. Standardized SKUs and rapid fulfillment compete on convenience rather than technical consultation.
- Specialty Stores:Regional laboratory supply cooperatives with localized inventory and same-day delivery for urgent reagent preparation needs.
Distributors lead by transaction volume. Direct Sales expands most quickly on pharmaceutical automation platform integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures precision instruments for export while the United States and China absorb the highest consumption volumes. Production clusters concentrate where ISO 8655 calibration infrastructure and precision engineering traditions intersect.
United States
Pharmaceutical quality control laboratories drive demand for electronic pipettes with FDA 21 CFR Part 820 documentation. EPA Good Laboratory Practice guidelines constrain gravimetric verification protocols for environmental testing workflows. Greater Boston and the San Francisco Bay Area anchor genomics research clusters deploying multichannel systems for CRISPR screening.
Germany
Baden-Württemberg and Saxony sustain premium manufacturing for ISO 8655-certified devices serving regulated European pharmaceutical environments. EU IVDR traceability mandates accelerate recertification spending across diagnostic instrument OEMs. Eppendorf leverages precision engineering heritage to maintain positioning in high-margin electronic pipette segments.
China
Contract research organizations deploy multichannel pipettes at scale for pharmaceutical screening operations. NMPA regulations increasingly align with international quality system standards for clinical diagnostic applications. Shanghai and Suzhou industrial parks concentrate automated liquid handling platform assembly for domestic and export markets.
India
Point-of-care molecular diagnostics in rural clinics drive demand for portable battery-operated pipetting systems. The PLI scheme for medical devices attracts contract assembly operations for electronic pipettes serving South Asian diagnostic networks. Maharashtra and Karnataka host emerging manufacturing clusters for decentralized PCR testing infrastructure.
Japan
Specialty ceramics manufacturers supply precision piston components for positive displacement mechanisms. METI industrial standards support high-reliability instrument production for regional diagnostic markets. Tokyo-Osaka corridor maintains concentration of metrology expertise for gravimetric verification services.
Global Pipettes and Pipettors Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across precision tiers. The vendor base stratifies into three layers: integrated life science platforms with consumables ecosystems, German precision engineering houses with manufacturing heritage, and emerging Asian assemblers leveraging cost-positioned electronic variants. Dominant competitive moves include vertical integration into specialty ceramics supply chains and cloud-connected calibration service bundling.
Within the integrated platform tier, Thermo Fisher Scientific and Sartorius exemplify the consumables-lock-in model through bundled tip-rack procurement. Eppendorf occupies a position as the precision-engineering archetype, leveraging German manufacturing concentration to sustain premium positioning in regulated pharmaceutical environments. These three anchors represent contrasting pathways: ecosystem breadth, precision heritage, and bioanalytical workflow extension.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Eppendorf |
| Sartorius |
| Mettler Toledo |
| Hamilton Company |
| Brand GmbH + Co KG |
| Integra Biosciences |
| Gilson |
| Corning Incorporated |
| Others |
Supply & Pricing Matrix
REACH restrictions on per- and polyfluoroalkyl substances gate qualified supply for piston seal lubricants and premium-tier pricing access for EU-certified electronic pipettes, forcing eighteen-to-twenty-four-month requalification timelines that concentrate margin capture among ceramic-drive specialists.
Pricing Analysis
Price erosion across manual pipette tiers traces to group purchasing organization consolidation in United States academic systems, compressing equipment margins while bundled calibration services defend distributor profitability. Three-tier pricing structure across premium ISO 8655-certified electronic, standard mechanical multichannel, and economy disposable variants differentiates on gravimetric traceability documentation and after-sales service bundling. Cost-down pressure on mechanical instruments accelerates because automated liquid handling platforms displace standalone units in pharmaceutical quality control laboratories. Academic institutions exhibit highest price sensitivity due to NIH grant cycle lumpiness, while German pharmaceutical manufacturers prioritize certification compliance over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle pharmaceutical automation platform demand, while distributor networks with value-added calibration services serve fragmented academic procurement. Manufacturing concentrates in Germany for precision engineering, China for automated platform assembly, and Japan for specialty ceramic piston components. Platinum-iridium alloy and fluoropolymer-free lubricant coatings constitute critical input dependencies. Single-source vulnerability pervades Japanese and German specialty ceramics suppliers for positive displacement mechanisms. Distribution runs through consolidated group purchasing organizations in North American hospital systems and direct enterprise agreements with pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around automated platform ecosystems and consumables lock-in, with EU IVDR compliance mandates and REACH reformulation requirements forcing weaker mechanical-only players toward exit or acquisition.
For Market Incumbents: Deepen backward integration into specialty ceramics supply chains to secure positive displacement piston capacity against Japanese supplier concentration risk. Expand cloud-connected calibration service bundling to pharmaceutical quality control laboratories, creating predictive maintenance revenue streams that resist price compression from group purchasing organizations.
For New Entrants and Emerging Players: Launch via India's PLI scheme for medical devices to capture contract assembly demand for battery-operated portable pipetting systems serving South Asian point-of-care molecular diagnostics networks. Target rural clinic deployments with ergonomic lightweight polymer designs that bypass REACH-restricted lubricant dependencies.
For Investors and Strategic Acquirers: NMPA alignment with international quality system standards is the leading indicator that Chinese contract research organization demand for multichannel systems will sustain premium-tier volume expansion. Five-to-ten-year viability favors precision engineering specialists with ISO 8655 certification infrastructure and ceramic-drive product lines. Watch for gravimetric verification service capacity expansion in emerging diagnostic markets as the inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Connected Calibration Service Launch | IoT-enabled pipettes integrating with laboratory information management systems create recurring revenue streams. |
| Ceramic Drive Mechanism Product Line Expansion | All-ceramic architectures bypass REACH-restricted lubricant coatings and command preference in EU procurement tenders. |
| PLI Scheme Manufacturing Footprint Establishment | Domestic assembly in Maharashtra and Karnataka captures South Asian decentralized PCR testing infrastructure demand. |
| Automated Platform Integration Partnership | Thermo Fisher Scientific and Sartorius demonstrate consumables-lock-in models that compress vendor switching. |
| Gravimetric Verification Service Capacity Buildout | Specialized metrology technician scarcity in emerging markets limits service expansion for ISO 8655 recertification cycles. |
Research Methodology
Multi-period observation of pharmaceutical automation adoption rates, EU IVDR recertification spending patterns, and REACH reformulation timelines anchored the trend analysis, supplemented by interviews with laboratory equipment procurement managers, biomedical engineers at genomics core facilities, GPO contracts managers in United States integrated delivery networks, and field application scientists at precision instrument manufacturers. Secondary validation drew from FDA 510(k) filings, EPA Good Laboratory Practice guidelines, ISO 8655 calibration standard documentation, and NMPA quality system alignment notices. Bottom-up segment sizing triangulated against top-down pharmaceutical R&D expenditure allocation models.
Input-output matrices mapped electronic pipette unit demand to automated liquid handling platform installations, manual instrument refresh cycles to NIH grant award patterns, and disposable pipette consumption to point-of-care molecular diagnostics deployment across the projection horizon. Segmentation dimensions modeled include product type precision tier, end-user compliance burden, volume range application specificity, and distribution channel consolidation pattern. CAGRs derived from regression analysis against pharmaceutical screening throughput expansion and decentralized testing infrastructure buildout, with cross-validation against ceramic piston supply capacity and metrology service availability.
Regulatory harmonization delays, precious metal price volatility, and metrology technician training bottlenecks are the dominant revision risks to forecast trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Laboratory Pulverizer Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
US Cath Labs Market
Laboratory Equipment
Laboratory Supplies Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
ASEAN Laboratory Equipment Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Laboratory Refrigerators and Ovens Market
Laboratory Equipment
Hemostasis Analyzers Market
Laboratory Equipment
Blood Volume Analyzer Market
Laboratory Equipment
Pipettes and Accessories Market
Laboratory Equipment
Laboratory Vacuum Drying Oven Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Global Blood Gas Analyzers Market