
 Global Sterility Testing Market | 2026-2036
Global Sterility Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Sterility Testing Market Foresight
Traditional culture-based media is rebalancing toward rapid microbial methods as polymerase chain reaction and flow cytometry platforms cut detection timelines from fourteen days to under forty-eight hours. Charles River Laboratories leverages its biologics testing network to anchor sterility services across North American and European pharmaceutical corridors. Merck KGaA sustains competitive positioning through integrated membrane filtration product lines that span consumables through automated workflow systems. bioMérieux SA differentiates via diagnostics-to-pharma technology transfer, applying clinical microbiology expertise to industrial sterility applications.
Sterility testing comprises validated analytical procedures designed to detect viable microorganisms in pharmaceuticals, biologics, medical devices, and cell therapy products, with membrane filtration requiring pore sizes of 0.45 micrometers or less per pharmacopeial standards. The primary purpose is to verify absence of contaminating bacteria, fungi, and mycoplasma before product release or during in-process control. Rapid microbial methods are capturing disproportionate investment as pharmaceutical manufacturers seek real-time release paradigms for perishable biologics. Culture-based testing still occupies the largest revenue pool due to regulatory familiarity and compendial acceptance, though automated systems are narrowing the validation gap through enhanced data integrity features.
The FDA enforces sterility requirements under 21 CFR 211 for finished pharmaceuticals, while the EMA's Annex 1 revision mandates contamination control strategies that elevate sterility testing to quality system centrality. China's NMPA aligns with pharmacopeial harmonization initiatives, accelerating local adoption of rapid methods for domestic biologics export readiness. ISO 14698 provides cleanroom monitoring frameworks that upstream sterility assurance programs. Stakeholders must weigh validation investment against regulatory inspection precedent as agencies calibrate enforcement intensity between innovation encouragement and patient safety assurance.
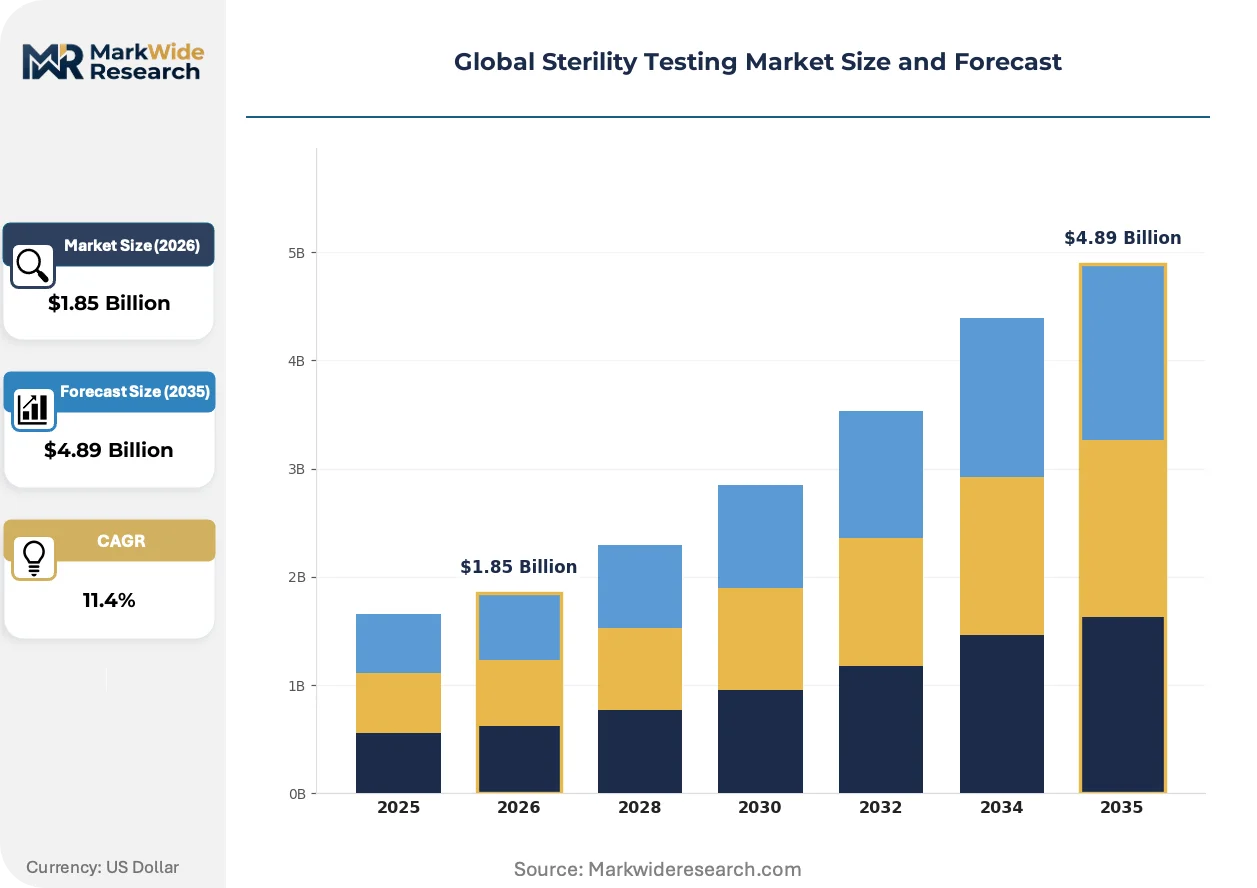
Market Dynamics
Cell and gene therapy commercialization is forcing sterility testing infrastructure to compress fourteen-day detection windows into same-day release decisions, rewiring capital allocation across pharmaceutical quality control networks.
Growth Catalysts
- 21 CFR 211 Enforcement:FDA inspections are intensifying for finished pharmaceutical sterility, compelling manufacturers to validate rapid microbial methods ahead of license renewals.
- Biologics Manufacturing Concentration:Germany, the United States, and China host expanding cell therapy production corridors that require continuous in-process sterility monitoring.
- Flow Cytometry Platforms:Automated cell-counting technologies are cutting detection timelines to under forty-eight hours for perishable gene therapy vectors.
Market Restraints
- Validation Cost Burden:Method transfer from culture-based protocols to rapid systems demands eighteen-to-twenty-four-month qualification timelines with no revenue offset.
- Consumables Supply Concentration:Membrane filtration media production clusters in Western European chemical manufacturing corridors, exposing buyers to single-source risk.
- Compendial Acceptance Lag:Pharmacopeial standards in major jurisdictions still privilege growth-based detection, creating regulatory friction for alternative technologies.
Strategic Opportunities
- EMA Annex 1 Revision:Contamination control strategy mandates are elevating sterility testing to quality system centrality, opening consulting and validation service revenue pools.
- China NMPA Harmonization:Domestic biologics export readiness programs are accelerating rapid method adoption among contract manufacturers in Jiangsu and Zhejiang provinces.
- PCR-Fluorescence Convergence:Polymerase chain reaction platforms integrating real-time fluorescence detection are enabling same-shift release for autologous cell therapies.
Industry Challenges
- Microbiology Talent Scarcity:Industrial sterility validation requires hybrid skill sets spanning classical microbiology, automation engineering, and data integrity compliance that command premium compensation.
- Legacy LIMS Integration:Rapid microbial method data streams must interface with decade-old laboratory information management systems without triggering audit trail gaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Sterility Testing Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Membrane Filtration, Direct Inoculation, Media Fill, Rapid Microbial Methods, Automated Systems Application: Pharmaceuticals, Biopharmaceuticals, Medical Devices, Vaccines, Cosmetics End User: Pharmaceutical Manufacturers, Contract Research Organizations, Diagnostic Laboratories, Quality Control Units, Biotech Companies Technology: Culture-Based Testing, Polymerase Chain Reaction, Flow Cytometry, Spectroscopy, Immunoassay Techniques |
| Companies Covered | Charles River Laboratories, Merck KGaA, bioMérieux SA, Sartorius AG, Thermo Fisher Scientific, SGS SA, Sotera Health, STERIS Plc, WuXi AppTec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Sterility Testing Market Shifts & Advancements
Real-time release paradigms are compressing traditional quality control timelines from weeks to hours, forcing infrastructure reinvestment across pharmaceutical manufacturing networks.
Automated membrane filtration workstations are consolidating sterility testing workflows by integrating sample preparation, incubation, and imaging into single-platform configurations. Biopharmaceutical contract manufacturers in the United States and Germany are deploying these systems to handle rising cell therapy volumes without proportional headcount expansion. Platform consolidation is compressing laboratory footprint requirements and reducing cross-contamination risk through closed-system architecture.
EMA's Annex 1 revision mandates contamination control strategies that elevate environmental monitoring to sterility assurance centrality. Pharmaceutical manufacturers must now demonstrate continuous viable particle control across Grade A and B cleanroom zones with documented intervention risk assessments. European biologics facilities are responding by deploying continuous air sampling systems linked to building management platforms for real-time excursion alerts.
Biopharmaceutical procurement teams are unbundling sterility testing from bundled quality control contracts to secure method-specific expertise for cell therapy programs. Large molecule developers are shifting from full-service quality agreements to discrete rapid microbial method validations with specialized providers. This pattern is most visible in Massachusetts and North Carolina biotech clusters where gene therapy developers prioritize speed-to-clinic over integrated service relationships.
Global Sterility Testing Market Segmentation
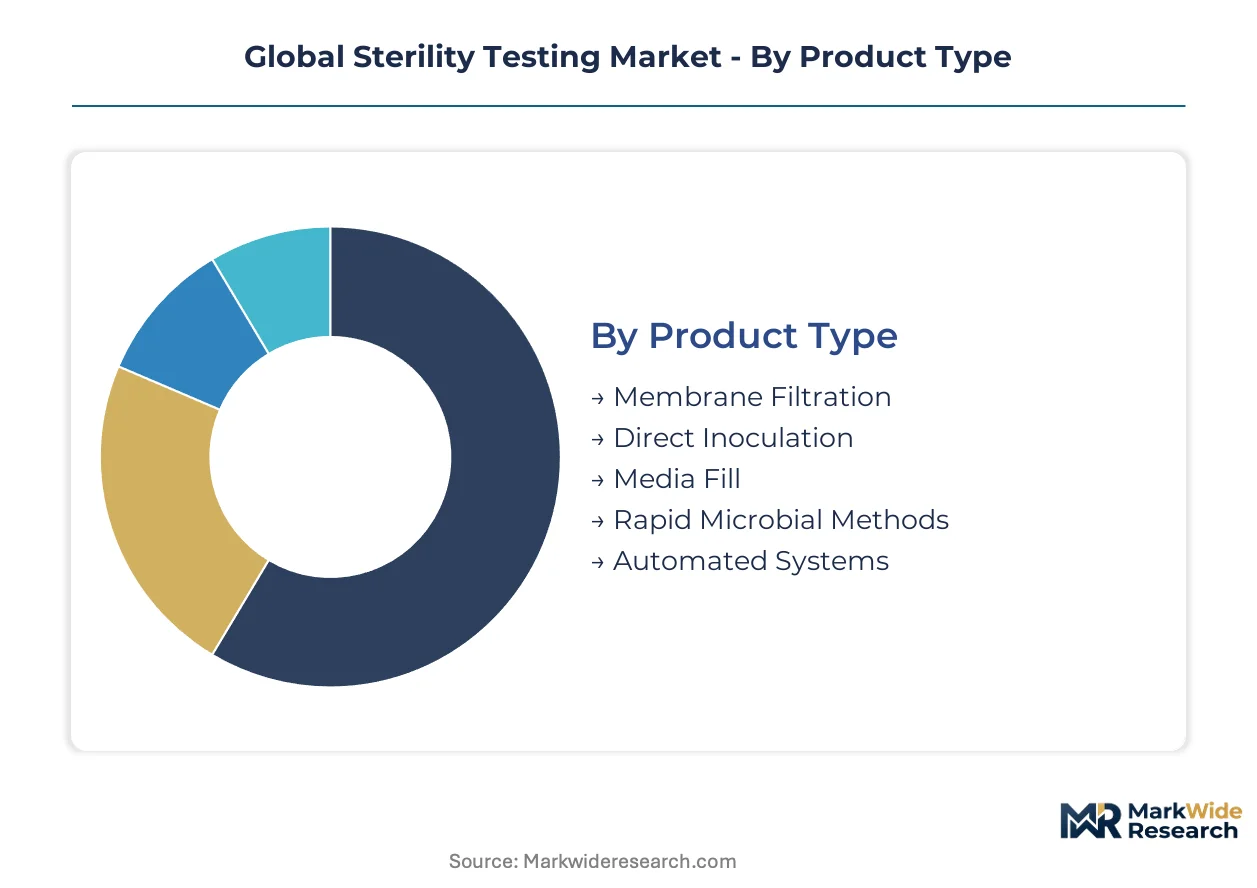
Sterility testing infrastructure must align with product perishability, regulatory jurisdiction, and manufacturing scale. Segmentation reveals where capital concentrates and which technologies command premium validation investment.
Product Type:
Customization intensity varies from standardized consumables to integrated automation platforms requiring site-specific qualification protocols.
- Membrane Filtration:Pore sizes of 0.45 micrometers or less trap microorganisms on filter surfaces for transfer to growth media. Demand concentrates in German and United States parenteral drug manufacturing corridors where pharmacopeial compliance is non-negotiable.
- Rapid Microbial Methods:Polymerase chain reaction and flow cytometry platforms compress detection timelines from fourteen days to under forty-eight hours. Cell and gene therapy developers in Massachusetts and North Carolina biotech clusters prioritize these for real-time release paradigms.
- Direct Inoculation:Sample introduction into liquid culture media remains prevalent for small-volume parenterals.
- Media Fill:Aseptic process simulations validate manufacturing environments through microbial growth promotion.
- Automated Systems:Robotic sample handling reduces operator intervention risk in high-throughput quality control laboratories.
Most installed capacity flows through membrane filtration. Expansion is steepest in rapid microbial methods.
Application:
Margin structures diverge sharply between commoditized medical device testing and complex biologics validation requiring extended method development.
- Biopharmaceuticals:Monoclonal antibodies, recombinant proteins, and gene therapy vectors demand specialized mycoplasma and viral detection protocols. Facilities in Jiangsu and Zhejiang provinces are scaling rapid method adoption for export readiness.
- Pharmaceuticals:Small-molecule parenterals and ophthalmic preparations require compendial sterility assurance with documented environmental monitoring integration.
- Medical Devices:Implantable and sterile surgical instruments follow ISO standards with lower per-test complexity.
- Vaccines:Live-attenuated and mRNA platforms require matrix-specific validation to distinguish product from contaminant signal.
- Cosmetics:Preservative efficacy testing and sterile product claims follow regional pharmacopeial variations with lighter regulatory burden.
Biopharmaceuticals command the highest testing fees per batch. Vaccines are gaining share fastest as mRNA manufacturing scales.
End User:
Customer sophistication ranges from integrated pharmaceutical quality departments to outsourced specialists managing multi-client method portfolios.
- Pharmaceutical Manufacturers:In-house quality control units at large molecule developers maintain captive sterility laboratories for release testing and stability protocols.
- Contract Research Organizations:Charles River Laboratories and specialized providers offer validated rapid microbial methods for gene therapy developers prioritizing speed-to-clinic.
- Diagnostic Laboratories:Clinical microbiology expertise transfers to industrial applications through technology platform adaptation.
- Quality Control Units:Embedded manufacturing site laboratories handle in-process and finished product release.
- Biotech Companies:Emerging cell therapy developers outsource sterility validation to avoid eighteen-to-twenty-four-month qualification timelines.
Pharmaceutical manufacturers retain the largest testing volume. Contract research organizations are expanding most quickly as outsourcing accelerates.
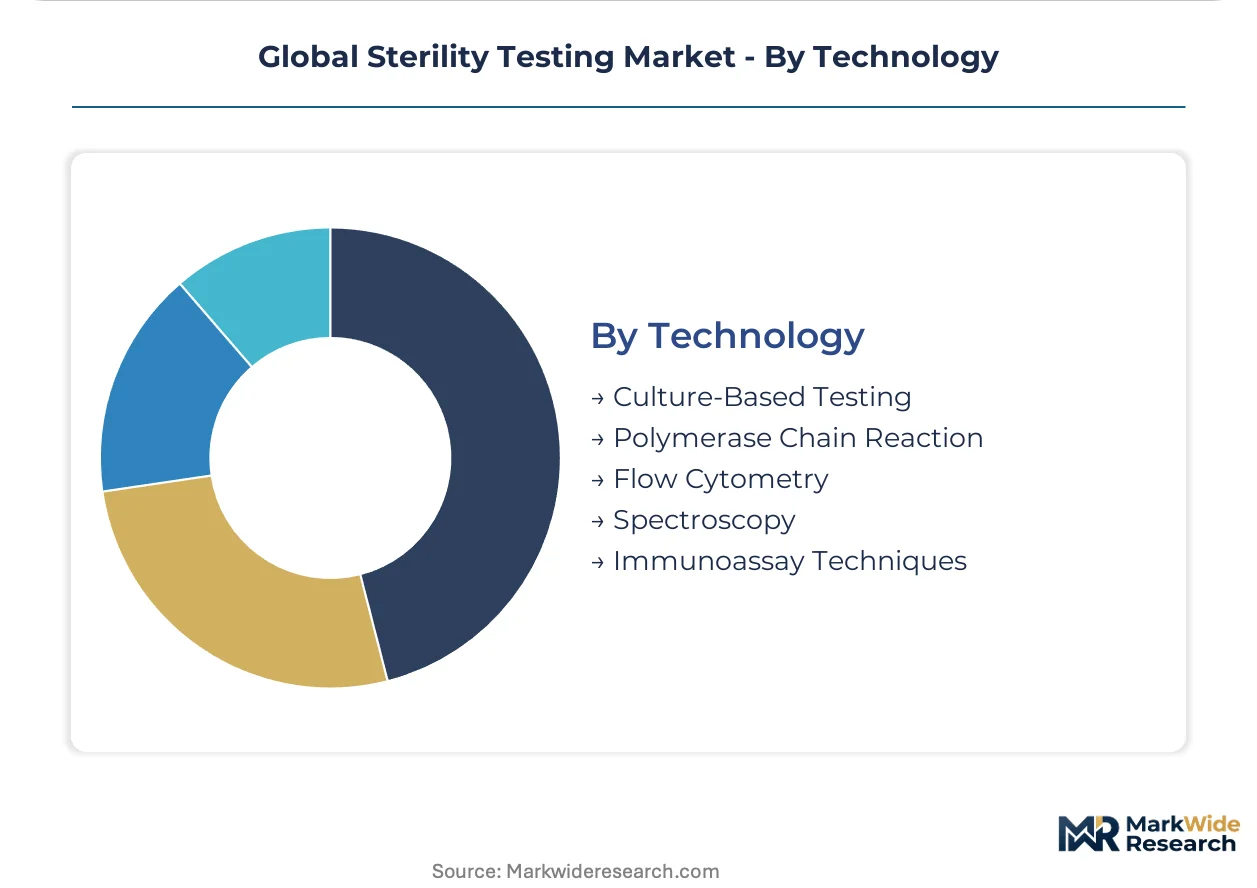
Technology:
Technology maturity spans century-old culture methods to same-shift molecular detection platforms requiring extensive validation investment.
- Culture-Based Testing:Growth-dependent detection remains the regulatory reference standard despite fourteen-day incubation requirements. EMA and FDA inspections continue to privilege compendial familiarity.
- Polymerase Chain Reaction:Nucleic acid amplification enables same-shift release for autologous cell therapies with fluorescence detection integration.
- Flow Cytometry:Automated cell-counting technologies deliver under-forty-eight-hour detection windows for perishable gene therapy vectors.
- Spectroscopy:Raman and infrared methods detect metabolic activity without growth-dependent lag phases.
- Immunoassay Techniques:Antigen-based detection targets specific microbial contaminants with reduced time-to-result.
Culture-based testing dominates installed base. Polymerase chain reaction is climbing the fastest as FDA rapid method guidance accelerates technology transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Massachusetts biotech corridor anchors global sterility testing demand as cell therapy developers compress release timelines from fourteen days to under forty-eight hours. Germany's membrane filtration manufacturing base supplies validated consumables across European pharmaceutical networks. China's NMPA harmonization initiatives accelerate rapid method adoption in Jiangsu and Zhejiang export zones.
United States
FDA's 21 CFR 211 enforcement intensifies sterility validation requirements for finished pharmaceuticals ahead of license renewals. The agency's rapid microbial method guidance accelerates technology transitions from culture-based protocols. Massachusetts and North Carolina biotech clusters deploy flow cytometry platforms for same-day release of perishable gene therapy vectors.
Germany
EMA's Annex 1 revision mandates contamination control strategies elevating environmental monitoring to quality system centrality. German membrane filtration manufacturers supply 0.45 micrometer pore-size media meeting pharmacopeial standards across European corridors. Bavarian and North Rhine-Westphalian facilities integrate automated workstations handling rising cell therapy volumes without proportional headcount expansion.
China
NMPA alignment with international pharmacopeial harmonization accelerates rapid method adoption for domestic biologics export readiness. Jiangsu and Zhejiang contract manufacturers scale PCR-fluorescence platforms to meet European and United States import requirements. Shanghai and Suzhou clusters concentrate quality control infrastructure serving multinational pharmaceutical outsourcing contracts.
Switzerland
Swissmedic maintains stringent sterility assurance requirements for biologics manufacturing under European regulatory convergence. Basel and Zurich pharmaceutical corridors host integrated quality control laboratories serving monoclonal antibody and recombinant protein production. Swiss facilities pioneer real-time release paradigms linking automated membrane filtration to building management platforms.
India
CDSCO's alignment with ICH guidelines positions Indian contract manufacturers for global biologics supply chain integration. Maharashtra and Gujarat pharmaceutical zones expand sterility testing capacity for generic injectable exports to regulated markets. Hyderabad and Mumbai clusters attract rapid microbial method validations from emerging cell therapy developers seeking cost-competitive quality control.
Global Sterility Testing Market Competitive Landscape
Global majors compete with regional champions across technology platform breadth and geographic service density. The vendor base separates into three tiers: integrated life science conglomerates spanning consumables through automated systems, specialized contract research organizations offering validated rapid methods, and regional quality control service providers. Consolidation pressure intensifies as cell therapy developers unbundle testing from full-service contracts to secure method-specific expertise. Dominant competitive moves include portfolio diversification into adjacent contamination control technologies and strategic partnerships linking rapid method platforms to real-time release software.
Within the integrated conglomerate tier, Charles River Laboratories and Thermo Fisher Scientific exemplify geographic network density across North American and European pharmaceutical corridors. Merck KGaA occupies a position bridging membrane filtration consumables with automated workflow systems. bioMérieux SA represents the diagnostics-to-pharma technology transfer archetype, applying clinical microbiology platforms to industrial sterility applications.
| Leading Market Players |
|---|
| Charles River Laboratories |
| Merck KGaA |
| bioMérieux SA |
| Sartorius AG |
| Thermo Fisher Scientific |
| SGS SA |
| Sotera Health |
| STERIS Plc |
| WuXi AppTec |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up contract research organizations have consolidated sterility testing capacity across North American and European pharmaceutical corridors, tightening pricing discipline through portfolio breadth while feeding supply chain concentration into membrane filtration media sourcing.
Pricing Analysis
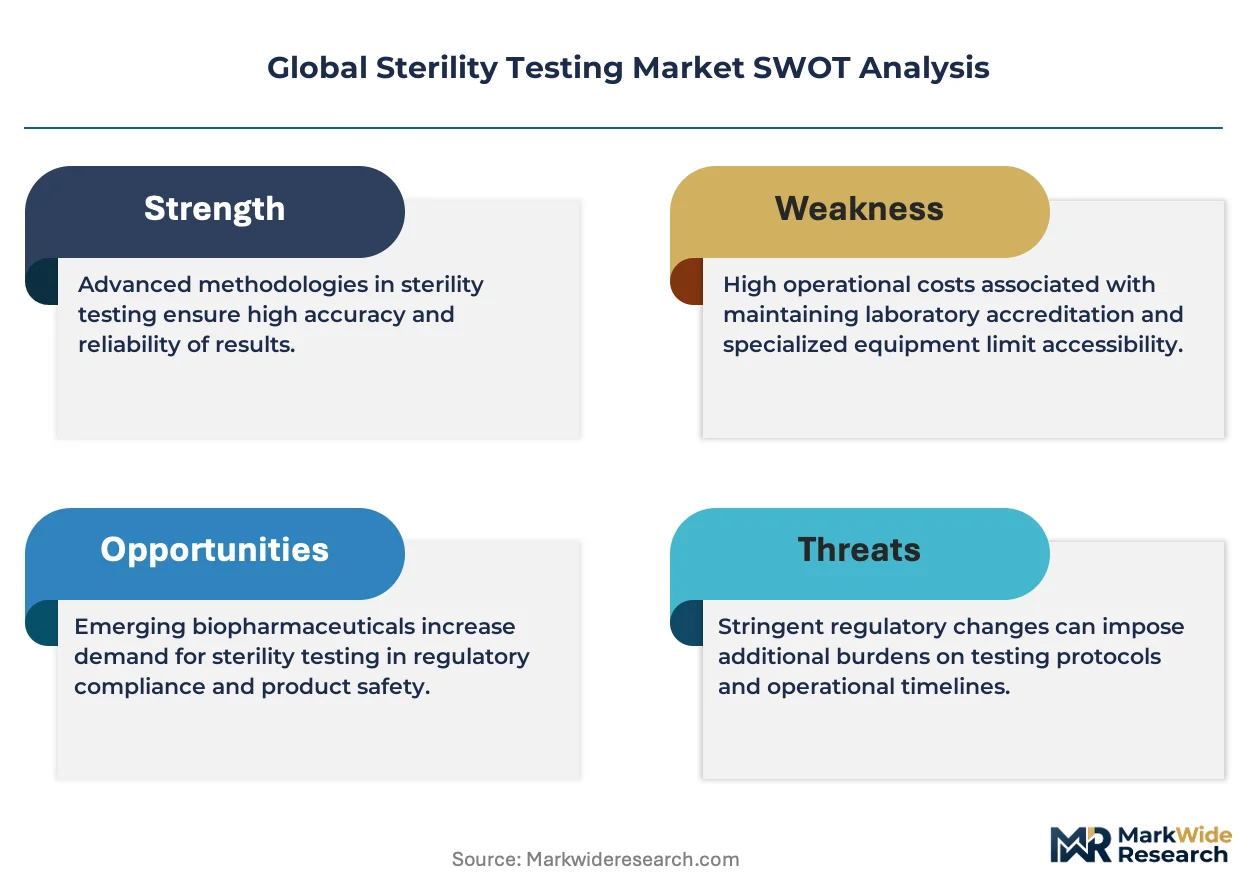
Input-cost pass-through from specialty cellulose ester and polyethersulfone membrane suppliers anchors pricing structures in the sterility testing market. Three-tier pricing structure across premium, standard, and economy levels separates validated rapid microbial method platforms from automated membrane filtration workstations and basic consumable kits. Cost compression in standard-tier consumables is intensifying because Chinese contract manufacturers are scaling membrane production for export readiness. Emerging cell therapy developers in Massachusetts and North Carolina biotech clusters show least price sensitivity, prioritizing same-day release capabilities over per-test economics.
Supply Chain Analysis
Membrane filtration media supply rests on German and United States specialty chemical producers, with Chinese manufacturers rapidly scaling capacity for domestic biologics export programs. Key inputs span validated 0.45 micrometer pore-size membranes, gamma-irradiated packaging materials, and PCR reagent chemistries. Single-source vulnerability concentrates in Western European chemical manufacturing corridors where specialized polymer production clusters. Distribution runs through direct OEM partnerships for automated platforms and regional distributors for high-volume consumables serving contract manufacturing organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: rapid microbial method validation costs in China run substantially below United States and European levels while NMPA harmonization unlocks export access to regulated markets.
For Market Incumbents: Extend rapid microbial method platform portfolios through targeted acquisition of PCR-fluorescence specialists in Jiangsu and Zhejiang provinces. Charles River Laboratories and Thermo Fisher Scientific should anchor capacity additions in these Chinese export zones before local champions consolidate regional expertise. Certification investment in EMA Annex 1 contamination control strategy consulting offers defensive moat against pure-play automation vendors. For New Entrants and Emerging Players: Mid-sized gene therapy developers with sub-$500 million valuation represent the most penetrable buyer archetype for specialized rapid method validation services. These developers prioritize speed-to-clinic over integrated relationships and unbundle testing from full-service quality contracts. A focused go-to-market angle centers on same-shift release guarantees for autologous cell therapy vectors, bypassing incumbent fourteen-day culture-based protocols. For Investors and Strategic Acquirers: Valuations sit cheapest among regional quality control service providers with captive rapid method expertise but limited geographic footprint. Long-term viability over the next decade hinges on successful technology transfer from diagnostics-to-pharma applications and regulatory navigation across FDA, EMA, and NMPA jurisdictions. The signal to watch is FDA inspection precedent on rapid microbial method equivalence determinations, which will either accelerate or stall capital deployment into alternative detection platforms.| Strategic Initiative | Industry Significance |
|---|---|
| PCR-Fluorescence Platform Integration | Enables same-shift release for autologous cell therapies in Massachusetts and North Carolina clusters. |
| EMA Annex 1 Consulting Services | Captures contamination control strategy mandates elevating sterility testing to quality system centrality. |
| Backward Integration into Membrane Production | Reduces single-source exposure to German and United States specialty chemical suppliers. |
| Jiangsu-Zhejiang Capacity Expansion | Positions for NMPA harmonization-driven rapid method adoption among export-oriented contract manufacturers. |
| Automated Workstation Deployment | Consolidates sample preparation, incubation, and imaging for cell therapy volume scaling without headcount expansion. |
Research Methodology
Bottom-up biopharmaceutical manufacturing modeling reconciled against top-down membrane filtration and rapid method platform tracking forms the analytical core of this study. Primary interviews with quality control directors, regulatory affairs leads at gene therapy developers, contract manufacturing organization procurement managers, and EMA inspection consultants combined with secondary validation from FDA guidance documents, EMA Annex 1 revision texts, NMPA harmonization notices, and pharmacopeial standard updates. Triangulation across these sources anchored market sizing and growth trajectory assessments.
Historical trendline analysis of culture-based versus rapid microbial method adoption rates informed projection frameworks across the analysis window. Segmentation dimensions modeled include product type, application, end user, and technology platform maturity, with regional regulatory cluster variations capturing FDA, EMA, and NMPA enforcement intensity differentials. CAGRs derived from installed base expansion curves, replacement cycle dynamics, and perishability-driven release timeline compression in cell and gene therapy manufacturing.
Underlying measurement precision varies by segment; rapid microbial methods carry tighter precision than established culture-based testing due to discrete platform deployment tracking. Forecasts reflect assumptions on regulatory equivalence determination timelines and cell therapy commercialization velocity. A small set of triggers warrants ongoing watch: FDA rapid method guidance enforcement precedent, EMA Annex 1 inspection interpretation consistency, and Chinese export readiness program acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
Rapid Antigen Testing Market
Testing Services
Esoteric Testing Market
Testing Services
Lipase Testing Reagents Market
Testing Services
INR Test Meter Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Nipah Virus (Niv) Infection Testing Market
Testing Services
Europe Newborn Screening Market
Testing Services
Hemostasis Testing Systems Market
Testing Services
Phenytoin Testing Market
Testing Services
Employer and Workplace Drug Testing Market
Testing Services
Paediatric and Neonatal Testing Kits Market
Testing Services
India GMP Testing Service Market
Testing Services
Gamma Glutamyl Transferase Testing Market
Testing Services
Allergy Tester Market
Testing Services
Europe Point-Of-Care-Testing (POCT) Market