
 Solid Phase Extraction Market | 2026-2036
Solid Phase Extraction Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Phase Extraction Market Outlook
Direct distribution to pharmaceutical quality control labs is tilting as vendors build specialized e-commerce portals for consumables. Thermo Fisher Scientific dominates cartridge supply through its integrated chromatography platform. Biotage anchors its position with automated SPE workstations that reduce solvent consumption. Waters Corporation leverages its mass spectrometry installed base to pull through proprietary sorbent formats.
Solid phase extraction employs selective sorbent materials packed into cartridges, plates, or columns to isolate target analytes from liquid matrices using adsorption and elution cycles, typically operating with particle sizes of 10 to 60 micrometers and pore structures engineered for specific analyte classes. The technique serves as a front-end purification step for chromatographic analysis in regulated testing environments. Cartridges command the largest volume share due to their compatibility with manual and automated workflows across pharmaceutical research. Disks are gaining traction in environmental analysis where large-volume water sampling demands faster flow rates and reduced clogging.
The US FDA bioanalytical guidance and EMA ICH Q2(R1) revisions are elevating method validation standards for extraction recovery and matrix effect control, forcing vendors to supply certificate-of-analysis documentation with every batch. EPA Method 525 and ISO 17025 accreditation requirements in contract laboratories are standardizing sorbent performance benchmarks for environmental and food safety testing. Stakeholders must monitor how regulatory convergence between FDA and EMA on analytical procedure lifecycle management reshapes sorbent qualification protocols and procurement specifications.
Market Dynamics
Regulatory convergence between FDA and EMA on analytical procedure lifecycle management is compressing sorbent qualification timelines and forcing vendors to restructure batch documentation workflows. This structural pressure is reshaping procurement specifications across pharmaceutical quality control operations.
Growth Catalysts
- Bioanalytical method validation standards:FDA and EMA ICH Q2(R1) revisions mandate tighter extraction recovery benchmarks, compelling contract laboratories to upgrade SPE infrastructure.
- Environmental monitoring protocols:EPA Method 525 and ISO 17025 accreditation requirements standardize sorbent performance for water testing applications.
- Contract research organization expansion:Germany's dedicated sample preparation centers concentrate demand for automated SPE workstations and high-throughput cartridge formats.
Market Restraints
- Specialty sorbent supply concentration:Bonded-phase silica production clusters in select chemical manufacturing regions, exposing buyers to input volatility.
- Capital intensity of automation:Automated SPE workstations require substantial upfront investment, limiting adoption among mid-sized testing laboratories.
- Alternative extraction technologies:QuEChERS and dispersive liquid-liquid microextraction methods compete for food safety and environmental applications.
Strategic Opportunities
- Underpenetrated biologics segment:Protein A and immunoaffinity sorbents for monoclonal antibody purification represent nascent demand in bioprocessing workflows.
- Point-of-care diagnostic integration:Miniaturized SPE cartridges for dried blood spot analysis enable decentralized clinical testing infrastructure.
- Green chemistry mandates:EU Green Deal solvent reduction targets favor sorbent formats that minimize organic solvent consumption during elution cycles.
Industry Challenges
- Analytical chemist shortage:Method development expertise for complex matrix interference resolution remains scarce in contract testing laboratories.
- Legacy chromatography platform integration:Proprietary cartridge formats from major vendors create switching friction for laboratories with established workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Phase Extraction Market |
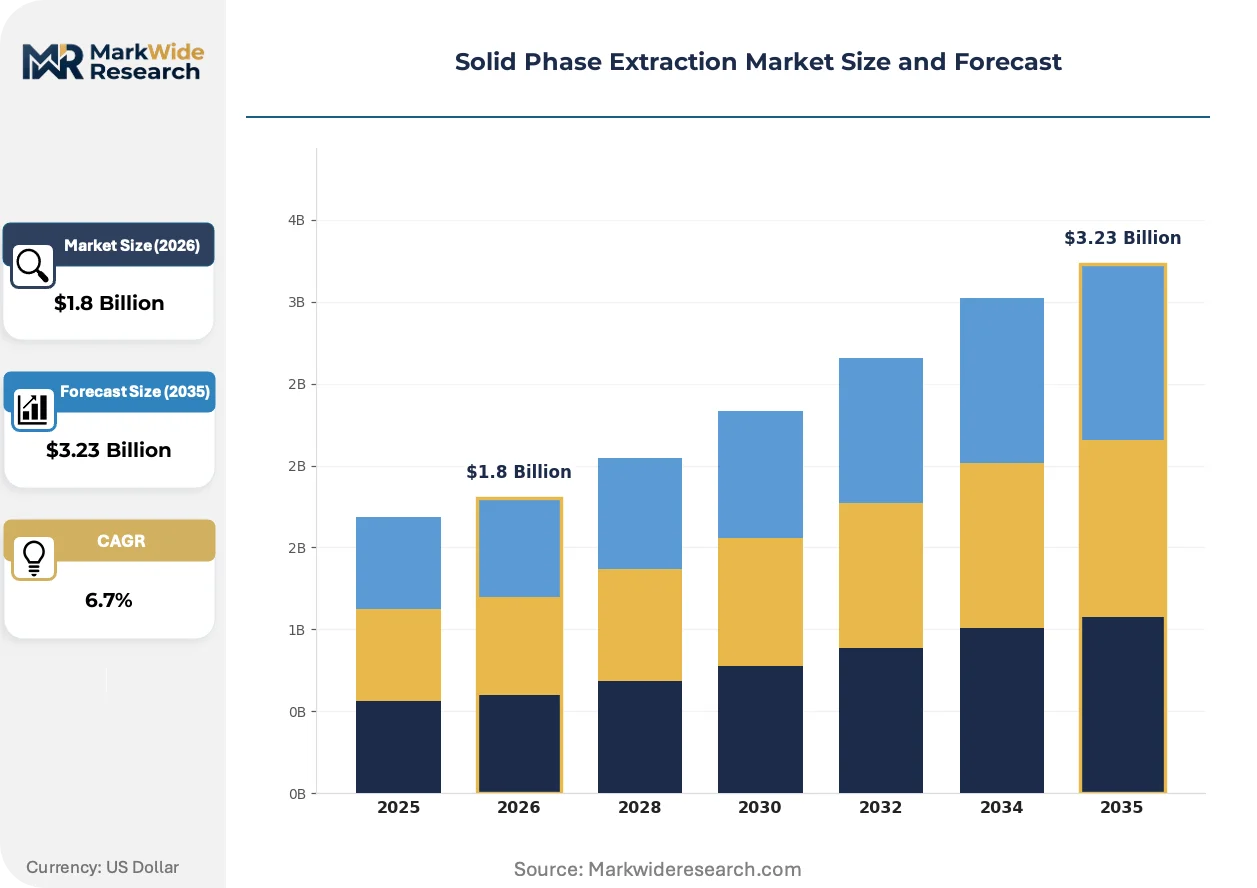
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cartridges, Plates, Columns, Disks Application: Environmental Analysis, Food Safety, Clinical Diagnostics, Pharmaceutical Research End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Environmental Agencies Material: Polymers, Silica Gel, Activated Carbon, Organic Solvents |
| Companies Covered | PerkinElmer Inc., Biotage, Agilent Technologies, Inc., Phenomenex Inc., Restek Corporation, Thermo Fisher Scientific Inc., Merck KGaA, GL Sciences Inc., Waters Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Phase Extraction Market Strategic Shifts
SPE technology is pivoting toward automation compatibility and solvent minimization as laboratories face simultaneous pressure to increase throughput and meet sustainability targets. These shifts are reconfiguring vendor R&D priorities and customer procurement criteria.
Monolithic sorbent structures with through-pore architectures are rendering obsolete traditional packed-bed cartridges in high-throughput pharmaceutical screening. Large-molecule drug developers in the United States and Germany are adopting these formats to reduce backpressure and accelerate method development cycles. The structural consequence is compressing margins on conventional particle-based offerings.
REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of fluorinated sorbents used in environmental and food safety applications. European manufacturers must phase out PFAS-containing bonded phases by specified deadlines, redirecting R&D investment toward hydrocarbon and polymer alternatives. Environmental contract laboratories in Germany and France are accelerating qualification of replacement chemistries.
Direct-to-laboratory e-commerce portals for consumables are displacing traditional distributor relationships in pharmaceutical quality control procurement. Thermo Fisher Scientific and specialized vendors now transact cartridge replenishment through proprietary digital platforms that integrate with laboratory information management systems. This channel shift is most pronounced in the United States, where integrated chromatography platform users prioritize seamless reordering workflows.
Solid Phase Extraction Market Segmentation
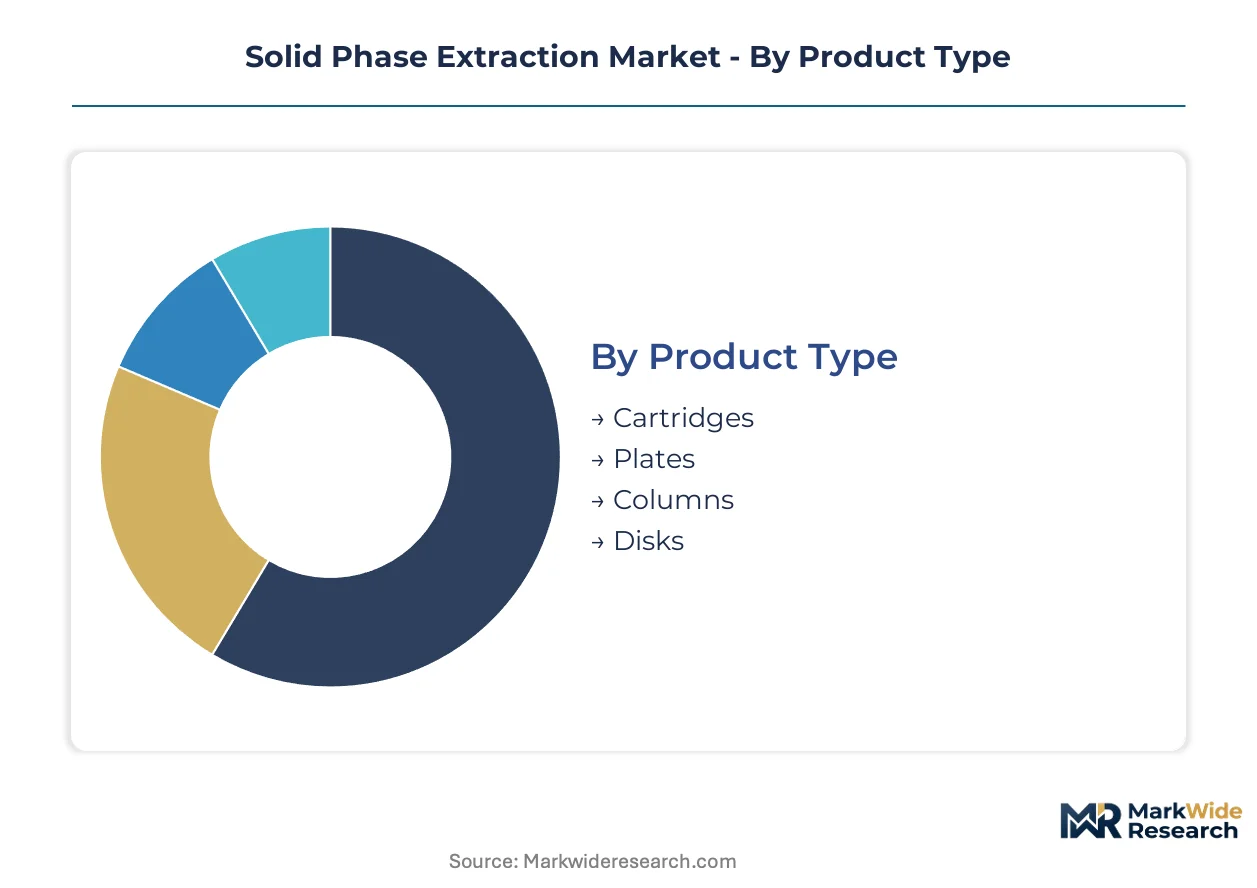
Solid phase extraction markets fragment across four structural dimensions that dictate procurement cycles and margin profiles. Product format determines automation compatibility and per-unit economics. Application verticals impose divergent regulatory compliance burdens. Understanding these segment boundaries clarifies where vendor R&D investments concentrate versus where price competition dominates.
Product Type:
Cartridge formats turn over fastest in high-throughput pharmaceutical screening, while column installations persist for years in validated analytical workflows.
- Cartridges:Disposable polypropylene or glass housings packed with 10-60 micrometer sorbent particles, designed for single-use extraction cycles. Pharmaceutical quality control labs in Germany and the United States consume the highest volumes as FDA bioanalytical method validation guidelines mandate fresh cartridges for each sample batch to eliminate cross-contamination risk.
- Plates:96-well formats enabling parallel processing of multiple samples on automated liquid handling platforms. Contract research organizations building dedicated sample preparation centers favor plate-based workflows for bioanalytical studies where throughput directly correlates with revenue capacity.
- Columns:Reusable stainless steel or PEEK housings for preparative-scale purification. Bioprocessing facilities employ larger-diameter columns for monoclonal antibody capture steps where sorbent lifetime justifies cleaning validation costs.
- Disks:Membrane-based formats with embedded sorbent particles offering reduced flow resistance. Environmental monitoring stations processing large-volume water samples specify disks to minimize clogging from particulate-laden matrices.
Cartridges anchor the volume base while disks gain share at the steepest rate in environmental applications demanding faster flow processing.
Application:
Regulatory stringency varies dramatically across verticals, with pharmaceutical and clinical segments bearing the heaviest documentation requirements.
- Environmental Analysis:Surface water, groundwater, and wastewater testing for trace contaminants. EPA Method 525 and ISO 17025 accreditation requirements in contract laboratories standardize sorbent performance benchmarks for persistent organic pollutant detection.
- Food Safety:Pesticide residue and mycotoxin screening in agricultural commodities. European reference laboratories under EFSA oversight drive adoption of QuEChERS-compatible sorbent formats for multi-residue methods.
- Clinical Diagnostics:Therapeutic drug monitoring and biomarker quantification from biological matrices. Hospital laboratories in the United States integrate miniaturized SPE cartridges into dried blood spot workflows for decentralized testing infrastructure.
- Pharmaceutical Research:Impurity profiling, pharmacokinetic studies, and forced degradation analysis. ICH Q2(R1) revisions compel method developers to demonstrate extraction recovery consistency across batch-to-batch sorbent variability.
Pharmaceutical research commands the highest average selling prices while clinical diagnostics expands most quickly through point-of-care integration.
End User:
Procurement sophistication stratifies sharply between capital-rich pharmaceutical operators and budget-constrained academic facilities.
- Academic Institutions:University chemistry and environmental science departments with episodic grant-funded purchases. Method development flexibility outweighs throughput requirements, favoring manual cartridge formats over automated platforms.
- Research Laboratories:Government and private analytical facilities with standardized operating procedures. These buyers negotiate annual framework agreements with vendors supplying certificate-of-analysis documentation for every sorbent batch.
- Pharmaceutical Companies:Quality control and bioanalytical departments with validated chromatography platforms. Integrated supply contracts with Thermo Fisher Scientific and Waters Corporation lock in proprietary cartridge formats that resist switching.
- Environmental Agencies:National and regional monitoring networks with high-volume, price-sensitive procurement. These operators prioritize disk formats and bulk sorbent purchases to minimize per-sample costs across thousands of routine analyses.
Pharmaceutical companies dominate revenue concentration while environmental agencies represent the highest unit-volume opportunity with compressed margins.
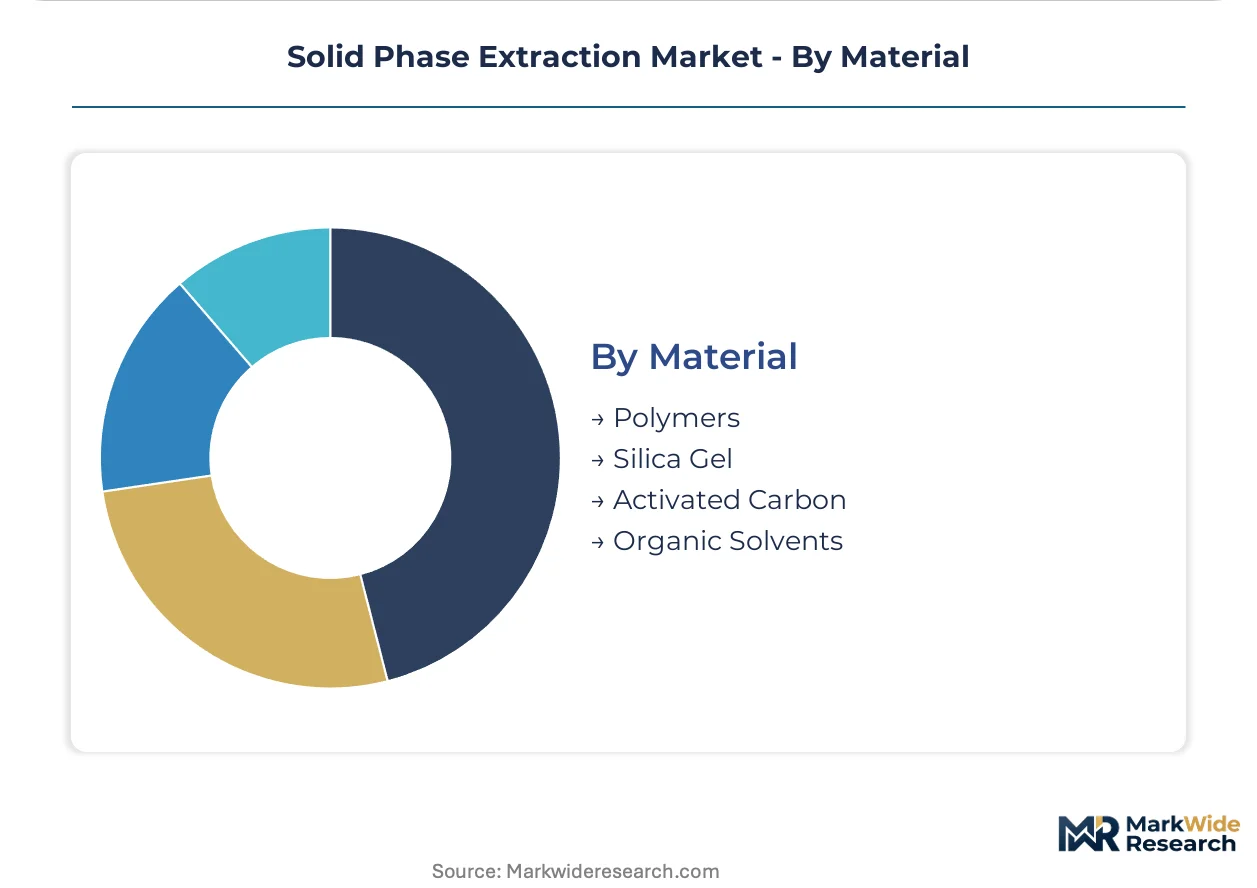
Material:
Sorbent chemistry selection determines extraction selectivity, with bonded-phase silica facing substitution pressure from polymer alternatives.
- Polymers:Hydrophilic-lipophilic balance and mixed-mode ion exchange resins offering pH stability across 1-14 range. Biologics manufacturers specify polymer sorbents for protein and peptide purification where silica dissolution would compromise recovery.
- Silica Gel:C18, C8, and polar-embedded bonded phases manufactured from high-purity silica substrates. Traditional reversed-phase separations in pharmaceutical quality control remain dependent on silica-based sorbents with established retention characteristics.
- Activated Carbon:High-surface-area carbonaceous materials for non-polar contaminant adsorption. Water utilities deploy carbon-packed cartridges for taste and odor compound removal in drinking water treatment applications.
- Organic Solvents:Methanol, acetonitrile, and ethyl acetate employed as conditioning and elution media. EU Green Deal solvent reduction targets are redirecting method development toward aqueous-compatible polymer sorbents that minimize organic consumption.
Silica gel retains the largest installed base while polymers climb the fastest as biologics processing scales and green chemistry mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical logistics infrastructure underwrites Europe's sorbent import capacity, while direct rail links from Shanghai to Duisburg compress delivery timelines for bonded-phase silica raw materials.
United States
FDA bioanalytical method validation guidelines tighten extraction reproducibility requirements for pharmaceutical quality control labs. EPA Method 525 mandates standardized sorbent performance for environmental contract laboratories. Greater Boston's biotech cluster concentrates demand for automated SPE workstations in pharmacokinetic studies.
Germany
Contract research organizations are building dedicated sample preparation centers that concentrate procurement of high-throughput cartridge formats. REACH restrictions on per- and polyfluoroalkyl substances force reformulation of fluorinated sorbents by specified deadlines. The Rhine-Main region's pharmaceutical manufacturing corridor anchors demand for certificate-of-analysis documentation with every batch.
China
NMPA alignment with ICH Q2(R1) revisions elevates method validation standards for domestic pharmaceutical exporters. Dual carbon goals redirect R&D investment toward aqueous-compatible polymer sorbents that minimize organic solvent consumption. Yangtze River Delta analytical service providers scale disk-based formats for large-volume water sampling.
Japan
PMDA oversight of bioanalytical studies drives adoption of fresh cartridges per sample batch to eliminate cross-contamination risk. METI green chemistry initiatives favor sorbent formats with reduced elution solvent requirements. Kansai region contract laboratories integrate miniaturized SPE into dried blood spot workflows.
India
CDSCO tightening of analytical procedure validation compels upgrade of SPE infrastructure in generic pharmaceutical manufacturing. BIS accreditation requirements for testing laboratories standardize sorbent performance benchmarks. Hyderabad-Visakhapatnam pharmaceutical corridor concentrates demand for C18 bonded-phase silica in impurity profiling.
Solid Phase Extraction Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the cartridge and sorbent supply layer. The vendor base arranges into three concentration zones: chromatography platform owners with captive SPE formats, independent consumables manufacturers with broad distribution, and regional chemical suppliers with commodity bonded phases. Two competitive moves dominate: direct-to-laboratory e-commerce portal construction, and automated workstation integration with laboratory information management systems.
Among diversified laboratory technology conglomerates, Thermo Fisher Scientific Inc., Agilent Technologies, Inc., and Waters Corporation exemplify the platform-integrated archetype. These entities leverage installed chromatography and mass spectrometry bases to pull through proprietary consumable formats. Biotage occupies a distinct position as a workstation-centric specialist with automated SPE systems that reduce solvent consumption. PerkinElmer Inc. and Merck KGaA represent the diversified analytical reagents tier with cross-portfolio presence in sample preparation. Phenomenex Inc., Restek Corporation, and GL Sciences Inc. sit within the independent chromatography consumables specialist category, supplying sorbent chemistries across multiple instrument platforms.
| Leading Market Players |
|---|
| PerkinElmer Inc. |
| Biotage |
| Agilent Technologies, Inc. |
| Phenomenex Inc. |
| Restek Corporation |
| Thermo Fisher Scientific Inc. |
| Merck KGaA |
| GL Sciences Inc. |
| Waters Corporation |
| Others |
Value Chain & Pricing Dynamics
The Port of Rotterdam's chemical logistics infrastructure compresses bonded-phase silica import costs while amplifying price differentiation between pharmaceutical-grade and environmental-testing sorbent tiers. Freight rate volatility on Asia-Europe routes feeds directly into procurement negotiations for contract research organizations balancing certificate-of-analysis documentation costs against volume-discount thresholds.
Pricing Analysis
Volume-discount tiering separates pharmaceutical quality control labs purchasing integrated chromatography platform cartridges from environmental agencies procuring bulk disk formats. Certification-grade sorbents with batch-specific documentation command premium positioning, while commodity C18 bonded phases face cost compression from polymer alternatives. Price erosion runs through standard-grade silica cartridges as REACH-driven PFAS reformulation redirects R&D budgets toward hydrocarbon replacements. Academic institutions exhibit highest price sensitivity; bioprocessing facilities demonstrate lowest sensitivity due to cleaning validation cost avoidance.
Supply Chain Analysis
Upstream feedstock concentration for high-purity silica substrates centers on Germany, China, and the United States, with bonded-phase manufacturing clustering in the Rhine-Main and Yangtze River Delta regions. Production draws from organosilane coupling agents, high-purity methanol, and specialized polypropylene housing resins. Single-source vulnerability persists in fluorinated bonded-phase chemistry ahead of REACH phase-out deadlines. Distribution runs through direct-to-laboratory e-commerce portals displacing traditional distributor relationships in pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory convergence between FDA and EMA on analytical procedure lifecycle management constitutes a high-growth disruption, compressing sorbent qualification timelines and forcing infrastructure upgrades across contract testing networks.
For Market Incumbents: Insulate proprietary cartridge format lock-in by deepening integration with laboratory information management systems and accelerating automated workstation deployment. Defend against polymer sorbent substitution by investing in aqueous-compatible silica reformulations that satisfy EU Green Deal solvent reduction mandates. Prioritize certificate-of-analysis digitization to compress batch documentation workflows.
For New Entrants and Emerging Players: Build out miniaturized SPE cartridge capabilities for dried blood spot workflows in decentralized clinical diagnostics, the most penetrable segment given point-of-care infrastructure expansion. Target biologics manufacturers with protein A and immunoaffinity sorbent offerings where incumbent coverage remains thin. Pursue direct e-commerce channel establishment to bypass established distributor relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified analytical reagents conglomerates seeking to divest non-core sample preparation assets. Long-term viability favors vendors with captive sorbent chemistry development and automated platform integration. Monitor NMPA alignment with ICH Q2(R1) revisions as the signal indicating accelerated infrastructure spend by Chinese pharmaceutical exporters.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated SPE Workstation Deployment | Reduces solvent consumption while satisfying EPA Method 525 throughput requirements for environmental contract laboratories. |
| PFAS-Free Sorbent Reformulation | Addresses REACH restrictions forcing European manufacturers to phase out fluorinated bonded phases by specified deadlines. |
| Direct-to-Laboratory E-Commerce Portal | Integrates with LIMS platforms to capture pharmaceutical quality control cartridge replenishment from traditional distributors. |
| Monolithic Sorbent Architecture Development | Compresses backpressure in high-throughput pharmaceutical screening applications across Greater Boston biotech clusters. |
| Biologics-Specific Affinity Sorbent Launch | Captures monoclonal antibody purification demand in bioprocessing workflows where protein A chemistry dominates. |
Study Parameters
The analysis maps sorbent chemistry tiers, product format categories, and application verticals, each validated through analytical chemists, pharmaceutical quality control managers, environmental contract laboratory directors, and chromatography platform engineers. Primary interview findings were cross-referenced against FDA bioanalytical guidance documents, EMA ICH Q2(R1) revision texts, EPA Method 525 protocols, and ISO 17025 accreditation standards. Bottom-up segment sizing and top-down market triangulation were applied to reconcile vendor shipment data with end-user procurement patterns.
Assumptions regarding regulatory timeline adherence, raw material cost trajectories, and automation adoption curves were held fixed across baseline scenarios while stress-testing sensitivity to REACH enforcement intensity and NMPA implementation pace. Segmentation dimensions modeled include product format, sorbent material chemistry, application vertical, end-user procurement sophistication, and regional regulatory cluster. CAGRs were derived from logarithmic trend fitting across validated data points, with pharmaceutical research and clinical diagnostics segments receiving distinct growth coefficients reflecting bioanalytical method validation investment cycles.
Stress conditions across bonded-phase silica supply disruption, PFAS substitution timeline acceleration, and analytical chemist labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these bounded assumptions and acknowledge that regulatory divergence or alternative extraction technology adoption could materially revise trajectory. Cross-checking against vendor-reported consumables revenue disclosures and contract research organization capital expenditure announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Extracts
Global Aphrodisiac Powder Market
Extracts
Floral Extract Market
Extracts
Orange Oil Market
Extracts
Lavender Oil Market
Extracts
Helichrysum Oil Market
Extracts
Lemon Balm Extract Market
Extracts
Pennyroyal Oil Market
Extracts
Clary Sage Oil Market
Extracts
Pearl Extract Market
Extracts
Peru Balsam Extract Market
Extracts
Functional Extract Market
Extracts
Thymoquinone Market
Extracts
Salvia Miltiorrhiza Extract Market
Extracts
Organic Extracts Market
Extracts
Polygonum Cuspidatum Extract Market
Extracts
Irish Moss Market